
 Europe Commercial Aircraft Cabin Interior Market | 2026-2036
Europe Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Aircraft Cabin Interior Market Foresight
Modular lightweight interior architectures is reconfiguring how European OEMs design, certify, and install cabin systems across single-aisle and wide-body programs. Safran leverages its integrated seating-to-IFE pipeline to capture retrofit cycles at airlines seeking faster turnaround times. Diehl Aerospace GmbH anchors galley and lavatory production through captive manufacturing in Germany. Recaro Group specializes in ergonomically optimized slimline seats that reduce per-passenger weight while maintaining EASA-certified 16g dynamic test compliance.
Europe commercial aircraft cabin interior encompasses the engineered assemblies, fixed monuments, and loose equipment installed within the pressurized fuselage to ensure passenger safety, comfort, and operational efficiency during flight. These systems must satisfy stringent flammability requirements under CS-25 Appendix F, with thermoplastic composites and intumescent coatings now displacing traditional aluminum in sidewall panels and overhead bin shells to achieve weight reductions. Seating commands the largest product category as airlines prioritize densification without sacrificing 18-inch minimum seat width on long-haul configurations. Composites represent the fastest-expanding material segment, driven by Airbus's expanded use of carbon fiber-reinforced polymers in A320neo and A350 cabin monuments to lower fuel burn per seat.
EASA's Certification Specifications for Large Aeroplanes (CS-25) and the EU's REACH regulation on chemical substances in cabin textiles jointly determine material eligibility, compliance cost, and supplier qualification timelines for interior manufacturers across the continent. The EU Green Deal's emerging requirements for aircraft end-of-life recyclability are pressuring seating and monument producers to design for disassembly, with aluminum-to-composite bonding methods now facing scrutiny under revised waste framework directives. Stakeholders must monitor how EASA's anticipated updates to cabin air quality standards will filter through to ventilation-integrated seating designs and antimicrobial surface specifications.
Market Dynamics
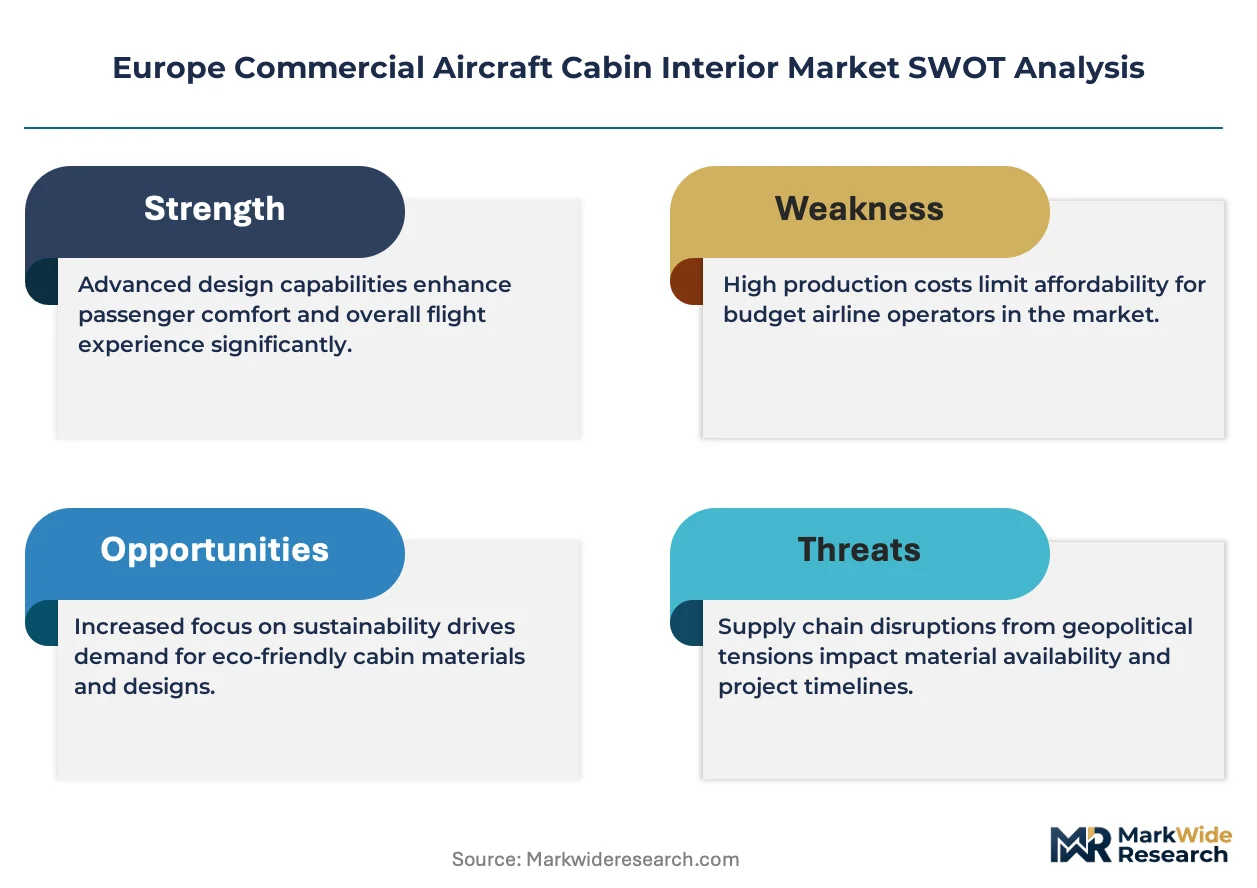
EASA's updated fire-smoke-toxicity standards are compressing supplier qualification timelines while accelerating composite material substitution across seating and monument systems. Tier-one manufacturers in Germany and France now face dual pressure from certification deadlines and airline retrofit schedules.
Growth Catalysts
- CS-25 Appendix F compliance mandates:Airlines across Eastern Europe must replace non-compliant cabin materials during C-check cycles, creating replacement demand for thermoplastic sidewall panels and intumescent-coated bin shells.
- Low-cost carrier fleet densification:Ryanair, Wizz Air and similar operators are retrofitting narrow-body aircraft with slimline configurations to maximize seat count without fuselage modifications.
- EU Green Deal recyclability requirements:Seating manufacturers redesigning aluminum-to-composite bonding methods to satisfy revised waste framework directives for aircraft end-of-life disassembly.
Market Restraints
- Carbon fiber prepreg cost volatility:Composite raw material prices fluctuate with aerospace-grade carbon fiber supply constraints from Japanese and US precursor manufacturers.
- Supplier concentration in Southern Germany:Final assembly proximity to Airbus Hamburg and Toulouse creates geographic dependency for galley and lavatory system procurement.
- REACH chemical substance restrictions:The EU's registration, evaluation, authorization and restriction of chemicals framework limits flame-retardant textile treatments available to seat upholstery suppliers.
Strategic Opportunities
- Polish and Romanian MRO hub expansion:Emerging maintenance facilities in Eastern Europe seek localized cabin retrofit capabilities to reduce logistics costs for regional low-cost carriers.
- Ventilation-integrated antimicrobial seating:Anticipated EASA cabin air quality updates create design white space for seats with embedded HEPA filtration and copper-alloy touch surfaces.
- Digital twin certification pathways:Convergence of physics-based modeling and EASA's evolving virtual testing protocols promises to compress dynamic 16g seat qualification timelines.
Industry Challenges
- Composite repair technician scarcity:The shift from aluminum to carbon fiber-reinforced polymer monuments outpaces vocational training capacity at German and French technical institutes.
- CS-25 change certification backlog:EASA's limited engineering staff capacity extends supplemental type certificate approval timelines for interior modification kits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Aircraft Cabin Interior Market |
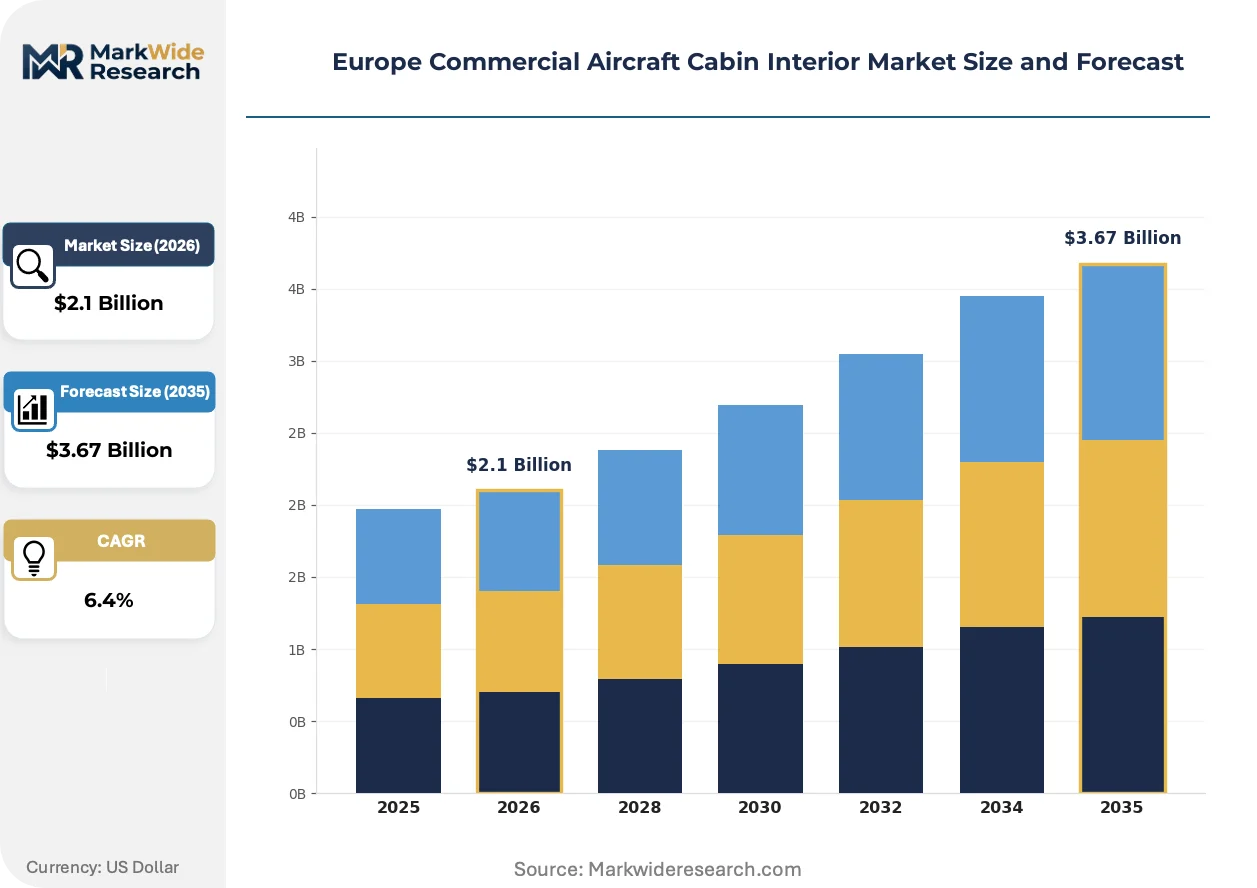
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Overhead Bins, Lavatories, Galley Material: Aluminum, Composites, Textiles, Plastics End User: Airlines, Charter Services, Military, Private Operators Delivery Mode: Direct Sales, Online Sales, Distributors, Others |
| Companies Covered | Recaro Group, Astronics Corporation, Safran, Diehl Aerospace GmbH, FACC AG, Collins Aerospace, Thales Group, Thompson Aero Seating, Panasonic Avionics Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Aircraft Cabin Interior Market Shifts & Advancements
Digital engineering workflows are compressing design-to-certification cycles while antimicrobial surface specifications reshape material selection criteria across European cabin programs.
Virtual prototyping software is virtualizing the traditional physical test sequence for seat dynamic qualification. Safran and Recaro engineering teams now simulate 16g crash pulses and flammability scenarios before cutting metal or molding composites. This virtualization is collapsing the feedback loop between design iteration and regulatory submission, enabling faster response to airline customization requests.
REACH Annex XVII restrictions on halogenated flame retardants are forcing textile suppliers to reformulate seat cover materials. The regulation's industrial consequence is a supply chain scramble for phosphorus-based and intumescent alternatives that maintain CS-25 burn-through resistance. Seating manufacturers in Germany face the steepest compliance cost increases due to their high-volume production of long-haul premium configurations with extensive upholstery surface area.
Airline technical procurement teams now unbundle interior retrofit contracts into separate seating, IFE, and monument work packages. This disintermediation of integrated cabin solutions disrupts traditional turnkey supplier relationships at Lufthansa Technik and Air France Industries MRO divisions. The pattern is most visible in Spain and Italy, where Iberia Maintenance and Atitech actively solicit competitive bids for individual system categories rather than single-source cabin overhauls.
Europe Commercial Aircraft Cabin Interior Market Segmentation
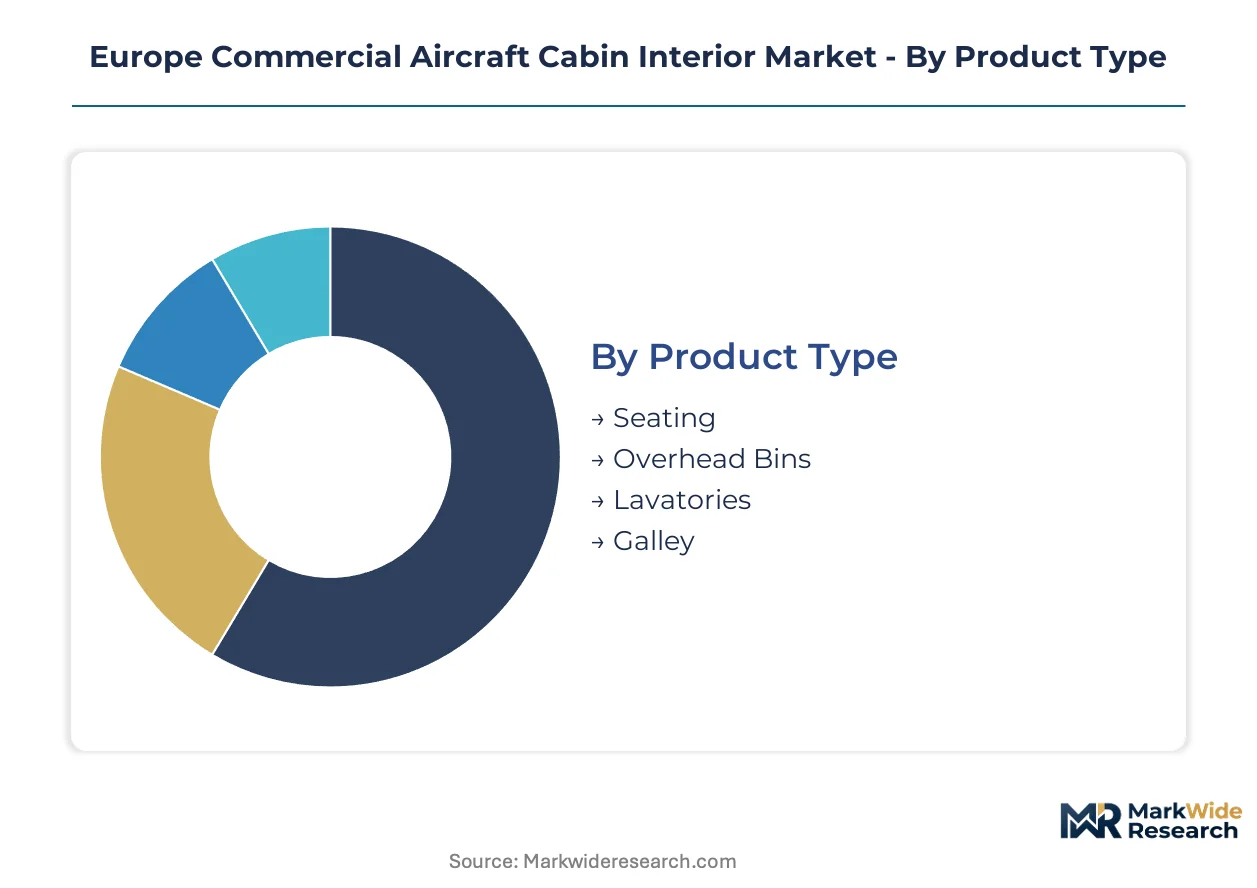
European cabin interior procurement divides sharply between OEM line-fit programs and aftermarket retrofit cycles, with material selection and certification pathways varying dramatically across these channels. Airlines prioritize weight reduction and densification, while regulatory compliance costs reshape supplier economics differently for each product category.
Product Type:
Application focus determines engineering specifications, with line-fit monuments requiring deeper integration into airframe assembly schedules than loose equipment retrofits.
- Seating:Slimline configurations with 16g dynamic test compliance dominate narrow-body retrofits across Ryanair and Wizz Air fleets. German and French manufacturers anchor supply for long-haul premium cabins where 18-inch minimum width standards apply.
- Overhead Bins:Thermoplastic composite shells with intumescent coatings displace aluminum to achieve CS-25 Appendix F burn-through resistance. Airbus A320neo and A350 programs in Hamburg and Toulouse drive specification updates for pivot-bin mechanisms.
- Lavatories:Space-optimized modules with antimicrobial surfaces serve single-aisle densification programs.
- Galley:Monument-integrated systems from Diehl Aerospace support meal service efficiency on European short-haul networks.
Seating commands the established base. The steepest expansion runs through Overhead Bins.
Material:
Cost tier positioning separates legacy aluminum architectures from next-generation composite systems competing on fuel-burn reduction metrics.
- Composites:Carbon fiber-reinforced polymers from Japanese and US precursor suppliers enable 20-30% weight reduction in A350 sidewall panels and bin shells. EASA fire-smoke-toxicity updates accelerate substitution timelines for Eastern European retrofit programs.
- Aluminum:Conventional alloys retain cost advantage for non-structural brackets and fastener systems in budget carrier configurations. Polish and Romanian MRO facilities favor aluminum for repair accessibility.
- Textiles:REACH Annex XVII compliance drives reformulation of seat upholstery toward phosphorus-based flame retardants.
- Plastics:Injection-molded thermoplastics serve lavatory and galley interior fittings.
Aluminum retains the volume base. The steepest expansion runs through Composites.
End User:
Customer type shapes procurement scale and customization depth, from high-volume standardized orders to bespoke VIP configurations.
- Airlines:Network carriers at Lufthansa and Air France-KLM drive premium cabin refresh cycles, while low-cost operators prioritize turnaround-time-optimized slimline retrofits. Fleet densification mandates concentrate procurement volumes in Germany, UK, and Ireland.
- Charter Services:Seasonal demand patterns from Mediterranean and Alpine tourism operators require rapid reconfiguration capabilities for mixed-use cabins.
- Military:Specialized transport configurations serve European defense procurement programs with enhanced durability specifications.
- Private Operators:VIP completion centers in Switzerland and Austria specify custom monuments and handcrafted seating for business jet conversions.
Airlines command the established base. The steepest expansion runs through Charter Services.
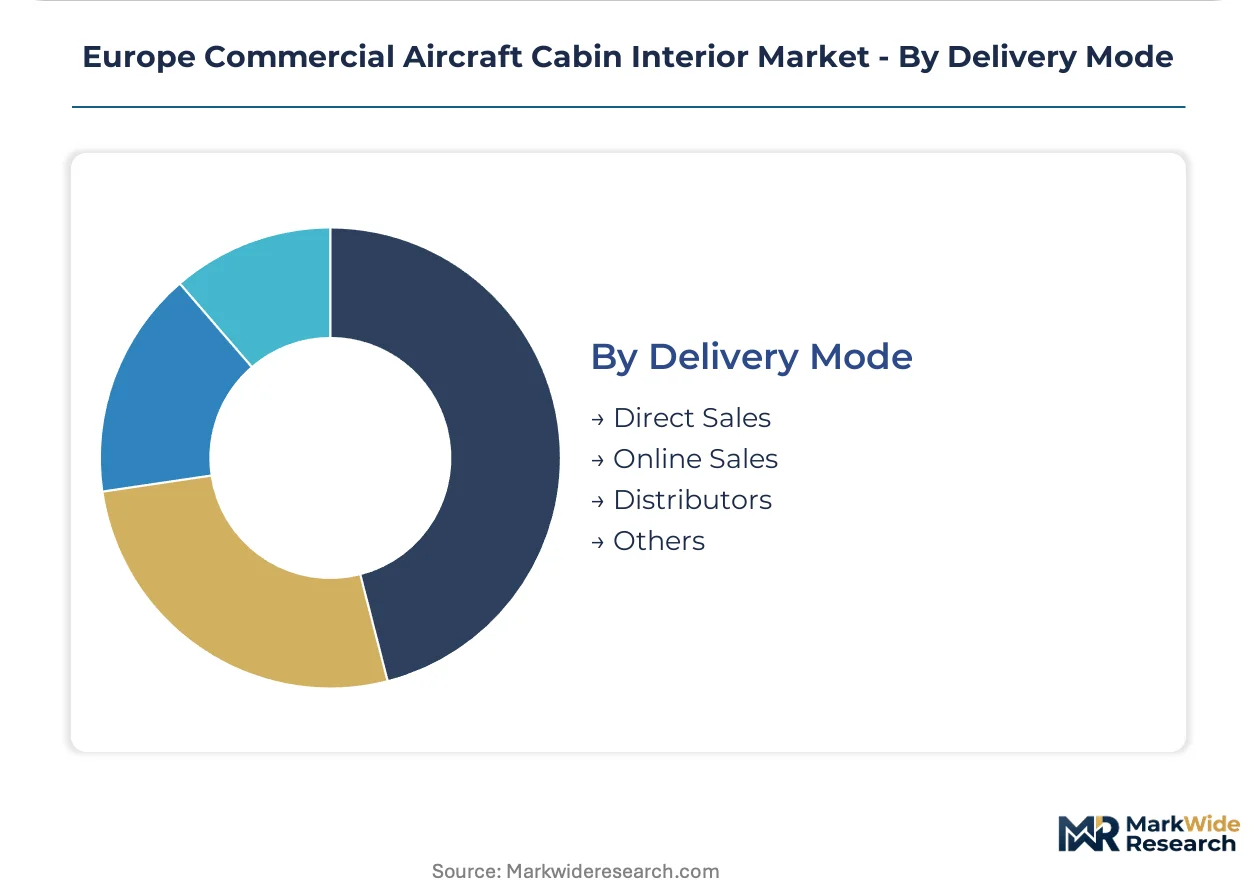
Delivery Mode:
Supply concentration around Airbus final assembly lines dictates channel preference, with proximity logistics outweighing cost considerations for time-sensitive line-fit programs.
- Direct Sales:Tier-one suppliers including Safran and Recaro maintain dedicated account teams at airline technical procurement departments. Long-term framework agreements cover multi-year retrofit schedules for major European flag carriers.
- Distributors:Regional inventory hubs in Poland and Romania serve emerging MRO facilities with reduced logistics costs for urgent A-check material replenishment.
- Online Sales:Limited to consumables and minor modification kits for general aviation operators.
- Others:Leasing company intermediaries manage cabin configuration standardization across pooled narrow-body assets.
Direct Sales commands the established base. The steepest expansion runs through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports cabin interior systems to Airbus final assembly lines in France and Spain, while Eastern European airlines import retrofit components from Polish and Romanian distributor hubs.
Germany
Airbus Hamburg and Toulouse procurement drives galley and seating volumes from Diehl Aerospace and Recaro Group facilities. EASA's CS-25 Appendix F compliance deadlines compress supplier qualification timelines for thermoplastic composite monuments. The Hamburg-Airbus cluster anchors line-fit production for A320neo and A350 programs.
France
Safran leverages integrated seating-to-IFE pipelines to capture airline retrofit cycles at Air France-KLM and Transavia. REACH Annex XVII restrictions on halogenated flame retardants force textile reformulation at Lyon-based upholstery suppliers. The Toulouse-Blagnac aerospace corridor concentrates final assembly integration for wide-body cabin systems.
United Kingdom
Ryanair's UK bases and British Airways drive slimline seat densification programs across narrow-body fleets. The EU Green Deal's recyclability requirements pressure seating manufacturers to redesign aluminum-to-composite bonding methods. Northern England MRO facilities at Manchester and Prestwick expand retrofit capabilities for regional low-cost carriers.
Poland
Wizz Air's Warsaw and Krakow hubs generate aftermarket demand for rapid-turnaround cabin reconfigurations. EASA fire-smoke-toxicity standards accelerate composite adoption in Eastern European C-check cycles. Emerging MRO facilities at Rzeszów-Jasionka Airport seek localized inventory partnerships to reduce logistics costs.
Spain
Iberia Maintenance and Atitech unbundle interior retrofit contracts into separate seating and monument work packages. CS-25 change certification backlogs at EASA extend supplemental type certificate timelines for modification kits. The Madrid-Barajas maintenance cluster serves Mediterranean charter operators with seasonal reconfiguration demands.
Europe Commercial Aircraft Cabin Interior Market Competitive Landscape
Channel-controlling players compete with product-specialist players across line-fit and aftermarket segments. The vendor base concentrates around Airbus final assembly proximity, with German and French manufacturers anchoring tier-one supply. Three archetypes dominate: integrated system houses spanning seating-to-IFE pipelines, monument specialists capturing galley and lavatory procurement, and retrofit-focused slimline seat producers. Competitive moves center on EASA certification acceleration and geographic expansion into Eastern European MRO hubs.
Among Germany-based fabricators, Diehl Aerospace GmbH and Recaro Group exemplify the integrated-to-specialist spectrum. Diehl Aerospace occupies a position within the monument-specialist archetype, while Recaro Group represents the ergonomically optimized seating tier. Safran anchors the integrated system house category with its cross-product pipeline capabilities. These three entities collectively illustrate how European suppliers align organizational structure with Airbus procurement geography and EASA regulatory sequencing.
| Leading Market Players |
|---|
| Recaro Group |
| Astronics Corporation |
| Safran |
| Diehl Aerospace GmbH |
| FACC AG |
| Collins Aerospace |
| Thales Group |
| Thompson Aero Seating |
| Panasonic Avionics Corporation |
| Others |
Supply & Pricing Matrix
Japanese and US carbon fiber precursor manufacturers anchor upstream supply for aerospace-grade composites, concentrating margin capture in raw material conversion while European tier-one seating and monument producers compete on certification speed and customization flexibility downstream.
Pricing Analysis
Current-generation slimline seating with full EASA CS-25 Appendix F compliance commands premium positioning against prior-generation aluminum-frame configurations, while next-generation ventilation-integrated antimicrobial designs are priced at prototype premiums pending qualification. Three-tier pricing structure across premium long-haul, standard narrow-body, and economy retrofit levels differentiates primarily on certification grade and after-sales service bundling. Pricing pressure stems from low-cost carrier procurement teams unbundling integrated cabin contracts into competitive-bid work packages. Charter operators and Eastern European MRO facilities exhibit highest price sensitivity due to seasonal utilization patterns, while VIP completion centers in Switzerland and Austria show lowest sensitivity given customization premiums.
Supply Chain Analysis
Contract manufacturing for thermoplastic composite monuments concentrates at Diehl Aerospace captive facilities in Germany and Safran-integrated production lines in France, with limited qualified alternatives for EASA-certified fire-smoke-toxicity compliant assemblies. Geographic supply concentration centers on Germany, France, and emerging Polish MRO hubs. Raw material dependencies draw from Japanese carbon fiber precursors, US resin systems, and REACH-compliant phosphorus-based flame retardants from specialized European chemical suppliers. Single-source vulnerability runs through aerospace-grade prepreg qualification timelines that extend 18-24 months for alternative supplier approval. Distribution runs through tier-one direct sales for line-fit programs and Polish-Romanian distributor hubs for urgent aftermarket replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including retrofit engineering, spare parts logistics, and digital twin maintenance contracts are expanding faster than hardware shipments as airlines prioritize operational continuity over capital expenditure cycles.
For Market Incumbents: Insulate certification-derived margin pools by accelerating EASA virtual testing protocol adoption to compress 16g dynamic seat qualification timelines before regulatory capacity constraints ease. Deepen backward integration into thermoplastic composite prepreg manufacturing to offset Japanese-US precursor price volatility and secure supply priority during aerospace upcycles. Channel control through long-term framework agreements with Ryanair and Wizz Air procurement teams limits competitive access to high-volume narrow-body retrofit schedules. For New Entrants and Emerging Players: Build out localized MRO capabilities at Rzeszów-Jasionka and emerging Romanian maintenance clusters where incumbent presence remains thin and logistics cost advantages favor regional suppliers. Polish and Romanian distributor partnerships offer the most penetrable channel structure, with charter operator seasonal reconfiguration demands providing volume entry points absent from flag carrier line-fit procurement. Go-to-market positioning should emphasize rapid-turnaround C-check material availability and REACH-compliant textile reformulation expertise. For Investors and Strategic Acquirers: Capital is best deployed toward monument-specialist fabricators with captive EASA certification pathways and established Airbus final assembly proximity, given 5-10 year program visibility on A320neo and A350 production ramps. Acquisition targets combining composite manufacturing depth with digital engineering workflows offer superior multiple resilience through certification acceleration capabilities. The signal to watch is EASA staffing announcements for CS-25 change certification capacity expansion, which would compress supplemental type certificate timelines and revalue retrofit-focused asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Certification Pathway | Physics-based modeling adoption at Safran and Recaro collapses EASA 16g seat qualification timelines. |
| Backward Integration into Composite Prepreg | Diehl Aerospace captive manufacturing secures supply priority during Japanese-US precursor constraint periods. |
| Eastern European MRO Hub Expansion | Polish and Romanian facilities reduce logistics costs for Wizz Air and regional low-cost carrier retrofit cycles. |
| REACH-Compliant Textile Reformulation | Lyon-based upholstery suppliers pivot to phosphorus-based flame retardants under Annex XVII restrictions. |
| Antimicrobial Surface Integration | Copper-alloy touch surfaces and HEPA-embedded seating capture anticipated EASA cabin air quality updates. |
Research Methodology
A spread of perspectives from airline technical procurement directors, MRO facility operations managers, EASA certification engineers, tier-one supplier program directors, and composite materials R&D leads converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from EASA CS-25 regulatory filings, EU REACH Annex XVII substance restriction updates, Airbus production disclosure statements, and Eastern European aviation authority capacity registers. Bottom-up procurement volume estimates triangulated against top-down Airbus delivery schedule projections.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, material grade tier, end-user archetype, and delivery channel. Modeled categories included seating configuration density, composite versus aluminum content ratios, line-fit versus aftermarket procurement splits, and geographic delivery clusters. CAGRs were derived from regression-based trending of procurement volume patterns against airframe production schedules and regulatory compliance cycle timing. Industry-specific forecast inputs incorporated EASA certification backlog estimates and REACH implementation phase-in schedules.
Stress conditions across carbon fiber precursor supply disruption severity, EASA engineering staff capacity expansion pace, and EU Green Deal recyclability enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding airline fleet densification commitment sustainability and low-cost carrier retrofit budget allocation stability. Quarterly review of EASA supplemental type certificate approval queue lengths and Polish-Romanian MRO facility utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market