
 Aircraft Seat Upholstery Market | 2026-2036
Aircraft Seat Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Seat Upholstery Market Analysis
Leather alternatives are repositioning cost structures across premium cabin configurations. Tapis Corporation leverages deep textile archives to sustain North American airline contracts. Lantal Textiles AG anchors European supply chains through integrated weaving and finishing operations. Safran Seats competes via captive seat manufacturing that controls upholstery specification and sourcing timelines.
Aircraft seat upholstery encompasses engineered textile and synthetic coverings applied to passenger seating structures, typically meeting 16 CFR Part 25.853 burn-test criteria and abrasion thresholds exceeding 100,000 double rubs, designed to balance occupant comfort with regulatory fire safety. Fabric dominates material type volumes due to weight advantages on single-aisle platforms, while leather commands margin pools in luxury and ergonomic design complexity tiers where unit economics favor premium procurement. Commercial aviation anchors application area demand through fleet expansion and refurbishment cycles, whereas private aviation segments concentrate higher customization rates per seat position.
FAA flammability protocols and EASA CS-25 certification requirements shape material selection and testing expenditures for all suppliers seeking platform approval. EPA chemical restrictions on perfluorinated compounds are forcing reformulation of stain-resistant coatings applied to synthetic upholsteries. OEM procurement teams and airline technical buyers must monitor evolving sustainable material mandates from both regulators before committing to multi-year fleet upholstery contracts.
Market Dynamics
FAA flammability standard revisions are compressing supplier qualification timelines while narrow-body fleet retrofits concentrate procurement volumes among carriers with aging Boeing 737 and Airbus A320 interiors requiring urgent reupholstery.
Growth Catalysts
- 16 CFR Part 25.853 burn-test compliance:Airlines facing FAA audit cycles accelerate seat replacement schedules to avoid operational grounding risks during routine inspections.
- Single-aisle platform density:Low-cost carriers expanding 180-seat narrow-body configurations multiply upholstery unit demand per aircraft delivery.
- Polyurethane foam reformulation:Next-generation fire-blocking layers meeting OSU heat-release thresholds below 55/55 enable lighter seat designs that reduce fuel burn.
Market Restraints
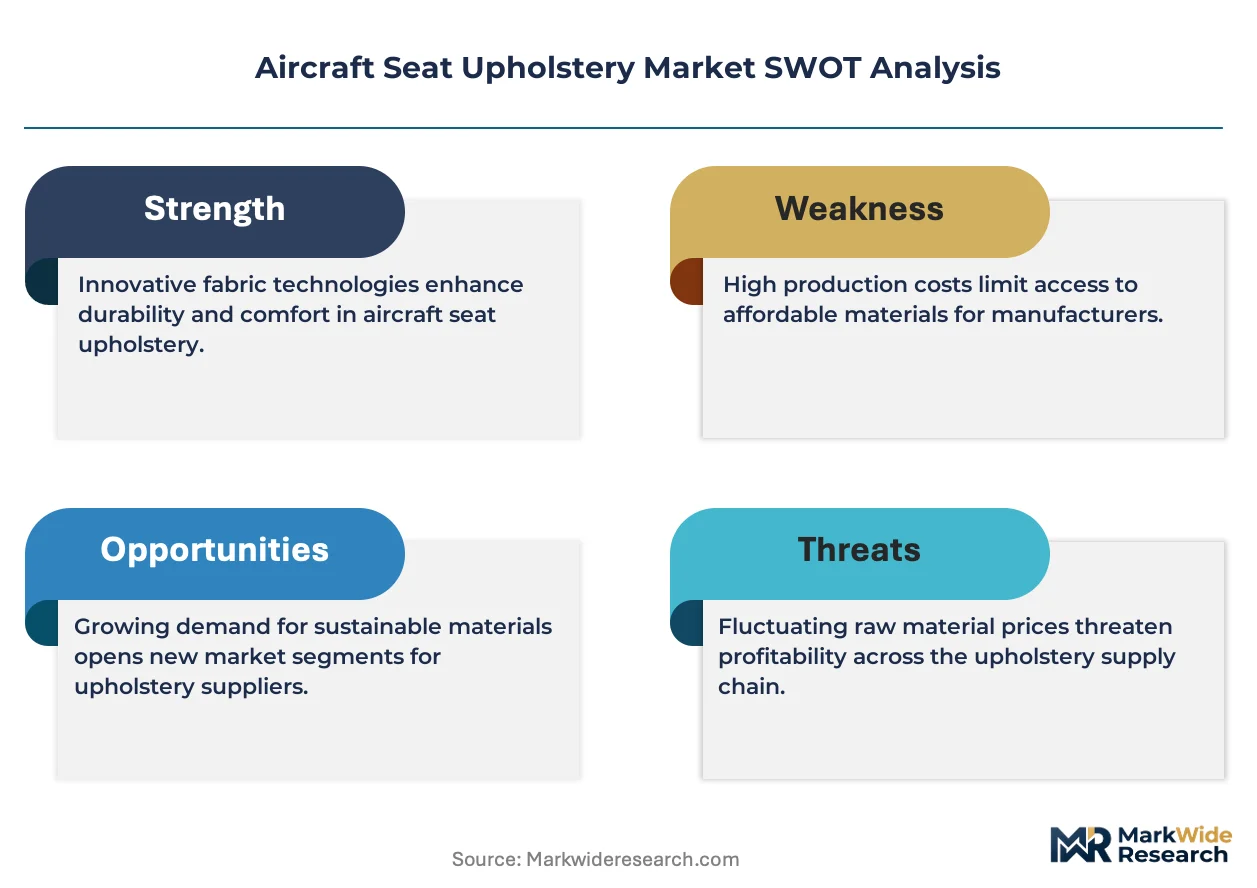
- Aramid fiber supply concentration:Fire-blocking textile substrates depend on DuPont and Teijin filament capacity concentrated in North Carolina and Japan, creating single-source vulnerability.
- Perfluorinated compound coating phase-out:EPA restrictions on PFAS stain-resistant treatments force upholstery mills to abandon proven chemistries without fully validated replacements.
- Leather tanning input volatility:Chromium sulfate prices fluctuate with South African mining output, compressing margin stability for premium cabin suppliers.
Strategic Opportunities
- India narrow-body induction wave:IndiGo and Air India A320neo deliveries create first-mover advantage for upholstery suppliers establishing local finishing operations under PLI scheme incentives.
- Bio-based polyurethane development:Castor oil-derived foam formulations align with airline ESG disclosure requirements under CSRD scope 3 reporting mandates.
- Digital textile printing integration:Direct-to-fabric patterning enables airline-specific branding at batch sizes below 500 meters, collapsing minimum order quantities that previously favored synthetic leather.
Industry Challenges
- 16G dynamic testing certification backlog:Seat assembly crashworthiness validation at FAA-approved facilities extends upholstery integration timelines by 4-8 months.
- Legacy seat frame compatibility:New lightweight upholstery materials require adhesive bonding protocols incompatible with 1990s-era seat pan geometries still operational in regional fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Seat Upholstery Market |
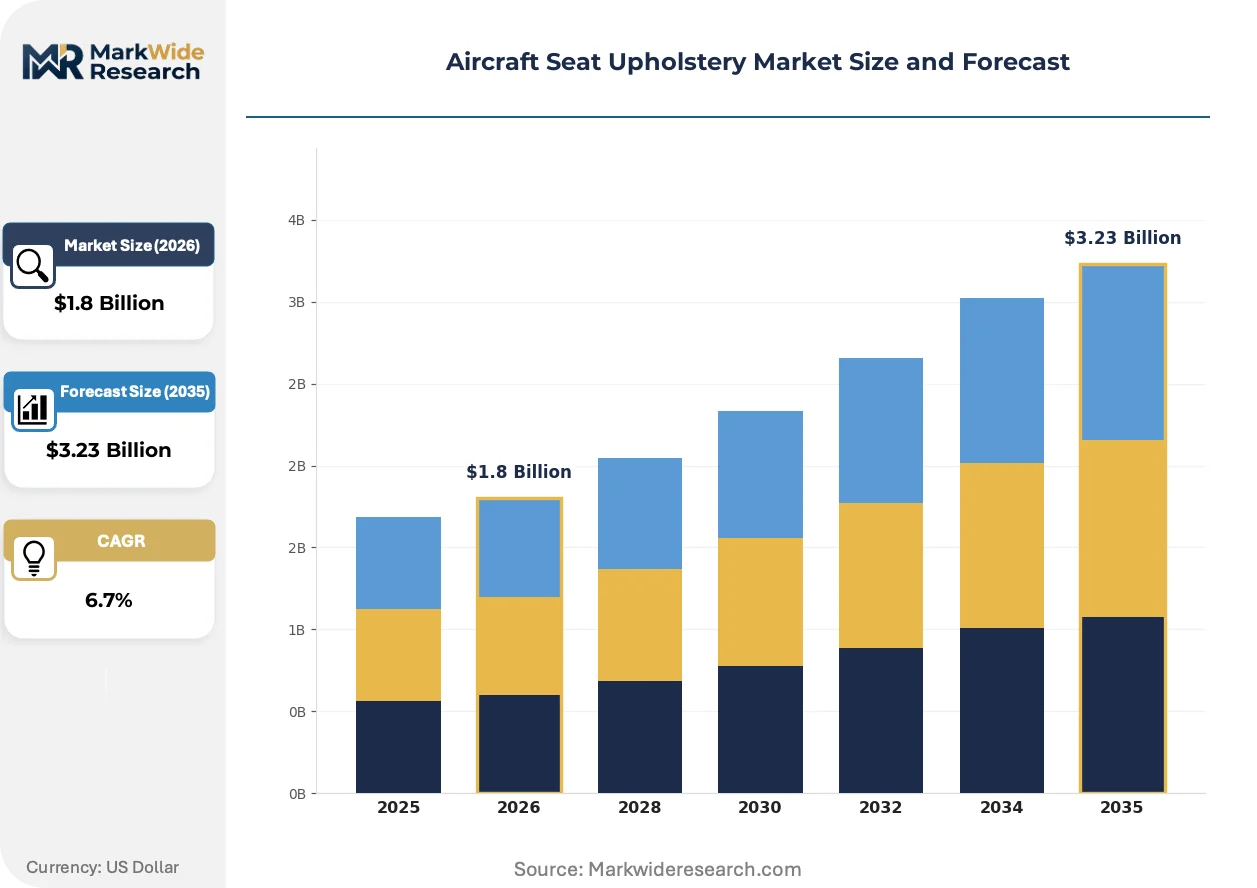
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Fabric, Vinyl, Foam Application Area: Commercial Aviation, Private Aviation, Military Aviation, Cargo Aircraft End User: OEMs, Airlines, Maintenance Providers, Interior Designers Design Complexity: Simplistic, Ergonomic, Luxury, Customizable |
| Companies Covered | Tritex Corporation, OmnAvia Interiors, Collins Aerospace, Aerotex Aircraft Interiors, Tapis Corporation, Safran Seats, Spectra Interior Products, Franklin Products, Lantal Textiles AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Seat Upholstery Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to displace incumbent synthetic leather formulations while digital manufacturing tools compress customization economics for airline branding programs.
Recycled polyethylene terephthalate (rPET) woven textiles derived from post-consumer plastic bottles are rewriting upholstery specification sheets at major carriers. Southwest Airlines and JetBlue have adopted 100% rPET fabric for economy cabins, compressing virgin polyester demand while meeting identical 100,000 double-rub abrasion thresholds. The shift enables suppliers to market closed-loop material flows that satisfy airline sustainability procurement scorecards.
EPA restrictions on perfluorinated compounds under TSCA Section 6 are forcing reformulation of stain-resistant coatings applied to synthetic upholsteries. Mills serving US-registered carriers must validate alternative silicone or bio-based repellent chemistries through renewed 16 CFR Part 25.853 testing, extending qualification cycles by 6-12 months. European suppliers face parallel pressure under ECHA PFAS restriction proposals, creating transatlantic regulatory alignment that favors integrated coating developers with dual-continent certification capabilities.
Airline technical buyers are consolidating upholstery procurement under multi-year fleet agreements that bundle specification, installation, and after-warranty replacement. Delta Air Lines and United Airlines have moved to 7-10 year sole-source contracts covering narrow-body and wide-body platforms, displacing spot purchasing through MRO intermediaries. The model concentrates volume with vertically integrated suppliers capable of in-house weaving, coating, and cut-and-sew operations, compressing margins for pure-play finishing houses dependent on toll manufacturing arrangements.
Aircraft Seat Upholstery Market Segmentation
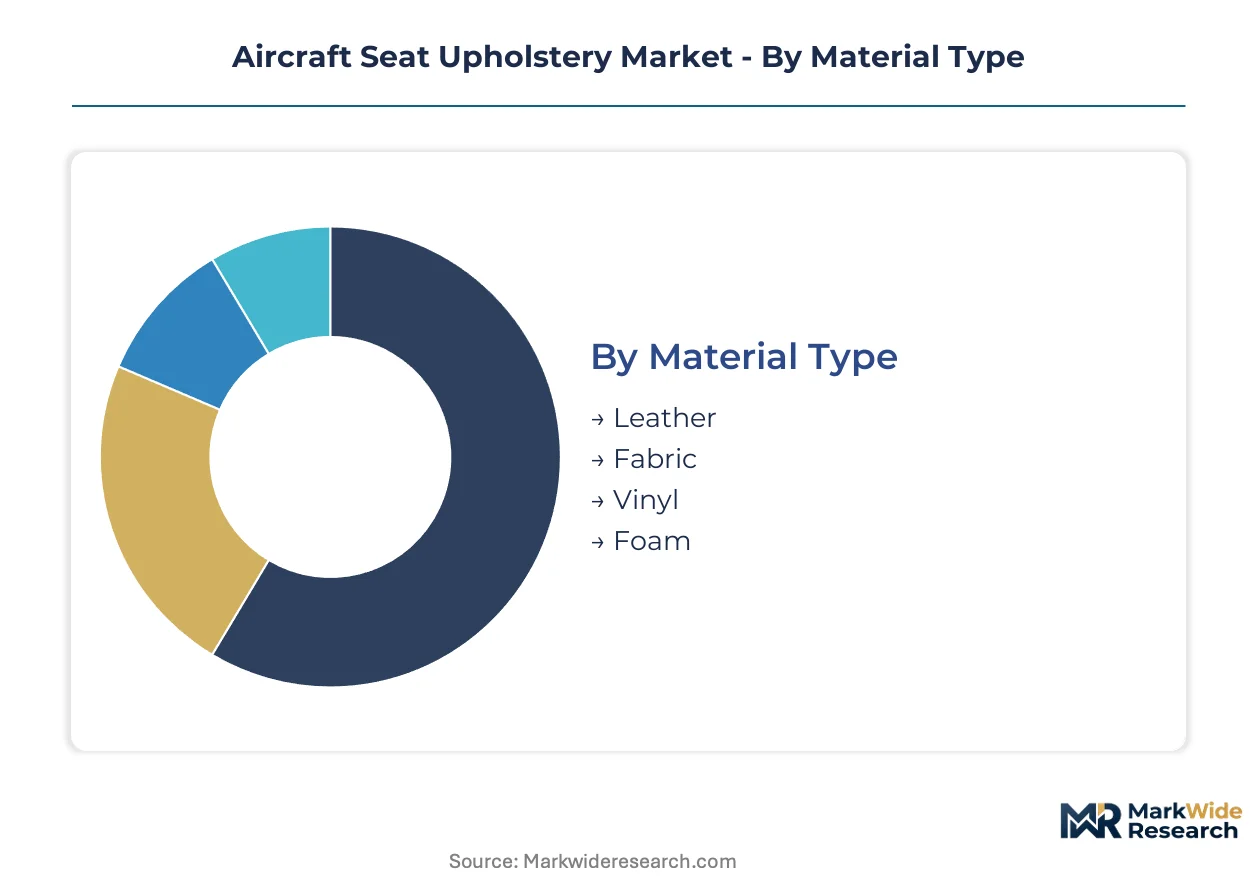
Aircraft seat upholstery procurement splits sharply across material chemistry, cabin tier, and buyer sophistication. Each segmentation axis reveals divergent margin structures and qualification barriers that reshape supplier positioning.
Material Type:
Cost tier separates buyers seeking weight savings from those prioritizing premium aesthetics and durability cycles.
- Leather:Full-grain and corrected-grain hides deliver 150,000+ double-rub abrasion resistance with natural breathability. Demand concentrates in Gulf carrier first-class cabins where Emirates and Qatar Airways specify aniline finishes meeting EASA CS-25 fire standards. Chromium tanning input volatility from South African mining compresses margin stability for tanneries serving this segment.
- Fabric:Woven nylon-polyester blends dominate narrow-body economy configurations through weight advantages of 40-60% versus leather. Southwest Airlines and Ryanair procurement teams specify rPET-derived textiles under fleet sustainability mandates, with 100% recycled content now qualifying for identical 16 CFR Part 25.853 burn-test certification.
- Vinyl:Polyurethane-coated substrates offer intermediate abrasion performance at unit costs 30-40% below leather. Regional carriers operating Bombardier CRJ fleets specify vinyl for quick-turn replacement cycles.
- Foam:Fire-blocking polyurethane layers meeting OSU 55/55 heat-release thresholds enable lighter seat designs. Reformulation pressures from EPA PFAS restrictions extend qualification timelines for US-registered aircraft.
Volume sits with fabric; growth tilts toward rPET-derived textiles as ESG disclosure requirements harden.
Application Area:
Platform type dictates certification burden and replacement frequency, with commercial narrow-bodies generating recurring retrofit demand.
- Commercial Aviation:Single-aisle fleets account for dominant upholstery unit volumes through 180-seat density configurations. FAA flammability audit cycles accelerate replacement schedules for aging Boeing 737 and Airbus A320 interiors.
- Private Aviation:Customization rates per seat position exceed commercial benchmarks by 5-8x, with Gulfstream and Dassault buyers specifying full leather wraps. Lead times stretch 12-16 weeks versus 4-6 weeks for airline programs.
- Military Aviation:MIL-STD-810G environmental testing adds vibration and altitude cycling requirements beyond civilian fire standards. Lockheed Martin C-130 programs specify Nomex-blend fabrics for troop transport durability.
- Cargo Aircraft:Converted freighter upholstery focuses on quick-removal seat configurations for flexible load factors. Amazon Air 767-300 conversions use simplified fabric covers without headrest assemblies.
Procurement volume concentrates in commercial narrow-bodies; margin expansion tracks private aviation customization intensity.
End User:
Technical buyer sophistication ranges from fleet-standardization teams to one-off interior studios.
- OEMs:Safran Seats and Collins Aerospace exercise captive upholstery specification control through in-house weaving and finishing operations. Long-term fleet agreements now span 7-10 years with sole-source terms.
- Airlines:Delta and United technical buyers consolidate procurement under multi-year contracts bundling specification, installation, and after-warranty replacement. Spot purchasing through MRO intermediaries is displacing rapidly.
- Maintenance Providers:STC-holding MROs like HAECO and Lufthansa Technik manage reupholstery during C-check intervals. Turnaround constraints favor pre-approved material kits over custom sourcing.
- Interior Designers:Boutique studios serving VIP completion centers specify bespoke patterns through digital textile printing at sub-500 meter batch sizes.
Volume aggregates with OEM captive supply; procurement autonomy is shifting fastest toward airline direct contracting.
Design Complexity:
Engineering integration depth separates commodity replacement from platform-development partnerships.
- Simplistic:Flat-pattern fabric covers attach with hook-and-loop fastening for regional fleet quick replacement. No 16G dynamic testing required.
- Ergonomic:Contoured foam integration with lumbar support zones demands CAD-modeled upholstery patterns. Recaro and Thompson Aero Seating specify these for long-haul premium economy.
- Luxury:Multi-panel leather construction with contrast stitching and embroidered logos requires hand-finishing at specialized cut-and-sew facilities. Singapore Airlines and Etihad Airways drive specification evolution.
- Customizable:Modular attachment systems enable airline-specific branding swaps without seat removal. Digital printing integration collapses minimum order quantities that previously constrained program economics.
Revenue concentration rests with luxury tier premium cabins; capability investment flows fastest toward customizable digital manufacturing platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline fleet renewal cycles concentrate upholstery procurement in the United States, where narrow-body retrofits generate dominant volumes, while European and Asian carriers accelerate parallel replacement programs under tightening flammability mandates.
United States
Southwest Airlines and United Airlines drive narrow-body reupholstery demand across aging Boeing 737 fleets. FAA 16 CFR Part 25.853 audit cycles compress supplier qualification timelines. Wichita, Kansas hosts seat assembly clusters where upholstery integration occurs alongside OEM manufacturing.
Germany
Lufthansa Group's technical procurement consolidates European wide-body upholstery contracts under multi-year agreements. EASA CS-25 certification requirements shape material selection for suppliers seeking platform approval. Hamburg's aviation manufacturing corridor anchors finishing operations serving Airbus delivery schedules.
India
IndiGo and Air India A320neo inductions create first-mover opportunities for upholstery suppliers establishing local operations. PLI scheme incentives support domestic finishing capacity under Make in India aerospace initiatives. Bengaluru's emerging aviation cluster attracts textile mills seeking proximity to airline technical centers.
United Arab Emirates
Emirates and Etihad Airways specify premium cabin leather configurations with aniline finishes meeting dual certification standards. GCAA alignment with EASA protocols streamlines material approval for European-registered aircraft. Dubai's VIP completion centers concentrate bespoke upholstery demand for private aviation.
Japan
ANA and JAL retrofit programs target 787 and A350 interior renewal cycles. METI industrial standards supplement FAA flammability requirements for materials serving international routes. Nagoya's aerospace supply chain integrates textile finishing with seat assembly operations.
Aircraft Seat Upholstery Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM captive supply chains concentrating volume while independent mills compete on customization velocity. The vendor base organizes around three strategic archetypes: vertically integrated seat manufacturers controlling specification, textile specialists with weaving-to-finishing capabilities, and regional cut-and-sew houses serving MRO turnaround demands. Consolidation pressures favor players with in-house fire-blocking certification and digital printing integration. Geographic expansion and strategic partnerships represent the dominant competitive moves as suppliers seek dual-continent regulatory alignment.
Among North American textile specialists, Tapis Corporation and Franklin Products exemplify the branded mill archetype, leveraging deep archives to sustain airline contracts. Lantal Textiles AG occupies a position within the European integrated manufacturing tier, while Safran Seats represents the OEM-captive model where upholstery specification aligns with seat assembly timelines. These three anchors illustrate how capability depth, rather than scale alone, determines procurement access under consolidated fleet agreements.
| Leading Market Players |
|---|
| Tritex Corporation |
| OmnAvia Interiors |
| Collins Aerospace |
| Aerotex Aircraft Interiors |
| Tapis Corporation |
| Safran Seats |
| Spectra Interior Products |
| Franklin Products |
| Lantal Textiles AG |
| Others |
Supply Flow & Price Mechanics
Airline consolidation of procurement under multi-year fleet agreements is forcing upholstery mills to absorb qualification costs upfront while compressing spot-market premiums. This buyer-side concentration rewards suppliers with in-house fire-blocking certification and digital printing capabilities, squeezing pure-play finishing houses that rely on toll manufacturing arrangements.
Pricing Analysis
Volume concentrates in narrow-body fabric programs where rPET-derived textiles compete on sustainability scorecards, while margin pools concentrate in luxury cabin leather configurations where aniline finishes and hand-stitching command premium positioning. Price differentiation hinges on certification tier—FAA 16 CFR Part 25.853 versus dual EASA CS-25 approval—and customization depth enabled by digital textile printing. Cost compression in economy fabric tiers is intensifying as Southwest Airlines and Ryanair procurement teams mandate 100% recycled content without abrasion threshold concessions. Low-cost carriers exhibit highest price sensitivity, whereas Gulf carrier first-class specifications show lowest elasticity due to brand positioning requirements.
Supply Chain Analysis
Certification gating through FAA-approved 16G dynamic testing facilities concentrates supply among vertically integrated players with in-house fire-blocking validation. Fire-blocking textile substrates draw from DuPont and Teijin aramid filament capacity concentrated in North Carolina and Japan, while polyurethane foam reformulation feeds from specialty chemical producers in Germany and the United States. Single-source vulnerability in aramid fiber supply creates structural risk for mills dependent on North Carolina filament output. Distribution runs through OEM captive supply chains and airline direct contracting, displacing spot purchasing through MRO intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft seat upholstery is transitioning from synthetic leather dominance to rPET-derived textile and bio-based polyurethane formulations. EPA restrictions on perfluorinated compounds and airline ESG disclosure mandates are accelerating this chemistry shift.
For Market Incumbents: Anticipate regulatory chemistry phase-outs by accelerating castor oil-derived foam qualification before EPA PFAS restrictions harden. Secure backward integration into digital textile printing to defend against minimum order quantity collapse, and establish dual-continent certification capabilities as ECHA aligns with TSCA Section 6 timelines.
For New Entrants and Emerging Players: Begin with narrow-body retrofit programs in India, where IndiGo and Air India A320neo inductions outpace local finishing capacity. Target PLI scheme incentives for domestic cut-and-sew operations, and leverage direct-to-fabric patterning to win airline branding contracts at sub-500 meter batch sizes that incumbents cannot economically serve.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated textile specialists with weaving-through-finishing capabilities and existing FAA fire-blocking certification. Watch for 16G dynamic testing certification backlogs as an inflection signal—extended validation timelines at approved facilities will concentrate volume with players holding in-house crashworthiness integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Sourcing | Reduces single-source exposure to DuPont and Teijin filament capacity concentrated in North Carolina and Japan. |
| Digital Textile Printing Platform Deployment | Enables airline-specific branding at batch sizes below 500 meters, collapsing legacy minimum order economics. |
| Bio-Based Polyurethane Formulation Investment | Aligns with airline ESG disclosure requirements under CSRD scope 3 reporting mandates. |
| Dual-Continent Certification Capability Buildout | Positions suppliers for ECHA-EASA alignment with EPA PFAS restriction timelines. |
| Local Finishing Operations in India | Captures PLI scheme incentives as IndiGo and Air India narrow-body inductions accelerate. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with airline technical procurement managers, seat OEM platform engineers, textile mill R&D directors, and MRO turnaround specialists combined with FAA certification databases, EASA CS-25 submission logs, and EPA chemical restriction notices. Bottom-up unit demand modeling across narrow-body and wide-body fleet configurations triangulated against top-down upholstery spend estimates from airline sustainability procurement disclosures.
Data-stream reconciliation integrated production volume tracking from textile weaving operations with airline fleet reupholstery schedules and OEM delivery timelines. Segmentation modeling covered material chemistry, cabin tier, design complexity, and end-user procurement sophistication across the projection horizon. CAGRs derived from fleet renewal cycle analysis, retrofit frequency assumptions, and regulatory compliance-driven replacement acceleration. Industry-specific inputs included 16 CFR Part 25.853 burn-test qualification timelines and OSU 55/55 heat-release threshold adoption rates.
Underlying measurement precision varies by segment; commercial narrow-body fabric programs carry tighter precision than private aviation custom leather configurations due to fleet standardization. Forecasts reflect assumptions about regulatory enforcement timing, aramid fiber supply continuity, and airline ESG procurement mandate adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Aerospace Lavatory System Market