
 Asia-Pacific Commercial Aircraft Cabin Seating Market | 2026-2036
Asia-Pacific Commercial Aircraft Cabin Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft Cabin Seating Market Outlook
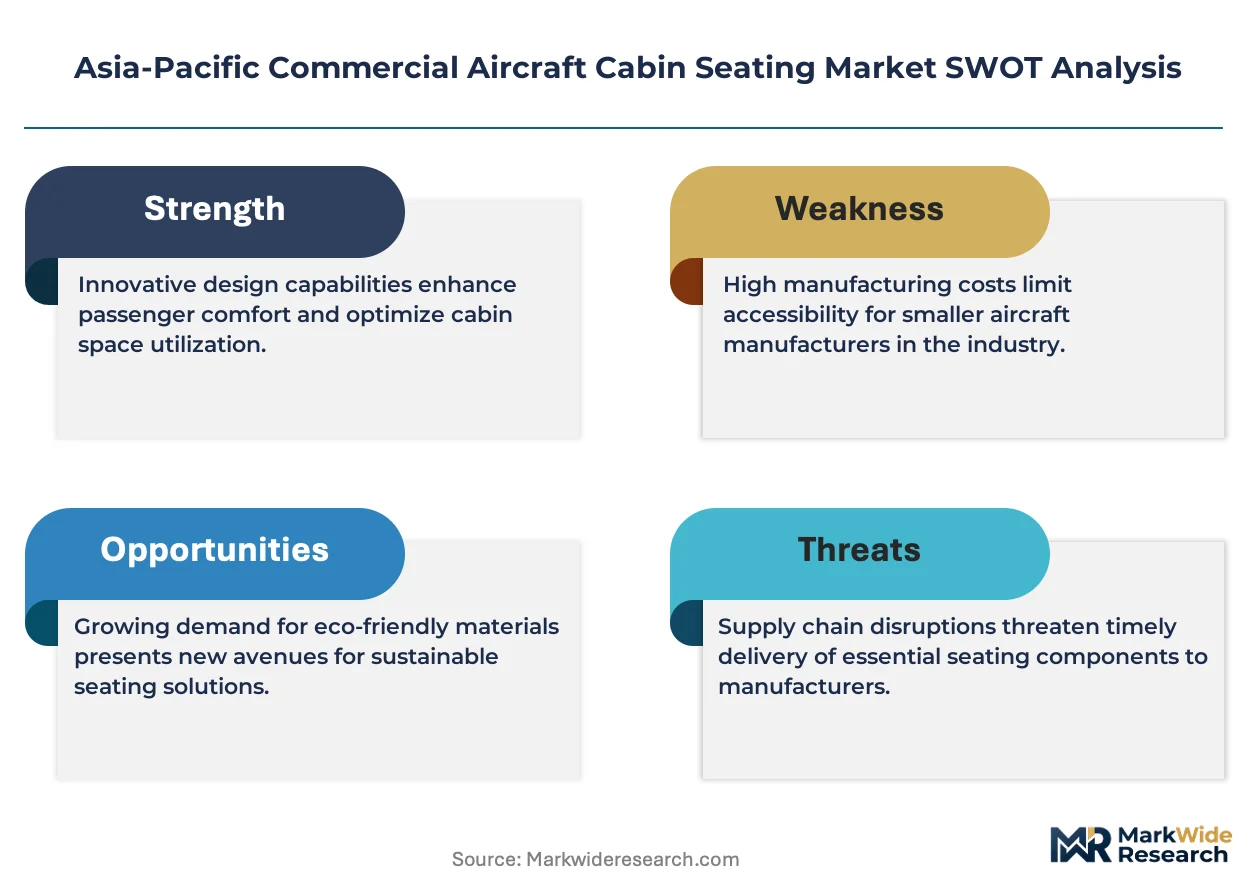
Buyer concentration across Asia-Pacific airlines is shifting as low-cost carriers consolidate fleet orders while full-service carriers fragment into premium sub-fleets. Collins Aerospace leverages its integrated avionics-to-interiors portfolio to anchor retrofit programs across Chinese and Indian carriers. Recaro Group specializes in lightweight economy seating that sustains fuel-efficiency mandates for narrow-body operators. Safran competes through vertical control over seat actuation and power distribution systems.
Asia-Pacific commercial aircraft cabin seating encompasses passenger seats engineered to specific pitch, width, and recline parameters, typically fabricated from aluminum frames, fire-blocking foam, and synthetic upholstery meeting 16g dynamic load criteria, serving the dual purpose of occupant safety and revenue-optimized cabin density. Economy class installations occupy the dominant volume share across the region's expanding narrow-body fleets, while premium economy configurations generate disproportionate margin pools as carriers seek yield differentiation without business-class complexity. Fabric materials lead in unit terms for cost-sensitive operators, though leather dominates refurbishment cycles among full-service airlines targeting brand positioning.
CAAC airworthiness directives, EASA CS-25 harmonization requirements, and China's GB standards collectively govern flammability, occupant injury criteria, and electrical integration protocols that dictate seat design cycles and supplier qualification timelines. The region's national regulators are tightening weight-certification standards that favor composite-intensive designs, effectively filtering market access toward R&D-capable manufacturers. Stakeholders must monitor evolving CAAC-EASA bilateral agreements and India's impending aircraft interior certification framework to anticipate qualification burdens and localize supply commitments.
Market Dynamics
China's GB standards and CAAC certification protocols are compressing design cycles for composite-intensive seating, forcing suppliers to localize R&D and fire-testing capabilities ahead of qualification timelines that now govern market access across the region's largest narrow-body fleets.
Growth Catalysts
- CAAC-EASA Harmonization:Bilateral airworthiness agreements are accelerating dual-certification pathways for Chinese and Indian carriers, reducing seat qualification timelines from 18 months to 12 months for compliant suppliers.
- Low-Cost Carrier Fleet Renewal:Southeast Asian budget airlines are consolidating narrow-body orders that specify 16g dynamic load-rated economy seating with reduced pitch tolerances.
- Fire-Resistant Composites:GB 8624 flammability standards are mandating thermoplastic matrix replacements for traditional aluminum frames in premium economy configurations.
Market Restraints
- Titanium Input Volatility:Seat actuation hardware depends on aerospace-grade titanium whose spot pricing fluctuates with Russian supply disruptions, compressing margin pools for actuation-integrated manufacturers.
- Supplier Concentration Risk:Three Japanese textile specialists control 70% of fire-blocking foam substrate supply to the region, creating single-source vulnerability for economy seat producers.
- 16g Dynamic Load Certification:Physical crash-test requirements for new seat frames impose capital-intensive testing protocols that filter market access toward R&D-capable incumbents.
Strategic Opportunities
- Vietnam and Indonesia Underpenetration:Emerging low-cost carrier hubs in these markets lack qualified local seat refurbishment infrastructure, creating service-contract whitespace for regional MRO networks.
- PLI Scheme Alignment:India's production-linked incentive framework for aerospace components subsidizes composite seat frame manufacturing, attracting tier-2 suppliers to Bangalore and Hyderabad clusters.
- Smart Seat Convergence:Integration of IoT sensors with power distribution systems is enabling real-time occupancy analytics that carriers monetize through dynamic yield management.
Industry Challenges
- Composite Repair Certification Gap:CAAC has not yet issued standalone repair station authorizations for thermoplastic seat frame damage, forcing operators to replace rather than repair damaged units.
- Legacy Fleet Integration Friction:New lightweight seats require floor track modifications on pre-2015 narrow-body aircraft that were not designed for composite rail attachments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft Cabin Seating Market |
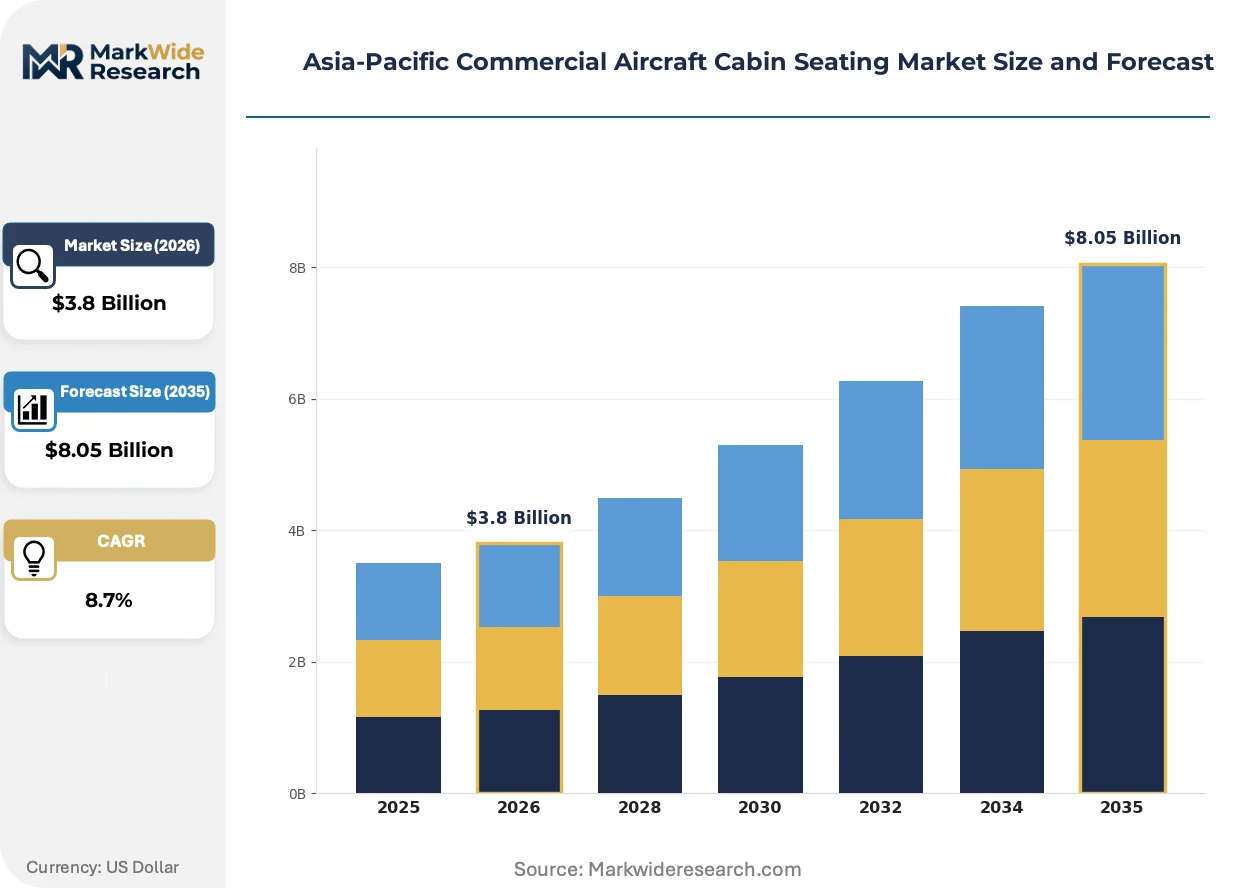
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First Class, Business Class, Economy Class, Premium Economy Material: Leather, Fabric, Plastic, Foam End User: Airlines, Leasing Companies, Private Operators, Government Agencies Installation Type: Fixed, Removable, Convertible, Modular |
| Companies Covered | Collins Aerospace, Adient Aerospace, Jamco Corporation, Safran, Recaro Group, Expliseat, STELIA Aerospace, Thompson Aero Seating, ZIM Aircraft Seating GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft Cabin Seating Market Strategic Shifts
Digital thread integration across seat design-to-manufacture workflows is compressing prototype-to-certification timelines while enabling mass customization at production scale previously reserved for premium configurations.
Automated fiber placement for thermoplastic seat shells is automating layup precision that previously required manual skilled labor, allowing Chinese manufacturers to achieve tolerance consistency within 0.2 millimeters. AirAsia and IndiGo are specifying AFP-produced economy seat backs for 2026 narrow-body deliveries. This automation is compressing labor cost differentials between established European suppliers and emerging Asia-Pacific manufacturers.
CAAC's 2024 revision to CCAR-25 transport category airworthiness standards tightens smoke-density thresholds for cabin materials, mandating new-generation intumescent coatings on all seat upholstery foams. Manufacturers serving Chinese carriers must retest existing product lines against revised burn-through protocols. Full-service airlines operating A350 and B787 fleets into China are accelerating upholstery refresh cycles to maintain route access.
Carrier procurement teams are consolidating seat orders across mixed Airbus-Boeing fleets to extract volume pricing on common economy platforms. VietJet and Scoot have shifted from frame-specific sourcing to platform-agnostic seat families that reduce spare parts complexity. This consolidation is most visible in Singapore and Kuala Lumpur, where procurement hubs coordinate multi-fleet standardization across Southeast Asian airline groups.
Asia-Pacific Commercial Aircraft Cabin Seating Market Segmentation
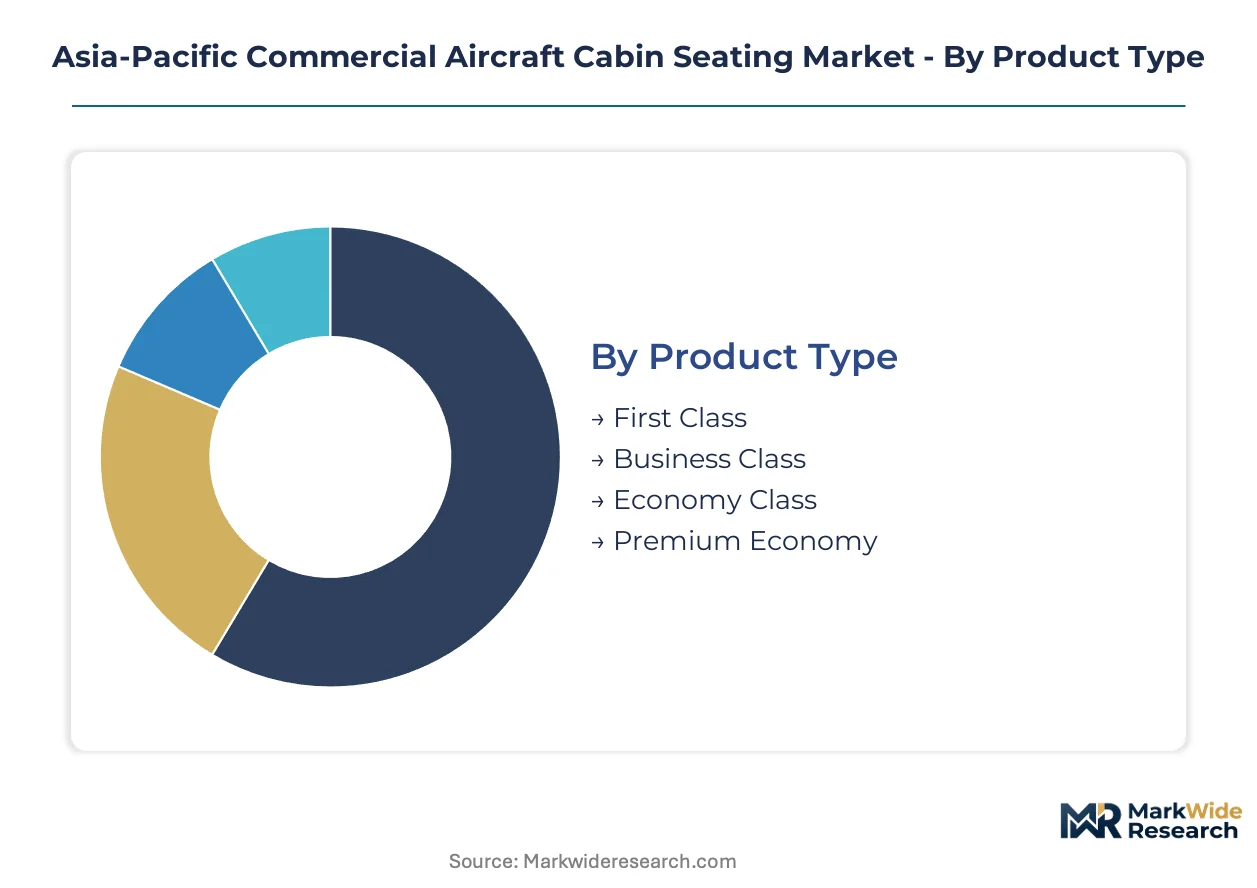
Asia-Pacific cabin seating procurement fragments across four intersecting dimensions that determine supplier qualification burdens and margin structures. Product type and material selection dominate fleet planning conversations, while installation type and end-user category dictate aftermarket service contract design.
Product Type:
Supply concentration in economy and premium economy seating reflects narrow-body fleet dominance across Chinese and Indian carriers.
- Economy Class:Aluminum-frame construction with 16g dynamic load rating and reduced pitch tolerances dominates installation volumes. Chinese low-cost carriers and Indian budget operators drive specification standardization across A320neo and 737 MAX fleets.
- Premium Economy:Wider seat pans and increased recline angles command disproportionate margin pools as full-service carriers seek yield differentiation without business-class complexity. Singapore Airlines and Cathay Pacific anchor regional demand for this configuration.
- Business Class:Lie-flat mechanisms and direct aisle access constrain supplier pools to actuation-integrated manufacturers.
- First Class:Suite-enclosed seating with personal storage and entertainment integration serves ultra-long-haul routes on limited fleet subsets.
Today's leader: Economy Class. Tomorrow's challenger: Premium Economy.
Material:
Cost tier separation between refurbishment cycles and new-build procurement determines material mix across airline business models.
- Fabric:Synthetic weaves meeting 16g fire-blocking standards occupy dominant unit share among cost-sensitive operators. Southeast Asian low-cost carriers specify fabric upholstery for fleet-wide standardization.
- Foam:Fire-blocking polyurethane cores with intumescent coatings face retesting under CAAC's revised CCAR-25 smoke-density thresholds. Chinese carriers and foreign operators serving Chinese routes accelerate refresh cycles to maintain compliance.
- Leather:Full-grain and synthetic leather dominates refurbishment demand among full-service airlines targeting brand positioning.
- Plastic:Thermoplastic matrix shells are displacing aluminum in seat back structures under GB 8624 flammability mandates.
Volume concentrates in fabric and foam. Margin expansion favors leather and thermoplastic conversions.
End User:
Customer type fragmentation shapes contract structure from design ownership to lease-return condition management.
- Airlines:Direct procurement with multi-fleet standardization mandates dominates installation volume. AirAsia and IndiGo consolidate seat families across mixed Airbus-Boeing fleets to reduce spare parts complexity.
- Leasing Companies:Residual value protection drives specification conservatism and standardized seat configurations for secondary market liquidity.
- Private Operators:Custom interior completions for business jet and VIP conversions represent specialized demand with extended lead times.
- Government Agencies:Military and head-of-state transport requirements impose additional security and survivability specifications beyond commercial standards.
Airlines command volume leadership. Leasing companies are gaining specification influence through sale-leaseback structures.
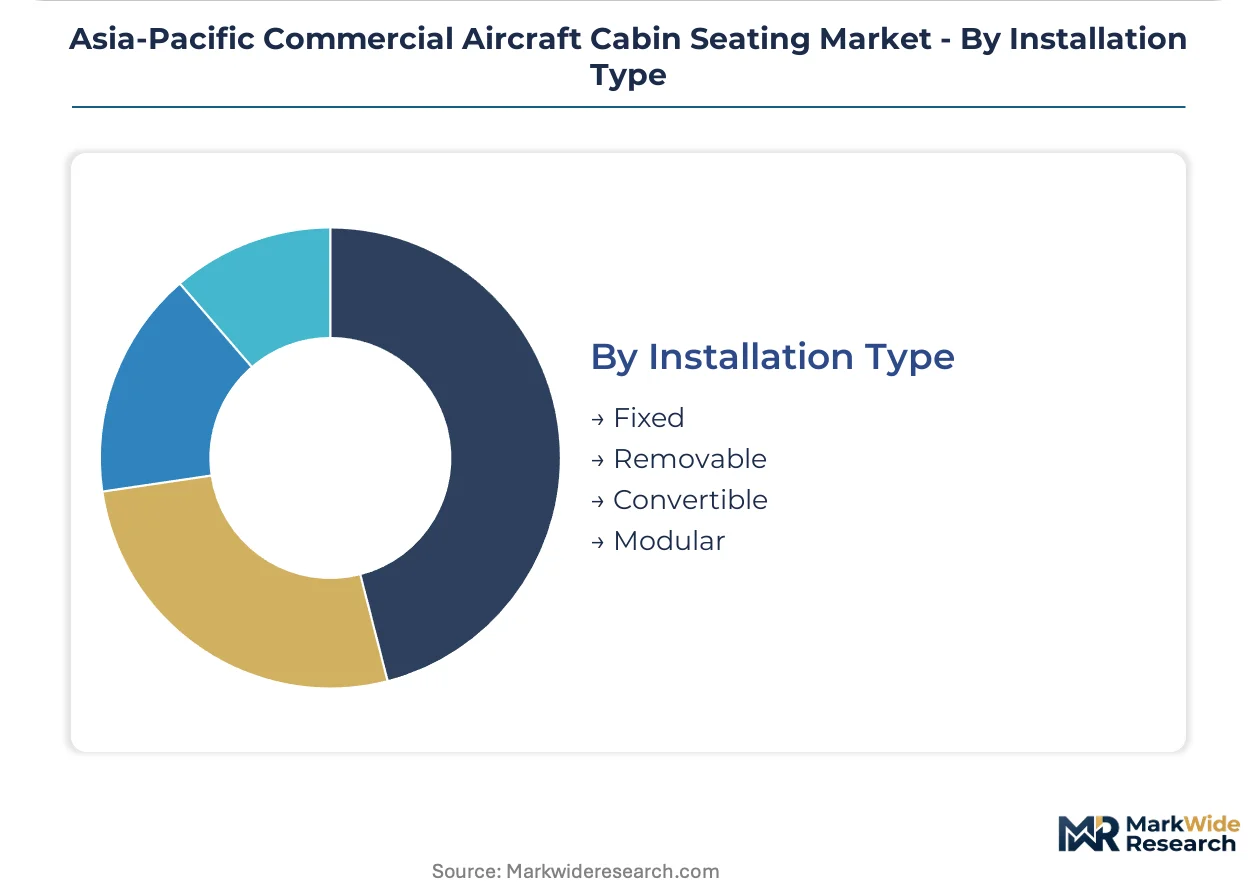
Installation Type:
Floor track compatibility and reconfiguration flexibility determine retrofit economics across aging narrow-body fleets.
- Fixed:Permanent rail attachment dominates new-build narrow-body deliveries with optimized weight distribution.
- Removable:Quick-release mechanisms serve mixed-use cabins and seasonal capacity adjustments on regional aircraft.
- Convertible:Seat-to-cargo and seat-to-berth transformations address multi-mission government and private operator requirements.
- Modular:Standardized rail interfaces enable rapid reconfiguration without structural modification, gaining traction among leasing companies managing multiple lessee transitions.
Fixed installation anchors new-build volume. Modular systems are climbing fastest in aftermarket retrofit planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerospace engineering talent concentrates in Shanghai, Bangalore, and Singapore, anchoring the region's seat design and certification capabilities. These clusters support both indigenous manufacturers and foreign suppliers establishing local R&D presence. Workforce depth varies sharply across the region, with some markets lacking qualified composite technicians.
China
CAAC certification protocols compress supplier qualification timelines for composite-intensive seating designs. GB 8624 flammability standards mandate thermoplastic matrix replacements for traditional aluminum frames in premium configurations. Shanghai and Tianjin host the dominant manufacturing clusters where local fabricators achieve automated fiber placement tolerance consistency within 0.2 millimeters.
India
Airlines consolidate seat families across mixed Airbus-Boeing fleets to reduce spare parts complexity. India's production-linked incentive framework subsidizes composite seat frame manufacturing, attracting tier-2 suppliers to Bangalore and Hyderabad. These southern clusters now support indigenous actuation component production previously imported from European sources.
Japan
Three domestic textile specialists control the majority of fire-blocking foam substrate supply to regional economy seat producers. METI standards align with EASA CS-25 harmonization requirements, enabling Japanese suppliers to serve dual-certification pathways for Chinese and Indian carriers. Nagoya and Tokyo maintain specialized testing facilities for 16g dynamic load certification.
Singapore
Full-service carriers anchor regional demand for premium economy configurations with wider seat pans and increased recline angles. The Civil Aviation Authority of Singapore enforces strict weight-certification standards that favor composite-intensive designs. Changi serves as the procurement coordination hub for Southeast Asian airline groups standardizing multi-fleet seat orders.
Vietnam
Emerging low-cost carrier hubs lack qualified local seat refurbishment infrastructure, creating service-contract whitespace for regional MRO networks. VietJet's fleet expansion drives specification standardization across A320neo deliveries. Ho Chi Minh City attracts maintenance providers establishing composite repair capabilities ahead of CAAC standalone repair station authorizations.
Asia-Pacific Commercial Aircraft Cabin Seating Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific cabin seating market. The vendor base stratifies into three tiers: integrated aerospace groups with avionics-to-interiors portfolios, dedicated seat manufacturers with vertical control over actuation systems, and regional fabricators leveraging automated production technologies. Market access filters toward R&D-capable incumbents capable of meeting compressed CAAC qualification timelines. Dominant competitive moves include strategic partnerships with Chinese carriers for local R&D localization and capacity expansion in Indian PLI-subsidized clusters.
Within the integrated aerospace tier, Collins Aerospace and Safran occupy positions exemplifying diversified portfolio strategies. Collins leverages its avionics-to-interiors breadth to anchor retrofit programs across Chinese and Indian carriers. Safran represents vertical control over seat actuation and power distribution systems. Among dedicated seat specialists, Recaro Group exemplifies the lightweight economy seating archetype serving fuel-efficiency mandates for narrow-body operators. These three anchors illustrate how competitive positioning depends on portfolio breadth versus functional depth trade-offs.
| Leading Market Players |
|---|
| Collins Aerospace |
| Adient Aerospace |
| Jamco Corporation |
| Safran |
| Recaro Group |
| Expliseat |
| STELIA Aerospace |
| Thompson Aero Seating |
| ZIM Aircraft Seating GmbH |
| Others |
Value Chain & Pricing Dynamics
Captive production of actuation hardware and fire-blocking foam substrates anchors supplier pricing power across Asia-Pacific cabin seating procurement. Collins Aerospace and Safran leverage in-house manufacturing of seat mechanisms to resist margin compression from titanium input volatility, while Japanese textile specialists command premium positioning through concentrated fire-blocking substrate supply.
Pricing Analysis
Capacity additions in India and Vietnam are reshaping price floors for economy-class seating as PLI-subsidized composite frame manufacturing attracts tier-2 suppliers to Bangalore and Hyderabad clusters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with full-service carriers least price-sensitive and low-cost operators driving volume procurement at stripped specifications. Price differentiation stems from CAAC-EASA dual-certification pathways and automated fiber placement tolerance consistency. Cost compression in economy seating intensifies because Chinese manufacturers achieve 0.2-millimeter AFP precision previously reserved for European incumbents.
Supply Chain Analysis
Refurbishment flows and lease-return seat reconditioning create reverse-logistics complexity that favors regional MRO networks with composite repair capabilities ahead of CAAC standalone authorizations. Component fabrication concentrates in China, Japan, and India, with Shanghai and Tianjin hosting dominant thermoplastic shell manufacturing and Nagoya maintaining specialized fire-blocking foam production. Aerospace-grade titanium for actuation hardware and synthetic textile weaves for upholstery draw from Russian and Japanese supply bases respectively. Single-source vulnerability runs through Japanese fire-blocking foam substrate specialists controlling majority regional supply. Distribution runs through procurement hubs in Singapore and Kuala Lumpur coordinating multi-fleet standardization across Southeast Asian airline groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific commercial aircraft cabin seating functions as a stable compounder anchored by narrow-body fleet renewal cycles across Chinese and Indian carriers that sustain installation volumes regardless of macroeconomic volatility.
For Market Incumbents: Hedge titanium input exposure through long-term offtake agreements with alternative suppliers outside Russian supply corridors. Accelerate automated fiber placement capacity in Indian PLI-subsidized clusters to match Chinese cost structures. Defend margin position by deepening captive supply of seat actuation components against emerging tier-2 competitors. For New Entrants and Emerging Players: Thermoplastic composite repair certification gaps create immediate service-contract whitespace in Vietnam and Indonesia where qualified MRO infrastructure remains underdeveloped. Target lease-return refurbishment cycles for modular seat systems as leasing companies gain specification influence through sale-leaseback structures. Pursue go-to-market partnerships with regional airline procurement hubs in Singapore standardizing multi-fleet seat families. For Investors and Strategic Acquirers: Consolidation pressure builds where R&D-capable manufacturers face compressed qualification timelines from CAAC-EASA harmonization requirements that filter market access. Five-to-ten-year viability favors suppliers with vertical control over actuation systems and localized fire-testing capabilities. Monitor CAAC standalone repair station authorization timelines for thermoplastic seat frames as inflection indicator for aftermarket service contract monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | Chinese manufacturers achieve 0.2-millimeter tolerance consistency matching European precision. |
| CAAC-EASA Dual-Certification Investment | Compliant suppliers reduce seat qualification timelines from eighteen to twelve months. |
| Composite Repair Infrastructure Buildout | Ho Chi Minh City maintenance providers establish capabilities ahead of regulator authorizations. |
| Actuation Hardware Backward Integration | Bangalore clusters now support indigenous component production previously European-sourced. |
| Multi-Fleet Seat Family Standardization | VietJet and Scoot consolidate procurement across mixed Airbus-Boeing fleets. |
Study Parameters
Coverage spans China, India, Japan, Singapore, and Vietnam, with primary inputs from each market cluster combining structured interviews with airline procurement directors, seat manufacturer program managers, CAAC certification engineers, and regional MRO operations heads. Secondary validation draws from CAAC airworthiness directive filings, EASA CS-25 harmonization documentation, Indian PLI scheme disbursement records, and fleet delivery databases from Airbus and Boeing. Bottom-up installation volume estimates triangulate against top-down narrow-body delivery projections.
Segmentation granularity models product type at seat-class level, material at frame and upholstery substrate level, end user at carrier versus lessor versus government level, and installation type at fixed versus modular attachment level across the analysis window. CAGRs derive from regression against fleet renewal schedules and regulatory compliance cycle timing. Industry-specific inputs include GB 8624 flammability standard revision impacts and CAAC CCAR-25 smoke-density threshold changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAAC-EASA bilateral agreement evolution and titanium supply corridor stability. Forecasts reflect documented assumptions regarding narrow-body delivery schedules and certification timeline compression. Practitioners should monitor CAAC standalone thermoplastic repair station authorization issuance and Indian PLI scheme extension decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market