
 High Level Brake Lamp Market | 2026-2036
High Level Brake Lamp Market Size, Share, and Industry Trends Forecast 2026-2036
High Level Brake Lamp Market Insights
Fleet operators is redrawing procurement priorities in the High Level Brake Lamp Market as commercial vehicle safety mandates tighten. Hella leverages its European manufacturing base to sustain LED module leadership. Koito anchors Asian OEM supply chains through dedicated high-mount stop lamp platforms. Stanley Electric differentiates via optical design specialization for premium passenger segments.
A high level brake lamp is a supplementary rear illumination device mounted at or near the vertical centerline of a vehicle, typically operating at luminous intensity between 25 and 150 candela depending on regulatory class, designed to enhance rear visibility signaling during deceleration events. LED product type commands the dominant value share due to thermal efficiency and design flexibility, though halogen retains residual volume in cost-sensitive fleet retrofit channels. Direct fit installation type captures the majority of OEM contract value, while universal fit serves the fragmented aftermarket where margin pools concentrate in certified plug-and-play conversions.
ECE R48, DOT FMVSS 108, and SAE J586 govern photometric performance, mounting height, and activation latency requirements across major automotive markets. EMA and NHTSA compliance testing shapes product development cycles and determines market access eligibility for lamp assemblies. Stakeholders must monitor harmonization gaps between UN ECE and federal standards as electrification architectures reshape rear lamp integration protocols.
Market Dynamics
Electric vehicle platform architectures are forcing modular lamp integration protocols that fuse lighting with battery management and ADAS communication stacks, compressing supplier development cycles and elevating systems engineering capabilities above component manufacturing scale.
Growth Catalysts
- ECE R48 visibility mandates:European regulators tightened photometric performance thresholds for supplementary stop lamps, compelling OEMs to upgrade high-mount installations across model refreshes.
- LED thermal efficiency gains:Advanced substrate materials now sustain luminous output above 100 candela without active cooling, enabling thinner lamp housings that integrate with aerodynamic rooflines.
- Germany's supplier corridor concentration:Tier 1 lamp manufacturers cluster within 200 kilometers of Stuttgart and Munich, creating captive engineering partnerships with premium OEM headquarters.
Market Restraints
- Automotive-grade LED die supply concentration:Epitaxial wafer production concentrates among three Asian substrate manufacturers, exposing lamp assemblers to allocation volatility during semiconductor cycle peaks.
- Homologation cost escalation:UN ECE type approval testing for ECE R48 compliance now requires multi-axis photometric validation that adds fourteen to eighteen months to product launch timelines.
- Residual halogen aftermarket:Cost-sensitive commercial fleet operators in Eastern European markets continue sourcing universal-fit incandescent retrofits, fragmenting volume and compressing margin pools at the low end.
Strategic Opportunities
- Software-defined vehicle integration:Lamp modules with CAN-FD communication capability enable dynamic intensity modulation and diagnostic feedback, creating recurring firmware revenue streams.
- India's PLI scheme for auto components:Domestic manufacturing incentives for advanced automotive electronics attract lamp suppliers establishing regional assembly for Maruti Suzuki and Tata Motors platforms.
- Smart trailer telematics convergence:High-mount stop lamps with integrated RF antennas and cargo sensors address fleet operator demand for consolidated rear-end hardware on commercial rigs.
Industry Challenges
- Optomechanical engineering scarcity:Lamp suppliers compete for talent possessing combined expertise in thermal simulation, optical ray-tracing, and automotive EMC validation.
- Legacy 12V electrical architecture integration:New LED driver circuits must maintain compatibility with aging truck and bus electrical systems without voltage conditioning hardware that inflates bill-of-materials cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Level Brake Lamp Market |
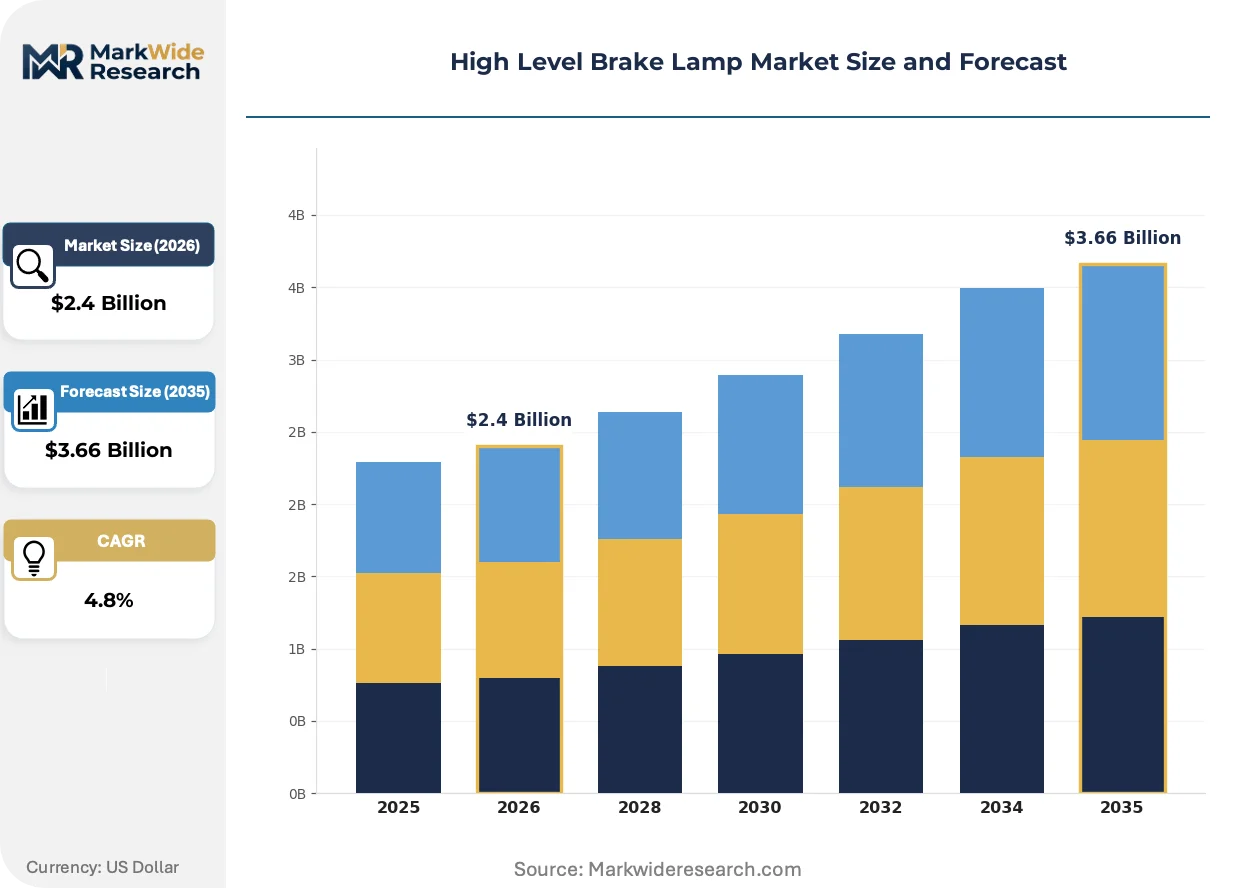
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Incandescent, Xenon End User: OEMs, Aftermarket Providers, Retailers, Fleet Operators Installation Type: Direct Fit, Universal Fit, Custom Fit, Plug-and-Play Certification: DOT, ECE, SAE, ISO |
| Companies Covered | Hella, Stanley Electric, Koito, Valeo, Magneti Marelli, ZKW Group, SL Corporation, Varroc, Osram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Level Brake Lamp Market Trends and Innovations
Photonic integration and regulatory harmonization pressures are compressing the traditional boundary between lamp hardware and vehicle electronics, elevating software competency and thermal management to primary competitive differentiators.
Multi-chip LED arrays with ceramic substrate thermal vias are displacing discrete packaged LEDs in premium passenger vehicle applications. German and Japanese OEM procurement teams now specify these platforms for flagship electric sedans launching between 2026 and 2028. The technology is displacing conventional PCB-mounted diode configurations by enabling 40% thinner lamp profiles without active cooling fans.
UN ECE Working Party on Lighting and Light-Signalling is advancing harmonized test protocols that bridge gaps between ECE R48 and DOT FMVSS 108 activation latency requirements. Lamp suppliers face dual homologation cost burdens until 2027 ratification, after which single-test certification will unlock transatlantic platform sharing. North American OEM engineering centers are pre-qualifying ECE-compliant designs to accelerate post-harmonization sourcing.
Fleet operators now contract directly with lamp module suppliers for lifecycle availability guarantees, bypassing traditional aftermarket distribution tiers. Commercial vehicle lessors in the US and Germany negotiate ten-year spare part commitments during initial platform procurement. This behavior concentrates volume with vertically integrated manufacturers possessing captive semiconductor die sourcing and regional warehouse networks.
High Level Brake Lamp Market Segmentation
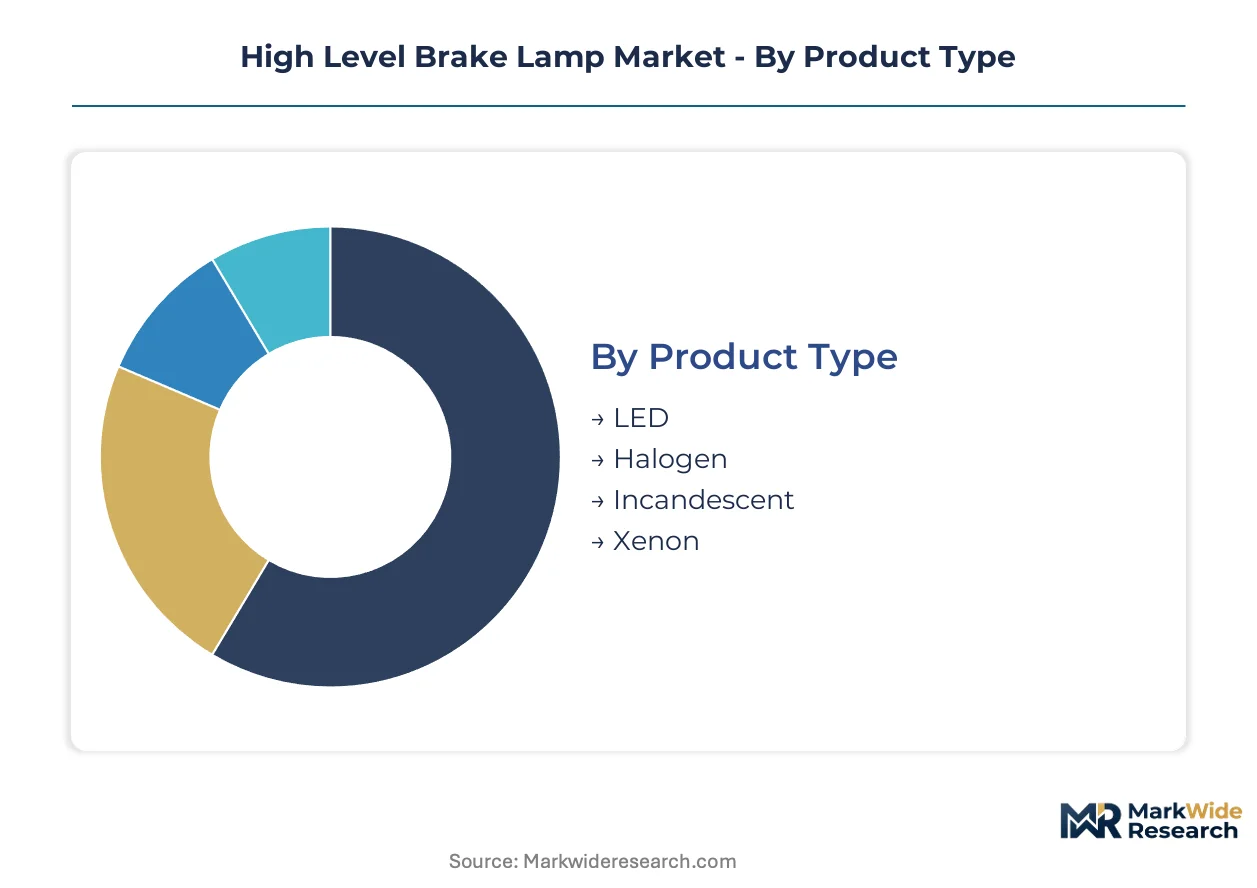
Segmentation in the High Level Brake Lamp Market determines which supplier capabilities align with specific procurement channels. Product technology, installation protocols, and certification requirements create distinct competitive arenas with divergent margin structures and customer loyalty patterns.
Product Type:
Channel mix varies sharply by light source technology, with LED modules flowing predominantly through OEM direct contracts while halogen and legacy formats persist in aftermarket retrofit channels.
- LED:Multi-chip arrays on ceramic substrates deliver luminous intensity above 100 candela without active cooling. German and Japanese OEM procurement teams specify these platforms for flagship electric sedans, compressing lamp profiles to integrate with aerodynamic rooflines. By volume, LED leads. By growth pace, advanced ceramic-substrate configurations are expanding most quickly.
- Halogen:Tungsten-halogen capsules retain residual demand in Eastern European commercial fleet retrofits where cost sensitivity overrides efficiency considerations. Cost-sensitive operators in Poland and Romania continue sourcing universal-fit incandescent replacements, fragmenting volume at the low end.
- Incandescent:Legacy bulb technology persists in aging truck and bus electrical architectures requiring 12V compatibility without driver circuit modifications.
- Xenon:High-intensity discharge systems occupy niche applications in premium commercial vehicles where instantaneous full-brightness activation is prioritized over thermal efficiency.
LED captures the dominant value share while halogen retains pockets of volume in cost-constrained retrofit channels.
End User:
Customer type determines contract structure, with OEMs demanding systems engineering capabilities and fleet operators negotiating lifecycle availability guarantees.
- OEMs:Original equipment manufacturers contract for modular lamp integration protocols that fuse lighting with battery management and ADAS communication stacks. Stuttgart and Munich engineering centers drive specification intensity for premium passenger platforms.
- Aftermarket Providers:Distributors and jobbers source certified plug-and-play conversions, concentrating margin pools in regulatory compliance documentation and regional warehouse networks.
- Retailers:Consumer-facing channels stock universal-fit LED retrofits for passenger vehicle owners seeking visibility upgrades outside warranty periods.
- Fleet Operators:Commercial vehicle lessors in the US and Germany negotiate ten-year spare part commitments during initial platform procurement, bypassing traditional distribution tiers.
OEM contracts generate the highest per-unit margins, while fleet operator direct sourcing is gaining share fastest in commercial vehicle segments.
Installation Type:
Installation protocol shapes supplier capability requirements, from precision-engineered direct fit modules to flexible universal configurations.
- Direct Fit:Vehicle-specific lamp housings engineered to exact mounting geometries and electrical pinouts. OEM procurement teams specify these for model-refresh programs where ECE R48 compliance mandates hardware upgrades.
- Universal Fit:Adjustable mounting brackets and adapter harnesses accommodate multiple vehicle platforms. Fragmented aftermarket demand concentrates in cost-sensitive Eastern European markets.
- Custom Fit:Bespoke lamp assemblies for specialty vehicle manufacturers and coachbuilders requiring non-standard mounting heights or aesthetic treatments.
- Plug-and-Play:Pre-wired LED modules with integrated drivers simplify retrofit installation for aftermarket technicians and fleet maintenance crews.
Direct fit commands OEM contract value, while plug-and-play configurations show the steepest expansion trajectory in aftermarket channels.
Certification:
Regulatory approval requirements create market access barriers that segment suppliers by testing investment capacity and technical documentation depth.
- DOT:FMVSS 108 compliance testing administered by NHTSA governs photometric performance and activation latency for US market entry. North American OEM engineering centers are pre-qualifying ECE-compliant designs to accelerate post-harmonization sourcing.
- ECE:UN ECE R48 type approval requires multi-axis photometric validation, adding fourteen to eighteen months to product launch timelines. German Tier 1 suppliers cluster within 200 kilometers of Stuttgart to maintain captive engineering partnerships.
- SAE:Society of Automotive Engineers standards provide voluntary performance benchmarks that influence procurement specifications in North American commercial vehicle segments.
- ISO:International Organization for Standardization protocols for quality management and environmental systems support supplier qualification for multinational OEM vendor lists.
ECE certification carries the broadest geographic recognition, while DOT compliance remains essential for North American market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier engineering capabilities cluster within 200 kilometers of Stuttgart and Munich, creating captive partnerships with premium OEM headquarters. German Tier 1 manufacturers dominate high-mount stop lamp specifications for European electric vehicle platforms. Procurement teams in Japan, the United States, and India are developing alternative sourcing corridors to reduce dependency on this concentrated supplier base.
Germany
ECE R48 compliance mandates drive hardware upgrades across model refresh programs. The KBA administers type approval testing that adds fourteen to eighteen months to product launch timelines. Engineering centers in Stuttgart and Munich specify ceramic-substrate LED arrays for flagship electric sedans.
United States
Fleet operators negotiate ten-year spare part commitments during initial platform procurement. NHTSA FMVSS 108 testing governs photometric performance and activation latency requirements. Engineering centers in Michigan and California pre-qualify ECE-compliant designs to accelerate post-harmonization sourcing.
Japan
OEM procurement teams specify multi-chip LED arrays for domestic and export electric vehicle platforms. METI oversees industrial standards coordination with UN ECE harmonization initiatives. Manufacturing clusters in Aichi and Kanagawa prefectures anchor supply chain relationships with Asian OEM headquarters.
India
Domestic OEM platforms from Maruti Suzuki and Tata Motors attract regional lamp assembly investment. The PLI scheme for auto components incentivizes advanced automotive electronics manufacturing. Supplier engineering partnerships concentrate in Pune and Chennai automotive corridors.
China
Electric vehicle platform volumes drive specification intensity for integrated lamp modules. MIIT governs GB standards compliance for rear lighting systems. Manufacturing capacity clusters in the Yangtze River Delta serve domestic OEMs and export markets.
High Level Brake Lamp Market Competitive Landscape
Concentration sits with vertically integrated European and Asian lamp manufacturers possessing captive semiconductor die sourcing and regional warehouse networks. The supplier base organizes around three strategic archetypes: full-system integrators with ADAS communication capabilities, optical specialists with thermal management expertise, and scale-driven assemblers serving cost-sensitive fleet retrofit channels. Competitive moves center on firmware-enabled recurring revenue streams and lifecycle availability guarantees that bypass traditional aftermarket distribution tiers.
Among European-based suppliers, Hella and Valeo exemplify the full-system integrator archetype with modular lamp platforms. Stanley Electric and Koito occupy positions within the Asian specialist tier, anchoring supply relationships with domestic OEM engineering centers. These named entities represent the geographic and capability clustering that defines procurement access in premium passenger and commercial vehicle segments.
| Leading Market Players |
|---|
| Hella |
| Stanley Electric |
| Koito |
| Valeo |
| Magneti Marelli |
| ZKW Group |
| SL Corporation |
| Varroc |
| Osram |
| Others |
Pricing and Supply Chain Analysis
Automotive-grade LED die fabrication scale in Taiwan, South Korea, and Japan concentrates upstream capacity utilization above 85 percent, compressing component cost curves for lamp assemblers while simultaneously elevating price floors during semiconductor allocation cycles. This scale dynamic binds pricing power to captive substrate sourcing relationships and regional warehouse positioning.
Pricing Analysis
Volume-discount tiering structures separate OEM direct contracts from fragmented aftermarket channels. Premium ceramic-substrate LED modules command price differentiation through ECE R48 certification grade and thermal performance guarantees, while universal-fit halogen retrofits face pricing pressure from cost-sensitive Eastern European fleet operators. OEM procurement teams exhibit least price sensitivity due to ten-year lifecycle availability requirements, whereas commercial retrofit buyers drive margin compression at the economy tier.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability on Asia-Europe trade lanes, directly impacting landed cost for epitaxial wafer shipments. Supply concentrates in Germany for Tier 1 lamp assembly, Taiwan and South Korea for LED die fabrication, and China for driver circuit components. Raw material dependencies span aluminum nitride ceramic substrates, copper thermal vias, and automotive-grade silicone encapsulants. Single-source vulnerability in epitaxial wafer production exposes assemblers to allocation volatility. Distribution runs through captive OEM supply chains and certified aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The High Level Brake Lamp Market sits in early-stage cyclical recovery as electric vehicle platform volumes normalize procurement schedules following semiconductor supply disruptions. OEM production cadence stabilization provides the cyclical anchor.
For Market Incumbents: Consolidate optical engineering talent pools in Stuttgart and Munich corridors to defend against modular platform standardization threats from emerging systems integrators. Deepen backward integration into ceramic substrate sourcing to secure thermal performance leadership. Prioritize ECE-DOT harmonization pre-qualification investments to accelerate post-ratification transatlantic contract capture.
For New Entrants and Emerging Players: Firmware-over-the-air update capabilities for lamp diagnostic modules represent a service-layer gap where incumbents under-serve fleet operator demand for predictive maintenance integration. Target India's PLI scheme corridors for regional assembly partnerships with Maruti Suzuki and Tata Motors platforms. Pursue direct fleet operator contracting models that bypass traditional aftermarket distribution markups.
For Investors and Strategic Acquirers: Optical specialists with combined thermal simulation and EMC validation capabilities present acquisition target archetypes positioned for software-defined vehicle integration premiums. Long-term viability hinges on firmware-enabled recurring revenue attachment rates rather than hardware shipment volumes alone. Monitor UN ECE Working Party ratification timelines as inflection indicators for transatlantic platform sharing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive thermal via production insulates Hella and Valeo from LED die allocation volatility. |
| ECE-DOT Harmonization Pre-Qualification | Single-test certification post-ratification unlocks transatlantic OEM platform sharing contracts. |
| Fleet Direct Lifecycle Contracting | Ten-year spare part commitments concentrate volume with vertically integrated manufacturers. |
| Software-Defined Lamp Module Development | CAN-FD diagnostic capability creates recurring firmware revenue streams beyond hardware sales. |
| India PLI Regional Assembly Investment | Domestic manufacturing incentives attract lamp suppliers for Maruti Suzuki and Tata Motors platforms. |
Research Methodology
Desk research of ECE R48 regulatory filings, NHTSA FMVSS 108 compliance databases, and automotive production registration data preceded structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and fleet operator maintenance heads. Secondary validation drew from vehicle production databases, customs trade records for LED component flows, and SEC filings of listed lamp manufacturers. Bottom-up segment volume builds triangulated against top-down OEM procurement budget allocations.
Variance decomposition across product technology, installation protocol, end-user archetype, and certification tier shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included electric vehicle platform launch schedules and UN ECE harmonization ratification assumptions.
Forecasts assume regulatory continuity in ECE R48 and DOT FMVSS 108 regimes; material policy shifts would require re-modeling. Semiconductor cycle volatility and automotive production disruption represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Transfer Case Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market