
 Secondary Packaging Market | 2026-2036
Secondary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Packaging Market Outlook
Food-grade barrier specification is rotating toward higher virgin-fiber content and moisture-resistant coatings as pharmaceutical and fresh-food shippers reject recycled-stock failures. Mondi Group leverages integrated pulp-to-board operations across Central Europe to control substrate quality from forest to converter. Smurfit Westrock anchors North American corrugated supply through mill-level scale and just-in-time plant networks. DS Smith plc differentiates via circular-design consulting that locks in multinational food accounts with reusable-loop contracts.
Secondary packaging denotes the outer containment layer—corrugated cases, shrink-wrapped bundles, or rigid trays—that consolidates primary units for handling, storage, and distribution, typically manufactured from 23–44 lb/msf linerboard or 200–350 micron polyethylene with burst strengths calibrated to ASTM D642 stack-load thresholds. Its commercial purpose centers on unitization efficiency, damage reduction, and supply-chain traceability rather than consumer-facing aesthetics. Cardboard dominates volume across food and beverage end users where recycled-content mandates and lightweighting programs compress cost per shipped case. Plastic films in wrap formats capture growth in electronics and cosmetics where clarity and tamper-evidence outweigh fiber-based alternatives. Sustainable packaging design is concentrating margin pools as brand-owners pay premiums for carbon-accounted, Forest Stewardship Council-certified structures that satisfy Scope 3 reporting requirements.
The EPA enforces recycled-content thresholds under evolving solid-waste frameworks that push converters toward post-consumer fiber integration. ISO 18606 and ASTM D6400 set compostability and biodegradability benchmarks that determine market access for bio-based plastic secondary formats. The EU Green Deal's packaging waste reduction targets are forcing redesign of multi-material laminates that complicate recycling streams. Stakeholders must monitor regulatory divergence between California's extended producer responsibility mandates and federal preemption debates that could fragment compliance architecture across US distribution networks.
Market Dynamics
Pharmaceutical cold-chain logistics is compressing secondary packaging specifications as temperature-sensitive biologics multiply, forcing converters to engineer moisture-resistant barrier structures that withstand thermal cycling without compromising stack-load integrity.
Growth Catalysts
- EU Green Deal packaging waste targets:The regulation mandates redesign of multi-material laminates, accelerating fiber-based substitution and creating certified circular-design contracts with multinational food accounts.
- Biologics distribution expansion:Temperature-sensitive pharmaceutical shipments require advanced protective formats with validated thermal performance, pulling demand toward engineered corrugated and insulated barrier systems.
- German pharmaceutical export concentration:Europe's largest pharma export base drives specification intensity for damage-reduction formats in cross-border distribution.
Market Restraints
- Recycled fiber quality volatility:Post-consumer stock failures in moisture-critical applications force shippers toward higher virgin-fiber content, compressing margin pools as raw material costs fluctuate with pulp commodity cycles.
- Central European substrate concentration:Integrated pulp-to-board operations cluster in Germany, Austria, and Poland, creating supply vulnerability when energy or logistics disruptions hit this corridor.
- Multi-material laminate incompatibility:Existing film-fiber combinations complicate recycling streams and face regulatory friction under evolving EU packaging waste frameworks.
Strategic Opportunities
- Reusable-loop contract penetration:Circular-design consulting locks in multinational accounts through carbon-accounted, Forest Stewardship Council-certified structures that satisfy Scope 3 reporting requirements.
- Indian pharmaceutical distribution modernization:Cold-chain infrastructure buildout for generic drug exports creates specification upgrade pathways for temperature-validated secondary formats.
- ISO 18606 compostability certification:Bio-based plastic secondary formats gain market access as compostability benchmarks determine regulatory acceptance in premium European fresh-food channels.
Industry Challenges
- Barrier coating chemistry expertise gap:Moisture-resistant virgin-fiber formulations require polymer science capabilities scarce among traditional corrugated converters.
- ASTM D6400 biodegradability testing timeline:Certification delays for bio-based formats extend product launch cycles and tie up R&D capital.
- Legacy ERP integration with traceability systems:Supply-chain visibility mandates for pharmaceutical serialization conflict with decades-old converter IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Packaging Market |
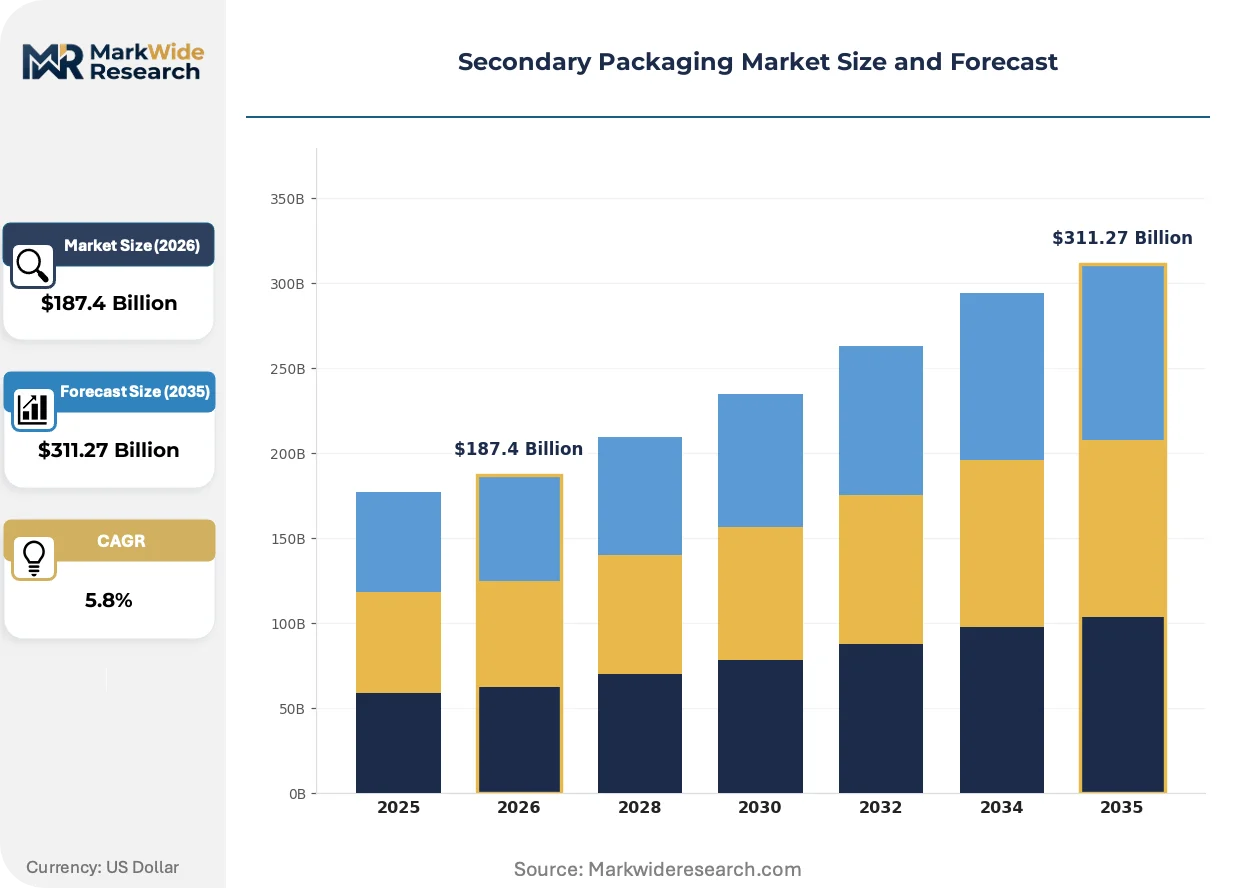
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Metal, Glass Product Type: Boxes, Bags, Trays, Wraps End User: Food & Beverage, Cosmetics, Pharmaceuticals, Electronics Packaging Design: Protective, Functional, Labeling, Sustainable |
| Companies Covered | Packaging Corporation of America, Mondi Group, Smurfit Westrock, Sonoco Products Company, DS Smith plc, International Paper Company, Graphic Packaging Holding Co., Amcor plc, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Packaging Market Strategic Shifts
Active RFID-embedded smart packaging is reshaping how secondary formats communicate handling history and authenticity, converting passive containment into data-generating infrastructure that pharmaceutical and electronics shippers now specify in procurement tenders.
Printed electronics integration with temperature-logging sensors is miniaturizing cold-chain monitoring costs from dedicated data loggers to sub-dollar film inserts. Pharmaceutical 3PL providers in Germany and the Netherlands are specifying these formats for high-value biologics lanes. The technology is miniaturizing quality-assurance infrastructure, enabling lane-level traceability without dedicated hardware capital.
REACH substance restrictions and F-Gas Regulation phase-downs are eliminating certain blowing agents and coating chemistries from European secondary packaging supply chains. Converters must reformulate barrier foams and adhesives to maintain thermal performance under tightened environmental safety thresholds. German automotive parts distributors face compressed compliance timelines as these rules synchronize with EU Green Deal packaging waste reduction targets.
Buyer consolidation among pharmaceutical 3PLs is concentrating procurement leverage and compressing supplier rosters toward vertically integrated converters with in-house testing and certification capabilities. Smaller regional players without captive pulp supply or ISO 17025 laboratories are losing specification access. This pattern is most visible in the Rhine-Ruhr logistics corridor, where three major 3PLs now control the majority of temperature-validated secondary packaging spend.
Secondary Packaging Market Segmentation
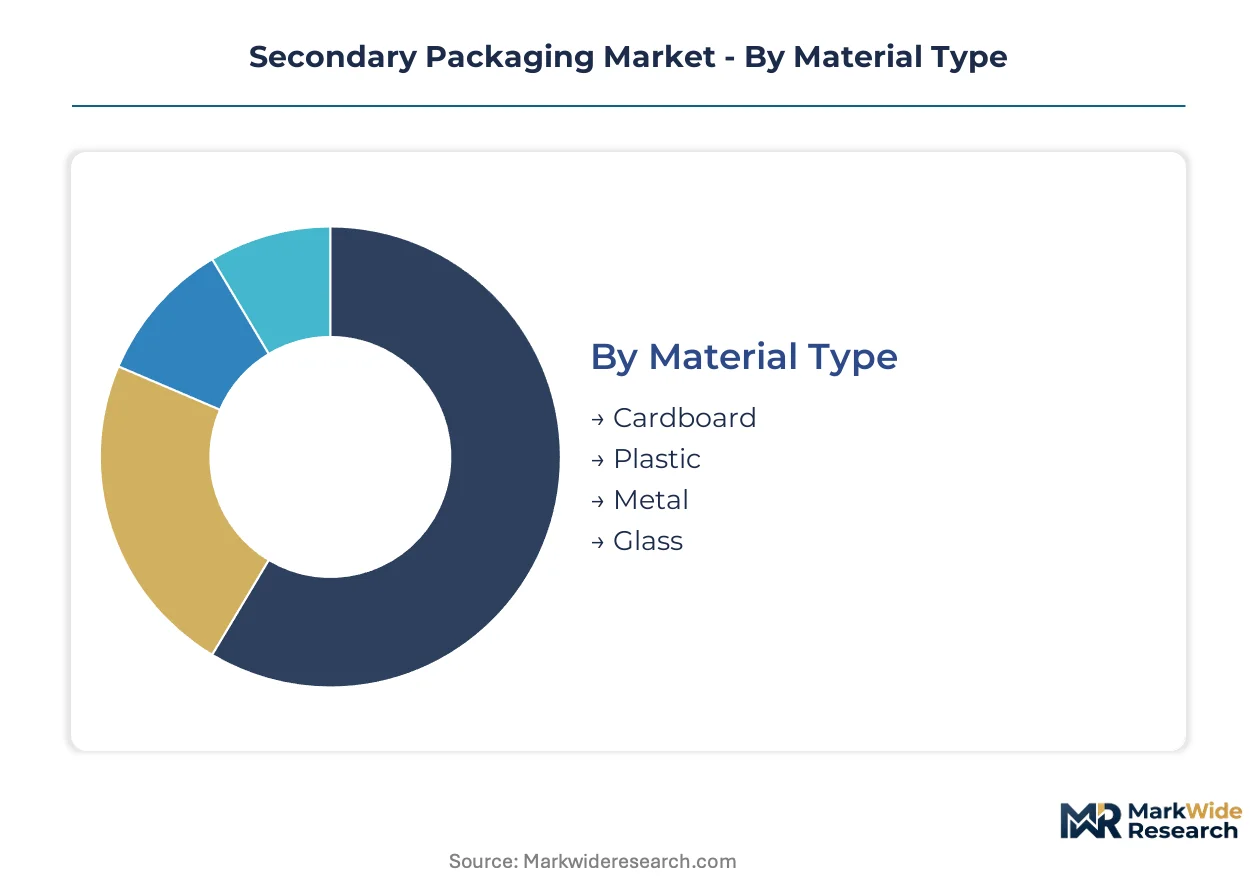
Secondary packaging specification intensity varies sharply by material chemistry and end-use compliance burden, with pharmaceutical and cold-chain applications commanding premium engineering while commodity food service drives volume consolidation.
Material Type:
Margin pools concentrate in moisture-resistant barrier formulations where virgin-fiber quality commands pricing power over recycled-stock alternatives.
- Cardboard:Manufactured from 23–44 lb/msf linerboard with burst strengths calibrated to ASTM D642 stack-load thresholds. Pharmaceutical cold-chain logistics in Germany and the Netherlands pull demand toward engineered corrugated with validated thermal performance, though recycled-content mandates under the EU Green Deal compress cost structures for commodity food applications.
- Plastic:Extruded films in 200–350 micron polyethylene deliver clarity and tamper-evidence for electronics and cosmetics distribution. REACH substance restrictions and F-Gas Regulation phase-downs are eliminating certain blowing agents from European supply chains, forcing reformulation of barrier foams to maintain performance under tightened environmental safety thresholds.
- Metal:Tinplate and aluminum rigid containers serve high-value industrial components requiring electromagnetic shielding and crush resistance.
- Glass:Borosilicate and soda-lime secondary formats protect precision instrumentation and luxury cosmetics where breakage tolerance approaches zero.
The dominant share belongs to cardboard, while plastic is closing the gap fastest in temperature-validated pharmaceutical applications.
Product Type:
Volume distribution tracks directly against automation compatibility, with formats that integrate seamlessly into robotic palletizing systems capturing share in high-throughput distribution centers.
- Boxes:Rigid corrugated cases dominate pharmaceutical and automotive parts distribution where stack-load integrity and printability for serialization codes are non-negotiable. The Rhine-Ruhr logistics corridor concentrates procurement leverage among three major 3PLs controlling temperature-validated secondary packaging spend.
- Wraps:Shrink and stretch films achieve unitization efficiency in beverage and electronics bundling. Active RFID-embedded smart formats are converting passive containment into data-generating infrastructure that pharmaceutical and electronics shippers now specify in procurement tenders.
- Trays:Thermoformed and molded pulp platforms stabilize primary units during automated handling.
- Bags:Flexible woven and film constructions serve bulk agricultural and chemical distribution.
Boxes retain the largest installed base, though wraps are expanding most quickly through printed electronics integration with temperature-logging sensors.
End User:
Compliance architecture intensity separates segments, with serialization mandates and carbon-accounting requirements fragmenting procurement specifications across verticals.
- Pharmaceuticals:Temperature-sensitive biologics distribution demands moisture-resistant barrier structures that withstand thermal cycling without compromising stack-load integrity. Buyer consolidation among 3PLs is compressing supplier rosters toward vertically integrated converters with in-house ISO 17025 testing capabilities.
- Food & Beverage:Recycled-content thresholds under EPA frameworks and EU packaging waste targets push converters toward post-consumer fiber integration, though quality volatility in moisture-critical applications forces shippers toward higher virgin-fiber content.
- Electronics:Anti-static and moisture-vapor-barrier specifications protect semiconductor and component shipments through multi-modal distribution.
- Cosmetics:Premium unboxing experiences and tamper-evidence requirements favor rigid formats with high-resolution print surfaces.
Food & Beverage commands the greatest tonnage, while pharmaceuticals generate the steepest margin expansion through validated cold-chain formats.
Packaging Design:
Certification tiering is stratifying this category, with Forest Stewardship Council-certified and ISO 18606-compostable structures capturing premium positioning.
- Sustainable:Circular-design consulting locks in multinational accounts through carbon-accounted structures that satisfy Scope 3 reporting requirements. DS Smith plc and similar operators differentiate via reusable-loop contracts that embed long-term volume commitments.
- Protective:Engineered cushioning and barrier systems prevent damage in cross-border pharmaceutical and automotive parts distribution, with German export concentration driving specification intensity.
- Functional:Ergonomic handling features and automation-compatible dimensions reduce labor and equipment capital in high-velocity fulfillment.
- Labeling:Integrated print surfaces and smart-tag receptacles enable supply-chain traceability without secondary processing.
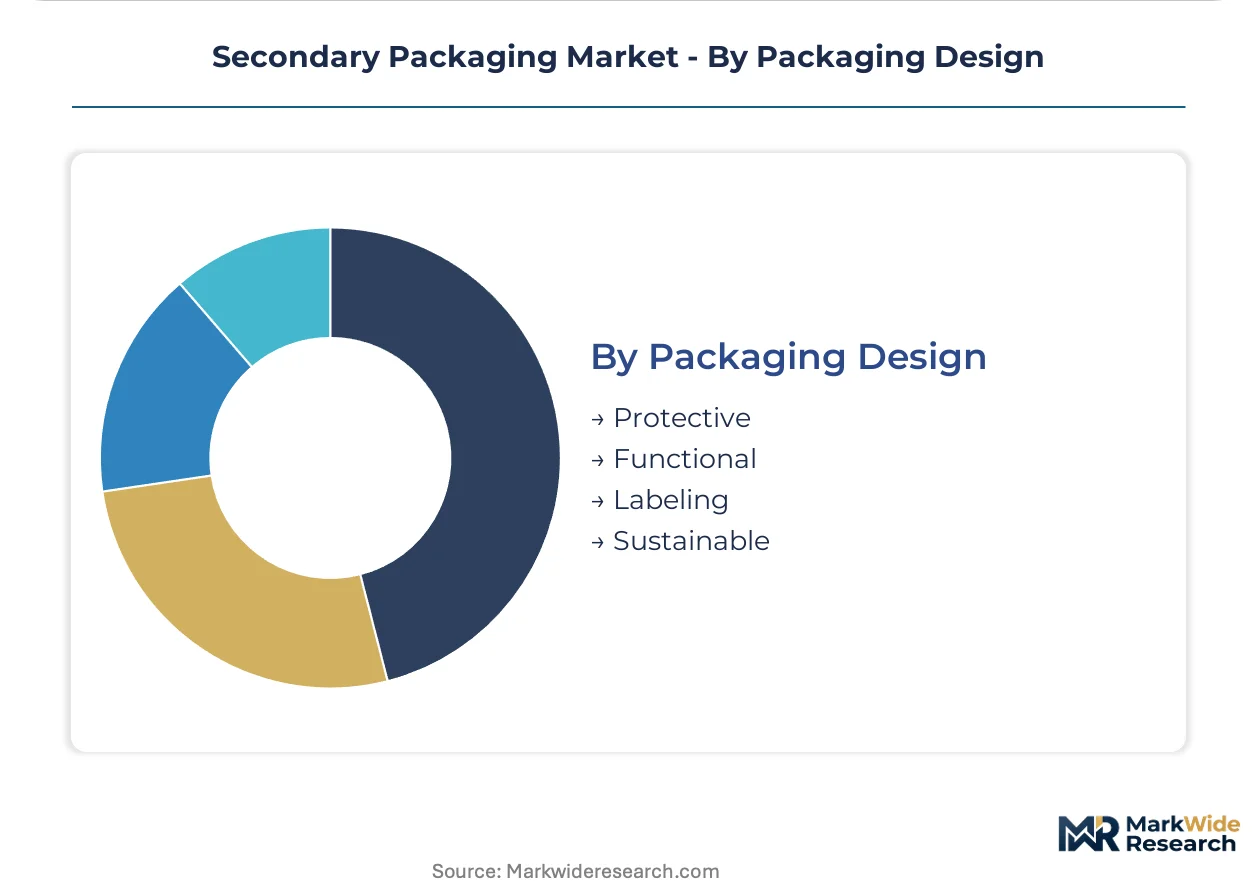
Protective design holds the largest current share, while sustainable formats are gaining share fastest through EU Green Deal packaging waste reduction targets and extended producer responsibility mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-board operations cluster heavily in Central Europe, creating supply vulnerability when energy or logistics disruptions hit this corridor. Pharmaceutical cold-chain infrastructure in Germany and the Netherlands pulls specification intensity toward engineered corrugated formats. Regulatory divergence between California's extended producer responsibility mandates and federal preemption debates fragments compliance architecture across distribution networks.
Germany
Pharmaceutical exports and automotive parts distribution require advanced protective formats with validated thermal performance. The EU Green Deal and F-Gas Regulation tighten material specifications and eliminate certain blowing agents from barrier foams. The Rhine-Ruhr logistics corridor concentrates procurement leverage among three major 3PLs controlling temperature-validated secondary packaging spend.
United States
Food and beverage shippers drive volume demand through recycled-content mandates and lightweighting programs compressing cost per shipped case. The EPA enforces evolving solid-waste frameworks that push converters toward post-consumer fiber integration. California's extended producer responsibility mandates create compliance fragmentation against federal preemption debates affecting national distribution networks.
Netherlands
Pharmaceutical 3PL providers specify printed electronics integration with temperature-logging sensors for high-value biologics lanes. REACH substance restrictions force reformulation of barrier coatings and adhesives to maintain thermal performance. Rotterdam and Amsterdam logistics hubs enable lane-level traceability infrastructure for cross-border pharmaceutical distribution.
India
Cold-chain infrastructure buildout for generic drug exports creates specification upgrade pathways for temperature-validated secondary formats. The CDSCO and DGFT frame pharmaceutical distribution modernization requirements. Maharashtra and Gujarat pharmaceutical manufacturing clusters drive demand for moisture-resistant barrier structures in export logistics.
China
Electronics and cosmetics distribution favors plastic film formats where clarity and tamper-evidence outweigh fiber-based alternatives. GB standards and SAMR regulations govern packaging material safety and recyclability. The Yangtze River Delta manufacturing belt concentrates electronics export volume requiring anti-static and moisture-vapor-barrier specifications.
Secondary Packaging Market Competitive Environment
Concentration sits with integrated pulp-to-board operators and mill-level scale players who control substrate quality from forest to converter. The vendor base stratifies across three tiers: multinational paperboard conglomerates with captive fiber supply, regional corrugated specialists serving proximate industrial clusters, and niche barrier-coating formulators addressing pharmaceutical cold-chain specifications. M&A activity targets ISO 17025 testing capabilities and circular-design consulting competencies, while capacity expansion focuses on moisture-resistant virgin-fiber formulations.
Within the integrated multinational tier, Mondi Group and Smurfit Westrock exemplify divergent geographic anchoring strategies. Mondi leverages Central European pulp-to-board operations to control substrate quality for pharmaceutical and food-grade barrier specifications. Smurfit Westrock anchors North American corrugated supply through mill-level scale and just-in-time plant networks. DS Smith plc occupies a position on the circular-design consulting vector, locking in multinational food accounts with reusable-loop contracts and Forest Stewardship Council-certified structures that satisfy Scope 3 reporting requirements.
| Leading Market Players |
|---|
| Packaging Corporation of America |
| Mondi Group |
| Smurfit Westrock |
| Sonoco Products Company |
| DS Smith plc |
| International Paper Company |
| Graphic Packaging Holding Co. |
| Amcor plc |
| Stora Enso Oyj |
| Others |
Value Chain & Pricing Dynamics
Virgin-fiber substitution for post-consumer recycled stock simultaneously redraws Central European supply geography and compresses converter margin pools as pulp commodity cycles amplify raw material cost volatility. Pharmaceutical shippers in Germany and the Netherlands now reject moisture-critical recycled formulations, forcing specification upgrades that tether pricing power to captive pulp supply.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across certified circular-design contracts, virgin-fiber barrier formulations, and commodity recycled-content grades. Price differentiation separates Forest Stewardship Council-certified structures from standard fiber grades and uncertified alternatives. Pricing pressure stems from post-consumer stock quality failures that push pharmaceutical cold-chain buyers toward premium virgin-fiber content. Food and beverage procurement teams exhibit highest price sensitivity, while pharmaceutical 3PLs absorb premiums for validated thermal performance.
Supply Chain Analysis
Strategic stockpiling of linerboard inventory dominates converter behavior near German and Austrian pulp-to-board clusters, contrasting with just-in-time preferences among North American corrugated networks. Supply concentrates in Germany, Austria, and Poland where integrated operations control substrate quality. Raw material dependencies center on northern bleached softwood kraft pulp, recycled fiber bales, and moisture-resistant coating chemistries. Single-source vulnerability runs through Central European energy corridors. Distribution runs through Rhine-Ruhr logistics hubs serving pharmaceutical 3PL consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary packaging sits at an early-cycle expansion story as temperature-sensitive biologics penetration accelerates specification intensity for validated cold-chain formats.
For Market Incumbents: Compound barrier-coating chemistry capabilities through captive polymer science R&D or targeted acquisition of specialty formulators serving pharmaceutical cold-chain specifications. Defend specification access against buyer consolidation among Rhine-Ruhr 3PLs by embedding ISO 17025 testing laboratories within mill operations. Vertical integration into temperature-logging sensor partnerships locks in lane-level traceability mandates. For New Entrants and Emerging Players: ISO 18606 compostability certification fast-tracks market entry into premium European fresh-food channels where regulatory acceptance determines procurement eligibility. White-space concentrates in Indian pharmaceutical distribution modernization, where CDSCO and DGFT requirements create specification upgrade pathways for temperature-validated formats. Target Maharashtra and Gujarat manufacturing clusters with localized moisture-resistant barrier production. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated converters with captive pulp supply and circular-design consulting competencies. Long-term viability hinges on carbon-accounted structures satisfying Scope 3 reporting requirements across multinational food accounts. Acquisition targets should demonstrate ISO 17025 laboratory infrastructure and Forest Stewardship Council certification pipelines. Watch for inflection when EU packaging waste reduction targets accelerate multi-material laminate redesign mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive northern bleached softwood kraft pulp secures pharmaceutical-grade substrate quality against commodity volatility. |
| ISO 17025 Laboratory Certification | In-house testing capabilities satisfy buyer consolidation among Rhine-Ruhr 3PLs controlling temperature-validated spend. |
| Circular-Design Consulting Service Launch | Reusable-loop contracts embed long-term volume commitments with multinational food accounts under EU Green Deal targets. |
| Printed Electronics Partnership | Temperature-logging sensor integration miniaturizes cold-chain monitoring costs for high-value biologics lanes. |
| Indian Manufacturing Footprint Expansion | Localized production serves CDSCO-framed pharmaceutical distribution modernization in Maharashtra and Gujarat clusters. |
Study Parameters
Cross-validation between primary interviews with corrugated plant managers, pharmaceutical 3PL procurement directors, barrier-coating R&D leads, and retail category buyers anchors the qualitative findings against secondary validation. Bottom-up triangulation draws from customs trade data, EU packaging waste directive filings, SEC 10-K disclosures from integrated paperboard conglomerates, and Forest Stewardship Council certification databases. Top-down modeling incorporates ASTM D642 stack-load testing protocols and REACH substance restriction compliance records.
Sensitivity analysis across material type, end-use compliance burden, and regional regulatory cluster dimensions shapes the analytical framework throughout the forecast period. CAGRs derive from segment-level volume build-ups cross-referenced against pharmaceutical cold-chain infrastructure expansion rates and EU Green Deal implementation timelines. Modeled inputs include pulp commodity price trajectories, 3PL buyer consolidation patterns, and ISO 18606 certification adoption curves.
Decision-makers should treat outputs as directional under sustained EU packaging waste target enforcement and stable Central European energy supply; material deviation would warrant model refresh. Revision becomes warranted when REACH substance restrictions or F-Gas Regulation phase-downs accelerate reformulation timelines beyond current converter R&D capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market