
 FMCG Packaging Market | 2026-2036
FMCG Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
FMCG Packaging Market Intelligence
A shift from single-source to multi-source procurement for specialized materials is broadening supply chain resilience for major consumer brands. Amcor leverages its global manufacturing footprint to supply multinational clients with standardized flexible packaging solutions. Mondi Group differentiates through its integrated paper and plastic production, offering sustainable substrate options. Tetra Pak dominates the aseptic carton segment for beverages, focusing on food preservation and safety.
FMCG packaging comprises primary, secondary, and tertiary materials designed to contain, protect, and present fast-moving consumer goods. These solutions often involve multi-layer films for barrier properties or molded paperboard for structural integrity. Flexible packaging formats lead in volume due to their cost-efficiency and material reduction benefits in food applications. Biodegradable materials represent the fastest-growing segment, driven by consumer preference and corporate sustainability goals in the personal care and beverage industries.
The US Food and Drug Administration (FDA) enforces strict regulations on materials that come into contact with food and beverages. In parallel, frameworks like the European Union's REACH and China's national GB standards impose controls on chemical substances and material recyclability. Navigating divergent international compliance standards while advancing material science innovation is the central challenge for packaging converters.
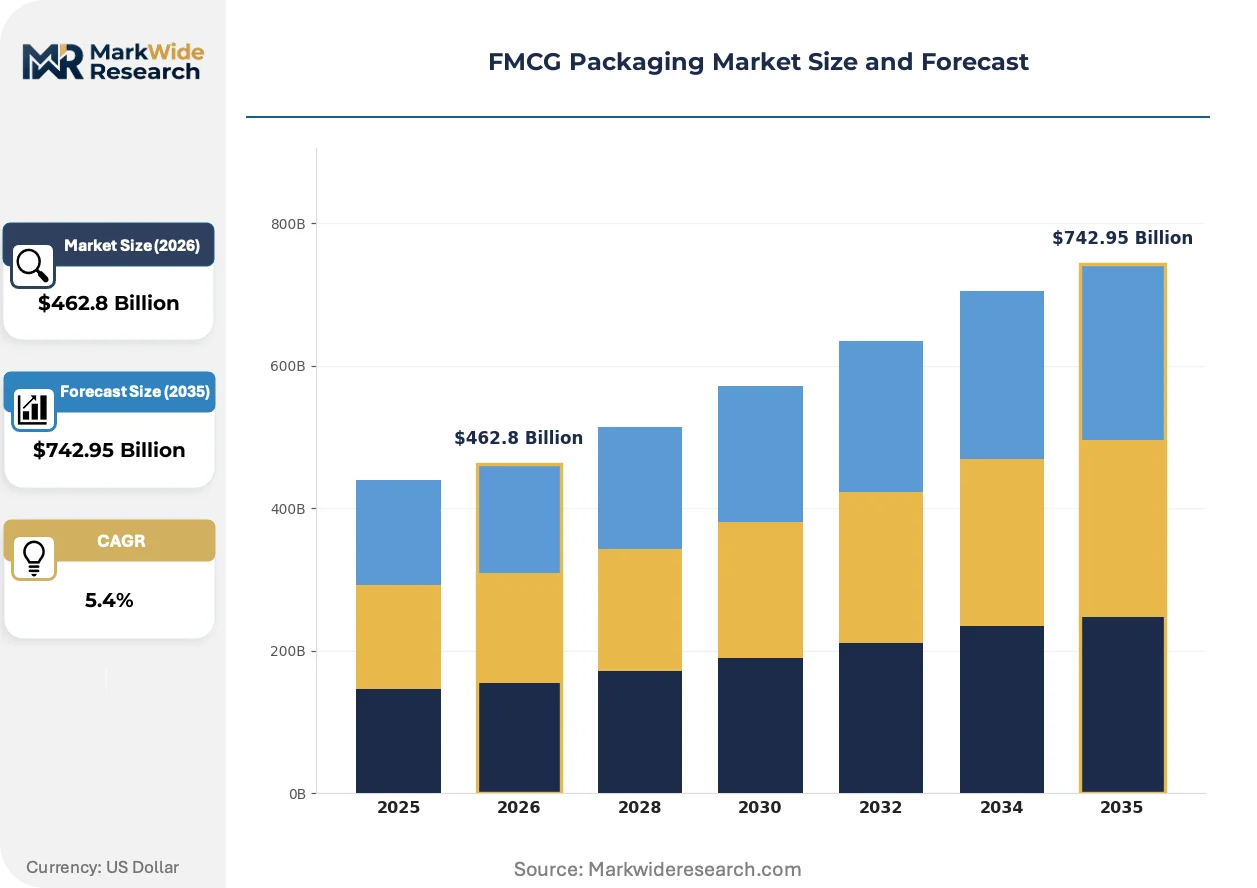
Market Dynamics
The central structural force shaping the FMCG packaging market is the direct conflict between regulatory pressures for circularity, exemplified by the EU's Green Deal, and the stringent technical requirements for material performance in food and personal care applications.
Growth Catalysts
- EU Green Deal:This comprehensive policy framework accelerates the industry-wide transition toward recyclable and biodegradable materials, compelling significant investment in material science innovation across the supply chain.
- Indian Middle-Class Expansion:A growing consumer base with higher disposable income in India is increasing demand concentration for packaged goods, particularly through the expansion of organized retail channels.
- Personal Care Premiumization:Brands in the personal care segment increasingly adopt premium and sustainable container solutions to enhance product appeal, signal quality, and meet evolving consumer expectations.
Market Restraints
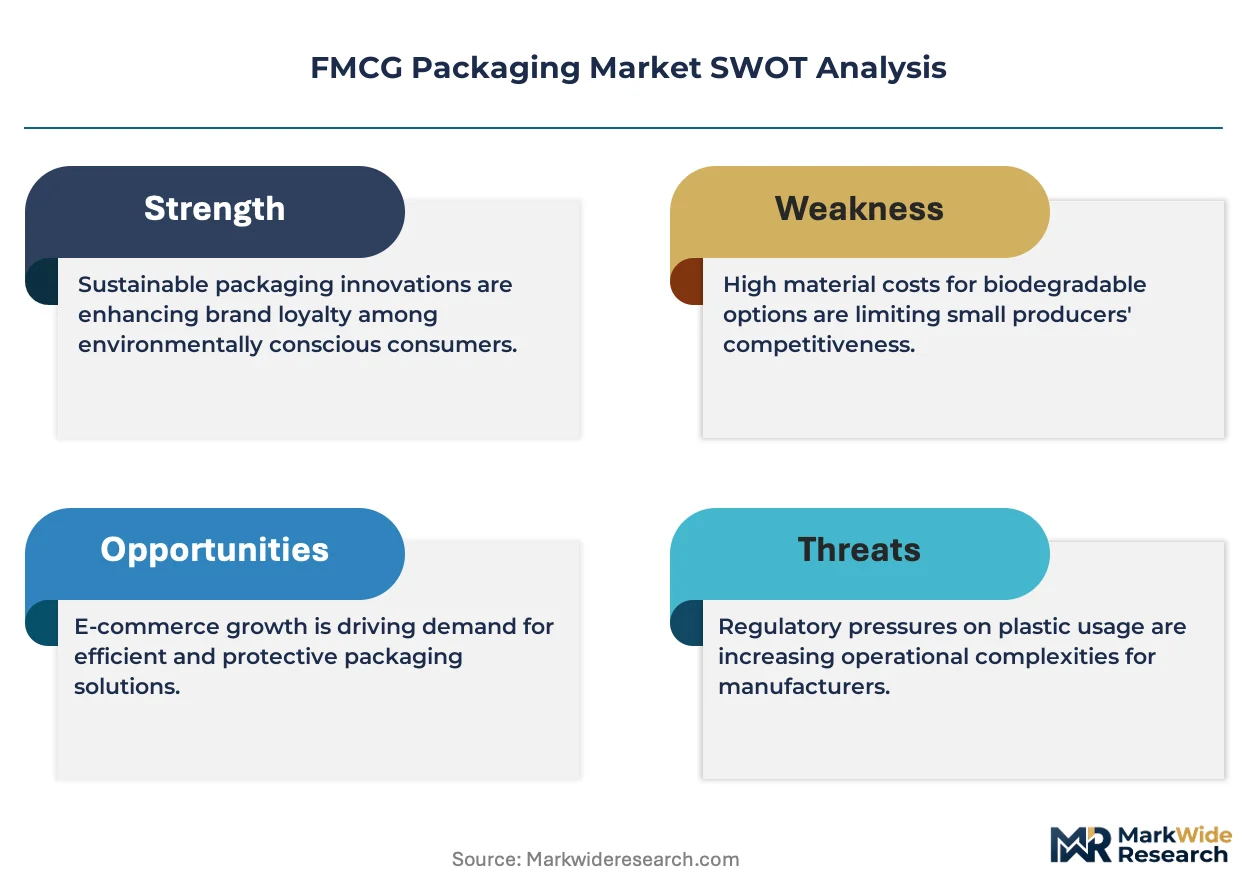
- Input Cost Volatility:Price fluctuations for key raw materials, including polymer resins and paper pulp, create significant margin pressure and forecasting challenges for packaging converters and their FMCG clients.
- Regulatory Fragmentation:Navigating divergent international standards, such as the US FDA's food contact regulations and the EU's REACH framework, complicates material sourcing, product development, and global distribution.
- Biodegradable Material Limitations:Current biodegradable polymers often exhibit inferior barrier properties for oxygen and moisture, which restricts their use in applications requiring extended shelf life for sensitive food products.
Strategic Opportunities
- Active Packaging Integration:Incorporating sensor technologies into packaging to monitor product freshness and supply chain integrity offers a new value proposition for high-value food and pharmaceutical goods.
- Rural Market Penetration:Developing low-cost, small-format packaging can unlock significant volume in underpenetrated rural markets across Southeast Asia and other emerging economies for essential consumer goods.
- Advanced Biopolymer Development:Investment in R&D for next-generation plant-based materials beyond PLA presents an opportunity to create high-performance, compostable flexible films suitable for demanding food applications.
Industry Challenges
- Circular Infrastructure Investment:Establishing effective reverse logistics and sorting infrastructure for post-consumer recycled content presents a significant operational and capital investment challenge for converters and municipalities.
- Compliance and Machinery Upgrades:Meeting stringent recyclability certification timelines under frameworks like the EU's directives necessitates rapid innovation and high capital expenditure on compatible converting equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FMCG Packaging Market |
| Market Size in 2026 | $462.8 Billion |
| Market Size in 2035 | $742.95 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Rigid, Flexible, Blister, Vacuum, Clamshell Material: Plastic, Paperboard, Glass, Metal, Biodegradable End Use Industry: Personal Care, Household Care, Beverages, Confectionery, Tobacco Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Markets, Specialty Stores |
| Companies Covered | Mondi Group, Huhtamaki, Amcor, Smurfit Westrock, Sonoco Products Company, Sealed Air Corporation, International Paper Company, Tetra Pak, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FMCG Packaging Market Strategic Shifts & Innovations
Material science advancements are converging with digital technologies to create packaging that is both sustainable and interactive. This fusion redefines packaging from a simple container to a data-rich brand touchpoint, enhancing consumer engagement and supply chain visibility.
A key product evolution is the development of mono-material flexible films, which use a single polymer type to simplify recycling. Food and personal care brands adopt these films to meet sustainability goals. This transition is electrifying the design process, forcing re-evaluation of barrier properties and shelf-life performance.
The European Union's Green Deal and its Packaging and Packaging Waste Regulation mandate increased recycled content. This forces a shift from multi-layer laminates toward simplified, mono-material structures. The food and beverage sector is most affected, investing in R&D to maintain product protection while ensuring compliance.
Major consumer brands are moving to multi-source procurement for specialized materials like post-consumer resin (PCR). This change disrupts incumbent converters and creates openings for suppliers with certified green credentials. The trend is most visible in North America and Europe, where supply chain resilience is a key corporate priority.
FMCG Packaging Market Segmentation
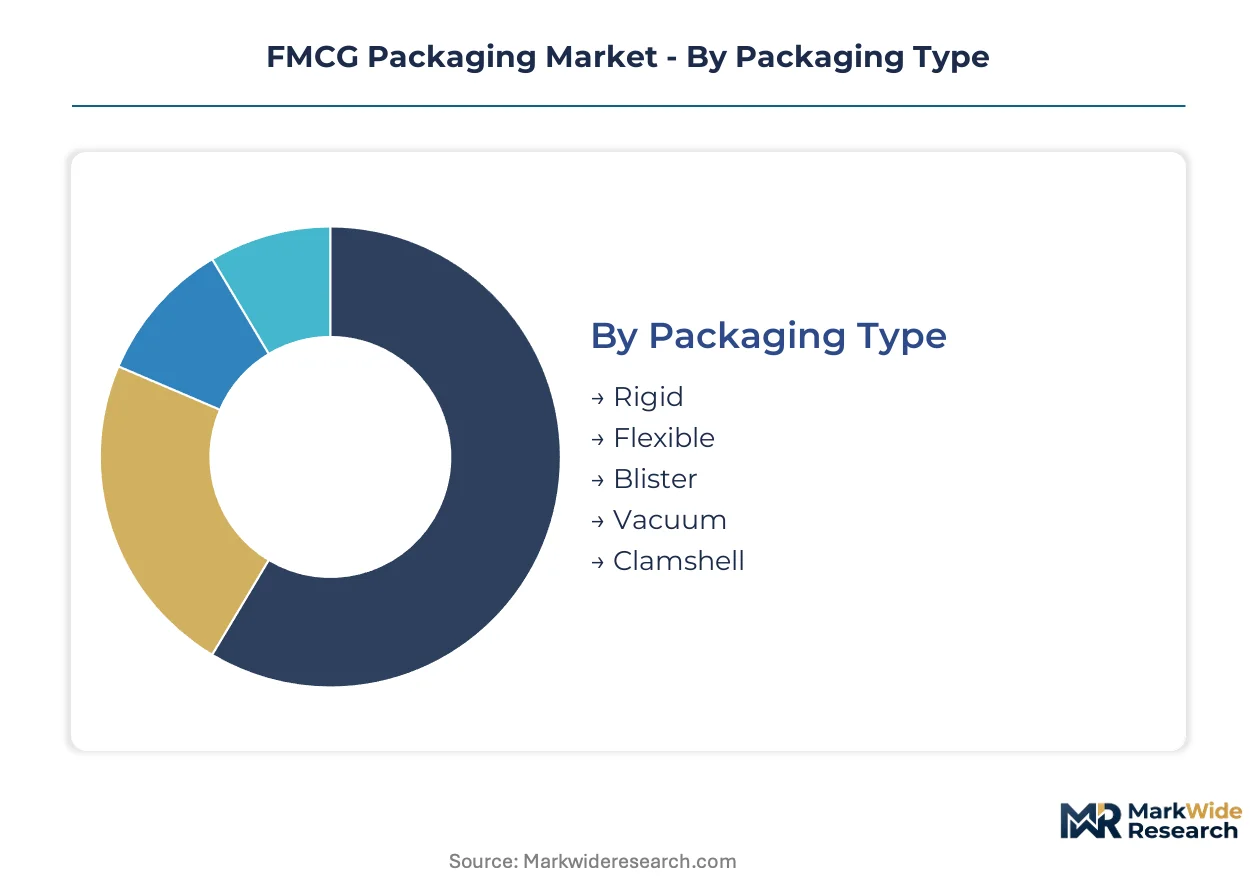
Understanding the FMCG packaging market requires a detailed segmentation across critical dimensions. This granular analysis reveals varied demands and supply dynamics influencing material choices and design innovations. Each segment reflects distinct consumer needs, regulatory compliance pathways, and supply chain configurations within the fast-moving consumer goods sector.
Packaging Type:
The integration of packaging types into automated production lines versus their role as standalone presentation units differentiates this segment.
- Flexible:Multi-layer films or pouches offer material reduction and cost-efficiency. Food applications drive demand due to superior barrier properties and extended shelf life.
- Rigid:Pre-formed containers like bottles, jars, and tubs provide robust protection and premium brand perception. Personal care drives demand for aesthetic and structural integrity.
- Blister:Blister packaging secures individual items within a formed plastic cavity sealed with paperboard or foil. Pharmaceuticals and small consumer goods use this for visibility.
- Vacuum:Vacuum packaging removes air, extending perishable goods' shelf life by inhibiting microbial growth. Meat, cheese, and prepared meals extensively use this method.
- Clamshell:Clamshell packaging involves hinged, pre-formed plastic containers fully enclosing a product. Electronics, fresh produce, and small hardware benefit from its protective display.
Volume placements concentrate in Flexible packaging; the faster expansion belongs to Rigid formats driven by premiumization trends.
Material:
Material choices are defined by specific application requirements, balancing cost, barrier properties, and environmental impact across FMCG.
- Plastic:Versatile polymer-based materials like PET, PP, and PE dominate due to low cost, flexibility, and barrier properties. Food and beverage sectors rely heavily for product protection.
- Biodegradable:Materials such as PLA and PHA offer compostability and reduced environmental footprint, addressing sustainability demands. Personal care brands increasingly adopt these for eco-conscious lines.
- Paperboard:Derived from wood pulp, paperboard offers structural integrity and printability for cartons and sleeves. Confectionery and dry goods use paperboard for aesthetic appeal.
- Glass:Glass containers offer inertness, premium perception, and excellent barrier properties. Beverages and high-end personal care products leverage glass for product integrity.
- Metal:Aluminum and steel form cans, aerosols, and foils, protecting against light, oxygen, and moisture. Beverages, household care, and processed foods are primary users.
Growth is primarily driven by Plastic materials, with Biodegradable options showing significant potential for future expansion.
End Use Industry:
Packaging demand varies significantly across end-use industries, driven by product characteristics, consumer engagement, and regulatory requirements.
- Personal Care:This segment demands packaging combining aesthetic appeal with functional protection for cosmetics and toiletries. Brands prioritize premium and sustainable solutions to enhance product appeal.
- Beverages:Packaging for drinks emphasizes preservation, safety, and convenience, utilizing aseptic cartons, glass, and PET bottles. Tetra Pak dominates aseptic cartons, focusing on food preservation.
- Household Care:Packaging focuses on durability, safe dispensing, and chemical resistance for cleaning products. Functional design and child-resistant features are critical for safety.
- Confectionery:This segment requires attractive, often flexible, packaging to protect delicate items and extend shelf life. Multi-layer films are common for barrier properties.
- Tobacco:Tobacco packaging adheres to strict regulatory guidelines for branding, health warnings, and anti-counterfeiting. Paperboard and flexible films are common with specialized security features.
The largest revenue contributions originate from the Personal Care segment, while Beverages are experiencing rapid expansion.
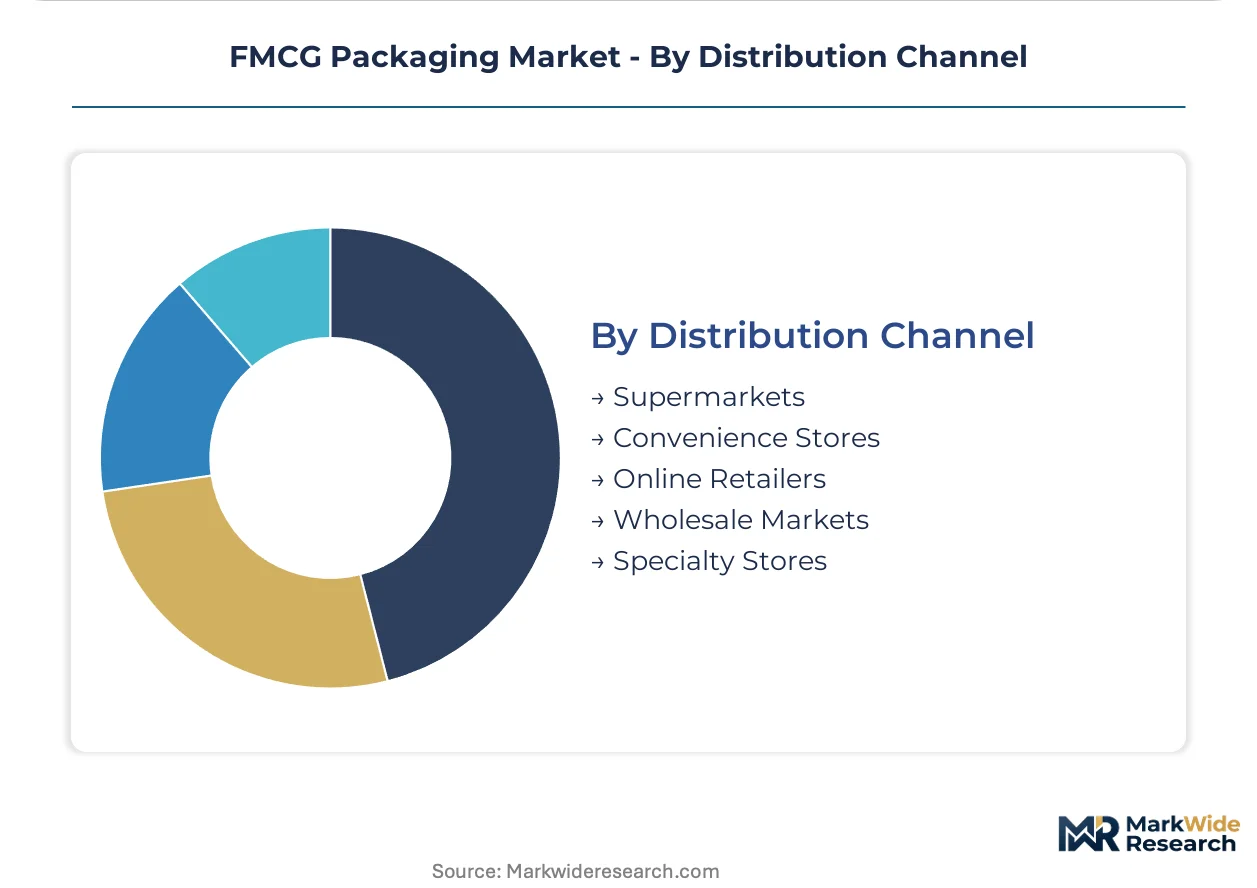
Distribution Channel:
The maturity and reach of each distribution channel significantly influence packaging requirements, from bulk transport to consumer presentation.
- Supermarkets:These large-format retail environments are a primary channel for FMCG, demanding efficient, shelf-ready packaging. High volume sales drive demand for cost-effective, visually appealing designs.
- Online Retailers:E-commerce requires robust packaging to withstand multiple shipping touchpoints, minimizing damage and ensuring product integrity. Sustainable, frustration-free designs are important for online satisfaction.
- Convenience Stores:Convenience stores focus on immediate consumption and impulse purchases, favoring single-serve or small-format packaging. High visibility and quick-grab designs are essential.
- Wholesale Markets:Wholesale markets cater to bulk purchases, necessitating durable, cost-effective, and easy-to-transport packaging. Large-format and industrial solutions are prevalent.
- Specialty Stores:Specialty stores stock premium or artisanal FMCG, driving demand for unique, high-quality, and customized packaging. Brand storytelling and aesthetic appeal are paramount.
The bulk of transactions flow through Supermarkets, with Online Retailers demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer resin production in the United States underpins significant packaging material supply for its vast consumer goods market. This global industry sees diverse regional demands and regulatory frameworks shaping material innovation. From advanced biopolymers to traditional paperboard, each country presents distinct growth opportunities.
United States
Consumer demand for convenient, sustainable packaging solutions drives innovation across the United States. The US FDA enforces strict regulations on food contact materials, influencing product development for safety and compliance. Packaging manufacturers in the Midwest are investing heavily in advanced recycling technologies to meet sustainability targets.
Germany
The European Union's Green Deal policies accelerate the shift towards recyclable and biodegradable materials within Germany's packaging sector. German manufacturers navigate stringent REACH regulations for chemical substances, driving material science innovation. Industrial clusters in the Rhine-Ruhr region focus on developing high-performance, mono-material flexible films for major brands.
India
A rapidly expanding middle class and the growth of organized retail channels fuel substantial demand for packaged goods across India. The Bureau of Indian Standards (BIS) regulates packaging materials, ensuring product quality and safety for consumers. Major packaging converters in the Delhi-NCR region are scaling production to serve this burgeoning domestic market.
China
E-commerce expansion and heightened food safety concerns stimulate significant demand for protective and traceable packaging solutions in China. The country's national GB standards impose strict controls on material composition and recyclability, impacting global supply chains. Manufacturing hubs in the Yangtze River Delta are integrating smart packaging features for enhanced consumer engagement.
Brazil
Urbanization and evolving consumer lifestyles increase demand for single-serve and ready-to-eat food packaging formats across Brazil. ANVISA, the National Health Surveillance Agency, governs food contact materials, ensuring public health protection. Packaging producers in the São Paulo state focus on cost-efficient and sustainable solutions for the domestic market.
FMCG Packaging Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the need to meet evolving sustainability mandates and consumer preferences. The FMCG packaging market exhibits a tiered structure, with large multinational corporations coexisting alongside specialized regional players. Strategic archetypes include integrated material producers, flexible packaging specialists, and innovation-focused biopolymer developers. Geographic expansion and technology licensing represent other significant competitive moves.
Within the integrated material producers tier, Mondi Group, a European multinational, exemplifies diversified material capabilities from paper to flexible plastic, emphasizing sustainable substrate options. Huhtamaki, a Finnish-headquartered specialist, occupies a position focused on global flexible packaging solutions, adapting rapidly to market shifts towards mono-materials and circularity. Amcor, an Australian-American corporation, anchors the global flexible packaging segment, leveraging its extensive manufacturing network to serve multinational clients worldwide with standardized solutions.
| Leading Market Players |
|---|
| Mondi Group |
| Huhtamaki |
| Amcor |
| Smurfit Westrock |
| Sonoco Products Company |
| Sealed Air Corporation |
| International Paper Company |
| Tetra Pak |
| Berry Global |
| Others |
Cost & Logistics Intelligence
European Union's Green Deal mandates for increased recycled content are reshaping material procurement, directly influencing pricing structures for compliant packaging solutions. This regulatory pressure forces significant investment across the supply chain.
Pricing Analysis
Service-level agreements bundled with material supply contracts differentiate pricing for specialized FMCG packaging solutions. The dominant pricing structure remains per-unit transactional, influenced by volume and customization levels. Price differentiation also stems from certification grade, particularly for food contact materials governed by the US FDA. Pricing softness reflects intense competition for high-volume, standardized flexible packaging, while personal care brands exhibit lower price sensitivity for premium, sustainable solutions.
Supply Chain Analysis
Reverse logistics for post-consumer recycled content presents a significant operational bottleneck, impacting material availability and cost. Geographic supply concentration for polymer resins centers on the United States and China, while wood pulp largely sources from Europe. Commodity price volatility for these inputs poses a structural risk across the value chain. Distribution runs through established networks of converters and regional distributors serving diverse end-use industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FMCG packaging market currently operates under supply constraints, particularly for certified mono-materials and advanced biopolymers. Limited investment in new recycling infrastructure props up pricing for post-consumer recycled content.
For Market Incumbents: To counter the threat of regulatory fragmentation and material input volatility, incumbents should deepen vertical integration into polymer resin production. Investing in advanced recycling technologies, especially in Germany and the US, secures access to certified recycled content. This move also enhances control over material quality and reduces reliance on external market fluctuations. Diversifying material portfolios beyond traditional plastics can mitigate long-term supply risks.
For New Entrants and Emerging Players: Specialized packaging distributors represent a viable entry point for novel biopolymer solutions targeting niche segments. Penetration into the personal care segment, particularly with compostable flexible films, offers significant white-space opportunity. Focusing on certifications like those required by the EU Green Deal provides a strong go-to-market angle. Collaborating with local brands in India for sustainable small-format packaging can unlock new volume.
For Investors and Strategic Acquirers: The window for entry favors integrated material science specialists with proven expertise in advanced biopolymer development. Long-term viability over the next decade hinges on intellectual property in high-barrier mono-materials. Acquisition targets should focus on mid-sized converters possessing proprietary technology for active packaging integration. Practitioners should monitor the commercialization pace of next-generation plant-based materials as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Mono-Materials | Increases supply of recyclable films, supporting compliance with EU Green Deal mandates. |
| Advanced Biopolymer R&D Investment | Develops high-performance, compostable alternatives for demanding food and personal care applications. |
| Multi-Source PCR Procurement | Enhances supply chain resilience and meets demand for increased recycled content from major consumer brands. |
| Active Packaging Technology Integration | Adds new value propositions for high-value food and pharmaceutical goods through freshness monitoring. |
| Rural Market Small-Format Development | Unlocks significant volume in underpenetrated markets like Southeast Asia for essential consumer goods. |
Research Approach
Multi-period observation of material consumption patterns and regulatory compliance anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with brand managers, packaging engineers, raw material suppliers, and retail buyers. Secondary validation drew from customs data, corporate sustainability reports, and national regulatory frameworks like the US FDA and EU REACH. Both bottom-up and top-down triangulation ensured data integrity.
An input-output matrix framework modeled market dynamics across the analysis window, projecting volume and value. Segmentation dimensions included packaging type, material, end-use industry, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected forward based on demand drivers. Key forecast inputs included polymer resin pricing trends and recycled content mandates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global trade policies. Forecasts reflect assumptions regarding technological advancements in biopolymers and circular infrastructure development. Practitioners should monitor major legislative changes in Asia and North America for early signals of market redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Global Packaging Market