
 Surface Cleaning Products Market | 2026-2036
Surface Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Cleaning Products Market Analysis
The EPA Safer Choice program is pivoting demand toward biodegradable surfactant systems and reduced volatile organic compound formulations. Procter & Gamble leverages its captive supply of renewable feedstock alcohols to secure cost advantages in plant-derived cleaners. Unilever anchors its position through concentrated refill formats that slash plastic intensity per cleaning cycle. Henkel dominates professional channels with Ecolab-competing sanitation protocols tailored to healthcare and foodservice environments.
Surface cleaning products encompass aqueous and solvent-based formulations engineered to remove soils, microorganisms, and residues from hard surfaces through chemical action, mechanical application, or combined processes. These products typically contain surfactants, chelating agents, pH adjusters, and antimicrobial actives dosed between 0.1% and 5% concentration depending on target pathogen class and contact time requirements. Disinfectants command the largest revenue pool given healthcare-acquired infection prevention mandates and post-pandemic protocol permanence. All-purpose cleaners represent the fastest-expanding consumption segment as consumers consolidate SKUs and retailers reduce shelf-space complexity. Glass cleaners face margin compression amid private-label substitution and dilutable concentrate alternatives.
The EPA regulates antimicrobial claims under FIFRA, requiring substantiated kill claims and registered label language before interstate commerce. California's Department of Toxic Substances Control enforces Cleaning Product Right to Know Act disclosure thresholds that exceed federal requirements and de facto shape national formulation standards. OSHA workplace exposure limits for quaternary ammonium compounds and chlorine-based actives further constrain industrial application concentrations. Stakeholders must monitor pending state-level per- and polyfluoroalkyl substance restrictions that could force surfactant system redesigns across multiple product lines.
Market Dynamics
The Surface Cleaning Products Market pivots on chemical disclosure mandates that force reformulation investments while compressing product development cycles for legacy portfolios.
Growth Catalysts
- Hospital-grade disinfectant protocols:Healthcare-acquired infection prevention mandates in the United States sustain elevated procurement of sporicidal and virucidal formulations across acute care networks.
- California's Cleaning Product Right to Know Act:Disclosure thresholds exceeding federal EPA requirements create de facto national standards that accelerate biodegradable surfactant adoption.
- Sun Belt commercial real estate expansion:Metropolitan growth corridors in Texas, Florida, and Arizona concentrate demand for professional sanitation services and bulk institutional purchasing.
Market Restraints
- Palm kernel and coconut fatty alcohol volatility:Plant-derived surfactant feedstocks face agricultural commodity price swings that compress margins on eco-positioned product lines.
- Quaternary ammonium compound workplace limits:OSHA exposure thresholds constrain maximum application concentrations in industrial cleaning environments, capping efficacy claims.
- Private-label glass cleaner substitution:Concentrate and refill formats displace conventional ready-to-use SKUs at mass retail, eroding branded pricing power.
Strategic Opportunities
- Per- and polyfluoroalkyl substance restrictions:Pending state-level PFAS bans in Maine, Washington, and Minnesota force surfactant system redesigns that reward early reformulation investment.
- Concentrated refill economics:Unit-dose and dilutable formats slash plastic intensity per cleaning cycle while capturing margin from packaging cost reduction.
- Foodservice sanitation protocols:Ecolab-competing professional channels offer recurring revenue streams through protocol-based service contracts beyond product sales.
Industry Challenges
- Dual-registration FIFRA complexity:EPA antimicrobial claim substantiation requires parallel state-level approvals that extend commercialization timelines by 18-24 months.
- Surfactant system requalification:Reformulation to meet Safer Choice biodegradability standards demands new stability and compatibility testing across hard surface substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Cleaning Products Market |
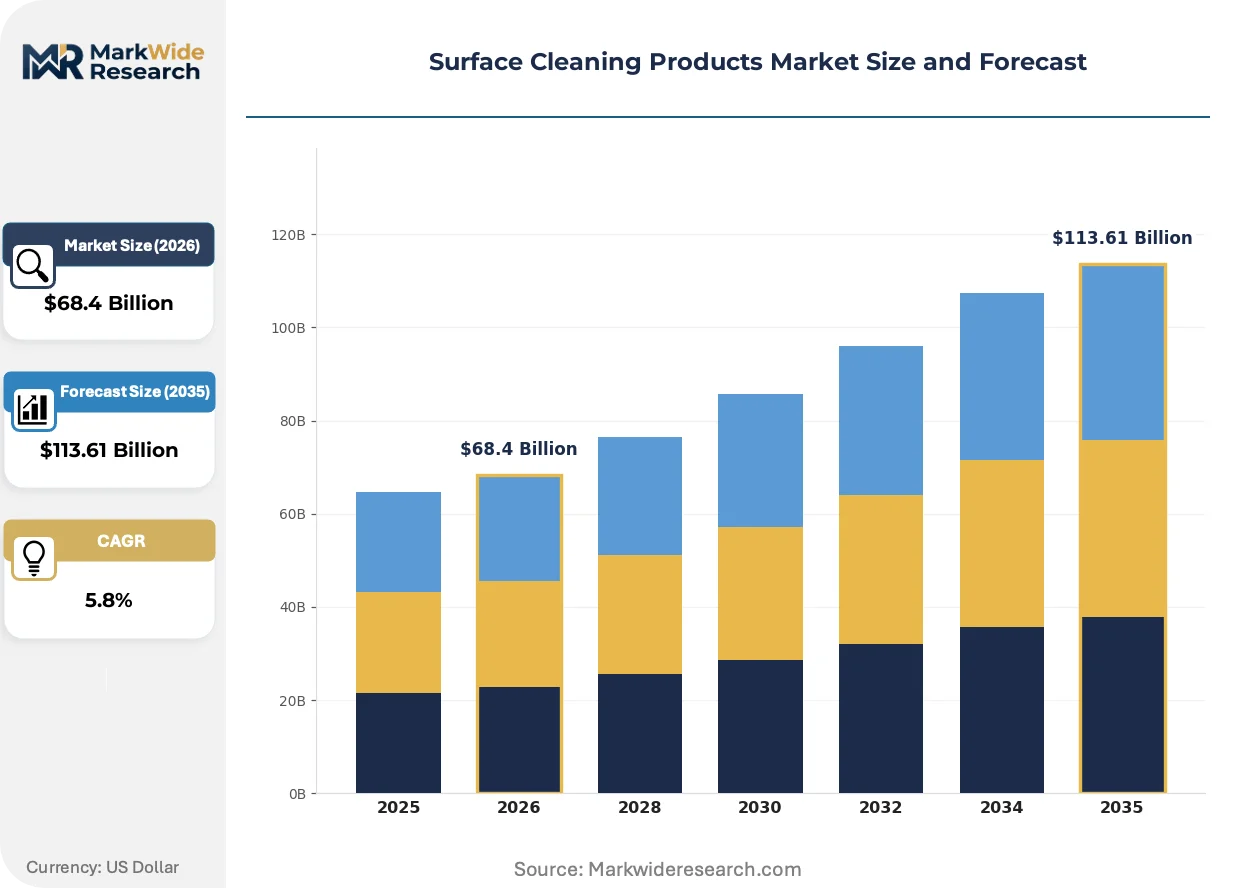
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, All-Purpose Cleaners, Glass Cleaners, Floor Cleaners Application: Residential, Commercial, Industrial, Healthcare Packaging Type: Bottles, Canisters, Aerosols, Refills End User: Households, Offices, Manufacturing Plants, Educational Institutions |
| Companies Covered | Procter & Gamble, Unilever, Reckitt Benckiser Group, Henkel, The Clorox Company, Colgate-Palmolive, SC Johnson, Ecolab, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Cleaning Products Market Emerging Trajectories
Formulation chemistry and delivery systems are converging to reduce environmental intensity while maintaining pathogen kill efficacy against tightening regulatory benchmarks.
Electrolyzed water generation systems are expanding into commercial foodservice and hospitality sectors. On-site hypochlorous acid production eliminates transportation of bulk chlorine concentrates while satisfying EPA-registered sanitizer claims. This decentralized generation model is compressing traditional chemical distribution margins in high-volume institutional accounts.
REACH restrictions on persistent organic pollutants are forcing European formulators to abandon certain quaternary ammonium precursors. The industrial consequence is accelerated adoption of lactic acid and citric acid-based alternatives in hard surface disinfectants. Professional cleaning contractors in Germany and France are responding by retraining application protocols around shorter contact times and higher frequency dosing.
Facility managers are consolidating SKU portfolios through multi-surface cleaner adoption. The all-purpose segment displaces specialized glass, bathroom, and kitchen formulations in procurement contracts. This behavioral shift is most visible in United States commercial real estate management, where standardization reduces inventory complexity and training burden across distributed property portfolios.
Surface Cleaning Products Market Segmentation
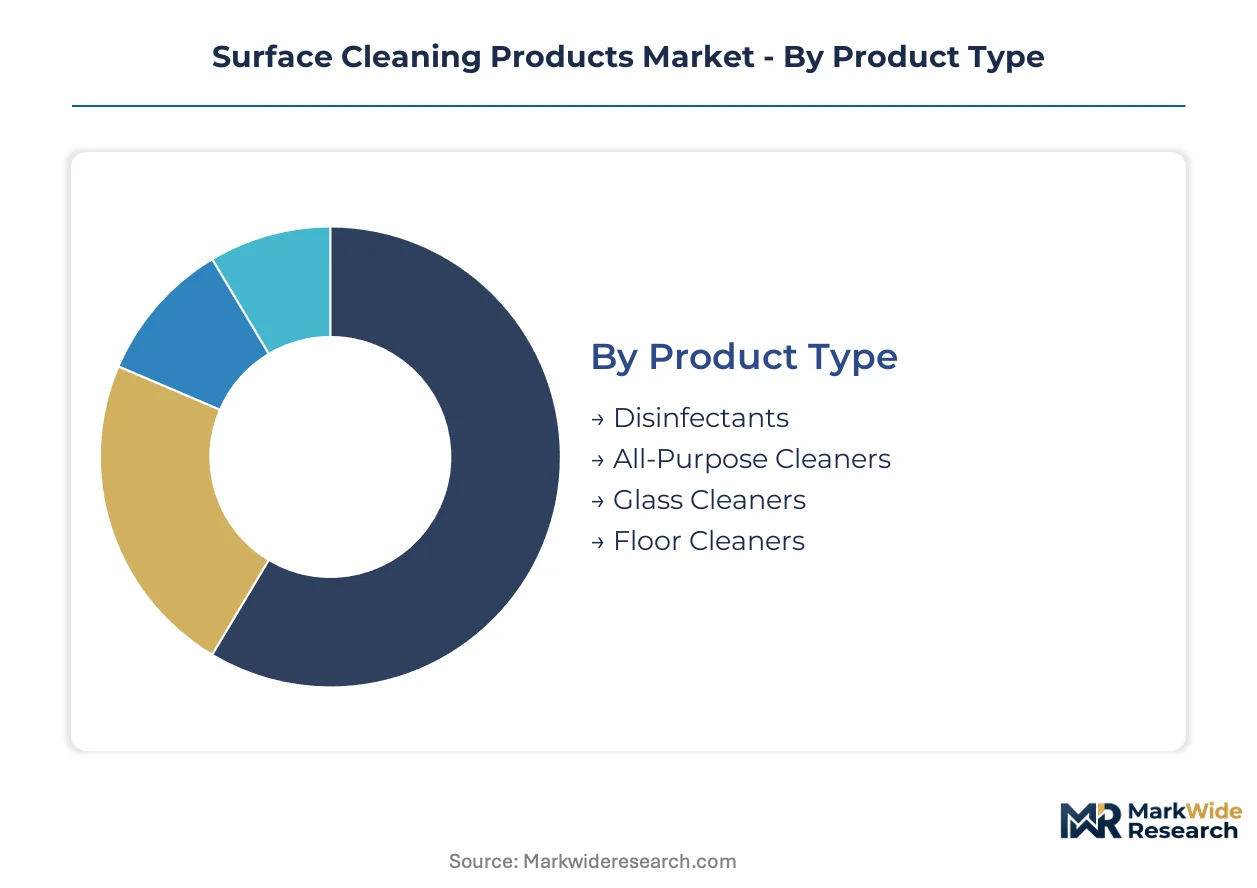
Surface cleaning products fragment across formulation chemistry, application environment, and procurement scale. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Buyers prioritize kill-claim efficacy against contact time and surface compatibility when selecting formulations.
- Disinfectants:These formulations combine quaternary ammonium compounds, sodium hypochlorite, or accelerated hydrogen peroxide at concentrations calibrated to EPA-registered kill claims against specific pathogen classes. Healthcare networks in Texas, Florida, and Arizona sustain procurement of hospital-grade sporicidal variants for infection prevention protocols.
- All-Purpose Cleaners:Surfactant-based aqueous systems engineered for multi-surface compatibility with pH buffers between 6.5 and 9.0. Residential consolidation of SKU portfolios and commercial real estate standardization across Sun Belt metropolitan areas concentrate demand for concentrated refill formats that reduce plastic intensity per cleaning cycle.
- Glass Cleaners:Ammonia or alcohol-based formulations with low-residue drying agents for optical clarity.
- Floor Cleaners:pH-optimized surfactant systems for sealed and unsealed hard surface flooring substrates.
Disinfectants lead on scale; all-purpose cleaners lead on momentum.
Application:
Regulatory stringency varies sharply across settings, with healthcare and foodservice facing the most demanding compliance thresholds.
- Residential:Mass-market consumption concentrated in spray-trigger bottles and dilutable concentrates. California's Cleaning Product Right to Know Act disclosure mandates exceed federal EPA requirements and reshape national formulation standards for surfactant biodegradability.
- Commercial:Professional cleaning contractors and facility management firms procure in bulk formats with protocol-based service contracts. Metropolitan growth corridors in Texas, Florida, and Arizona drive institutional purchasing for office and retail sanitation.
- Industrial:Heavy-duty degreasing and solvent-based formulations for manufacturing environments.
- Healthcare:EPA FIFRA-registered sporicidal and virucidal disinfectants with substantiated kill claims against healthcare-acquired infection pathogens. OSHA workplace exposure limits for quaternary ammonium compounds constrain maximum application concentrations in acute care settings.
Healthcare commands premium pricing; commercial channels offer recurring revenue expansion.
Packaging Type:
Packaging selection reflects a trade-off between convenience, unit economics, and environmental positioning.
- Bottles:PET and HDPE containers dominate mass retail with trigger-spray or flip-cap dispensing. Private-label substitution and retailer shelf-space reduction compress margins on conventional ready-to-use formats.
- Canisters:Pre-moistened wipe substrates for portable disinfection in healthcare and foodservice.
- Aerosols:Pressurized solvent and disinfectant delivery for vertical surface coverage and HVAC duct applications.
- Refills:Concentrated or unit-dose formats that slash packaging cost per cleaning cycle. Unilever anchors market position through concentrated refill economics that capture margin from plastic intensity reduction.
Bottles retain volume leadership; refills gain share fastest.
End User:
Procurement sophistication ranges from price-sensitive household purchasing to protocol-driven institutional contracts.
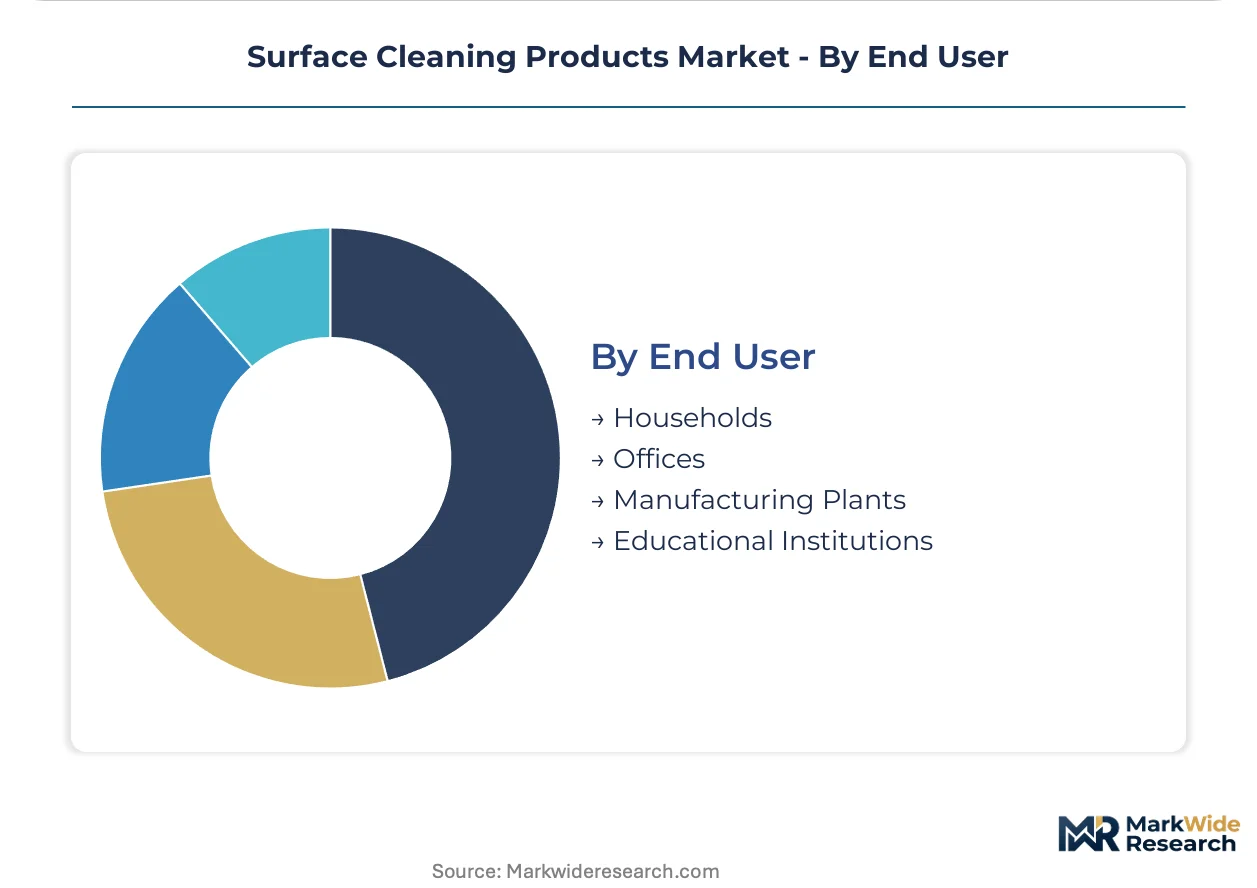
- Households:Consumer-directed purchasing through mass retail and e-commerce channels with SKU consolidation toward multi-surface formulations.
- Offices:Facility management procurement with standardized sanitation protocols across distributed property portfolios.
- Manufacturing Plants:Industrial hygiene compliance with OSHA exposure limits for cleaning chemical actives.
- Educational Institutions:K-12 and university procurement balancing budget constraints with student health protocols. Henkel dominates professional channels with Ecolab-competing sanitation systems tailored to institutional environments.
Offices concentrate contract value; educational institutions offer volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The surface cleaning products industry traces its modern scale to post-war American chemical manufacturing, where petrochemical surfactant production first achieved household penetration before spreading to European and Asian industrial centers.
United States
Sun Belt metropolitan corridors in Texas, Florida, and Arizona concentrate commercial real estate expansion and institutional procurement. EPA's Safer Choice program and California's Cleaning Product Right to Know Act exceed federal disclosure thresholds and reshape national formulation standards. Dallas-Fort Worth and Phoenix anchor healthcare network procurement of hospital-grade disinfectants.
Germany
REACH restrictions on persistent organic pollutants force abandonment of specific quaternary ammonium precursors. Industrial formulators accelerate lactic acid and citric acid-based alternatives. The Rhine-Ruhr manufacturing belt hosts professional cleaning contractors retraining protocols around shorter contact times.
China
Domestic chemical production scales surfactant feedstock supply for Asia-Pacific regional markets. GB standards and MIIT industrial policies govern antimicrobial claim substantiation. Yangtze River Delta chemical clusters supply both captive domestic demand and export manufacturing.
Japan
METI energy efficiency directives and compact living spaces concentrate demand for concentrated refill formats. Kao Corporation exemplifies domestic leadership in unit-dose packaging innovation. Tokyo-Osaka metropolitan corridors standardize multi-surface cleaner procurement across facility management.
United Kingdom
Post-Brexit regulatory divergence from REACH creates parallel compliance pathways for UK-specific formulations. London commercial property management consolidates SKU portfolios through all-purpose cleaner adoption. Southeast England distribution hubs service cross-channel professional cleaning supply.
Surface Cleaning Products Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance investment. The vendor base concentrates among diversified consumer goods conglomerates and professional sanitation specialists. Three archetypes dominate: petrochemical-integrated multinationals with captive surfactant supply, brand-anchored FMCG groups with retail shelf-space leverage, and protocol-driven professional service contractors. Competitive moves center on concentrated refill format expansion and state-level PFAS restriction anticipation.
Among diversified consumer goods conglomerates, Procter & Gamble, Unilever, and Henkel occupy positions across mass-market and professional channels. Procter & Gamble represents petrochemical-integrated scale with renewable feedstock alcohol advantages. Unilever exemplifies concentrated refill economics and plastic intensity reduction positioning. Henkel anchors professional channel presence with Ecolab-competing sanitation protocol offerings.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Reckitt Benckiser Group |
| Henkel |
| The Clorox Company |
| Colgate-Palmolive |
| SC Johnson |
| Ecolab |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Captive supply of renewable feedstock alcohols anchors both cost position and pricing power for integrated multinationals, while outsourced surfactant sourcing exposes mid-tier formulators to agricultural commodity volatility that compresses margin flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA Safer Choice-certified formulations from conventional actives and private-label substitutes. Price differentiation hinges on certification tier and volume procurement scale, with institutional healthcare contracts commanding premiums over mass retail. Cost compression in glass cleaner segments intensifies because concentrate and refill formats displace ready-to-use SKUs. Private-label buyers in residential channels exhibit highest price sensitivity; healthcare procurement committees prioritize kill-claim efficacy over unit cost.
Supply Chain Analysis
EPA FIFRA registration and state-level antimicrobial claim approvals gate supplier qualification, extending commercialization timelines and concentrating compliant manufacturing among established registrants. Feedstock supply draws from Malaysia and Indonesia for palm kernel fatty alcohols, the United States for corn-derived ethanol, and Germany for specialized surfactant precursors. Single-source vulnerability concentrates in Southeast Asian oleochemical processing exposed to El Niño agricultural disruption. Distribution runs through chemical distribution networks for institutional accounts and mass retail consolidation for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in surface cleaning products rests on concentrated refill economics that slash packaging cost per cleaning cycle while commanding premium positioning against dilutable alternatives.
For Market Incumbents: Anticipate pending PFAS restrictions in Maine, Washington, and Minnesota by accelerating surfactant system requalification investments ahead of compliance deadlines. Secure backward integration into renewable alcohol feedstocks to defend cost position against agricultural commodity volatility threatening plant-derived product lines. Channel control through protocol-based service contracts in foodservice and healthcare insulates recurring revenue from private-label substitution. For New Entrants and Emerging Players: California's Cleaning Product Right to Know Act opens a window for biodegradable surfactant specialists to capture share from legacy formulators facing reformulation cost burdens. Target commercial real estate management in Texas, Florida, and Arizona Sun Belt corridors where facility standardization concentrates procurement of multi-surface formulations. A direct-to-institutional sales model bypasses retail shelf-space barriers that entrench incumbent FMCG groups. For Investors and Strategic Acquirers: Roll-up economics work for regional professional sanitation contractors because fragmented local service markets lack scale-efficient protocol standardization. Long-term viability centers on recurring revenue streams from service contracts rather than transactional chemical sales. Watch for state-level PFAS enforcement acceleration as inflection indicator for reformulation investment cycles and acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Surfactant System Reformulation | California DTSC disclosure mandates force biodegradable feedstock adoption ahead of federal requirements. |
| Concentrated Refill Format Expansion | Unilever's unit-dose economics demonstrate margin capture from plastic intensity reduction per cleaning cycle. |
| Professional Channel Protocol Contracts | Henkel's Ecolab-competing sanitation systems lock recurring revenue through institutional service agreements. |
| Electrolyzed Water Generation Deployment | On-site hypochlorous acid production eliminates bulk chlorine transportation costs in high-volume foodservice accounts. |
| Healthcare-Grade Disinfectant Registration | EPA FIFRA sporicidal claims command premium pricing in Texas and Arizona acute care network procurement. |
Methodological Framework
Direct dialogue with formulation chemists, professional cleaning contractors, hospital procurement managers, and retail category buyers combined with secondary validation from EPA registration databases, California DTSC disclosure filings, and chemical trade association reports. Bottom-up demand modeling triangulates against top-down market sizing across surfactant feedstock supply analysis.
Segmented volume and value estimates across the projection horizon incorporate formulation chemistry tiers, application environments from residential to healthcare, packaging format economics, and end-user procurement sophistication. CAGRs derive from installed base penetration modeling and replacement cycle analysis for disinfectant versus all-purpose cleaner adoption. Key inputs include Sun Belt commercial real estate construction permits and hospital infection prevention protocol permanence assumptions.
Revisions become necessary when state-level PFAS enforcement timelines accelerate, agricultural commodity price volatility disrupts plant-derived surfactant feedstock economics, or electrolyzed water generation technology achieves cost parity with bulk chemical distribution. A model refresh is warranted upon material change in EPA Safer Choice program expansion or California disclosure threshold tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market