
 Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market | 2026-2036
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market Insights
Enzyme stabilization technology is fragmenting into cold-adapted and thermostable strain variants, forcing manufacturers to reconfigure formulation architectures around temperature-specific performance profiles. Ecolab leverages its institutional cleaning distribution network to sustain premium positioning across North American hospitality chains. Novonesis anchors microbial supply chains through in-house fermentation capacity, while Diversey competes on integrated dispensing system bundling that locks in recurring chemical volumes.
Bio-enzymatic odor control chemicals for restrooms and waste areas comprise non-pathogenic bacterial cultures—typically Bacillus subtilis, Pseudomonas putida, and selected lipase-producing strains—suspended in aqueous carriers with pH buffers between 6.5 and 8.5, designed to metabolize organic substrates including urea, fecal matter, and grease deposits into odorless carbon dioxide and water. Liquid concentrates dominate current procurement volumes due to dilution flexibility and lower freight costs, though gel-based chemicals are capturing share in transportation hub applications where extended surface contact time proves critical against intermittent cleaning schedules.
The EPA's Safer Choice standard and the EU REACH framework restrict volatile organic compound thresholds and mandate aquatic toxicity testing, directly shaping permissible surfactant packages and strain registration requirements for market access. Germany's Federal Institute for Risk Assessment and Japan's Ministry of Economy, Trade and Industry enforce additional biocidal claims substantiation that extends product development timelines. Stakeholders must monitor emerging strain patent filings and regional green procurement mandates to anticipate where formulation leadership will consolidate next.
Market Dynamics
Enzyme stabilization technology is fragmenting into temperature-specific strain variants, forcing manufacturers to reconfigure formulation architectures around cold-adapted and thermostable performance profiles rather than universal solutions.
Growth Catalysts
- REACH compliance deadlines:The European Union's phased restrictions on quaternary ammonium compounds are accelerating municipal procurement of biodegradable alternatives across German public sanitation infrastructure.
- Tropical climate amplification:Southeast Asian commercial building sectors face intensified odor control requirements in high-traffic restroom facilities, concentrating demand for extended-contact gel formulations.
- Cold-adapted strain development:Advances in psychrophilic Bacillus cultivation are opening deployment in unheated waste processing facilities previously inaccessible to mesophilic formulations.
Market Restraints
- Fermentation feedstock volatility:Molasses and corn steep liquor prices fluctuate with agricultural commodity cycles, compressing margins for in-house microbial production operations.
- Strain registration bottlenecks:Japan's METI and Germany's Federal Institute for Risk Assessment enforce extended biocidal claims substantiation timelines that delay product commercialization by 18-24 months.
- Quaternary ammonium residual efficacy:Legacy disinfectants retain institutional preference in healthcare settings where immediate kill claims override long-term odor prevention benefits.
Strategic Opportunities
- Brazilian municipal expansion:Sanitation agencies in São Paulo and Rio de Janeiro are tendering enzyme-based formulations for public restroom networks serving World Cup and Olympic legacy infrastructure.
- Transportation hub gel penetration:Airports and rail terminals with intermittent cleaning schedules present untapped demand for surface-adherent formulations with 12-hour residual activity.
- EPA Safer Choice certification:Federal procurement preference for labeled products creates a wedge into US government facility contracts previously captured by conventional chemical suppliers.
Industry Challenges
- Strain viability logistics:Temperature excursions during last-mile distribution to tropical climates degrade colony-forming unit counts below labeled guarantees, triggering performance disputes.
- Cross-jurisdiction formulation drift:Divergent strain approval lists between EPA, REACH, and METI registries force maintenance of multiple SKUs for functionally identical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market |
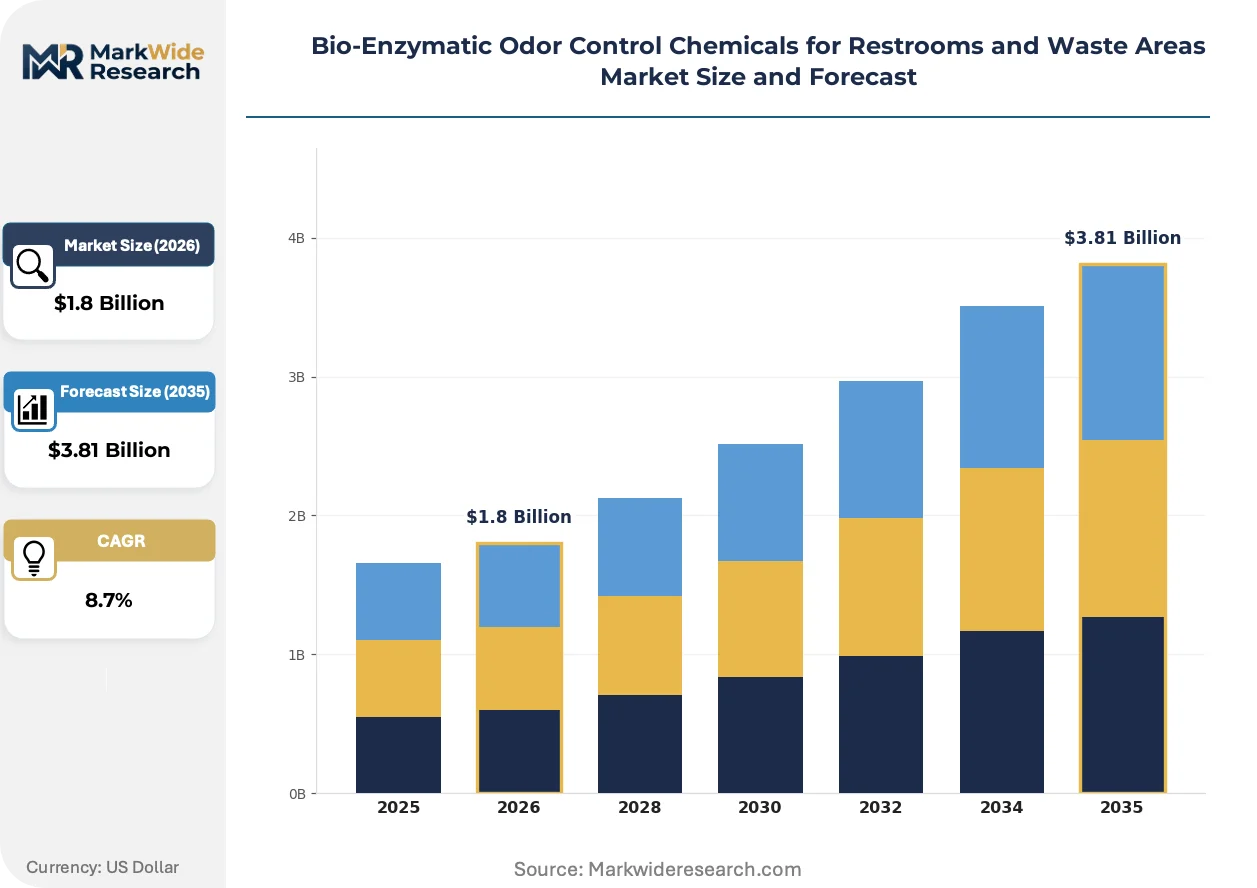
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Concentrates, Powdered Formulations, Gel-Based Chemicals, Spray Solutions Application: Public Restrooms, Waste Management Facilities, Commercial Buildings, Transportation Hubs End User Industry: Hospitality, Municipal Services, Food Processing Plants, Transportation Companies Deployment Method: Manual Dispensing, Automatic Sprayers, Fogging Equipment, Scheduled Release Systems |
| Companies Covered | Ecolab, Diversey, Zep, Spartan Chemical Company, Betco, OdoBan, Kemira, Novonesis, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market Trends and Innovations
Formulation science is converging with precision dispensing hardware and IoT-enabled consumption tracking, compressing the traditional separation between chemical supply and equipment vendors into bundled service relationships.
Cold-adapted psychrophilic strains derived from Antarctic soil samples are collapsing the temperature floor for bio-enzymatic efficacy from 15°C to 4°C. Cold-storage waste facilities in northern Japan and Canada are adopting these formulations for year-round odor control previously requiring chemical alternation. The technology is collapsing the seasonal demand cyclicality that historically structured procurement calendars.
REACH Annex XIV authorization requirements for nonylphenol ethoxylates are forcing surfactant package reformulation across European-destined products. Manufacturers are substituting biosourced alkyl polyglucosides and rhamnolipids at 15-30% cost premiums. German industrial laundries and Dutch municipal cleaning cooperatives are absorbing these premiums to maintain green procurement certifications.
Facility managers are consolidating vendor relationships around integrated dispensing system contracts that bundle hardware, chemicals, and consumption analytics. Singapore's Changi Airport and Dubai International have tendered multi-year odor control service agreements specifying outcome-based performance metrics rather than volume-based supply. Southeast Asian hospitality chains are replicating this model to reduce procurement administrative burden.
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market Segmentation
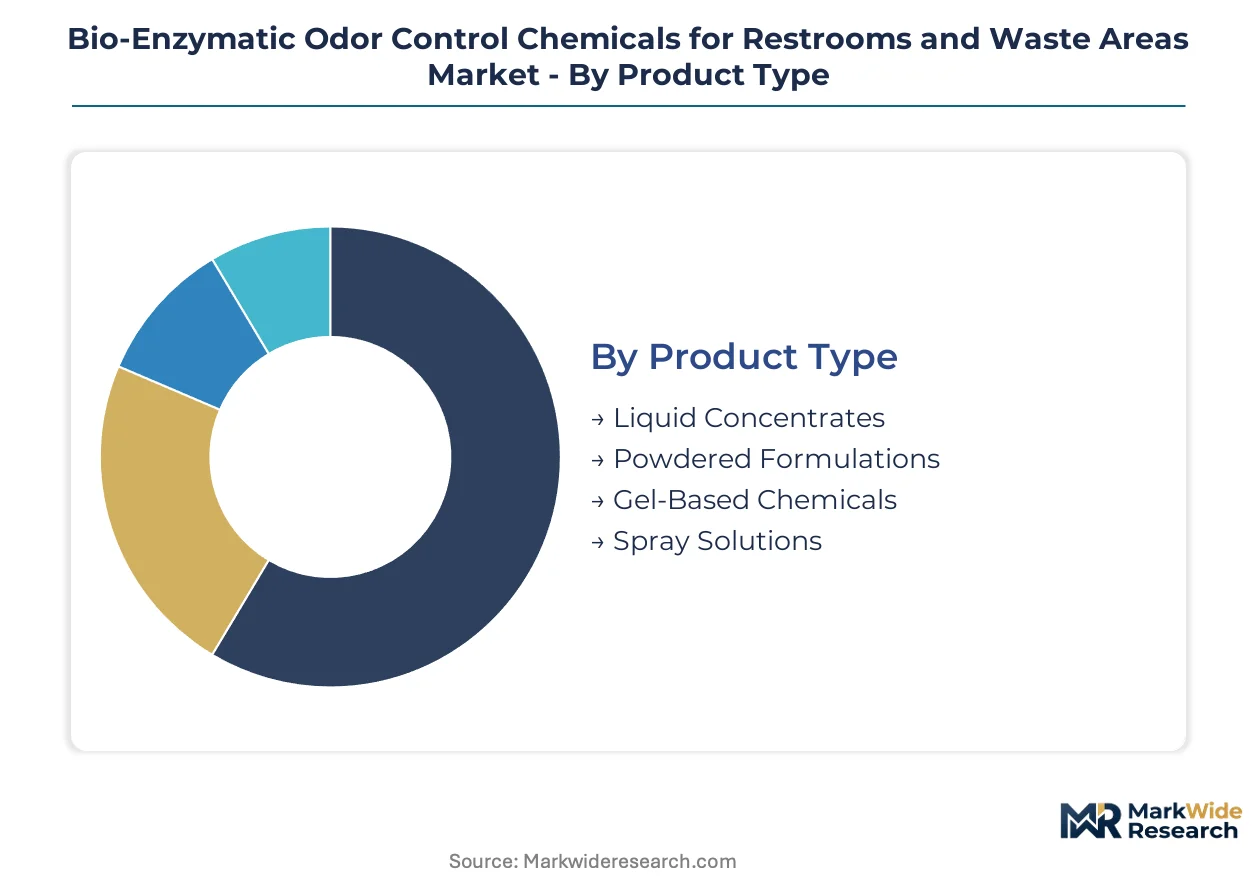
Segmentation in bio-enzymatic odor control reveals how formulation chemistry, application environment, and deployment infrastructure intersect to determine procurement patterns. Buyers optimize across temperature stability, contact time requirements, and labor automation rather than selecting on unit cost alone.
Product Type:
Mature liquid concentrates dominate procurement volumes while gel-based formats emerge as the fastest-climbing alternative for specialized deployment scenarios.
- Liquid Concentrates:Aqueous suspensions of Bacillus subtilis and Pseudomonas putida with pH buffers between 6.5 and 8.5, offering dilution flexibility and lower freight costs per active unit. Municipal services agencies across Germany and Brazil specify these for high-volume public restroom networks where daily dilution protocols are standardized.
- Gel-Based Chemicals:Thixotropic formulations with extended surface adhesion designed for 12-hour residual activity against intermittent cleaning schedules. Airports in Southeast Asia and rail terminals in Japan are tendering these for transportation hub applications where contact time trumps dilution economy.
- Powdered Formulations:Lyophilized bacterial cultures with extended shelf stability for remote deployment scenarios lacking cold-chain infrastructure.
- Spray Solutions:Ready-to-use aqueous suspensions for immediate-response odor incidents in facilities without trained dilution protocols.
Liquid concentrates handle the majority of throughput; gel-based chemicals are expanding most quickly on share as transportation infrastructure procurement accelerates.
Application:
Application segmentation tracks climate exposure and traffic density as primary determinants of formulation specification and reapplication frequency.
- Public Restrooms:High-frequency facilities in tropical climates drive demand for thermostable strain variants. Southeast Asian commercial building sectors concentrate procurement here, with tropical humidity amplifying odor generation rates beyond temperate-zone benchmarks.
- Transportation Hubs:Intermittent cleaning schedules and 24-hour operation create specification for extended-contact formulations. Singapore's Changi Airport and Dubai International have tendered multi-year service agreements specifying outcome-based performance metrics rather than chemical volume.
- Waste Management Facilities:Unheated processing environments in northern Japan and Canada are adopting cold-adapted psychrophilic strains for year-round operation.
- Commercial Buildings:Standardized janitorial protocols favor liquid concentrate compatibility with existing dilution equipment.
Public restrooms generate the highest absolute volume; transportation hubs are gaining share fastest as facility managers consolidate around integrated dispensing contracts.
End User Industry:
End user segmentation reflects divergent regulatory exposure and performance verification requirements across institutional procurement frameworks.
- Municipal Services:Public agencies in São Paulo and Rio de Janeiro are tendering enzyme-based formulations for legacy infrastructure from World Cup and Olympic development cycles. EPA Safer Choice certification creates federal procurement preference in US government facilities.
- Hospitality:North American hotel chains leverage institutional cleaning distribution networks for premium positioning, with Ecolab sustaining contracted supply relationships across major brands.
- Food Processing Plants:Lipase-producing strain formulations target grease deposit metabolism in sanitation-critical environments.
- Transportation Companies:Rail and airport operators specify surface-adherent chemistries compatible with automated dispensing hardware and IoT-enabled consumption tracking.
Municipal services anchor procurement volume; hospitality is climbing fastest as green certification requirements harden across brand standards.
Deployment Method:
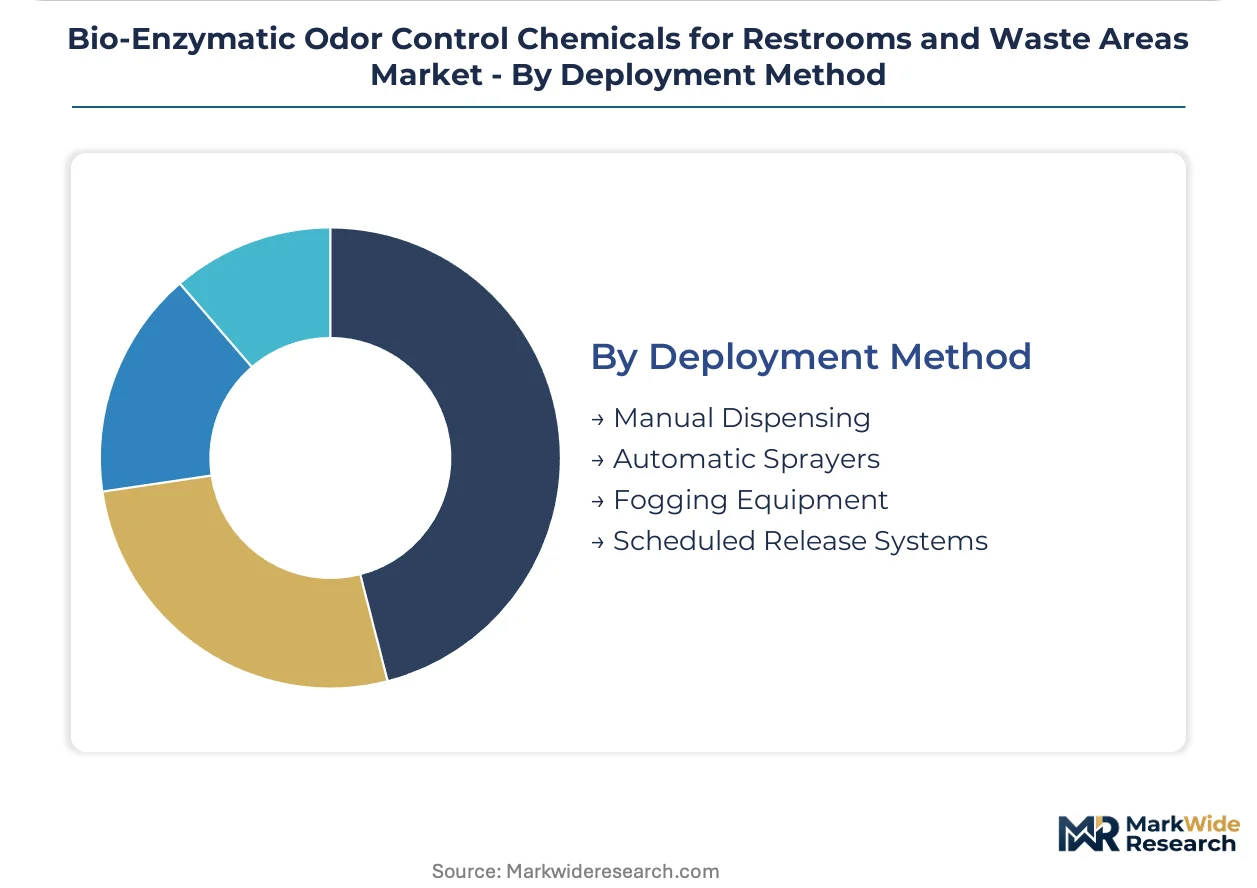
Deployment segmentation tracks the compression of chemical supply and equipment vendor relationships into bundled service contracts with outcome-based pricing.
- Automatic Sprayers:Sensor-activated dispensing systems with programmable dosage intervals. Diversey competes on integrated system bundling that locks in recurring chemical volumes through hardware contracts.
- Scheduled Release Systems:Time-programmed dispensers for facilities with predictable traffic patterns and standardized cleaning windows.
- Manual Dispensing:Dilution and application protocols requiring trained personnel, dominant in cost-sensitive municipal procurement.
- Fogging Equipment:Aerosolized delivery for comprehensive surface coverage in waste management facilities and large-volume restrooms.
Automatic sprayers capture the majority of new capital deployment; scheduled release systems are expanding most rapidly in mid-market commercial building retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and facility management contractors concentrate demand across temperate and tropical climate zones, with regulatory compliance timelines and legacy infrastructure investment cycles determining regional penetration rates.
Germany
Federal Institute for Risk Assessment biocidal claims substantiation extends product development timelines by 18-24 months for enzyme-based formulations entering municipal sanitation networks. REACH Annex XIV authorization requirements for nonylphenol ethoxylates force surfactant package reformulation across European-destined products. Industrial laundries in North Rhine-Westphalia and municipal cleaning cooperatives in the Netherlands absorb 15-30% cost premiums for biosourced alkyl polyglucosides to maintain green procurement certifications.
United States
EPA Safer Choice certification creates federal procurement preference for labeled products in government facility contracts previously captured by conventional chemical suppliers. Hospitality chains leverage institutional cleaning distribution networks for premium positioning across major brands. Facility managers in California and Texas consolidate vendor relationships around integrated dispensing system contracts bundling hardware, chemicals, and consumption analytics.
Japan
METI enforces extended biocidal claims substantiation timelines that delay commercialization of new strain variants. Cold-storage waste facilities in Hokkaido and northern prefectures adopt psychrophilic Bacillus formulations for year-round odor control previously requiring chemical alternation. Advances in psychrophilic cultivation collapse the temperature floor for bio-enzymatic efficacy from 15°C to 4°C.
Brazil
Sanitation agencies in São Paulo and Rio de Janeiro tender enzyme-based formulations for public restroom networks serving World Cup and Olympic legacy infrastructure. Tropical humidity amplifies odor generation rates beyond temperate-zone benchmarks in commercial building sectors. Municipal procurement frameworks prioritize biodegradable alternatives as federal environmental enforcement tightens.
Singapore
Changi Airport tenders multi-year odor control service agreements specifying outcome-based performance metrics rather than volume-based supply. Southeast Asian hospitality chains replicate this model to reduce procurement administrative burden. Tropical climate conditions intensify odor control requirements in high-traffic restroom facilities, concentrating demand for extended-contact gel formulations.
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation supply and integrated dispensing system bundling. The vendor base structures around three tiers: multinational chemical conglomerates with institutional distribution networks, microbial supply specialists with in-house fermentation capacity, and regional formulators serving price-sensitive municipal procurement. Dominant competitive moves include strategic partnerships between chemical suppliers and dispensing equipment manufacturers, plus geographic expansion through local strain registration and compliance certification.
Within the multinational tier, Ecolab and Diversey exemplify divergent approaches to market positioning. Ecolab leverages its institutional cleaning distribution network across North American hospitality chains, while Diversey competes on integrated dispensing system bundling that locks in recurring chemical volumes. Novonesis anchors microbial supply chains through captive fermentation infrastructure, representing the specialist archetype focused on strain development and registration expertise rather than downstream channel control.
| Leading Market Players |
|---|
| Ecolab |
| Diversey |
| Zep |
| Spartan Chemical Company |
| Betco |
| OdoBan |
| Kemira |
| Novonesis |
| Clariant |
| Others |
Pricing and Supply Chain Analysis
North Rhine-Westphalia's industrial fermentation cluster anchors European microbial supply, with molasses and corn steep liquor feedstock volatility transmitting directly into contract renegotiation leverage for buyers. Capacity concentration in this corridor lets large municipal procurers demand index-linked pricing adjustments when agricultural commodity cycles spike.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate municipal procurement in Germany and Brazil. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade formulations separates EPA Safer Choice-labeled products from REACH-compliant tiers and unregistered alternatives. Pricing pressure stems from REACH Annex XIV surfactant reformulation costs, with Dutch and German cooperatives absorbing 15-30% premiums for biosourced alkyl polyglucosides. Municipal services agencies exhibit highest price sensitivity; Singapore airport operators and North American hospitality chains demonstrate lowest sensitivity due to outcome-based contracting.
Supply Chain Analysis
Upstream molasses and corn steep liquor sourcing draws from agricultural processing hubs in Brazil, the United States, and Thailand, with fermentation feedstock prices tethered to sugar and corn futures. Bacillus subtilis and Pseudomonas putida strain libraries rest on cryopreserved master cell banks concentrated in Denmark and Japan. Single-source vulnerability runs through Antarctic-derived psychrophilic strain patents held by limited suppliers. Distribution runs through institutional cleaning distribution networks for hospitality and direct-to-municipality tenders for public sanitation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated dispensing system contracts at Singapore's Changi Airport and Dubai International, fragmenting procurement decisions away from standalone chemical volume purchasing toward bundled outcome-based agreements.
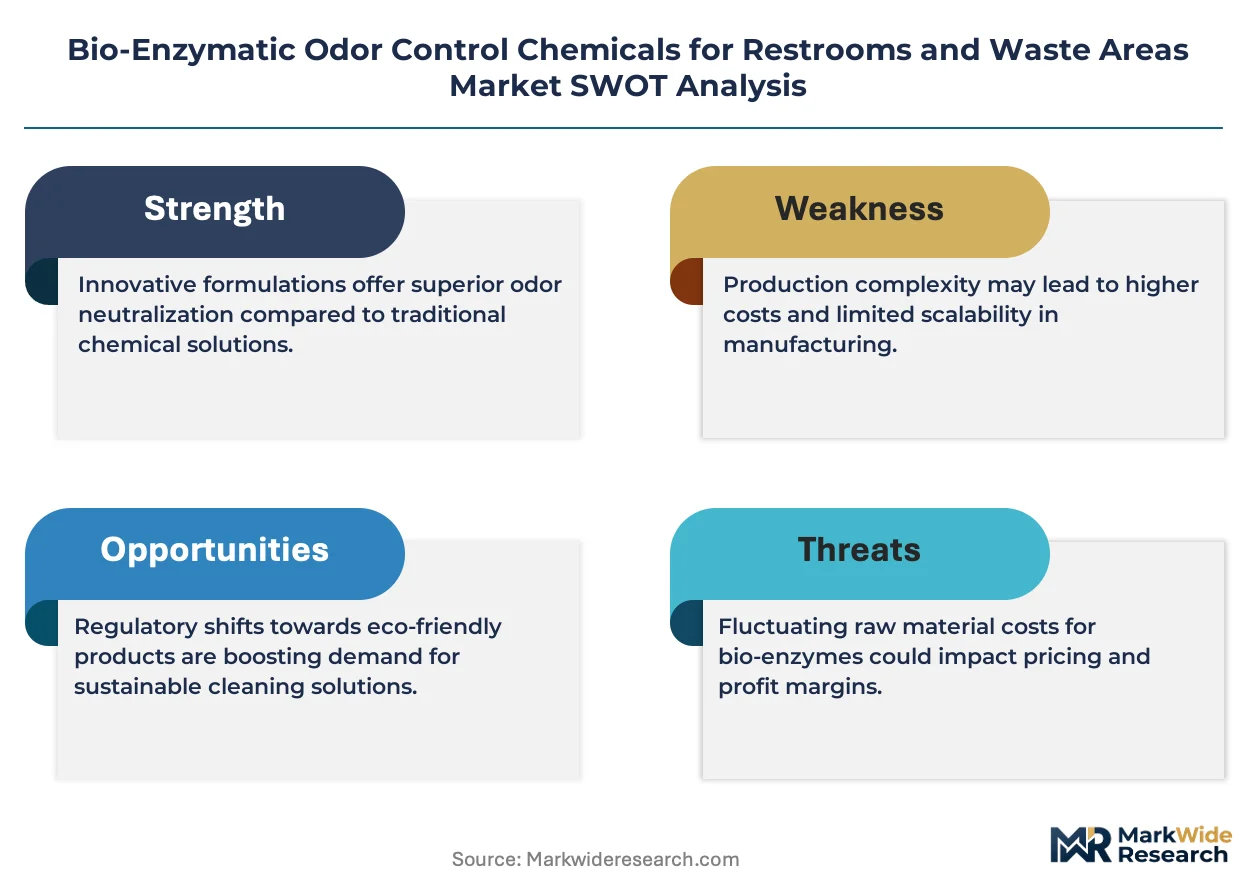
For Market Incumbents: Entrench through captive fermentation capacity additions in North Rhine-Westphalia and Hokkaido to secure strain viability logistics against temperature excursion disputes. Lock in recurring chemical volumes via automatic sprayer hardware bundling before emerging dispensing system vendors capture airport and rail terminal contracts. Prioritize cold-adapted strain patent filings to defend against psychrophilic formulation commoditization. For New Entrants and Emerging Players: Build out regional strain registration capabilities in São Paulo and Rio de Janeiro to capture Brazilian municipal tender opportunities from World Cup and Olympic legacy infrastructure. Target transportation hub gel formulations as the most penetrable segment, where intermittent cleaning schedules and 12-hour residual activity specifications favor specialized entrants over universal liquid concentrate suppliers. Pursue EPA Safer Choice certification as the go-to-market angle for federal facility wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microbial supply specialists with in-house fermentation infrastructure and strain registration expertise over channel-controlling chemical conglomerates. The 5-10 year viability window hinges on consolidation between formulation science and precision dispensing hardware. Watch for geographic expansion through local strain registration as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Molasses and corn steep liquor sourcing from Brazilian sugar mills insulates margin compression from agricultural commodity cycles. |
| Cold-Adapted Strain Patent Portfolio Expansion | Psychrophilic Bacillus formulations from Antarctic soil samples collapse seasonal demand cyclicality in northern Japan and Canada. |
| Integrated Dispensing System Bundling | Automatic sprayer hardware contracts at Singapore Changi Airport lock in recurring chemical volumes through outcome-based service agreements. |
| REACH-Compliant Surfactant Reformulation | Alkyl polyglucoside substitution for nonylphenol ethoxylates maintains German municipal procurement access despite 15-30% cost premiums. |
| Regional Strain Registration and Compliance Certification | METI and Federal Institute for Risk Assessment approvals in Japan and Germany accelerate product commercialization timelines by 18-24 months. |
Research Methodology
Operator-level perspectives from municipal procurement officers, facility management contractors, fermentation plant managers, and institutional distribution channel heads anchored the qualitative base. Primary interviews combined with secondary validation from EPA Safer Choice product registries, REACH Annex XIV authorization databases, METI biocidal claims filings, and customs trade data for enzyme-based sanitation chemical imports. Bottom-up strain production capacity estimates triangulated against top-down municipal tender value aggregation.
Scenario-bracketing around regulatory compliance timelines and tropical climate amplification patterns structured the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application environment, end user industry, and deployment method. CAGRs derived from temperature-specific strain adoption curves and integrated dispensing system penetration rates, with inputs from fermentation feedstock price elasticity and green procurement mandate enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by dispensing system hardware specialists into chemical formulation would shift outcomes. Material shifts in REACH authorization timelines or Antarctic strain patent litigation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Soap and Detergent Market