
 Commercial Deodorizers Market | 2026-2036
Commercial Deodorizers Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Deodorizers Market Outlook
REACH compliance in Europe is broadening the cost-of-entry calculus for manufacturers seeking to distribute commercial deodorizers across EU member states. Ecolab leverages its institutional cleaning platform to sustain contract penetration across healthcare and hospitality verticals. Zep Inc. anchors its position through specialized industrial formulations, while Reckitt Benckiser Group PLC competes via established consumer-to-commercial brand extension strategies.
Commercial deodorizers encompass formulated products designed to neutralize or mask malodorous compounds in enclosed commercial environments, typically employing cyclodextrin encapsulation, activated carbon adsorption, or quaternary ammonium compound chemistry at concentrations between 0.5% and 5% by volume. Their primary industrial purpose centers on maintaining occupant comfort thresholds and sanitation compliance in high-traffic facilities. Aerosol sprays occupy the largest revenue share due to immediate deployment convenience, though activated charcoal segments demonstrate the fastest structural expansion as facilities managers prioritize VOC-free continuous odor control. The hospitality application channel commands premium margin pools, particularly in full-service hotel properties where guest satisfaction metrics directly tie to air quality perception.
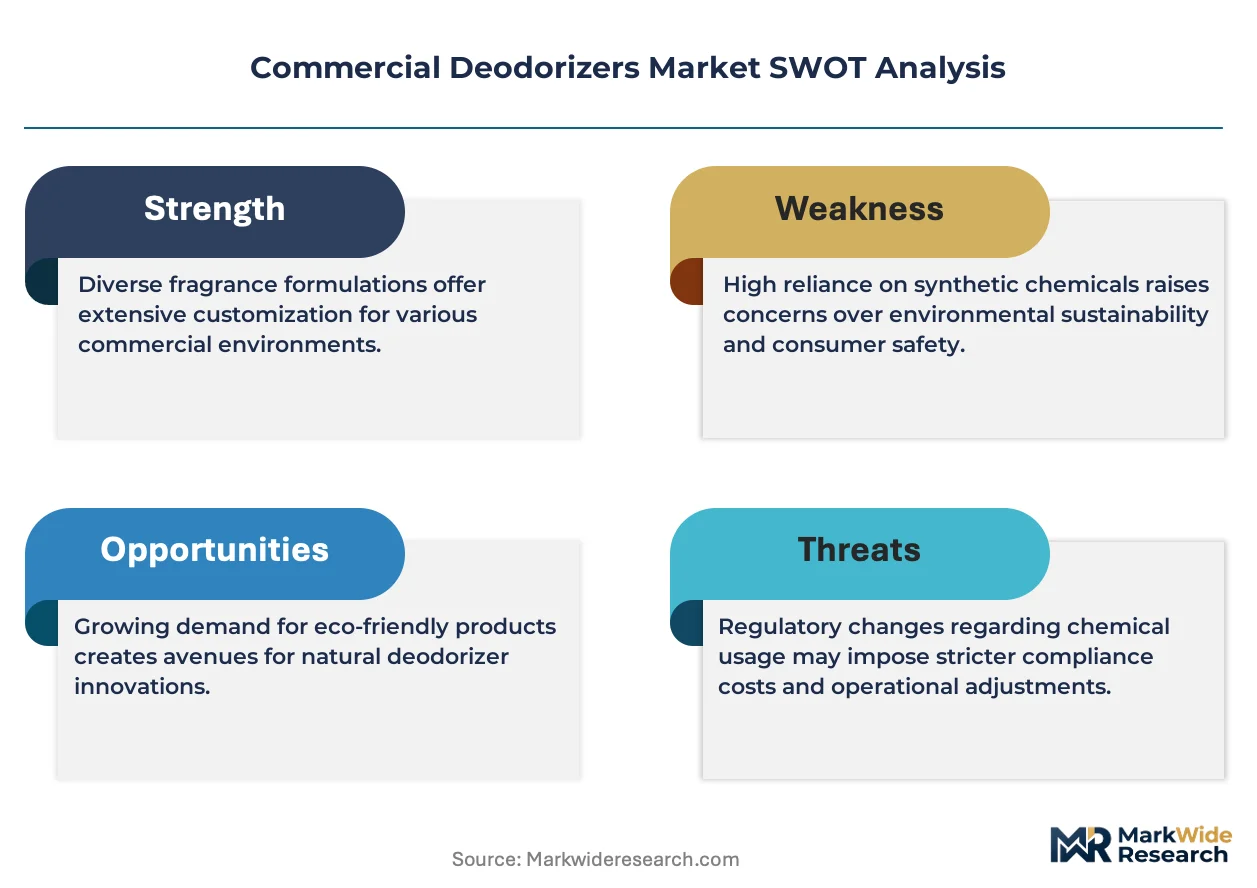
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, while OSHA maintains permissible exposure limits for fragrance chemical components in workplace settings; California's Air Resources Board imposes additional formulation constraints through its Consumer Products Regulation. These overlapping frameworks compel manufacturers to reformulate with exempt compounds or invest in alternative delivery mechanisms. Stakeholders must monitor pending state-level amendments to indoor air quality standards, as patchwork regulatory expansion threatens to fragment product registration requirements across jurisdictions.
Market Dynamics
Stricter indoor air quality mandates across commercial corridors are compressing formulation timelines and forcing capital reallocation toward activated carbon infrastructure and exempt compound R&D pipelines.
Growth Catalysts
- California VOC Regulations:Facilities managers in Los Angeles and San Francisco corridors are accelerating replacement of solvent-based systems with waterborne and solid-phase alternatives to maintain occupancy permits.
- Healthcare Sanitation Protocols:Post-acute care facilities and outpatient surgical centers are mandating continuous odor neutralization as a component of infection control audits.
- Activated Carbon Adsorption:Hospitality procurement teams are specifying fixed-bed charcoal systems for back-of-house and guest corridor applications to eliminate aerosol residue concerns.
Market Restraints
- Petrochemical Feedstock Volatility:Cyclodextrin and quaternary ammonium precursor costs fluctuate with propylene and benzene derivative markets, compressing margin stability for mid-tier formulators.
- Midwest Manufacturing Concentration:Aerosol propellant and canister supply chains cluster around Ohio and Illinois facilities, exposing national distribution to regional weather and labor disruptions.
- Fragrance Component PELs:OSHA permissible exposure limits for limonene and pinene derivatives restrict spray application frequency in enclosed commercial kitchens and custodial closets.
Strategic Opportunities
- Texas Urban Corridor Expansion:Dallas-Fort Worth and Houston office stock additions are outpacing legacy deodorizer service contracts, creating whitespace for integrated facility service providers.
- EPA Safer Choice Certification:Formulators achieving direct release recognition can bypass state-level registration friction and command specification preference in federal building procurement.
- IoT Sensor Convergence:Pairing volatile organic compound detectors with automated charcoal regeneration cycles enables predictive maintenance contracts in premium hospitality properties.
Industry Challenges
- Cross-Contamination Protocol Training:Janitorial contractors face skill gaps in distinguishing food-contact from non-food-contact deodorizer deployment, elevating liability exposure in restaurant and cafeteria accounts.
- Legacy HVAC Integration:Centralized duct-mounted systems require mechanical compatibility assessments with aging air handling units common in pre-2000 commercial building stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Deodorizers Market |
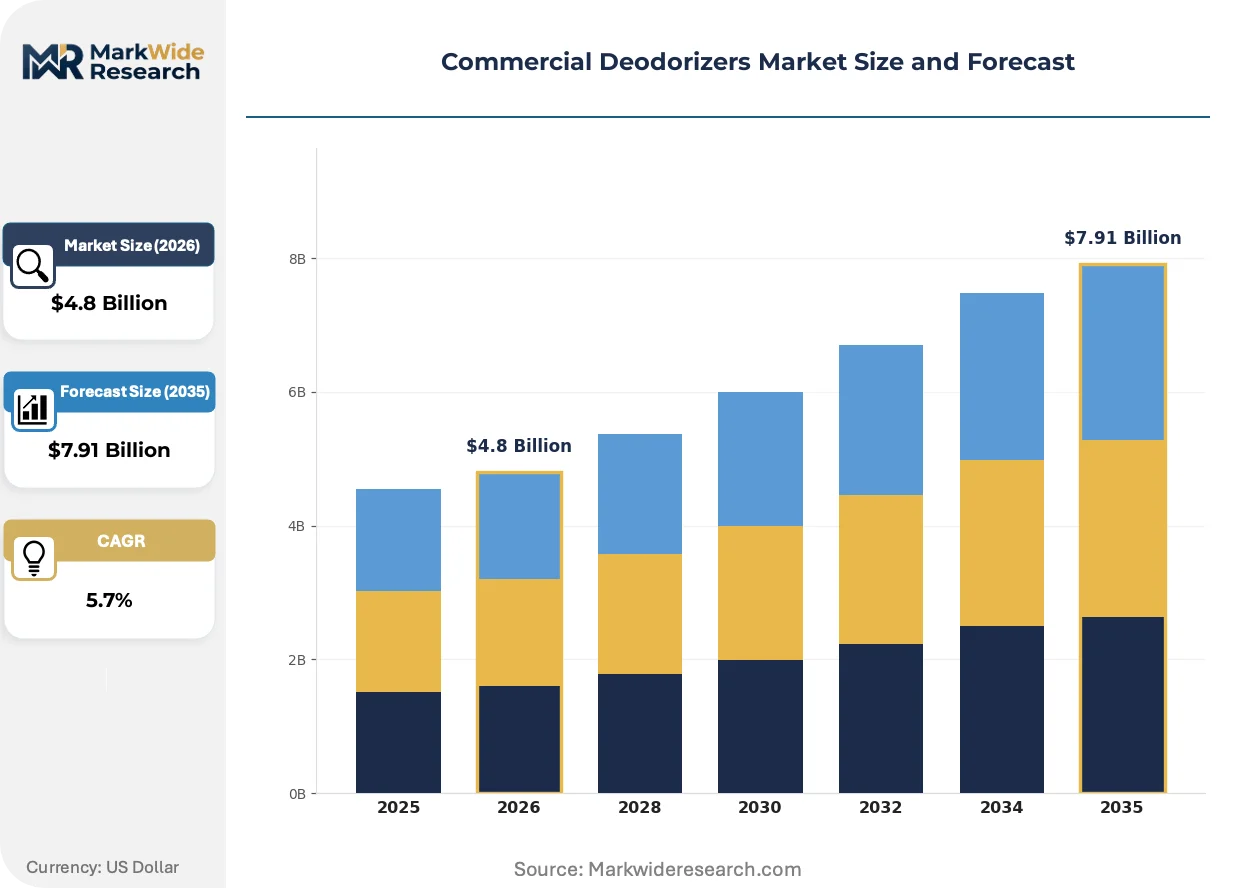
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Sprays, Gel Beads, Plug-ins, Activated Charcoal Application: Healthcare Facilities, Hospitality Industry, Automotive, Fitness Centers End User: Commercial Cleaners, Office Spaces, Restaurants, Retail Stores Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | State Industrial, ATCO International, Kinzua Environmental, Zep Inc., Ecolab, Thornell Corporation, OdoBan, DampRid, Reckitt Benckiser Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Deodorizers Market Strategic Shifts
Electrochemical and solid-phase technologies are displacing legacy aerosol infrastructure as facilities managers prioritize continuous monitoring over episodic masking.
Photocatalytic oxidation coatings applied to HVAC ductwork and ceiling tiles are electrifying the competitive landscape for continuous odor control. Marriott and Hilton engineering specifications now include titanium dioxide-embedded surfaces for corridor and lobby zones. This chemistry compresses service call frequency and shifts revenue models from consumable replenishment toward capital equipment installation.
EPA's 40 CFR Part 59 Subpart C amendments are narrowing the exempt compound list for consumer and commercial aerosols. Formulators are accelerating migration to compressed air and pump spray mechanisms ahead of compliance deadlines. The industrial and institutional channel bears the steepest retooling burden, with Midwest contract manufacturers investing in aqueous filling lines.
Facility managers in Manhattan and Chicago central business districts are consolidating deodorizer procurement under integrated pest management and janitorial service contracts. Bundled specifications favor vendors with multi-service capability over standalone chemical suppliers. This pattern concentrates account control among national facility service platforms and squeezes regional formulator margins.
Commercial Deodorizers Market Segmentation
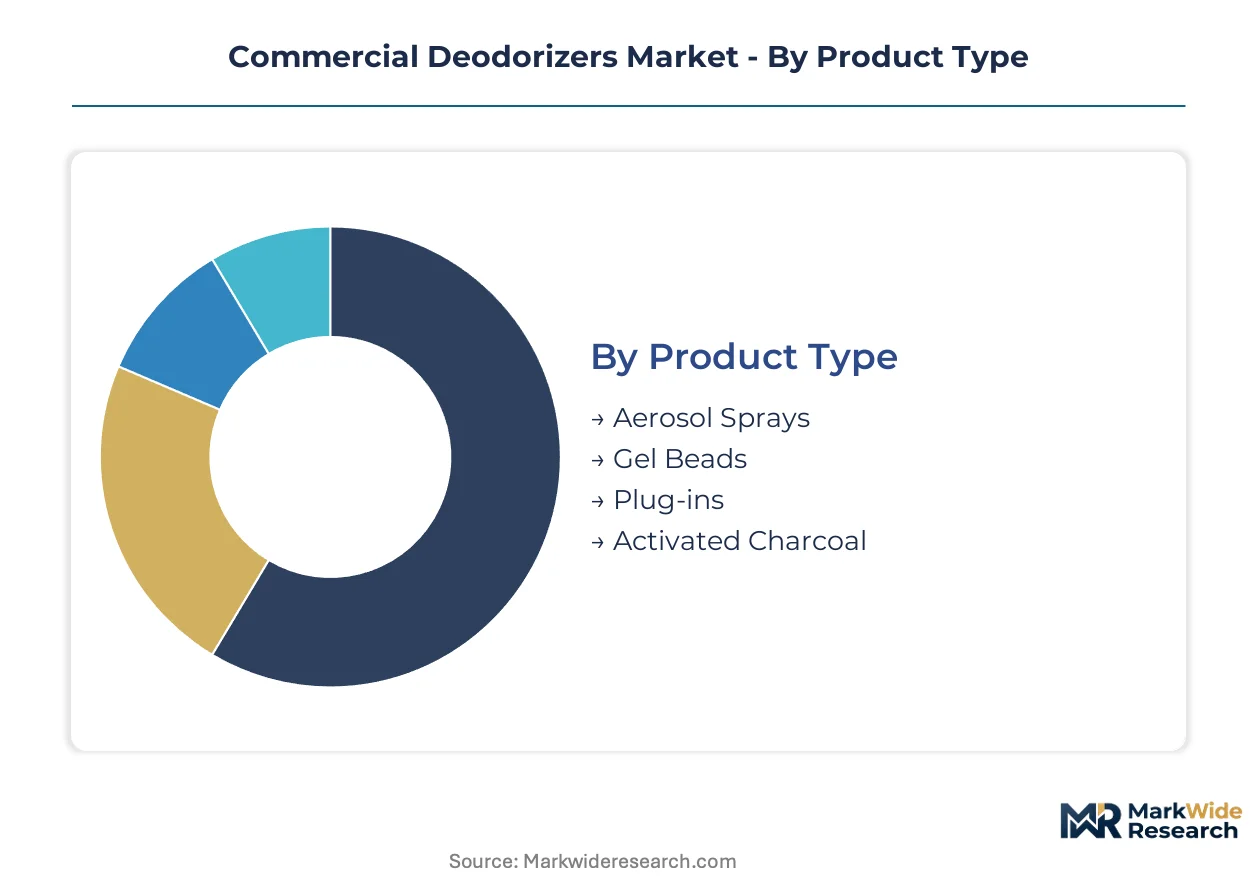
Commercial deodorizer procurement patterns diverge sharply across facility types, with infection control protocols in healthcare driving specification rigor while hospitality prioritizes guest-perception metrics. Understanding these segment boundaries clarifies where formulation investments yield contract penetration versus commodity margin compression.
Product Type:
Facility managers select delivery mechanisms based on deployment labor costs, residue tolerance, and ventilation infrastructure compatibility.
- Aerosol Sprays:Pressurized solvent or waterborne formulations deliver immediate coverage across large surface areas. Demand concentrates in quick-service restaurants and retail back-of-house operations where labor minimization overrides VOC exposure concerns.
- Activated Charcoal:Fixed-bed adsorption systems utilize high-surface-area carbon matrices to capture malodorous compounds without chemical release. Hospitality procurement teams in Los Angeles and San Francisco corridors specify these for guest corridors amid California's stringent indoor air quality mandates.
- Gel Beads:Slow-release polymer matrices suit enclosed spaces with limited HVAC circulation.
- Plug-ins:Continuous low-volume dispensers dominate office workstation clusters and small retail formats.
Volume sits with Aerosol Sprays; growth tilts toward Activated Charcoal.
Application:
Regulatory intensity and occupant sensitivity create tiered margin structures across verticals.
- Hospitality Industry:Full-service hotel properties and convention centers demand odor control systems integrated with brand standards and guest satisfaction surveys. Marriott and Hilton engineering specifications now include photocatalytic oxidation surfaces for lobby and corridor zones, compressing traditional consumable replenishment cycles.
- Healthcare Facilities:Post-acute care and outpatient surgical centers mandate continuous neutralization as a component of Joint Commission infection control audits. EPA Safer Choice certification carries specification weight in federal hospital procurement.
- Fitness Centers:High-occupancy, high-perspiration environments require frequent reapplication protocols.
- Automotive:Dealership service bays and rental fleet preparation facilities prioritize rapid turnaround masking.
Margin concentrates in Hospitality Industry; compliance burden peaks in Healthcare Facilities.
End User:
Contract structure and procurement centralization separate account control opportunities from fragmented spot purchasing.
- Commercial Cleaners:National janitorial service platforms bundle deodorizer procurement under integrated facility management contracts. Ecolab and similar institutional cleaning vendors leverage existing route density to sustain specification preference.
- Restaurants:Food-contact proximity restrictions elevate liability exposure and require staff training on deployment zone differentiation. Cross-contamination protocol gaps create account vulnerability for standalone chemical suppliers.
- Office Spaces:Corporate real estate managers in Manhattan and Chicago central business districts consolidate procurement under multi-service agreements.
- Retail Stores:Seasonal traffic volatility drives preference for flexible, low-commitment supply arrangements.
Contract value clusters with Commercial Cleaners; churn risk concentrates in Restaurants.
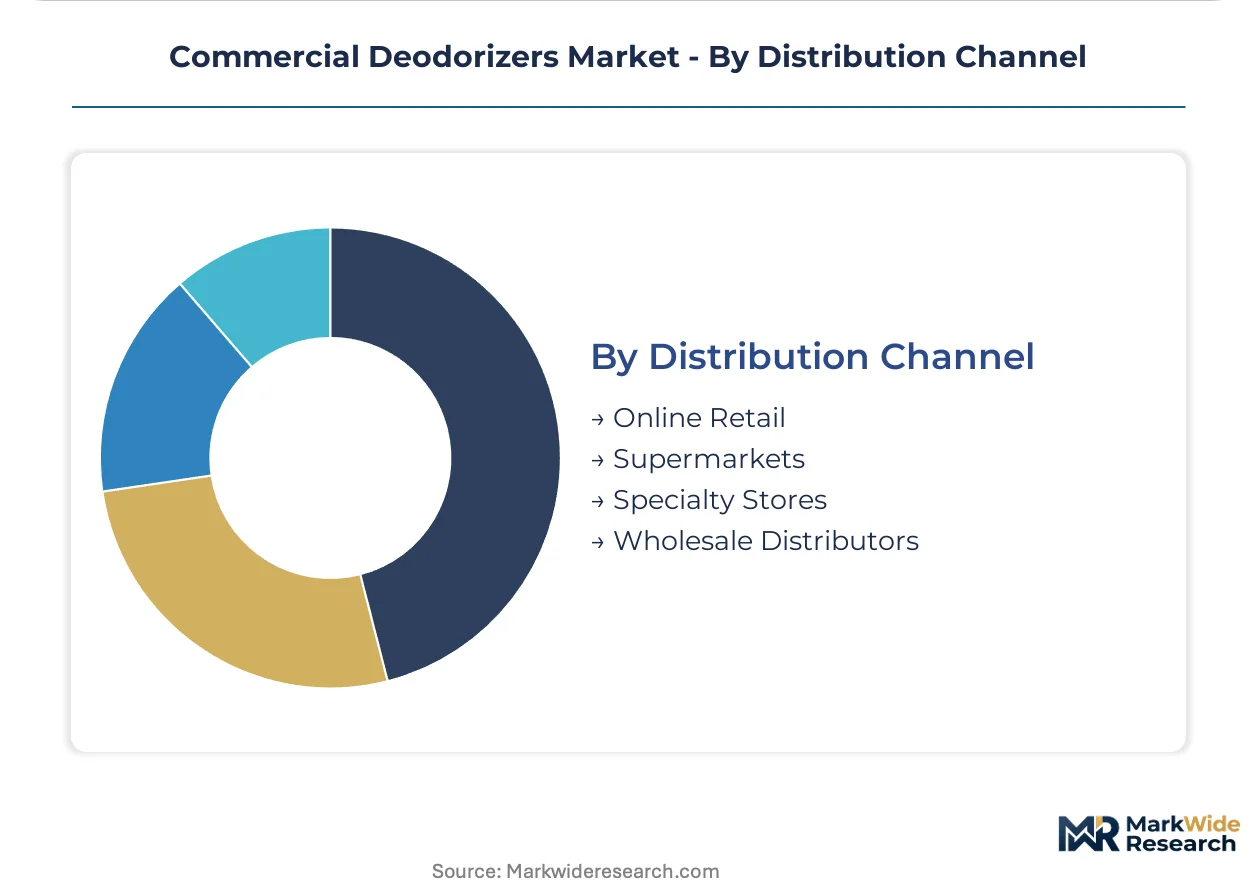
Distribution Channel:
Buyer scale and specification complexity determine channel selection, with large accounts bypassing retail intermediaries.
- Wholesale Distributors:Institutional supply houses serve healthcare systems and hospitality chains with consolidated logistics and technical specification support. Midwest aerosol propellant manufacturing concentration exposes this channel to regional supply disruptions.
- Online Retail:E-procurement platforms capture mid-tier facility managers seeking EPA Safer Choice product transparency and direct-to-site delivery scheduling.
- Specialty Stores:Janitorial supply showrooms provide hands-on product comparison for independent contractors.
- Supermarkets:Mass retail captures small-format commercial accounts with immediate availability requirements.
Share concentrates in Wholesale Distributors; expansion tilts toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones across the United Arab Emirates concentrate manufacturing capacity for Gulf export markets. Duty exemptions and streamlined customs protocols attract multinational formulators seeking Middle East distribution hubs.
United States
Urban commercial corridors in Manhattan and Chicago drive specification demand for continuous odor control systems. EPA's 40 CFR Part 59 Subpart C amendments compel aerosol formulators toward compressed air delivery mechanisms. Dallas-Fort Worth and Houston office stock expansions outpace legacy service contracts, creating whitespace for integrated facility providers.
Germany
REACH compliance broadens cost-of-entry for manufacturers distributing across EU member states. ECHA registration requirements force reformulation timelines for cyclodextrin and quaternary ammonium compounds. Industrial clusters in North Rhine-Westphalia host institutional cleaning platforms serving healthcare and hospitality verticals.
China
Dual carbon goals under MEE directives accelerate activated carbon infrastructure investment in manufacturing zones. GB standards for indoor air quality tighten formulation requirements for imported commercial deodorizers. Yangtze River Delta facilities prioritize solid-phase delivery systems over solvent-based alternatives.
United Arab Emirates
Hospitality construction in Dubai and Abu Dhabi specifies fixed-bed charcoal systems for luxury property portfolios. MOHAP sanitation protocols for healthcare facilities mandate continuous neutralization in post-acute care settings. Jebel Ali Free Zone concentration enables Gulf-wide distribution without tariff friction.
Japan
METI energy efficiency standards favor low-power continuous dispensing systems in commercial buildings. JIS certification requirements create specification barriers for non-domestic suppliers. Kanto region facility managers consolidate procurement under integrated pest management contracts.
Commercial Deodorizers Market Competitive Environment
United States producers anchor one tier; European specialists hold formulation compliance advantages. The vendor base separates into three functional layers: institutional cleaning platforms with route density, industrial chemical formulators with exempt compound pipelines, and consumer brand extenders leveraging retail recognition. Two dominant competitive moves define current positioning: geographic expansion into Texas urban corridors and portfolio diversification toward solid-phase delivery systems.
Within the institutional platform tier, Ecolab and Zep Inc. exemplify archetype positioning through existing contract infrastructure. Reckitt Benckiser Group PLC occupies a position bridging consumer recognition with commercial specification channels. These three entities represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| State Industrial |
| ATCO International |
| Kinzua Environmental |
| Zep Inc. |
| Ecolab |
| Thornell Corporation |
| OdoBan |
| DampRid |
| Reckitt Benckiser Group PLC |
| Others |
Value Chain & Pricing Dynamics
Midwest aerosol propellant technician concentrations in Ohio and Illinois drive labor-cost differentials that widen pricing-tier spreads between premium EPA Safer Choice-certified formulations and commodity solvent-based alternatives.
Pricing Analysis
Short lead-time premiums attach to activated charcoal systems with compressed air delivery mechanisms, while spot inventory of legacy aerosol formulations trades at discounts amid EPA 40 CFR Part 59 compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified solid-phase systems from waterborne mid-tier alternatives and commodity solvent-based sprays. Cost compression in the aerosol tier is intensifying because Midwest contract manufacturers retool aqueous filling lines. Quick-service restaurant procurement teams exhibit highest price sensitivity; hospitality chains in California corridors show lowest sensitivity given occupancy permit compliance requirements.
Supply Chain Analysis
California's domestic-content mandates for state building procurement are reshaping sourcing toward activated carbon manufacturers with in-state assembly capacity. Propellant and canister supply chains draw from Ohio, Illinois, and Texas facilities; cyclodextrin precursors feed from benzene derivative markets concentrated in Louisiana and Texas. Single-source vulnerability concentrates in Midwest aerosol propellant manufacturing clusters exposed to regional weather disruptions. Distribution runs through institutional supply houses serving healthcare systems and hospitality chains with consolidated logistics and technical specification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Activated carbon adsorption system capacity bottlenecks in compliant manufacturing zones prop pricing premiums, constraining volume expansion for facilities managers seeking VOC-free continuous odor control.
For Market Incumbents: Hedge against aerosol formulation obsolescence by accelerating backward integration into compressed air and pump spray mechanism production in Texas manufacturing corridors. Secure EPA Safer Choice direct release recognition to bypass state-level registration friction and defend contract penetration against emerging solid-phase specialists. For New Entrants and Emerging Players: Janitorial service platforms represent the most accessible channel partner type for bypassing fragmented spot purchasing in retail and restaurant accounts. Target Dallas-Fort Worth and Houston office stock expansions outpacing legacy deodorizer service contracts. Lead with bundled integrated facility management capabilities rather than standalone chemical supply. For Investors and Strategic Acquirers: Re-rating potential sits with institutional cleaning platforms with existing route density given IoT sensor convergence enabling predictive maintenance contract pricing. Long-term viability favors vendors with multi-service capability over standalone formulators. Watch EPA state-level amendment momentum as inflection indicator for registration cost fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressed Air Mechanisms | Midwest contract manufacturers retool aqueous filling lines ahead of EPA Subpart C compliance deadlines. |
| EPA Safer Choice Certification Investment | Federal building procurement specifications increasingly require direct release recognition for deodorizer products. |
| IoT Sensor Platform Partnership | Marriott and Hilton engineering teams specify VOC detector integration with automated charcoal regeneration cycles. |
| Texas Urban Corridor Service Expansion | Dallas-Fort Worth and Houston office stock additions outpace legacy deodorizer service contract coverage. |
| Photocatalytic Oxidation Surface Licensing | Titanium dioxide-embedded coatings shift revenue from consumable replenishment toward capital equipment installation. |
Study Parameters
Multi-period observation of EPA regulatory amendment timelines and hospitality procurement specification changes anchored the trend analysis, supplemented by interviews with facilities managers at full-service hotel properties, janitorial service platform procurement directors, activated carbon system manufacturers, and institutional supply house technical sales specialists. Secondary validation drew from EPA 40 CFR Part 59 regulatory filings, California Air Resources Board Consumer Products Regulation updates, hospitality engineering specification databases, and customs trade data on cyclodextrin and quaternary ammonium compound imports. Bottom-up facility-level demand modeling and top-down market sizing triangulation produced convergent volume estimates.
Input-output matrices mapped product type, application vertical, and end-user contract structure dimensions across the projection horizon. CAGRs derived from segmented growth rate differentials applied to base-year market estimates. Forecast inputs incorporated EPA compliance deadline phasing, California VOC regulation enforcement intensity, and hospitality construction pipeline data from urban commercial corridors.
Caveats apply where EPA state-level amendment acceleration or petrochemical feedstock volatility spikes could materially shift the outlook for mid-tier formulator margin stability. Forecasts reflect documented assumptions on regulatory timeline adherence and facility manager procurement consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Cleanroom Consumables Market