
 Surface Disinfectants Market | 2026-2036
Surface Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Disinfectants Market Analysis
Buyer concentration among hospital networks and long-term care chains is restructuring procurement dynamics across the surface disinfectants sector. Ecolab leverages its service-integrated model to anchor contracts with large healthcare systems, while STERIS competes through specialized infection prevention protocols for surgical suites. Reckitt Benckiser Group sustains consumer-facing brand strength in retail channels, extending its reach through pharmacy and grocery distribution.
Surface disinfectants are antimicrobial chemical preparations, typically containing active concentrations of quaternary ammonium compounds, sodium hypochlorite, or hydrogen peroxide, designed to eliminate or reduce pathogenic microorganisms on non-living surfaces in clinical, commercial, and industrial environments. Liquid solutions dominate institutional procurement due to cost efficiency and bulk dispensing compatibility, while wipes command premium positioning in healthcare settings where rapid point-of-use application reduces cross-contamination risk. Hydrogen peroxide formulations represent the fastest-growing chemistry segment as facilities seek sporicidal efficacy without persistent toxic residues on food contact and patient care surfaces.
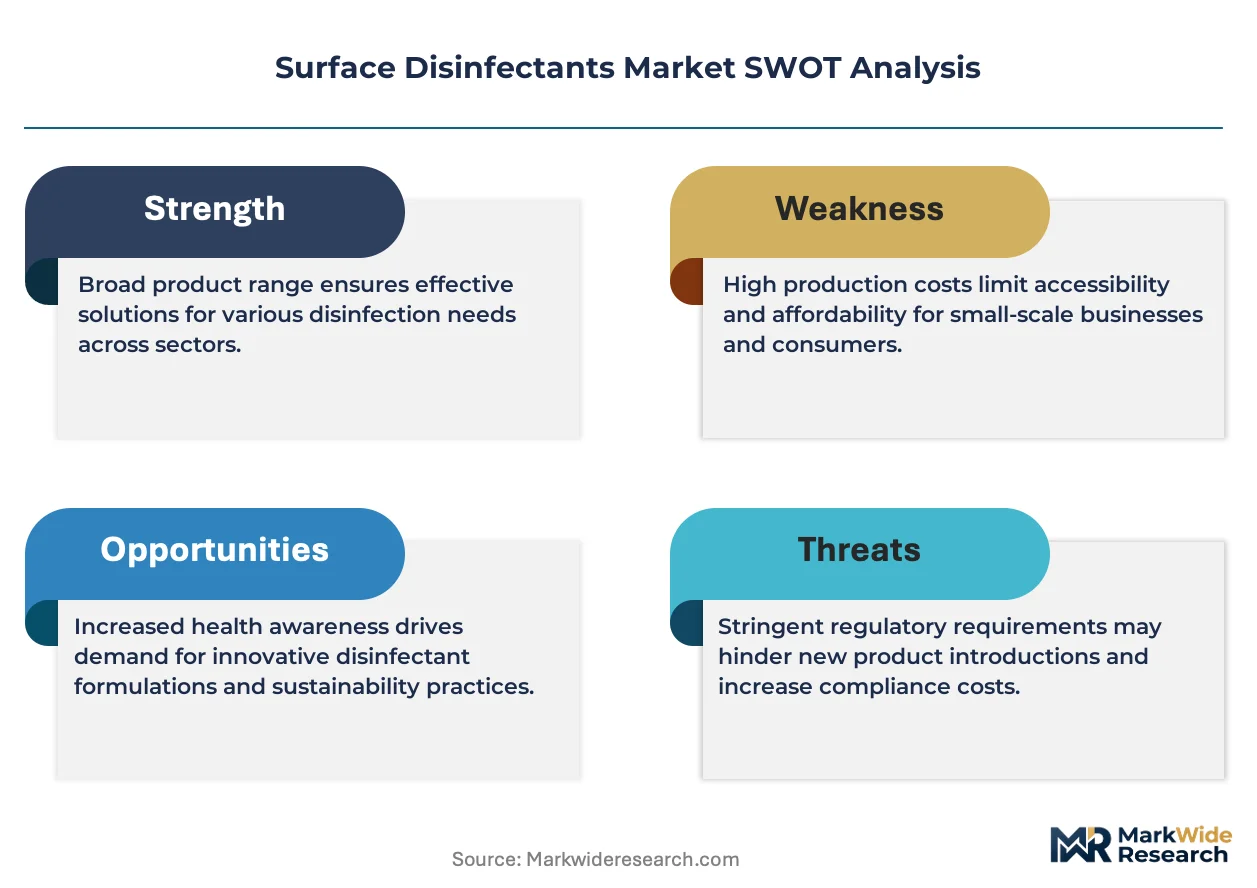
EPA regulates antimicrobial efficacy claims and toxicity profiles for surface disinfectants sold in the United States, while ECHA oversees biocidal product authorization under BPR guidelines across Europe, creating divergent compliance pathways that shape formulation development and market access timelines. FDA engagement with healthcare-associated infection reduction initiatives indirectly elevates product performance standards for hospital-grade disinfectants. Stakeholders must monitor evolving residue limits and green chemistry mandates that will determine which active ingredients retain commercial viability across regulated end-use environments.
Market Dynamics
Hospital-grade formulation procurement is restructuring around EPA toxicity mandates and hydrogen peroxide chemistry transitions, forcing manufacturers to retire legacy quaternary ammonium blends while building sporicidal efficacy portfolios.
Growth Catalysts
- EPA Hospital-Grade Mandates:United States healthcare facilities must upgrade to sporicidal formulations under revised toxicity thresholds, accelerating hydrogen peroxide adoption across surgical suites and patient care zones.
- Food Processing Sanitation:ECHA biocide regulations in Germany enforce hydrogen peroxide and quaternary ammonium protocols across meatpacking and dairy operations, creating institutional demand for residue-compliant chemistries.
- Long-Term Care Expansion:Aging demographics in Japan and Italy are expanding skilled nursing bed counts, driving recurring disinfectant consumption for infection control in high-density residential care settings.
Market Restraints
- Active Ingredient Supply Concentration:Hydrogen peroxide precursor manufacturing clusters in China and Germany create vulnerability to feedstock disruption and freight cost volatility.
- Biocide Authorization Timelines:ECHA BPR compliance pathways extend 18-36 months for novel formulations, freezing commercialization schedules and locking R&D capital in regulatory limbo.
- Electrolyzed Water Substitution:On-site generation systems for hypochlorous acid are capturing mid-tier institutional contracts by eliminating chemical procurement and storage overhead.
Strategic Opportunities
- India Healthcare Infrastructure:CDSCO hospital licensing expansion and Ayushman Bharat facility construction are opening procurement channels for EPA-registered formulations in tier-2 and tier-3 cities.
- Green Chemistry Incentives:EU Green Deal biocide sustainability criteria are creating preferential market access for peracetic acid and hydrogen peroxide blends with accelerated biodegradation profiles.
- E-Commerce Institutional Channels:Veterinary clinics and dental practices are migrating to specialized B2B platforms for small-batch disinfectant ordering, bypassing traditional distribution markups.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in sporicidal stability and surface compatibility is concentrating among legacy manufacturers, constraining new entrant R&D velocity.
- Legacy Equipment Integration:Automated dilution and dispensing systems in United States hospital networks require retrofitting for hydrogen peroxide concentration ranges, comifying facility upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Disinfectants Market |
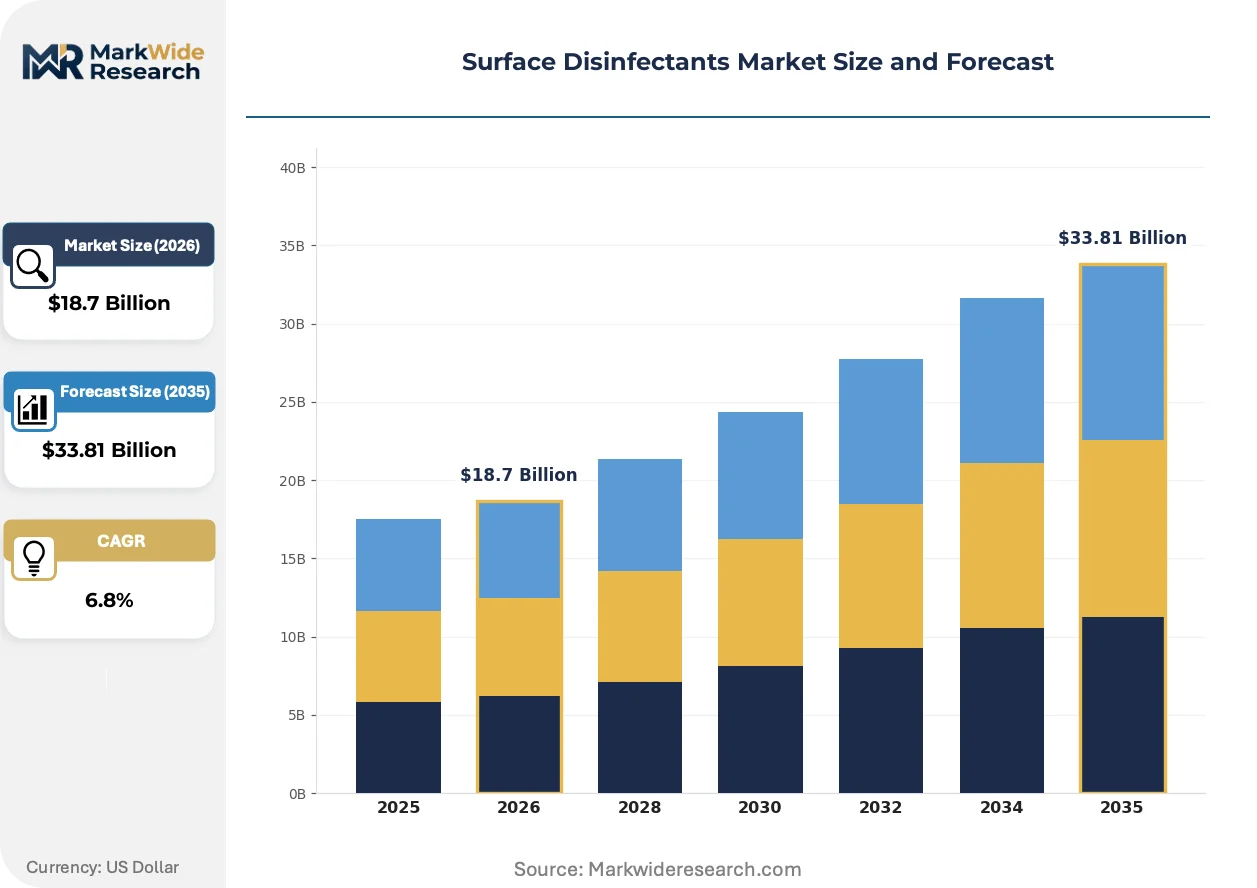
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Solutions, Wipes, Sprays, Foams Application: Healthcare Facilities, Food Processing, Household, Industrial Formulation: Alcohol-Based, Quaternary Ammonium Compounds, Hydrogen Peroxide, Sodium Hypochlorite Packaging Type: Bulk Containers, Bottle, Canister, Sachets |
| Companies Covered | Reckitt Benckiser Group, Procter & Gamble, 3M Company, Ecolab, The Clorox Company, STERIS, GOJO Industries, SC Johnson Professional, Diversey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Disinfectants Market Emerging Trajectories
Accelerated chemistry transitions and procurement digitization are compressing product lifecycles while elevating performance verification standards across institutional buyer segments.
Accelerated hydrogen peroxide formulations are overtaking stabilized chlorine blends in United States hospital networks seeking sporicidal efficacy without corrosive residue accumulation on stainless steel surgical equipment. Academic medical centers in Boston and Houston are completing chemistry transitions within 18-month procurement cycles. This displacement is compressing quaternary ammonium contract durations and forcing reformulation investments.
REACH restriction proposals on quaternary ammonium compound residues are compelling European manufacturers to submit enhanced toxicity dossiers or pivot active ingredient portfolios toward peracetic acid alternatives. Industrial laundries and food contact surface applications face the steepest compliance burdens. German chemical suppliers are consolidating hydrogen peroxide blending capacity to serve cross-border ECHA-authorized product lines.
Consolidated purchasing cooperatives among United States hospital systems are unbundling disinfectant supply from bundled service contracts, forcing Ecolab and STERIS to compete on standalone chemistry performance metrics. GPOs in Texas and California are piloting digital procurement platforms with real-time consumption tracking. This disintermediation is most visible in multi-hospital networks seeking transparent unit economics for infection prevention spend.
Surface Disinfectants Market Segmentation
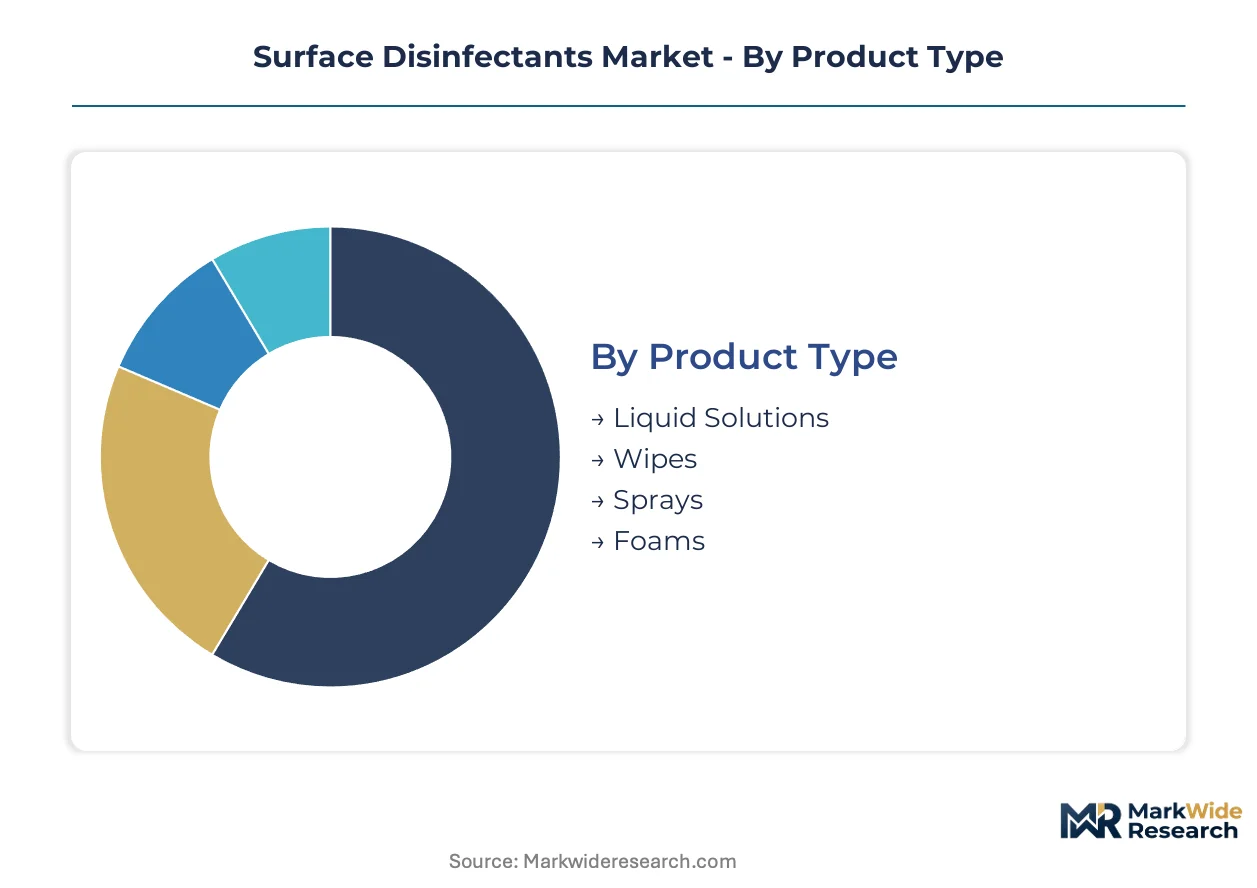
Surface disinfectant procurement diverges sharply across end-use environments, with healthcare networks prioritizing sporicidal efficacy while food processors optimize for residue compliance. Understanding these segment-specific performance thresholds determines both formulation R&D allocation and distribution channel strategy.
Product Type:
Liquid solutions demand the heaviest capital investment in automated dilution infrastructure and bulk storage systems, while wipes require specialized nonwoven substrate manufacturing and aseptic packaging lines.
- Liquid Solutions:Concentrated formulations designed for automated dispensing systems and manual dilution protocols. Hospital networks in the United States concentrate procurement here, driven by EPA-mandated sporicidal efficacy requirements and cost-per-application economics.
- Wipes:Pre-saturated nonwoven substrates delivering point-of-use convenience with controlled active ingredient dosing. German food processing facilities and Japanese long-term care chains drive demand, prioritizing cross-contamination reduction over unit cost.
- Sprays:Aerosol and trigger-dispensed formulations for rapid coverage of irregular surfaces.
- Foams:Clinging formulations extending contact time on vertical and overhead surfaces.
Most installed capacity flows through Liquid Solutions. Expansion is steepest in Wipes.
Application:
Healthcare facilities generate the highest margin per liter but require the most intensive regulatory documentation, while household applications trade performance certification for volume scale and retail shelf presence.
- Healthcare Facilities:Hospital-grade and critical care environments requiring EPA-registered sporicidal claims. Academic medical centers in Boston and Houston are accelerating hydrogen peroxide chemistry transitions, compressing procurement cycles to 18 months.
- Food Processing:Meatpacking, dairy, and beverage operations governed by ECHA biocide residue limits. German industrial laundries and slaughterhouses anchor European demand for peracetic acid and hydrogen peroxide blends with accelerated biodegradation profiles.
- Household:Consumer retail channels spanning pharmacy, grocery, and e-commerce platforms.
- Industrial:Manufacturing floors, warehousing, and transportation equipment sanitation protocols.
Healthcare Facilities command the highest certification burden. Food Processing exhibits the steepest chemistry transition velocity.
Formulation:
Hydrogen peroxide and quaternary ammonium compound manufacturing require specialized reactor infrastructure and stabilization chemistry expertise, creating capital barriers that concentrate supply among legacy producers.
- Hydrogen Peroxide:Sporicidal formulations achieving efficacy without persistent toxic residues. United States surgical suites and German food contact surfaces are displacing stabilized chlorine blends, driven by EPA toxicity thresholds and ECHA REACH restriction proposals on legacy chemistries.
- Quaternary Ammonium Compounds:Broad-spectrum bactericidal and virucidal agents with surface compatibility advantages. Long-term care chains in Japan and Italy sustain demand amid aging demographic pressures, though European authorization timelines are extending under enhanced toxicity dossier requirements.
- Alcohol-Based:Rapid-evaporation formulations for non-porous surface applications.
- Sodium Hypochlorite:Chlorine-based sanitizers facing displacement from hydrogen peroxide in premium institutional segments.
Quaternary Ammonium Compounds retain the largest installed base. Hydrogen Peroxide is climbing the fastest.
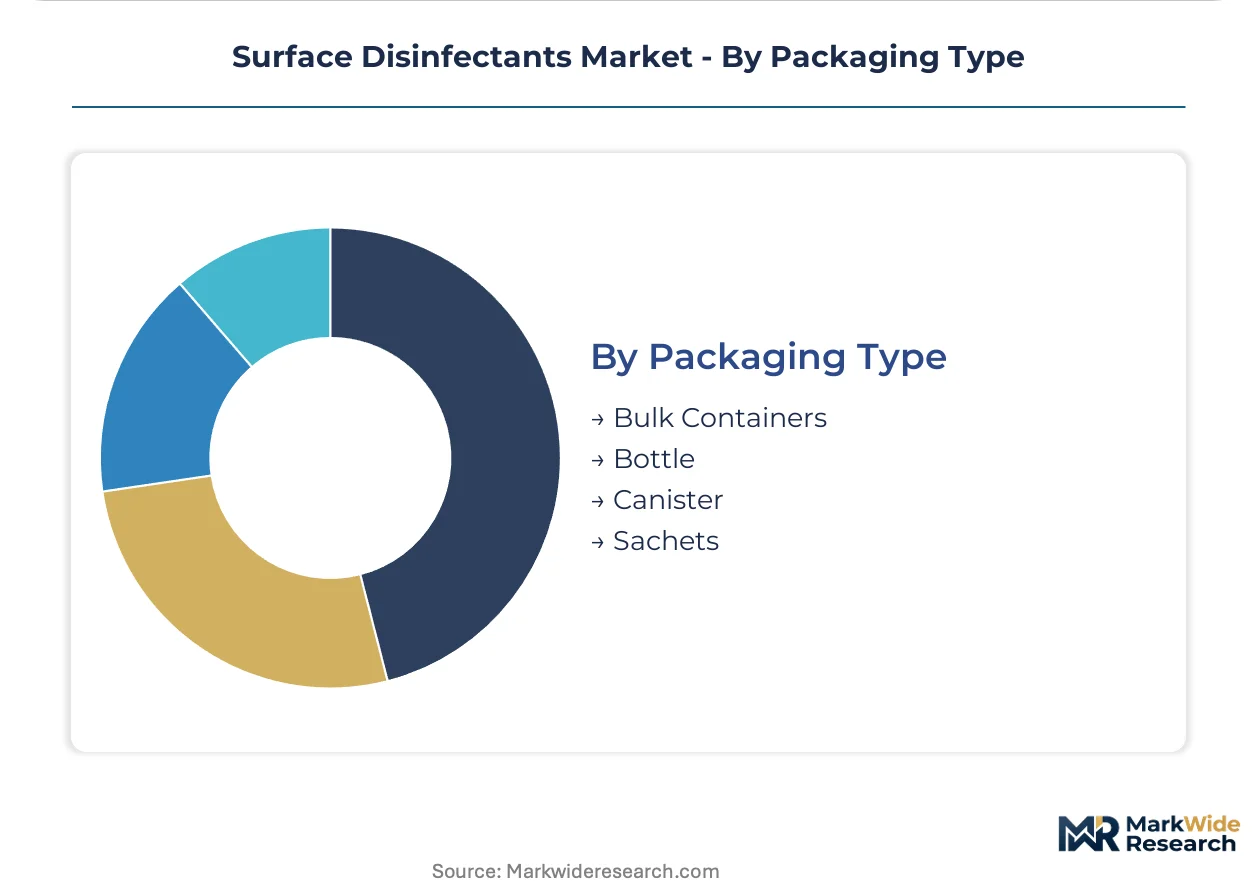
Packaging Type:
Bulk container supply chains demand integrated logistics partnerships and just-in-time replenishment systems, while sachet production requires precision form-fill-seal equipment and regional packaging adaptation.
- Bulk Containers:Refillable totes and drums serving automated dilution systems in hospital networks and industrial laundries. United States GPOs in Texas and California are unbundling these from service contracts, forcing transparent unit economics disclosure.
- Canister:Rigid dispensers for wet wipes in point-of-use healthcare and food processing environments.
- Bottle:Manual-pour containers for household and small institutional applications.
- Sachets:Single-use packets for field deployment and emerging market distribution.
Bulk Containers dominate institutional procurement volume. Canister formats are gaining share fastest in healthcare point-of-use applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with sporicidal stability expertise cluster in Germany and the United States, anchoring hydrogen peroxide innovation hubs that serve hospital networks and food processing facilities across multiple continents.
United States
EPA hospital-grade mandates are accelerating hydrogen peroxide chemistry transitions in surgical suites and patient care zones. Academic medical centers in Boston and Houston compress procurement cycles to eighteen months. GPOs in Texas and California pilot digital procurement platforms with real-time consumption tracking.
Germany
Industrial cleaning protocols and ECHA biocide regulations push adoption of hydrogen peroxide and quaternary ammonium formulations across food processing and clinical settings. REACH restriction proposals on quaternary ammonium compound residues compel manufacturers to submit enhanced toxicity dossiers. German chemical suppliers consolidate hydrogen peroxide blending capacity to serve cross-border ECHA-authorized product lines.
Japan
Aging demographics expand skilled nursing bed counts, driving recurring disinfectant consumption for infection control in high-density residential care settings. METI guidelines for healthcare-associated infection prevention elevate product performance standards. Long-term care chains in Tokyo and Osaka sustain demand for quaternary ammonium formulations amid demographic pressures.
India
CDSCO hospital licensing expansion and Ayushman Bharat facility construction open procurement channels for EPA-registered formulations in tier-2 and tier-3 cities. The national pharmaceutical regulator tightens sanitation mandates for clinical environments. Manufacturing clusters in Maharashtra and Gujarat develop blending capacity to serve domestic healthcare infrastructure growth.
Italy
Long-term care expansion accelerates disinfectant procurement for elderly residential facilities. EU Green Deal biocide sustainability criteria create preferential market access for peracetic acid and hydrogen peroxide blends. Industrial laundries in Lombardy and Emilia-Romagna face steep compliance burdens from enhanced residue limit enforcement.
Surface Disinfectants Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and service integration vectors. The vendor base organizes around three strategic archetypes: service-integrated hygiene platforms, specialized infection prevention protocol providers, and consumer-facing brand houses with pharmacy distribution. Consolidated purchasing cooperatives among hospital systems unbundle disinfectant supply from bundled service contracts, forcing transparent chemistry performance metrics. Two dominant competitive moves reshape positioning: backward integration into hydrogen peroxide precursor manufacturing and geographic expansion through CDSCO-registered product lines in Indian tier-2 cities.
Among diversified conglomerates with hygiene platforms, Reckitt Benckiser Group and Procter & Gamble occupy positions spanning consumer retail and institutional channels. Ecolab represents the service-integrated archetype, anchoring contracts with large healthcare systems through bundled facility hygiene programs. STERIS exemplifies the specialized infection prevention tier, with positioning concentrated in surgical suite protocols. These three companies illustrate the competitive tension between breadth and depth across the procurement landscape.
| Leading Market Players |
|---|
| Reckitt Benckiser Group |
| Procter & Gamble |
| 3M Company |
| Ecolab |
| The Clorox Company |
| STERIS |
| GOJO Industries |
| SC Johnson Professional |
| Diversey |
| Others |
Supply Flow & Price Mechanics
Hydrogen peroxide chemistry transitions across United States hospital networks simultaneously compress formulation costs and concentrate supplier power among legacy manufacturers with stabilized blending expertise. EPA-mandated sporicidal efficacy requirements are forcing procurement departments to abandon legacy quaternary ammonium contracts, reshaping how pricing power distributes across the value chain.
Pricing Analysis
Bundled facility hygiene contracts are fragmenting into unbundled chemistry procurement as GPOs demand transparent unit economics. Three-tier pricing structure across EPA-registered sporicidal, hospital-grade broad-spectrum, and economy retail tiers separates certification burden from volume scale. Pricing pressure stems from electrolyzed water on-site generation systems capturing mid-tier institutional contracts. Small veterinary clinics and dental practices exhibit highest price sensitivity; academic medical centers prioritize sporicidal performance over per-unit cost.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital networks and German food processors require qualification of secondary hydrogen peroxide precursor suppliers. Active ingredient manufacturing clusters in China and Germany feed blending operations across North America and Europe. Feedstock vulnerability rests on concentrated anthraquinone oxidation capacity and freight cost volatility. Distribution runs through integrated logistics partnerships for bulk totes and specialized B2B platforms for small-batch wet wipe canisters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hydrogen peroxide formulation transitions, where chemistry stability expertise commands premium positioning against commodity chlorine blends. Cost compression in legacy quaternary ammonium manufacturing is accelerating premium-tier displacement.
For Market Incumbents: Acquire hydrogen peroxide precursor manufacturing assets to secure captive supply of anthraquinone-process feedstock. Build ECHA-authorized blending capacity in Germany to serve cross-border European demand. Electrolyzed water substitution threats and GPO unbundling pressure demand backward integration into active ingredient production. For New Entrants and Emerging Players: Launch via specialized B2B e-commerce platforms targeting veterinary clinics and dental practices with small-batch wet wipe canister formats. Penetrate Indian tier-2 and tier-3 cities through CDSCO-registered liquid solution formulations. Focus initial positioning on residue-compliant peracetic acid blends for EU Green Deal sustainability criteria. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale hydrogen peroxide blenders lacking service-integration capabilities but holding ECHA BPR authorization assets. Five-to-ten year viability hinges on green chemistry transition completion. Watch ECHA REACH restriction finalization on quaternary ammonium compound residues as inflection signal for chemistry portfolio repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive anthraquinone supply secures margin control against Chinese feedstock volatility. |
| ECHA BPR Authorization Investment | Cross-border European market access requires 18-36 month regulatory pathway completion. |
| Digital Procurement Platform Launch | Real-time consumption tracking meets GPO transparency demands in Texas and California. |
| Green Chemistry Formulation Pivot | Peracetic acid and hydrogen peroxide blends unlock EU Green Deal preferential positioning. |
| India CDSCO Registration Expansion | Ayushman Bharat facility construction opens tier-2 and tier-3 city procurement channels. |
Methodological Framework
Bottom-up healthcare facility modeling reconciled against top-down chemical manufacturing tracking forms the analytical core of this study. Primary interviews with infection prevention officers, hospital procurement managers, GPO contracts specialists, and ECHA regulatory consultants combined with secondary validation from EPA registration databases, ECHA biocidal product records, customs trade data, and SEC 10-K filings. Triangulation across formulation chemist expertise clusters and automated dispensing system installations anchored supply-side verification.
Historical trendline analysis of hydrogen peroxide displacement velocity in academic medical centers informed projection framework construction. Segmentation dimensions span product type, application environment, formulation chemistry, and packaging format across the analysis window. CAGR derivation incorporated chemistry transition timelines, regulatory authorization delays, and procurement cycle compression patterns. Feedstock concentration indices and GPO contract unbundling rates served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA REACH restriction acceleration or electrolyzed water technology breakthrough conditions. Deviation in EPA toxicity threshold revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Cosmetic Grade Preservative Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Calcium Peroxide Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market