
 South Africa Cleaning Products Market | 2026-2036
South Africa Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Cleaning Products Market Analytics
Sodium hypochlorite is hardening its position against quaternary ammonium compounds in institutional disinfectant formulations due to cost efficiency and broader pathogen efficacy. Procter & Gamble leverages its manufacturing scale to dominate mass-market laundry detergent supply chains across South African retail. Unilever anchors its portfolio through concentrated liquid formats that reduce plastic intensity per wash cycle. Tiger Consumer Products competes aggressively in township economies through smaller pack sizes distributed via informal trade channels.
South Africa cleaning products encompass formulated chemical solutions designed for soil removal, microbial inactivation, or odor control on surfaces, textiles, or ambient air, typically containing surfactant systems at 5-20% active concentration alongside builders, solvents, and antimicrobial actives. Their primary purpose spans hygiene maintenance in domestic households, commercial facilities, and industrial process equipment. Surface cleaners occupy the largest revenue pool within product type segmentation, though disinfectants command premium pricing in healthcare and food processing applications. Pouch packaging is gaining fastest traction among distribution channels serving price-sensitive residential end users, while bulk containers sustain margin structures for industrial and commercial contracts.
South Africa's National Regulator for Compulsory Specifications administers SANS 1828 for chemical household products, while the Department of Health enforces infection control protocols in healthcare settings that specify minimum biocidal efficacy. These frameworks elevate compliance costs for imported formulations while creating preferential market access for locally tested and certified products. Stakeholders must monitor pending amendments to hazardous chemical classification rules and assess whether reformulation investments or supply chain restructuring delivers superior returns under tightened regulatory enforcement.
Market Dynamics
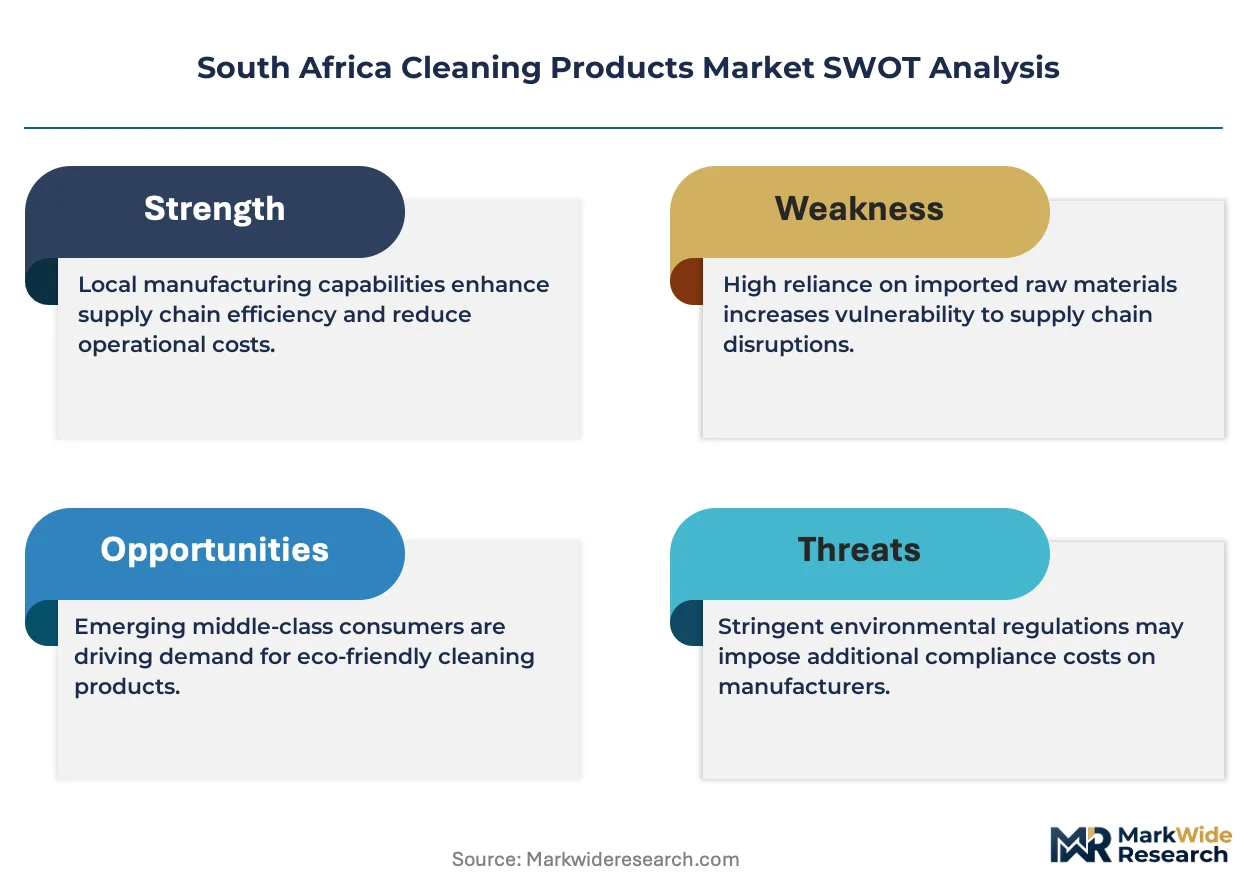
South Africa's cleaning products sector is being restructured by the National Regulator for Compulsory Specifications' tightening enforcement of SANS 1828 chemical safety standards, which forces reformulation investments and favors local certification holders over importers.
Growth Catalysts
- Healthcare procurement mandates:Hospital-grade disinfectant volumes are rising as the Department of Health expands infection control protocols across public and private facilities.
- Sodium hypochlorite cost advantage:The chemical's broader pathogen efficacy and lower per-liter cost versus quaternary ammonium compounds is accelerating adoption in institutional cleaning contracts.
- Gauteng commercial density:Johannesburg and Pretoria anchor concentrated demand for industrial and commercial cleaning services, creating scale economies for service providers.
Market Restraints
- Petrochemical input volatility:Surfactant feedstock costs fluctuate with rand-dollar exchange rates and global oleochemical pricing, compressing margin predictability for formulators.
- Import dependency for specialty actives:Concentrated sourcing of biocidal intermediates from European and Asian suppliers exposes local blenders to shipping cost spikes and currency risk.
- SANS 1828 compliance friction:The certification timeline and testing costs create barriers for new entrants and delay product launches for reformulated lines.
Strategic Opportunities
- Pouch packaging penetration:Flexible sachet formats are capturing price-sensitive residential segments in township economies through informal trade channels.
- Concentrated liquid formats:Reduced plastic intensity per wash cycle aligns with retailer sustainability mandates and lowers logistics costs for mass-market distribution.
- Industrial bulk contracts:Mining and food processing facilities in the Western Cape and KwaZulu-Natal present underpenetrated demand for certified sanitation chemicals.
Industry Challenges
- Biocidal efficacy testing capacity:Limited local laboratory infrastructure for SANS 1828 compliance verification extends time-to-market for new disinfectant registrations.
- Informal trade distribution complexity:Fragmented spaza shop and street vendor networks require specialized logistics and credit risk management capabilities that formal retailers do not.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Cleaning Products Market |
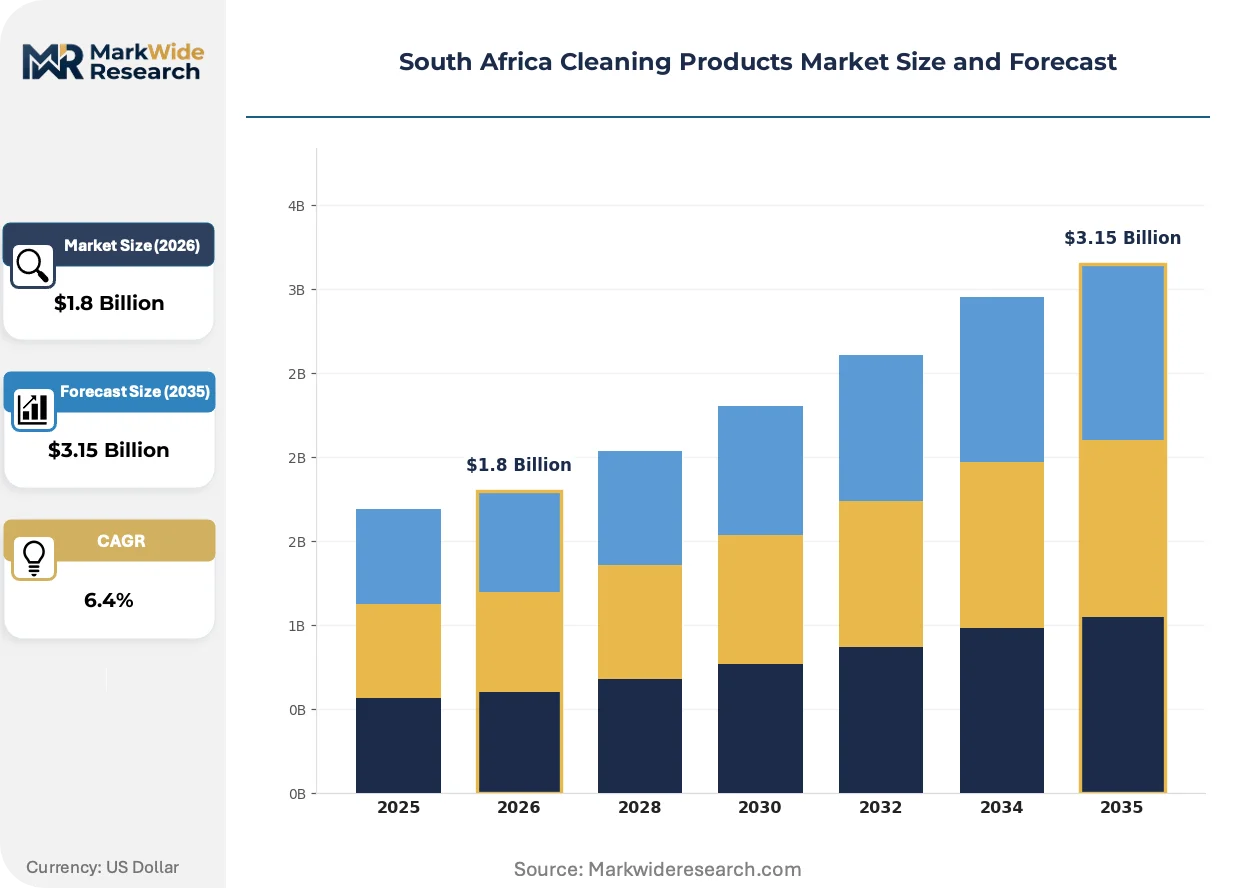
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Cleaners, Disinfectants, Laundry Detergents, Air Fresheners End User: Residential, Commercial, Industrial, Healthcare Packaging Type: Bottles, Canisters, Pouches, Bulk Containers Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Unilever, Procter & Gamble, Reckitt Benckiser, Henkel, Tiger Consumer Products, Libstar, S C Johnson, Ecolab, Diversey, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Cleaning Products Market Evolving Landscape
Formulation chemistry and packaging formats are converging around cost reduction and regulatory compliance, with three distinct vectors reshaping competitive positioning in the South African market.
Sodium hypochlorite-based disinfectant technology is consolidating its position in institutional formulations. Municipal healthcare facilities and food processing plants are accelerating procurement of these solutions. The shift is compressing market share for quaternary ammonium compound alternatives that carry higher active ingredient costs.
SANS 1828 enforcement by the National Regulator for Compulsory Specifications is tightening chemical classification requirements for household products. Local manufacturers must submit reformulated lines for retesting and certification renewal. Healthcare and institutional segments are responding by qualifying multiple approved suppliers to ensure continuity.
Smaller pack sizes distributed through informal channels are capturing residential demand in township economies. Traditional supermarket and hypermarket formats are losing volume to spaza shops and mobile vendors. Gauteng province exhibits the most pronounced channel fragmentation, with Johannesburg's peripheral settlements driving sachet and single-dose format adoption.
South Africa Cleaning Products Market Segmentation
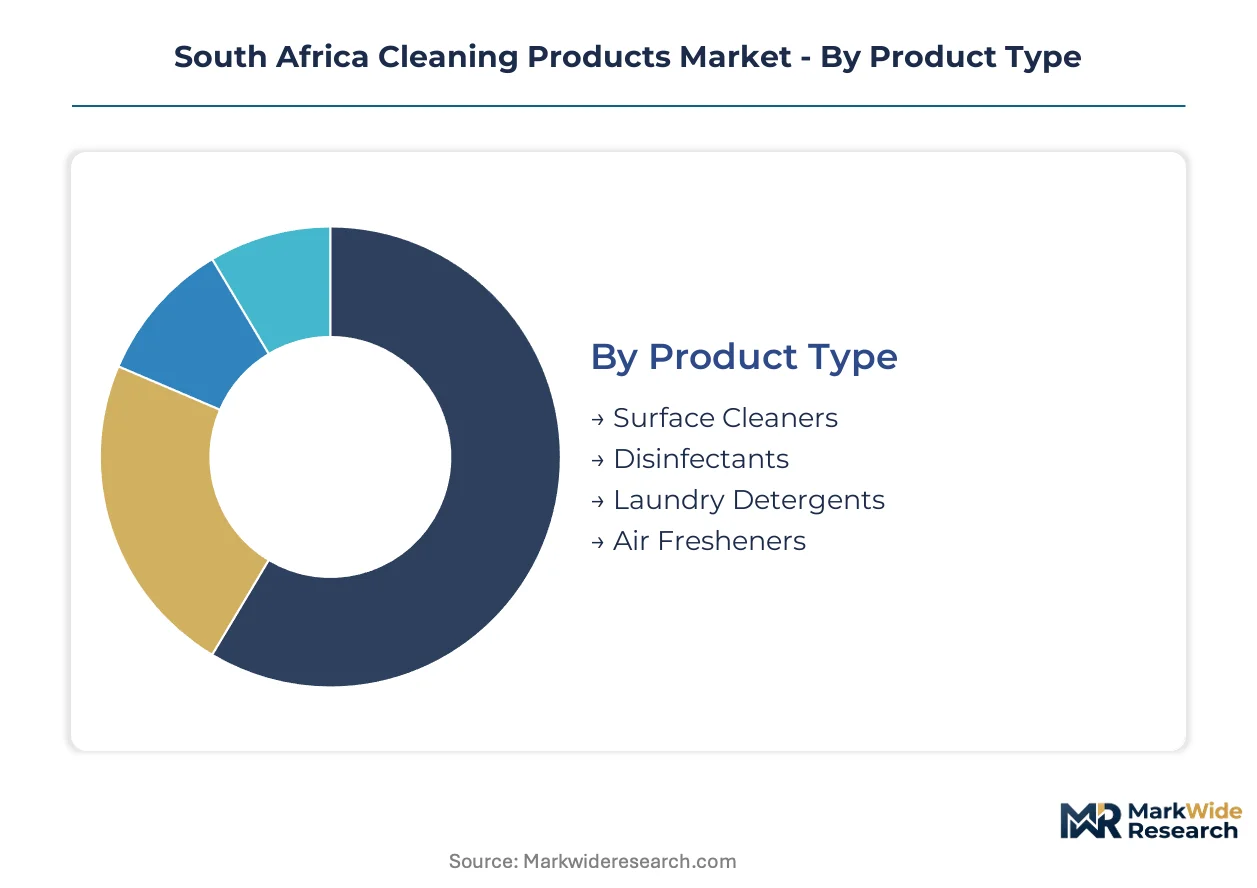
Segmentation in South Africa's cleaning products market exposes divergent margin structures and channel strategies across buyer categories. Procurement specifications vary sharply between healthcare facilities enforcing biocidal efficacy standards and township households prioritizing unit affordability.
Product Type:
Buyers select formulations based on surface compatibility requirements and pathogen neutralization mandates rather than brand loyalty alone.
- Surface Cleaners:Formulations containing 5-20% surfactant systems address soil removal across hard surfaces in domestic and commercial settings. Gauteng province drives the largest volume concentration, with Johannesburg's commercial property sector sustaining bulk procurement contracts. The National Regulator for Compulsory Specifications' SANS 1828 enforcement elevates compliance costs for imported formulations, favoring locally certified manufacturers.
- Disinfectants:Hospital-grade solutions with sodium hypochlorite or quaternary ammonium compounds achieve microbial inactivation for healthcare and food processing applications. The Department of Health's expanding infection control protocols are accelerating procurement volumes across public and private facilities, though biocidal efficacy testing capacity constraints extend registration timelines.
- Laundry Detergents:Concentrated liquid formats with reduced plastic intensity per wash cycle align with retailer sustainability mandates and lower logistics costs.
- Air Fresheners:Odor control formulations for ambient air maintenance in commercial facilities and residential spaces.
Surface cleaners lead on scale; disinfectants lead on momentum.
End User:
Application environment dictates formulation specification, with healthcare and industrial segments commanding premium pricing against mass-market residential supply.
- Residential:Household procurement concentrates in Gauteng's urban centers and Western Cape metropolitan areas, with township economies driving sachet and single-dose format adoption through informal trade channels. Price sensitivity shapes purchasing toward smaller pack sizes distributed via spaza shops.
- Commercial:Office complexes, retail facilities, and hospitality operations in Johannesburg and Pretoria anchor concentrated demand for industrial and commercial cleaning services. Service providers achieve scale economies through concentrated geographic coverage.
- Industrial:Mining and food processing facilities in the Western Cape and KwaZulu-Natal present specialized demand for certified sanitation chemicals. Bulk container procurement sustains margin structures for formulators able to meet sector-specific efficacy requirements.
- Healthcare:Hospital-grade disinfectant volumes are expanding as the Department of Health extends infection control protocols across public and private facilities. Procurement mandates favor suppliers with verified SANS 1828 certification and established local testing relationships.
Residential commands absolute volume; healthcare demonstrates steepest expansion trajectory.
Packaging Type:
Logistics cost and retail channel compatibility determine format selection, with flexible packaging gaining traction in price-sensitive segments.
- Bottles:Rigid polyethylene terephthalate or high-density polyethylene containers dominate supermarket and hypermarket shelf presence for liquid formulations. Standard sizing accommodates automated filling lines and established retail distribution infrastructure.
- Canisters:Pressurized metal containers for aerosolized products including air fresheners and specialty surface treatments.
- Pouches:Flexible sachet formats are capturing price-sensitive residential segments in township economies through informal trade channels. Reduced material cost per unit and lower shipping weight improve margin structures for manufacturers targeting mass-market penetration.
- Bulk Containers:Industrial-scale packaging sustains margin structures for mining, food processing, and commercial service contracts requiring high-volume chemical supply.
Bottles retain channel dominance; pouches climb the fastest.
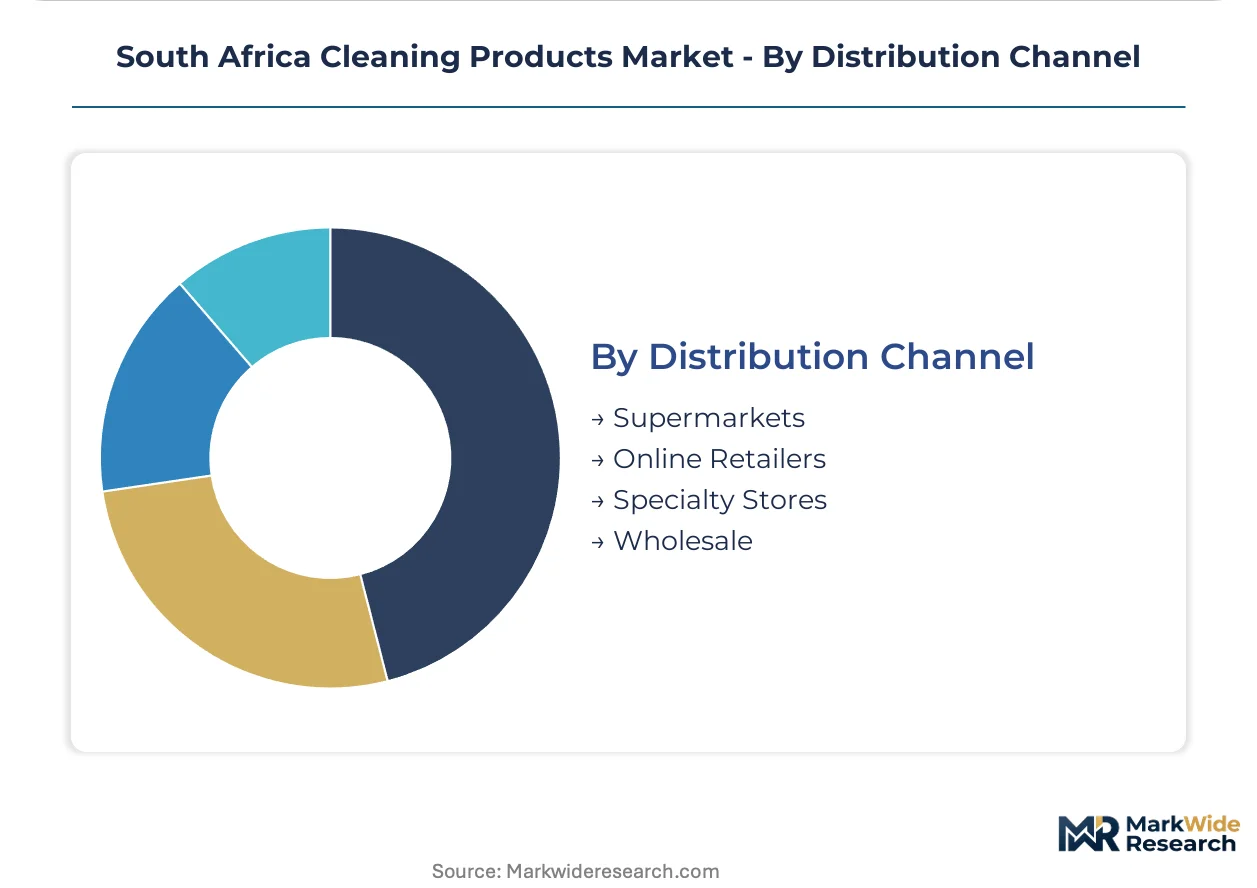
Distribution Channel:
Channel selection reflects buyer location, purchase frequency, and credit availability, with informal networks requiring specialized logistics capabilities.
- Supermarkets:Formal retail chains including Shoprite, Pick n Pay, and Spar anchor mass-market supply for branded household formulations. Concentrated liquid formats and sustainability-aligned packaging secure preferential shelf positioning.
- Online Retailers:E-commerce platforms are expanding reach for concentrated and bulk formats where shipping economics permit, though last-mile cost constraints limit penetration in peripheral settlements.
- Specialty Stores:Dedicated cleaning supply retailers serve commercial and industrial buyers requiring technical specification support and bulk procurement terms.
- Wholesale:Distributor networks supply spaza shops, street vendors, and commercial service providers, requiring specialized credit risk management and fragmented logistics capabilities distinct from formal retail.
Supermarkets maintain volume leadership; wholesale networks gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province anchors South African demand for cleaning products, with Johannesburg and Pretoria sustaining concentrated procurement from commercial property managers, healthcare facilities, and industrial service providers.
Western Cape
Food processing plants and mining operations in the Western Cape drive specialized demand for certified sanitation chemicals. The Department of Health enforces infection control protocols that specify minimum biocidal efficacy for hospital-grade disinfectants used in Cape Town's public health facilities. Bulk container procurement sustains margin structures for formulators serving the Saldanha Bay industrial corridor.
KwaZulu-Natal
Manufacturing and logistics hubs in Durban and Richards Bay generate industrial cleaning contracts requiring high-volume chemical supply. The National Regulator for Compulsory Specifications administers SANS 1828 certification for household products distributed through KwaZulu-Natal's wholesale networks. Pouch packaging formats penetrate price-sensitive residential segments in Durban's peripheral settlements via informal trade channels.
Eastern Cape
Healthcare facility expansion in Gqeberha and East London accelerates procurement of hospital-grade disinfectants. Provincial health departments align procurement with Department of Health infection control mandates that favor suppliers with verified local testing relationships. Industrial bulk contracts remain underpenetrated relative to Gauteng and Western Cape benchmarks.
Mpumalanga
Mining operations in the Witbank and Middelburg corridors present specialized demand for heavy-duty surface cleaners and degreasers. The National Regulator for Compulsory Specifications' SANS 1828 enforcement elevates compliance costs for imported formulations, favoring locally certified manufacturers. Concentrated liquid formats reduce logistics costs for mass-market distribution to mining town residential communities.
South Africa Cleaning Products Market Competitive Landscape
Portfolio diversification dominates the current landscape as multinational and local manufacturers reposition around regulatory compliance and channel fragmentation. The market exhibits tiered concentration, with global consumer goods conglomerates controlling mass-market retail shelf space while regional specialists capture informal trade volumes. Three archetypes define competitive positioning: multinational scale players with manufacturing depth, mid-cap local blenders with SANS 1828 certification advantages, and township-focused distributors with spaza shop penetration. M&A activity and concentrated liquid format launches represent the dominant competitive moves reshaping supply relationships.
Within the multinational tier, Unilever and Procter & Gamble exemplify scale-driven positioning through manufacturing infrastructure and retail distribution dominance. Tiger Consumer Products occupies a distinct archetype as a local specialist competing aggressively in township economies through smaller pack sizes and informal channel relationships. These three anchors demonstrate how competitive advantage separates along certification compliance, manufacturing scale, and channel access vectors rather than product differentiation alone.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| Reckitt Benckiser |
| Henkel |
| Tiger Consumer Products |
| Libstar |
| S C Johnson |
| Ecolab |
| Diversey |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap blenders with multi-generational Gauteng manufacturing footprints anchor supply discipline through conservative working capital management and selective raw material hedging, translating rand volatility into predictable contract pricing for institutional buyers.
Pricing Analysis
Petrochemical input pass-through from global oleochemical markets compresses margin predictability for South African formulators, with surfactant feedstock costs fluctuating alongside rand-dollar exchange rates. Three-tier pricing structure across premium, standard, and economy levels separates SANS 1828-certified institutional grades from mass-market retail formats and informal trade sachets. Pricing pressure stems from import dependency for specialty biocidal intermediates sourced from European and Asian suppliers. Township households exhibit highest price sensitivity, driving single-dose pouch adoption, while healthcare facilities prioritize verified efficacy over unit cost.
Supply Chain Analysis
Skilled chemical compounding labor availability concentrates in Gauteng's industrial corridors around Johannesburg and Pretoria, with secondary blending capacity emerging in KwaZulu-Natal's Durban chemical hub. Sodium hypochlorite and quaternary ammonium compound actives draw from concentrated Asian and European import channels. Single-source vulnerability for certified biocidal intermediates exposes local blenders to shipping cost spikes and extended SANS 1828 retesting timelines. Distribution runs through formal retail chains for branded household formulations, while specialized wholesale networks with credit risk capabilities serve spaza shops and commercial service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's cleaning products sector functions as a geographic-arbitrage play where SANS 1828 certification costs create preferential access for local manufacturers against import-dependent competitors facing extended compliance timelines.
For Market Incumbents: Anchor manufacturing scale through backward integration into surfactant feedstock production or captive sodium hypochlorite generation, reducing rand-dollar exposure. Defend against Tiger Consumer Products' township penetration by deploying dedicated informal trade distribution units with localized credit terms, while accelerating concentrated liquid format launches to meet retailer sustainability mandates. For New Entrants and Emerging Players: Capture underpenetrated industrial bulk contracts in Western Cape food processing and KwaZulu-Natal mining corridors where incumbent service coverage remains thin. Prioritize SANS 1828 certification investment ahead of product launch to bypass the 12-18 month registration barriers that disadvantage import-dependent competitors. Deploy technical sales teams with sector-specific sanitation expertise rather than competing on consumer brand building. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap local blenders with established SANS 1828 certification and existing hospital procurement relationships, as multinational conglomerates trade at retail distribution premiums. Long-term viability hinges on regulatory enforcement continuity and healthcare facility expansion trajectories. Watch for National Regulator for Compulsory Specifications amendments to hazardous chemical classification rules as the signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstock | Reduces rand-dollar volatility exposure for Gauteng-based formulators serving institutional contracts. |
| SANS 1828 Certification Acceleration | Creates preferential market access against import-dependent competitors facing extended testing timelines. |
| Pouch Packaging Format Expansion | Captures price-sensitive residential demand in Johannesburg and Pretoria township economies through informal channels. |
| Industrial Bulk Contract Penetration | Targets underpenetrated mining and food processing facilities in Western Cape and KwaZulu-Natal. |
| Concentrated Liquid Format Launch | Aligns with Shoprite and Pick n Pay sustainability mandates while reducing logistics cost per wash cycle. |
Research Methodology
Direct dialogue with plant managers at Gauteng and KwaZulu-Natal blending facilities, procurement leads at Johannesburg hospital groups, category buyers at Shoprite and Pick n Pay, and distribution channel partners supplying spaza shop networks grounded qualitative findings. Secondary validation drew from South African Bureau of Standards certification records, customs import data for surfactant feedstocks, Department of Health infection control protocol disclosures, and retail audit data from formal trade channels. Bottom-up volume modeling across product type, end user, packaging format, and distribution channel segments was triangulated against top-down macroeconomic indicators.
Bottom-up demand modeling tracked procurement volumes across healthcare, industrial, commercial, and residential end users, with segmentation by formulation chemistry and packaging format. Top-down validation referenced household consumption expenditure patterns and institutional facility expansion pipelines. CAGRs were derived from regression analysis of historical volume trajectories and projected healthcare procurement mandate expansion. Industry-specific forecast inputs included SANS 1828 certification timeline assumptions and informal trade channel penetration rates in Gauteng peripheral settlements.
Regulatory enforcement intensity shifts, rand-dollar exchange rate volatility, and informal trade credit default rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding National Regulator for Compulsory Specifications amendment timing and healthcare facility capital expenditure continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Europe Mastic Remover Market