
 Low-VOC Cleaning Chemicals for Enclosed Workspaces Market | 2026-2036
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market Size, Share, and Industry Trends Forecast 2026-2036
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market Insights
Green Seal GS-37 and EPA Safer Choice certification tiers is rotating toward the center of procurement specifications for enclosed workspace cleaning. Ecolab leverages its institutional channel depth to sustain contract renewals across Fortune 500 headquarters. Diversey anchors its position through enzyme-based formulation specialization for healthcare-adjacent office environments. SC Johnson Professional competes on brand recognition among facility management firms operating multi-site corporate portfolios.
Low-VOC cleaning chemicals for enclosed workspaces are formulated to emit less than 0.4% volatile organic compounds by weight, utilizing water-based or solvent-free carrier systems with surfactant packages that maintain efficacy at reduced vapor pressure. These formulations serve the primary purpose of maintaining indoor air quality compliance while delivering microbial control in mechanically ventilated buildings where pollutant dilution capacity is constrained. All-purpose cleaners and disinfectants together represent the largest volume segment, though nano-enhanced formulation technology is capturing disproportionate margin expansion as building operators seek residue-minimizing solutions. Application demand from data centers and laboratories is outpacing broader office building growth due to stringent contamination control protocols and 24/7 occupancy patterns that amplify indoor air quality sensitivity.
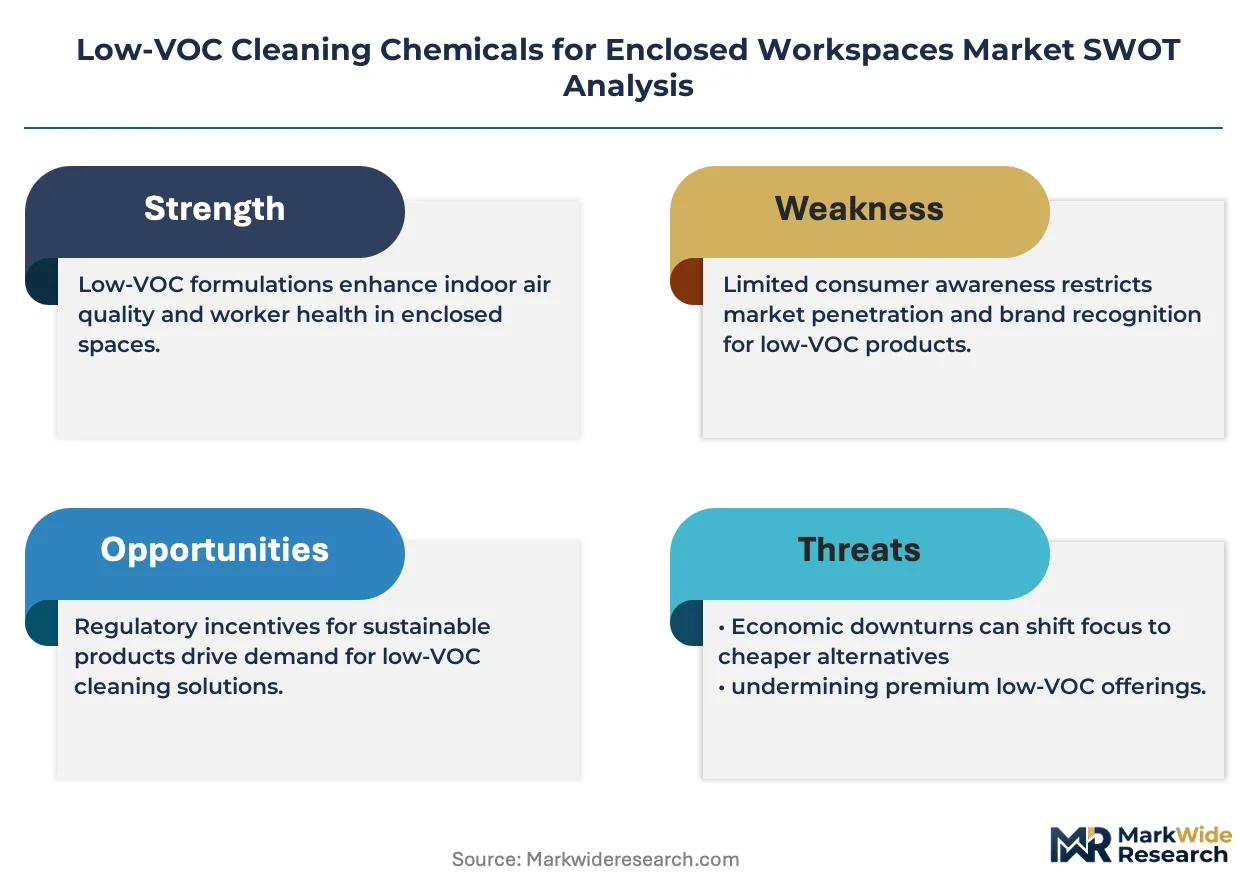
EPA Safer Choice labeling requirements and LEED v4.1 low-emitting materials credits are reshaping product qualification pathways for manufacturers seeking access to federal and premium commercial contracts. OSHA indoor air quality guidelines and state-level California Air Resources Board (CARB) consumer product regulations further compress permissible emission thresholds, effectively disqualifying legacy solvent-based formulations from institutional procurement lists. Facility managers and chemical formulators must monitor evolving state adoption of CARB-equivalent standards to anticipate qualification barriers before they propagate across additional jurisdictions.
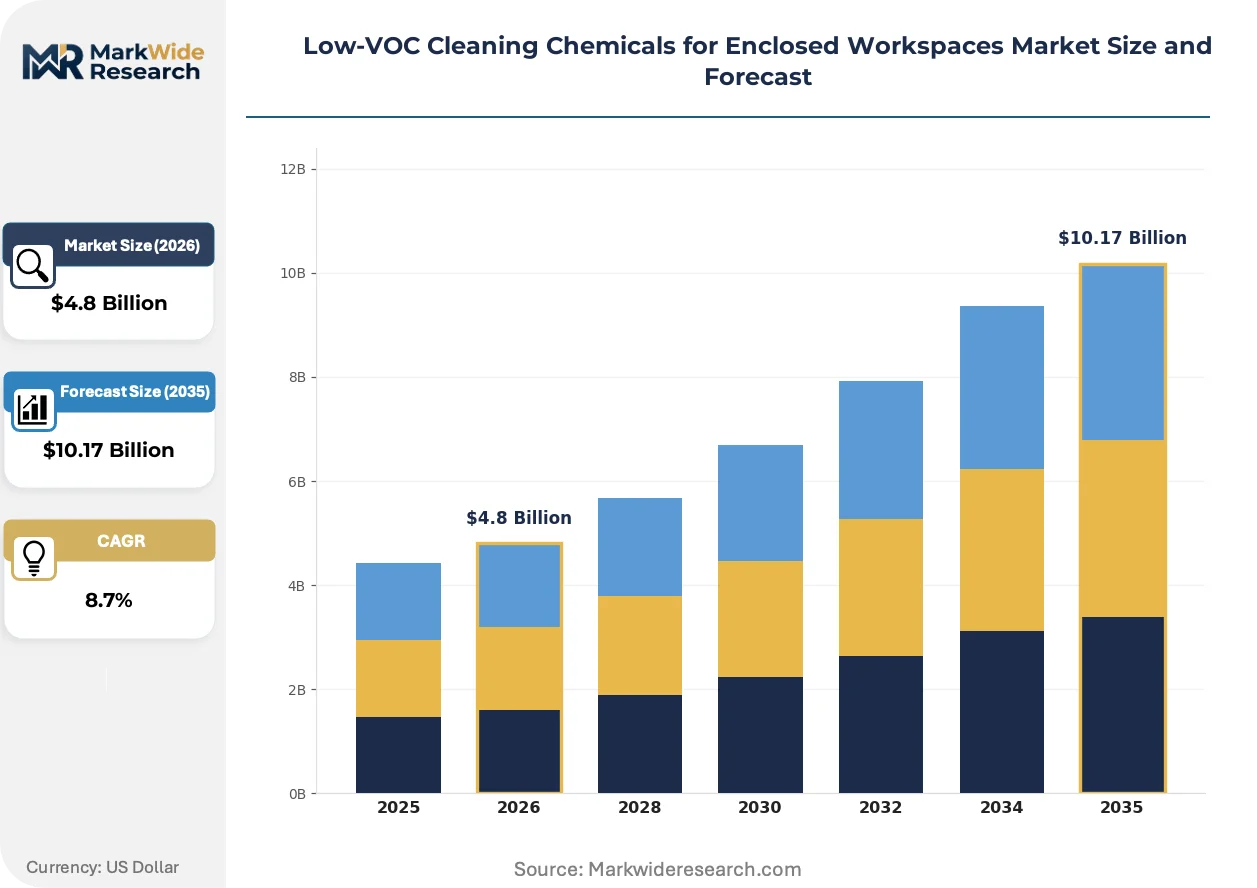
Market Dynamics
LEED v4.1 indoor air quality credits and EPA Safer Choice certification requirements are compressing permissible VOC thresholds, forcing reformulation investments across institutional chemical suppliers serving mechanically ventilated buildings.
Growth Catalysts
- LEED v4.1 Low-Emitting Materials Credits:Building operators pursuing certification must document compliant cleaning products, creating mandatory procurement filters for facility management contracts in premium office segments.
- Data center contamination protocols:24/7 occupancy patterns in hyperscale facilities amplify indoor air quality sensitivity, accelerating specification of residue-minimizing nano-enhanced formulations.
- California Air Resources Board standards:CARB consumer product regulations are propagating to additional state jurisdictions, expanding addressable markets for pre-qualified low-emission formulations.
Market Restraints
- Surfactant input volatility:Bio-based surfactant feedstocks face agricultural commodity price swings, compressing margin stability for water-based formulation specialists.
- Enzyme supply concentration:Protease and lipase production clusters in Denmark and the Netherlands create geographic concentration risk for enzyme-dependent disinfectant manufacturers.
- Legacy solvent substitution costs:Facilities with existing dispensing infrastructure face capital friction retrofitting for dilution-controlled low-VOC systems.
Strategic Opportunities
- Laboratory-adjacent office environments:Research park complexes in Massachusetts and North Carolina represent underpenetrated demand for healthcare-grade contamination control.
- Electrostatic application convergence:Integration of low-VOC chemistries with electrostatic sprayer systems opens disinfection service contracts in high-occupancy transit-oriented developments.
- Federal procurement mandates:EPA Safer Choice requirements in General Services Administration contracts create preferential access pathways for certified suppliers.
Industry Challenges
- Green Seal GS-37 certification timelines:Third-party validation cycles extend 8-14 months, delaying product launch windows for reformulated disinfectants.
- Legacy dispensing system incompatibility:Concentrate dilution ratios in new formulations require recalibration of installed equipment across multi-site corporate portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-VOC Cleaning Chemicals for Enclosed Workspaces Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Cleaners, Floor Cleaners, Disinfectants, All-Purpose Cleaners, Degreasers Formulation Technology: Water-Based, Solvent-Free, Enzyme-Based, Biodegradable, Nano-Enhanced Application Use Case: Office Buildings, Data Centers, Laboratories, Educational Facilities, Government Offices End User Segment: Facility Management Firms, Commercial Cleaners, Industrial Hygiene Providers, Institutional Service Providers |
| Companies Covered | Ecolab, Diversey, SC Johnson Professional, 3M, Reckitt, Procter & Gamble, Unilever, The Clorox Company, Zep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market Trends and Innovations
Nano-enhanced carrier systems and enzyme-stabilized formulations are displacing conventional quat-based disinfectants in premium building segments, while procurement platforms increasingly embed certification filters as default search parameters.
Peracetic acid-hydrogen peroxide blends are decomposing into oxygen and water post-application, eliminating residual film accumulation on sensitive electronic equipment. Data center operators in Northern Virginia and Dallas-Fort Worth are specifying these chemistries for white space maintenance. The technology is decomposing legacy solvent-based degreasers from contamination-controlled environments.
EPA Safer Choice Standard for Direct Release Products tightens aquatic toxicity screening thresholds for institutional cleaning formulations. Manufacturers must now submit expanded chronic ecotoxicity data packages to maintain listing status. Healthcare-adjacent office environments in California and New York face the steepest compliance recertification burdens.
Facility management firms are consolidating chemical supplier relationships from fragmented regional vendors to single-source national contracts with certification guarantees. Multi-site corporate portfolios in Chicago and San Francisco are driving this consolidation. The shift concentrates purchasing power with certified suppliers while marginalizing uncertified regional formulators.
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market Segmentation
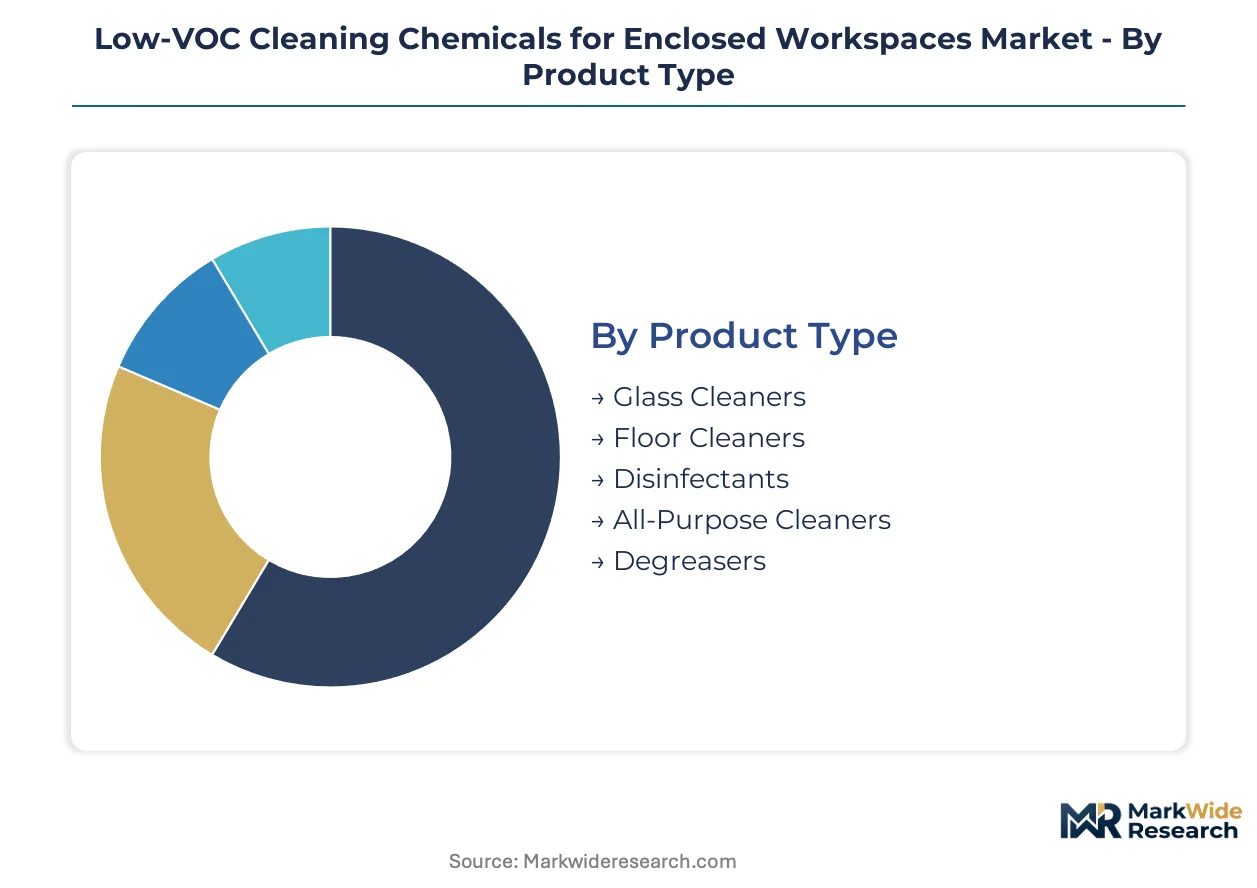
Segmentation in low-VOC cleaning chemicals reveals how certification requirements and building typologies reshape procurement patterns. Product qualification pathways diverge sharply between premium certified tiers and commodity alternatives, while application environments impose distinct contamination control protocols.
Product Type:
Domestic demand concentrates in formulations serving Class A office markets, while export-oriented production targets certification-heavy European and Asia-Pacific procurement specifications.
- All-Purpose Cleaners:Water-based surfactant systems dominate volume, formulated below 0.4% VOC thresholds for LEED v4.1 compliance. Demand clusters in multi-site corporate portfolios across New York and Chicago where facility managers mandate single-source certified supply.
- Disinfectants:Peracetic acid-hydrogen peroxide blends decompose to oxygen and water, eliminating residue on electronic equipment. Data center operators in Northern Virginia and Dallas-Fort Worth specify these chemistries for white space maintenance protocols.
- Glass Cleaners:Ammonia-free formulations with reduced vapor pressure serve mechanically ventilated atriums.
- Floor Cleaners:Enzyme-stabilized formulations address high-traffic commercial lobbies with slip-residue requirements.
- Degreasers:Solvent-free citrus terpene alternatives displace legacy petroleum distillates in kitchen-adjacent office spaces.
All-purpose cleaners hold the largest share; momentum sits with disinfectants.
Formulation Technology:
Cost tier stratification separates premium certified technologies from economy-grade compliant alternatives, with nano-enhanced systems commanding disproportionate margin expansion.
- Nano-Enhanced:Residue-minimizing carrier systems utilize particle-scale surfactant delivery for contamination-sensitive environments. Laboratory complexes in Massachusetts and North Carolina specify these formulations for particulate control alongside air quality compliance.
- Enzyme-Based:Protease and lipase stabilized formulations target organic soil breakdown without quat residue. Healthcare-adjacent office environments in California favor these for combined disinfection and indoor air quality maintenance.
- Water-Based:Surfactant-dominant systems with minimal volatile content serve baseline compliance requirements.
- Solvent-Free:Eliminates hydrocarbon carriers entirely through glycol ether substitution.
- Biodegradable:Aquatic toxicity screening under EPA Safer Choice Direct Release standards drives reformulation investment.
Water-based formulations retain volume leadership; nano-enhanced systems are climbing the fastest.
Application Use Case:
Customer type differentiation separates 24/7 occupancy environments with amplified air quality sensitivity from intermittent-use facilities with standard ventilation constraints.
- Data Centers:Hyperscale facilities require residue-minimizing chemistries compatible with sensitive electronic infrastructure. Northern Virginia and Dallas-Fort Worth clusters specify peracetic acid blends for white space maintenance under continuous occupancy conditions.
- Laboratories:Research park complexes demand healthcare-grade contamination control with particulate and microbial specifications. Massachusetts and North Carolina facilities combine nano-enhanced formulations with electrostatic application systems.
- Office Buildings:Class A properties in New York and San Francisco drive LEED v4.1 procurement mandates.
- Educational Facilities:K-12 and university systems prioritize budget-compliant certified alternatives.
- Government Offices:Federal procurement through General Services Administration contracts requires EPA Safer Choice listing.
Office buildings command current volume; data centers show steepest expansion trajectory.
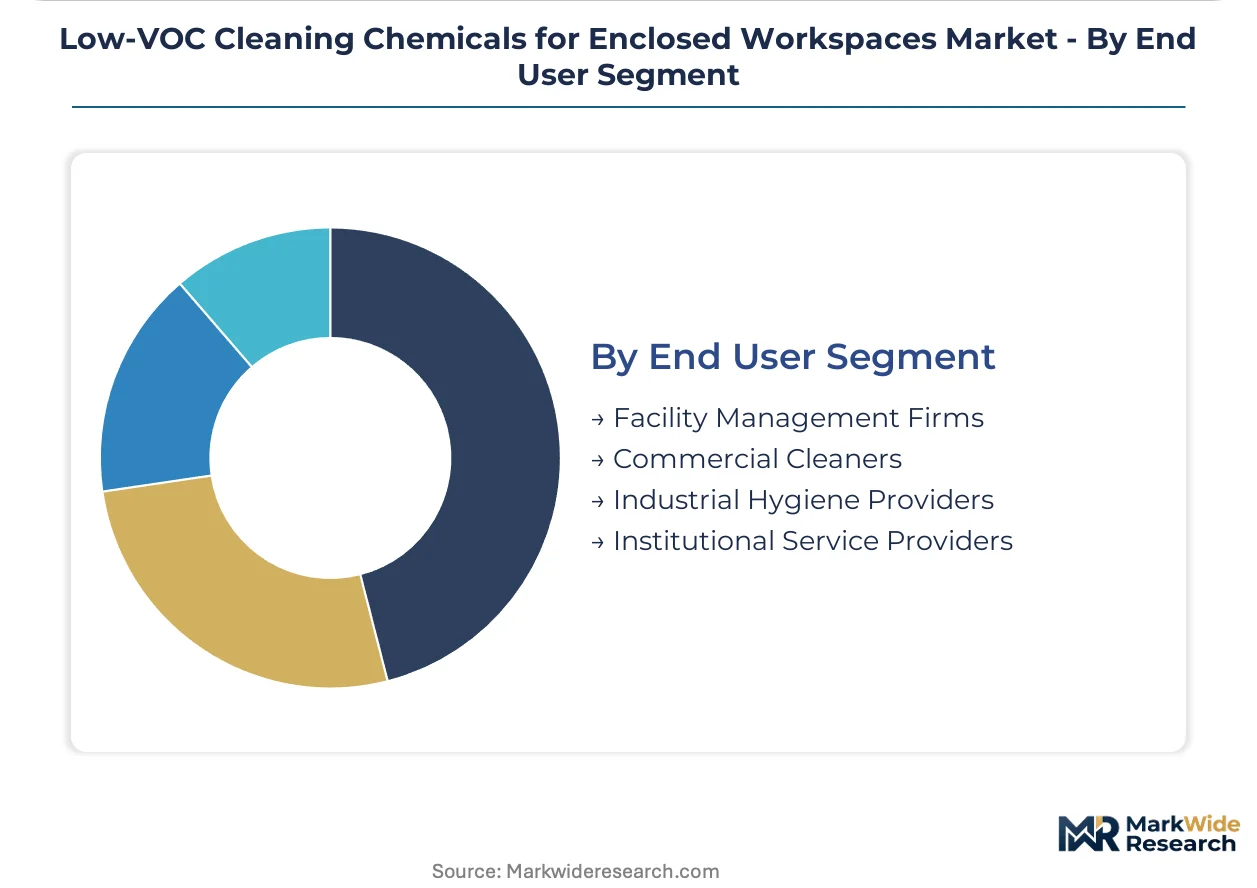
End User Segment:
Supply concentration favors national contract holders with certification guarantees over fragmented regional vendors as purchasing power consolidates.
- Facility Management Firms:Multi-site corporate portfolios in Chicago and San Francisco consolidate supplier relationships from regional fragmentation to single-source national contracts. Certification guarantees embedded in procurement platforms filter qualified vendors automatically.
- Commercial Cleaners:Service contractors compete on electrostatic application integration with low-VOC chemistry for transit-oriented developments.
- Industrial Hygiene Providers:Technical specialists serve contamination-controlled manufacturing-adjacent office environments.
- Institutional Service Providers:Universities and healthcare systems maintain in-house cleaning operations with certified product mandates.
Facility management firms hold the largest share; commercial cleaners are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation specialists cluster in jurisdictions with stringent indoor air quality mandates. Demand concentrates where LEED certification and federal procurement requirements overlap with dense Class A office stock.
United States
Class A office markets in New York, Chicago, and San Francisco drive procurement of EPA Safer Choice certified formulations. General Services Administration contracts mandate low-emitting materials for federal buildings. Northern Virginia data center operators specify peracetic acid blends for 24/7 white space maintenance protocols.
Germany
REACH compliance costs filter out non-certified suppliers from institutional contracts. The country's national chemical regulator enforces strict VOC thresholds in commercial cleaning products. Industrial clusters around Frankfurt and Munich prioritize residue-minimizing nano-enhanced formulations for research park complexes.
China
Dual carbon goals accelerate substitution of solvent-based degreasers in manufacturing-adjacent office environments. The Ministry of Ecology and Environment tightens emission standards for indoor air quality in commercial buildings. Yangtze River Delta facility managers consolidate supplier relationships toward certified national contracts.
Japan
METI efficiency standards push building operators toward dilution-controlled dispensing systems. JIS certification requirements create qualification barriers for imported formulations. Tokyo and Osaka corporate headquarters embed Green Seal GS-37 filters into procurement platform defaults.
United Kingdom
London facility management firms compete on electrostatic application integration with low-VOC chemistries. The country's national chemical regulator aligns with REACH thresholds for commercial cleaning products. Southeast England research parks specify healthcare-grade contamination control for laboratory-adjacent office environments.
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market Competitive Landscape
Concentration sits with diversified chemical conglomerates holding institutional channel depth and certification breadth. National contract consolidation marginalizes regional formulators lacking EPA Safer Choice or Green Seal validation. Three archetypes dominate: certification-heavy institutional suppliers, enzyme-based formulation specialists, and brand-recognized facility management partners. Competitive moves center on single-source national contract capture and electrostatic application system integration.
Within the certification-heavy tier, Ecolab and Diversey occupy positions anchored in Fortune 500 headquarters and healthcare-adjacent environments respectively. SC Johnson Professional sits within the brand-recognized vector serving multi-site facility management portfolios. These three exemplify how channel depth and certification guarantees filter procurement decisions across mechanically ventilated buildings.
| Leading Market Players |
|---|
| Ecolab |
| Diversey |
| SC Johnson Professional |
| 3M |
| Reckitt |
| Procter & Gamble |
| Unilever |
| The Clorox Company |
| Zep |
| Others |
Pricing and Supply Chain Analysis
Long-term national contracts with certification guarantees lock in supply access and price visibility for facility management firms operating multi-site corporate portfolios across the United States. These agreements embed EPA Safer Choice and Green Seal GS-37 compliance as non-negotiable terms, compressing procurement flexibility while stabilizing input costs for qualified suppliers.
Pricing Analysis
EPA Safer Choice and LEED v4.1 low-emitting materials credits dictate the pricing tier structure across the low-VOC cleaning chemicals market. Three-tier pricing structure across premium certified, standard compliant, and economy-grade formulations separates Ecolab and Diversey contract holders from regional commodity suppliers. Price differentiation rests on certification investment depth and enzyme-based formulation complexity rather than raw surfactant content alone. Cost compression in the economy tier is intensifying because agricultural commodity volatility feeds into bio-based feedstock expenses. Educational facilities and municipal procurement offices exhibit the highest price sensitivity, while data center operators in Northern Virginia prioritize residue performance over unit cost.
Supply Chain Analysis
Container availability fluctuations on trans-Pacific trade lanes from Rotterdam and Hamburg into East Coast ports elevate inbound logistics costs for European enzyme imports. Protease and lipase production clusters in Denmark and the Netherlands anchor geographic supply concentration, while surfactant feedstock processing centers on Gulf Coast petrochemical corridors and Brazilian oleochemical operations. Raw material dependencies span palm-derived fatty alcohols, petroleum-based glycol ethers, and specialty stabilizer packages. Single-source vulnerability concentrates in Nordic enzyme manufacturing, where limited alternative suppliers extend lead times for healthcare-adjacent disinfectant formulators. Distribution runs through institutional chemical distributors with dilution-controlled dispensing infrastructure, bypassing retail channels for corporate and federal contract fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified formulation capabilities are scarce relative to procurement mandate expansion, creating a structural gap between qualified supply and LEED-driven demand across mechanically ventilated buildings. This scarcity concentrates contract power with incumbents holding validated Green Seal and EPA Safer Choice portfolios.
For Market Incumbents: Fortify certification breadth by accelerating Green Seal GS-37 recertification timelines for reformulated disinfectants, compressing the 8-14 month validation window that delays product launches. Expand backward integration into bio-based surfactant production to offset agricultural commodity price volatility eroding water-based formulation margins. Channel control through electrostatic application system bundling defends against emerging service contractors competing on disinfection technology integration. For New Entrants and Emerging Players: Lead with laboratory-adjacent office environments in Massachusetts and North Carolina research parks, where healthcare-grade contamination control requirements outpace incumbent coverage. Target federal procurement pathways through General Services Administration contract vehicles, where EPA Safer Choice mandates create preferential access for newly certified suppliers. Electrostatic sprayer chemistry integration offers a differentiated go-to-market angle against established dilution-control infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulation specialists with validated certification tiers and concentrated enzyme supply relationships, positioned for national contract consolidation. Long-term viability across the projection horizon hinges on CARB-equivalent standard adoption propagating beyond California to additional state jurisdictions. Monitor state-level regulatory harmonization as the primary inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Surfactant Production | Captive supply of palm-derived feedstocks insulates margin stability from agricultural commodity swings. |
| Electrostatic Application System Bundling | Service contract capture in transit-oriented developments locks out competitors lacking integrated disinfection technology. |
| Green Seal GS-37 Accelerated Recertification | Compressed validation timelines open premium procurement windows before competitors complete reformulation cycles. |
| Federal GSA Contract Vehicle Entry | EPA Safer Choice mandates in government procurement create preferential access pathways with embedded volume commitments. |
| Enzyme Supply Concentration Diversification | Reduced dependence on Danish and Dutch protease clusters mitigates geographic concentration risk for disinfectant manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from facility management procurement directors, chemical formulator R&D leads, institutional distributor account managers, and LEED consultant technical specialists and refined through secondary validation. Primary fieldwork combined structured interviews with multi-site corporate portfolio managers and healthcare-adjacent building operators with technical consultations on nano-enhanced carrier system specifications. Secondary sources encompassed EPA Safer Choice product listings, Green Seal GS-37 certification databases, CARB consumer product regulation filings, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up demand modeling across building typologies and top-down supply validation through production capacity assessments were triangulated to reconcile volume estimates.
Variance decomposition across the projection horizon isolates regulatory adoption pacing, certification penetration rates, and surfactant feedstock cost trajectories as primary forecast drivers. Segmentation dimensions span formulation technology tier, application use case sensitivity, end-user contract scale, and regional regulatory stringency cluster. CAGRs were derived from installed base growth in mechanically ventilated buildings, replacement cycle acceleration for legacy solvent systems, and premium tier share expansion in data center and laboratory environments. Industry-specific inputs include hyperscale facility construction pipelines in Northern Virginia and Dallas-Fort Worth and LEED v4.1 project registration velocity in Class A office markets.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening and certification mandate expansion would require recalibration. Forecasts reflect assumptions on state-level CARB-equivalent standard propagation and federal procurement requirement continuity. Supply chain disruptions in Nordic enzyme manufacturing or bio-based surfactant feedstock markets would necessitate model adjustment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Instrument Detergents for Manual Cleaning Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market