
 Industrial and Institutional Hand Hygiene Chemicals Market | 2026-2036
Industrial and Institutional Hand Hygiene Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Institutional Hand Hygiene Chemicals Market Foresight
Food processing is expanding as the fastest-growing end-use vertical for industrial hand hygiene chemicals, outpacing traditional hospitality and corporate office segments. Ecolab Inc. leverages its integrated water-hygiene-energy platform to dominate food safety accounts. Diversey Holdings, Ltd. anchors its position through specialized sanitation protocols for protein processing environments. GOJO Industries, Inc. competes on dispenser technology leadership and touch-free system deployment.
Industrial and institutional hand hygiene chemicals comprise surfactant-based formulations, antimicrobial actives such as chlorhexidine and benzalkonium chloride, and alcohol-based sanitizers engineered for high-frequency use in commercial settings; these products typically meet ASTM E1174 testing standards for healthcare handwash efficacy and are manufactured through batch blending processes with controlled pH stabilization to ensure skin compatibility under repeated exposure. Foam soaps command the largest product type volume due to per-use cost efficiency and reduced water consumption, while wipes represent the fastest-growing format as portable compliance solutions gain traction in field-based industries. Healthcare facilities application generates the highest margin pool owing to infection control liability exposure, though food processing application shows the steepest volume trajectory.
FDA Food Code provisions, OSHA workplace sanitation guidelines, and EPA antimicrobial pesticide registration requirements collectively shape formulation standards and market access barriers for manufacturers serving US industrial accounts. The EU Biocidal Products Regulation and REACH chemical safety protocols impose parallel compliance burdens on European suppliers, raising reformulation costs for cross-border players. Stakeholders must monitor evolving state-level green chemistry mandates and healthcare-associated infection reporting thresholds to anticipate procurement specification shifts.
Market Dynamics
FDA Food Code updates and Joint Commission accreditation standards are compressing replacement cycles across food processing and healthcare facilities, forcing simultaneous compliance investments that reshape procurement priorities and supplier selection criteria.
Growth Catalysts
- Regulatory tightening:FDA Food Code provisions mandate enhanced sanitizing protocols in foodservice operations, expanding formulation requirements for antimicrobial actives.
- Healthcare liability exposure:Joint Commission standards in the United States accelerate hospital-grade foam soap deployment to reduce infection control litigation risk.
- Water stress adaptation:Foam soap chemistry reduces per-use water consumption, aligning with municipal conservation mandates in drought-prone regions.
Market Restraints
- Quaternary ammonium compound supply concentration:Benzalkonium chloride production clusters in Chinese chemical manufacturing zones, exposing buyers to shipping disruption risk.
- REACH reformulation burden:EU Biocidal Products Regulation requires costly substance dossier submissions that freeze legacy formulations from cross-border trade.
- Alcohol sanitizer price volatility:Ethanol and isopropanol feedstock costs fluctuate with biofuel policy shifts and energy market swings.
Strategic Opportunities
- Field-based portable compliance:Pre-moistened wipe formats address sanitation gaps in construction, agriculture, and remote food harvesting operations lacking fixed washing infrastructure.
- Green chemistry procurement mandates:State-level preferential purchasing laws in California and New York create first-mover advantage for bio-based surfactant developers.
- Touch-free dispenser retrofit cycles:Sensor-activated systems reduce cross-contamination risk while locking in recurring chemical cartridge revenue streams.
Industry Challenges
- Antimicrobial resistance documentation:EPA registration renewal processes demand expanded efficacy data against emerging pathogen strains, extending approval timelines.
- Skin compatibility testing protocols:Repeated exposure studies for healthcare workers require extended clinical validation that delays new formulation launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Institutional Hand Hygiene Chemicals Market |
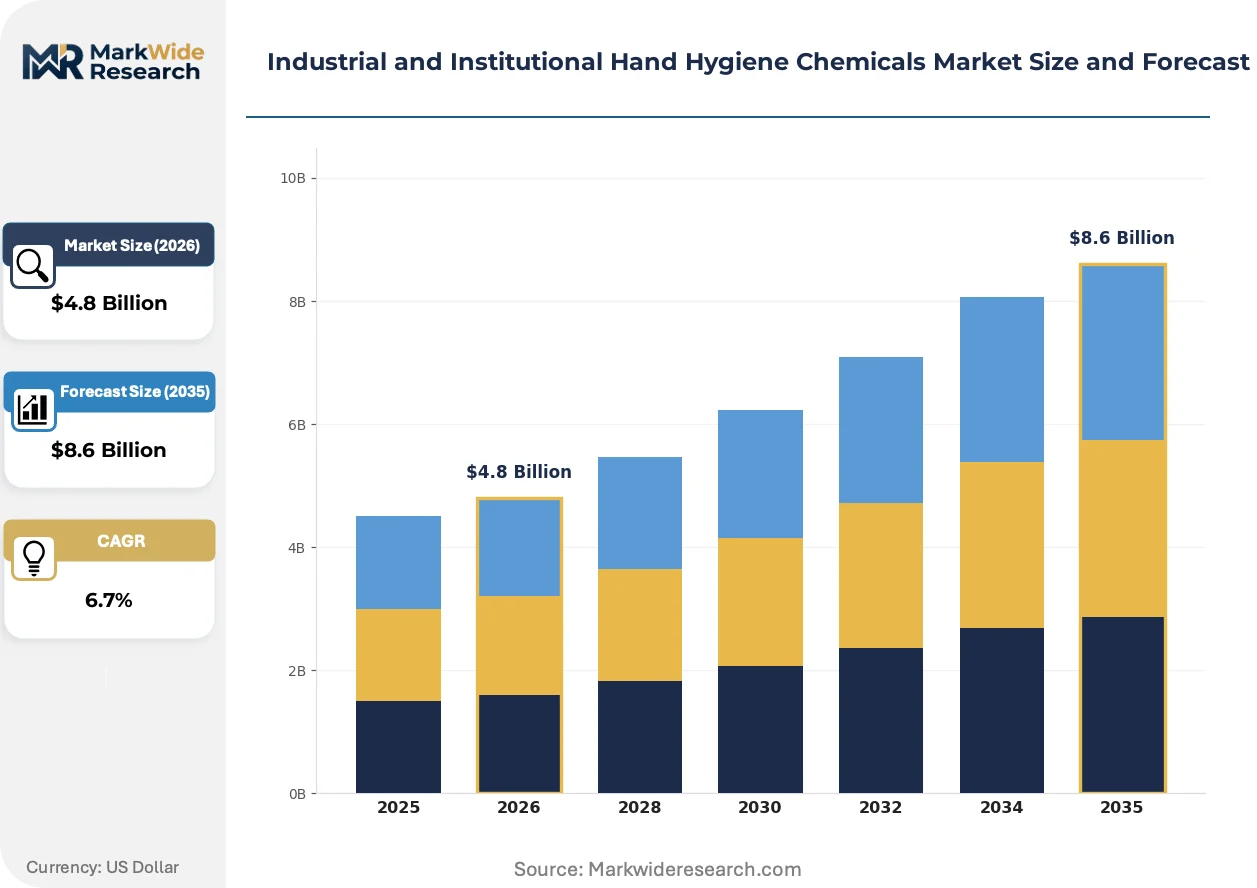
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soaps, Foam Soaps, Gels, Wipes Application: Healthcare Facilities, Food Processing, Education Centers, Hospitality End User: Hospitals, Restaurants, Schools, Corporations Packaging Type: Bottles, Dispensers, Jugs, Bulk Containers |
| Companies Covered | Ecolab Inc., Diversey Holdings, Ltd., GOJO Industries, Inc., SC Johnson Professional, 3M Company, Procter & Gamble Professional, Clorox Professional Products Company, Kimberly-Clark Corporation, Reckitt Benckiser Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Institutional Hand Hygiene Chemicals Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are converging to address simultaneous pressures from water conservation, pathogen resistance, and occupational skin health. These developments are compressing traditional product lifecycles and redrawing competitive boundaries.
Electrolyzed water generation systems are electrifying on-site sanitizer production for food processing plants. Large-scale protein processors in the United States and Germany are installing captive electrolysis units to eliminate bulk chemical transport and storage liability. This distributed manufacturing model is compressing margins for traditional sanitizer blenders while creating service revenue pools for equipment-integrated chemical monitoring.
REACH authorization procedures for biocidal active substances are forcing substance substitutions ahead of sunset dates. European suppliers face reformulation costs that advantage regional players with established ECHA dossier capabilities. Food processing applications show the steepest specification churn as manufacturers preempt compliance deadlines.
Consolidated purchasing through group procurement organizations is displacing decentralized facility-level buying in multi-site healthcare systems. These organizations negotiate multi-year chemical supply contracts bundled with dispenser hardware and compliance auditing services. The United States exhibits the most advanced buyer concentration, with three national GPOs controlling substantial hospital system procurement volume.
Industrial and Institutional Hand Hygiene Chemicals Market Segmentation
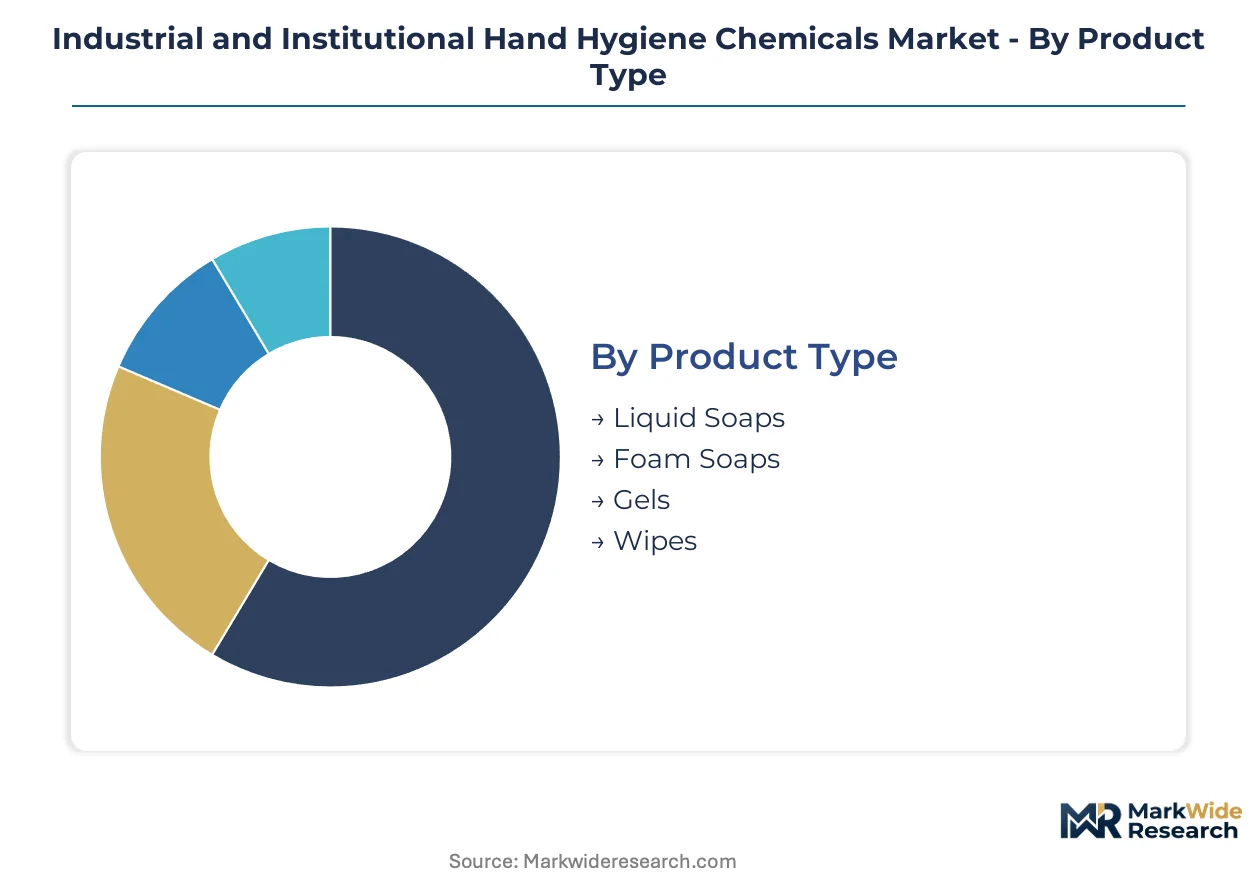
Industrial and institutional hand hygiene chemicals fragment across formulation chemistry, delivery format, and procurement context. Each segmentation axis reveals distinct margin structures and compliance burdens that reshape supplier positioning.
Product Type:
Foam soaps integrate into fixed infrastructure with dispenser-locked cartridges, while wipes travel as standalone portable units for field deployment.
- Liquid Soaps:Surfactant-based formulations with controlled pH stabilization for repeated-use skin compatibility. Demand concentrates in education centers and legacy healthcare facilities where existing dispenser infrastructure resists retrofit costs. ASTM E1174 compliance requirements drive specification rigidity.
- Foam Soaps:Air-entrained chemistry delivering per-use cost efficiency and reduced water consumption. Hospital systems in the United States concentrate procurement here as Joint Commission standards compress replacement cycles. Touch-free dispenser integration locks in recurring cartridge revenue.
- Gels:Viscous alcohol-based formulations for high-frequency sanitizing without water access.
- Wipes:Pre-moistened substrates addressing sanitation gaps in construction, agriculture, and remote food harvesting operations lacking fixed washing infrastructure.
Volume placements concentrate in foam soaps; the faster expansion belongs to wipes.
Application:
Healthcare and food processing sit at opposite ends of the liability spectrum, with infection control litigation exposure driving margin premiums in clinical settings.
- Healthcare Facilities:Hospital-grade formulations meeting EPA antimicrobial pesticide registration and FDA oversight for surgical hand scrubs. The United States concentrates demand as Joint Commission accreditation standards force simultaneous compliance investments across multi-site systems. Liability exposure sustains the highest margin pool.
- Food Processing:Sanitizing protocols for protein processing environments facing FDA Food Code update cycles. Plants are intensifying procurement of antimicrobial actives as compliance requirements tighten. Electrolyzed water generation systems are compressing margins for traditional sanitizer blenders.
- Education Centers:High-volume, low-specification procurement for K-12 and university facilities.
- Hospitality:Guest-facing formulations balancing efficacy with fragrance and skin-feel preferences.
Food processing commands the steepest volume trajectory; healthcare facilities retain the dominant margin position.
End User:
Procurement sophistication separates centralized hospital systems from fragmented restaurant operators, with corporations occupying a hybrid middle ground.
- Hospitals:Consolidated purchasing through group procurement organizations displaces decentralized facility-level buying. Three national GPOs in the United States control substantial system procurement volume, negotiating multi-year contracts bundled with dispenser hardware and compliance auditing services.
- Corporations:Multi-site office portfolios with sustainability mandates driving bio-based surfactant preference. State-level green chemistry procurement laws in California and New York create specification divergence.
- Restaurants:Price-sensitive operators with high staff turnover and variable compliance rigor.
- Schools:Municipal budget cycles and bulk purchasing constraints limit formulation premiumization.
Hospital procurement is concentrating fastest; restaurant volumes remain the largest in absolute terms.
Packaging Type:
Dispenser-integrated formats capture recurring revenue streams while bulk containers serve cost-driven high-volume accounts.
- Dispensers:Sensor-activated touch-free systems reducing cross-contamination risk while locking in proprietary cartridge compatibility. Retrofit cycles across United States healthcare facilities are accelerating replacement demand.
- Bulk Containers:Refill economics for food processing plants and education centers with captive filling infrastructure. REACH reformulation burdens in Europe raise costs for cross-border bulk shipments.
- Bottles:Portable retail-format procurement for small commercial accounts and emergency stockpiling.
- Jugs:Mid-volume containers bridging bulk and individual-use applications.
Dispenser placements are expanding most quickly; bulk containers retain the dominant volume share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for chemical manufacturing in China's eastern coastal provinces concentrate surfactant production capacity. FDA Food Code enforcement in the United States and EU Biocidal Products Regulation compliance in Europe reshape procurement specifications across industrial accounts.
United States
Joint Commission accreditation standards drive hospital-grade foam soap replacement cycles across multi-site healthcare systems. OSHA workplace sanitation guidelines mandate enhanced protocols for foodservice operations. Protein processing clusters in Nebraska and Iowa intensify procurement of antimicrobial sanitizing formulations.
Germany
Electrolyzed water generation systems displace bulk chemical procurement among large-scale food processors. ECHA authorization procedures under REACH force substance substitutions ahead of sunset dates. Industrial chemical manufacturing in North Rhine-Westphalia faces reformulation cost pressures from biocidal active substance reviews.
China
Benzalkonium chloride production clusters in Jiangsu and Zhejiang provinces expose buyers to shipping disruption risk. GB standards for antimicrobial products tighten formulation requirements for export-oriented manufacturers. Yangtze River Delta chemical parks dominate quaternary ammonium compound supply concentration.
India
FSSAI food safety regulations expand sanitizing protocol requirements across commercial food processing. CDSCO oversight of antimicrobial products creates parallel registration burdens for healthcare formulations. Maharashtra and Gujarat industrial corridors attract contract manufacturing investment for institutional hygiene chemicals.
Brazil
ANVISA antimicrobial product registration shapes market access for imported hand hygiene formulations. Food processing expansion in São Paulo and Minas Gerais states drives volume procurement of industrial sanitizers. MERCOSUR trade alignment pressures harmonization with EU biocidal safety protocols.
Industrial and Institutional Hand Hygiene Chemicals Market Competitive Landscape
Top-tier vendors anchor integrated hygiene platforms, while mid-tier specialists compete on formulation customization and regional compliance expertise. The vendor base stratifies across three concentration levels: multinational chemical conglomerates with water-hygiene-energy integration, dedicated institutional hygiene specialists with dispenser-locked cartridge systems, and regional blenders serving price-sensitive bulk accounts. Two strategic archetypes dominate competitive positioning: platform integrators bundling chemical supply with compliance auditing services, and format innovators capturing recurring revenue through proprietary dispenser retrofit cycles. M&A activity concentrates on captive electrolysis equipment manufacturers, while portfolio diversification extends into bio-based surfactant development for green chemistry procurement mandates.
Within the platform integrator tier, Ecolab Inc. and Diversey Holdings, Ltd. exemplify the water-hygiene-energy convergence model for food safety accounts. GOJO Industries, Inc. occupies a position within the format innovation archetype through touch-free dispenser technology deployment. These three entities represent distinct competitive vectors: integrated service bundling, specialized sanitation protocols for protein processing, and sensor-activated system hardware lock-in.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Diversey Holdings, Ltd. |
| GOJO Industries, Inc. |
| SC Johnson Professional |
| 3M Company |
| Procter & Gamble Professional |
| Clorox Professional Products Company |
| Kimberly-Clark Corporation |
| Reckitt Benckiser Group plc |
| Others |
Supply & Pricing Matrix
Benzalkonium chloride feedstock costs cascade through three pricing tiers as the quaternary ammonium compound travels from Jiangsu and Zhejiang manufacturing zones to hospital systems, food processing plants, and price-sensitive education centers. Buyers with locked-in dispenser cartridge contracts absorb premium pricing for guaranteed supply continuity, while spot purchasers in the restaurant segment face volatility from ethanol and isopropanol biofuel policy swings.
Pricing Analysis
Short lead-time premiums separate hospital procurement through group purchasing organizations from bulk container spot markets serving food processing plants. Three-tier pricing structure across dispenser-locked premium, contract standard, and bulk economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from electrolyzed water generation systems displacing traditional sanitizer blenders in protein processing clusters. Restaurant operators exhibit highest price sensitivity due to staff turnover and variable compliance rigor, while hospital systems prioritize liability reduction over unit cost.
Supply Chain Analysis
Workforce availability constraints in China's Yangtze River Delta chemical parks and North Rhine-Westphalia industrial corridors shape surfactant production scheduling. Supply concentrates in Chinese benzalkonium chloride manufacturing zones, German electrolyzed water equipment fabrication, and Indian contract formulation facilities. Raw material dependencies include quaternary ammonium compounds, ethanol feedstocks, and bio-based surfactant precursors. Single-source vulnerability from Chinese chemical park concentration exposes buyers to shipping disruption risk. Distribution runs through group procurement organizations for healthcare, direct plant supply for food processing, and janitorial distribution networks for education and hospitality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzed water generation technology is displacing bulk chemical procurement in food processing, compressing margins for traditional sanitizer blenders while creating service revenue pools for equipment-integrated monitoring platforms.
For Market Incumbents: Deepen backward integration into captive benzalkonium chloride production or electrolyzed water equipment manufacturing to offset margin compression from distributed on-site generation. Lock in recurring revenue through touch-free dispenser retrofit cycles across United States hospital systems facing Joint Commission replacement mandates. Anchor position through specialized sanitation protocols for protein processing environments where FDA Food Code compliance requirements intensify procurement stickiness. For New Entrants and Emerging Players: Direct-to-facility digital procurement platforms offer the lowest-friction entry vector for field-based wipe formats in construction, agriculture, and remote food harvesting operations lacking fixed washing infrastructure. Target portable compliance solutions as the most penetrable segment, where pre-moistened substrates address sanitation gaps without incumbent dispenser infrastructure lock-in. Pursue green chemistry certification as the primary go-to-market angle, leveraging state-level preferential purchasing laws in California and New York to bypass established supplier relationships. For Investors and Strategic Acquirers: REACH authorization sunset date announcements are the leading indicator that European reformulation cost burdens will advantage regional players with established ECHA dossier capabilities. The five-to-ten year viability window favors platform integrators bundling chemical supply with compliance auditing services over standalone formulation blenders. Acquisition target archetype: captive electrolysis equipment manufacturers with installed base in United States and German protein processing clusters. Monitor EPA antimicrobial pesticide registration renewal timelines as the critical inflection signal for formulation approval risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Production | Captive benzalkonium chloride supply insulates against Chinese shipping disruption and feedstock volatility. |
| Electrolyzed Water Equipment Acquisition | On-site generation capability captures service revenue from protein processors in Nebraska and Iowa clusters. |
| Touch-Free Dispenser Retrofit Deployment | Sensor-activated systems lock in recurring cartridge revenue across Joint Commission-driven hospital replacement cycles. |
| Bio-Based Surfactant Certification Investment | Green chemistry compliance opens procurement pathways under California and New York state mandates. |
| Group Procurement Organization Contract Negotiation | Multi-year bundled agreements with dispenser hardware and auditing services displace decentralized facility buying. |
Research Methodology
Document review covered FDA Food Code provisions, EPA antimicrobial pesticide registration databases, and ECHA biocidal substance dossiers, complemented by interviews with plant managers at protein processing facilities, procurement leads at hospital group purchasing organizations, distribution channel partners in janitorial supply, and technical R&D directors at surfactant manufacturers. Secondary validation drew from customs and trade data, SEC filings of listed chemical conglomerates, and American Chemistry Council sector reports. Bottom-up volume builds across formulation types and delivery formats were triangulated against top-down spending estimates from healthcare and food processing end-use verticals.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, delivery format infrastructure requirements, end-use liability exposure level, and regional regulatory cluster. CAGRs were derived from weighted scenario analysis incorporating compliance-driven replacement cycle acceleration and water stress adaptation mandates. Industry-specific forecast inputs encompassed Joint Commission accreditation timeline assumptions and FDA Food Code update implementation schedules.
The model holds under stable regulatory enforcement trajectories and continued group purchasing organization consolidation; deviation in REACH authorization timelines, biofuel policy shifts affecting alcohol feedstock costs, or antimicrobial resistance documentation requirements would shift volume and value trajectories. Material deviation in these named triggers warrants pause and re-evaluation of procurement specification assumptions and supplier positioning strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Drain Opener Chemicals Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Sponge and Scouring Pads Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
South Africa Cleaning Products Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market