
 North America Secondary Packaging Market | 2026-2036
North America Secondary Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Secondary Packaging Market Insights
Corrugated fiberboard is rebalancing product economics across North America as brands replace heavier rigid formats with lightweight, stackable alternatives. International Paper Company leverages its integrated pulp-to-box network across the southeastern United States to sustain cost leadership in high-volume corrugated. WestRock anchors its position through containerboard recycling infrastructure that controls post-consumer fiber flows. Sealed Air Corporation differentiates via automated void-fill and cushioning systems that reduce dimensional weight penalties for parcel carriers.
North America Secondary Packaging encompasses outer enclosures—corrugated cases, paperboard cartons, shrink-wrapped bundles, and palletized loads—that consolidate, protect, and identify primary product units during distribution and retail handling. These structures typically employ 23- to 42-pound basis weight linerboard combined with fluted medium in A, B, C, E, or F profiles to achieve calibrated burst strength and edge crush resistance for warehouse stacking and conveyor transit. Boxes dominate value capture given their indispensability in e-commerce and grocery replenishment, while shrink wrap grows fastest as beverage and personal care brands adopt collation films to replace paperboard multipacks. Digital printing technology expands across short-run corrugated and label segments, enabling versioned graphics without plate changeover costs.
The EPA oversees recycled fiber content guidelines and hazardous material transport packaging standards, while OSHA mandates ergonomic and machine-guarding requirements for high-speed case-packing lines across U.S. plants. California's SB 54 extended producer responsibility framework and emerging state-level plastic packaging taxes reshape material selection timelines for multinationals operating across the region. Stakeholders must monitor pending federal packaging waste legislation and state-by-state policy divergence to calibrate capital allocation between paperboard expansion and film-based formats.
Market Dynamics
California's SB 54 extended producer responsibility framework is forcing multinationals to accelerate fiber-based packaging transitions ahead of compliance deadlines, while e-commerce fulfillment density in the Great Lakes corridor concentrates demand for lightweight corrugated solutions.
Growth Catalysts
- E-commerce fulfillment density:Parcel carrier dimensional weight pricing is pushing retailers toward optimized box sizing and void-reduction engineering across Michigan, Ohio, and Illinois distribution hubs.
- EPA recycled content guidelines:Post-consumer fiber mandates are expanding virgin linerboard substitution in corrugated medium, creating pull-through demand for integrated recycling infrastructure.
- Shrink film collation:Beverage and personal care brands are replacing paperboard multipacks with collation films to reduce material weight and improve pallet cube efficiency.
Market Restraints
- Old corrugated container price volatility:OCC bale pricing fluctuations in the southeastern United States compress margin predictability for independent sheet feeders.
- Containerboard mill concentration:Four integrated producers control the majority of North American kraft linerboard capacity, creating supply vulnerability during planned maintenance cycles.
- Plastic packaging taxes:Emerging state-level levies on non-recycled film content create material selection friction for shrink-wrap-dependent categories.
Strategic Opportunities
- Digital printing convergence:Short-run corrugated and label segments are adopting versioned graphics capabilities without plate changeover costs, enabling regional personalization.
- Canadian provincial EPR expansion:Ontario and British Columbia extended producer responsibility frameworks are creating compliant packaging service demand ahead of federal harmonization.
- Automated void-fill systems:Dimensional weight penalty avoidance is driving adoption of on-demand cushioning equipment in third-party logistics facilities.
Industry Challenges
- Machine-guarding compliance:OSHA mandates for high-speed case-packing lines require capital-intensive retrofitting of legacy equipment across aging U.S. plants.
- Ergonomic injury liability:Manual palletizing operations in the Great Lakes manufacturing corridor face workers compensation pressure and automation upgrade requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Secondary Packaging Market |
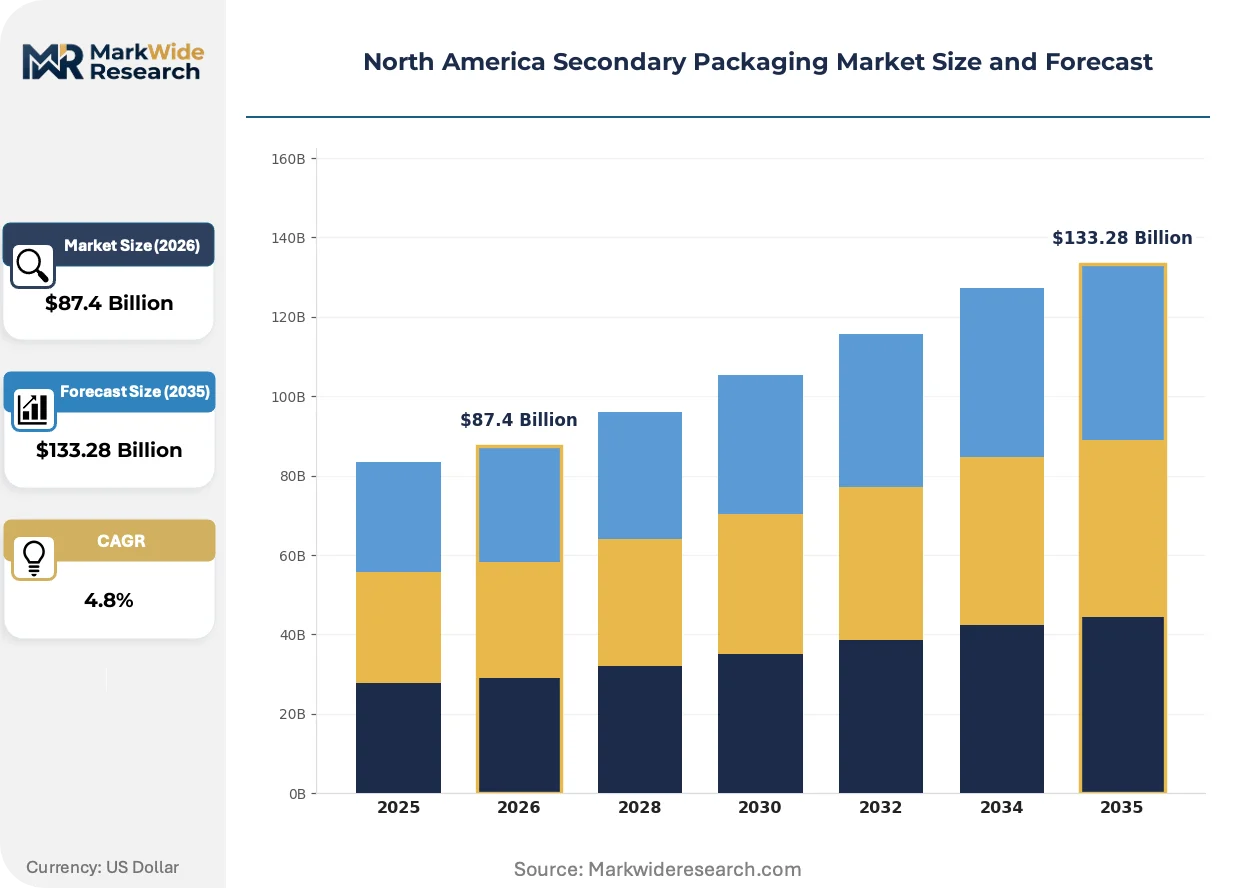
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Shrink Wrap, Labels Material: Paperboard, Plastic, Glass, Metal End User: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Technology: Digital Printing, Flexographic Printing, Rotary Printing, Labeling |
| Companies Covered | Amcor PLC, International Paper Company, WestRock, Ball Corporation, Crown Holdings Inc., Smurfit WestRock, Sealed Air Corporation, Packaging Corporation of America, Graphic Packaging Holding Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Secondary Packaging Market Trends and Innovations
Active reshaping in secondary packaging centers on three vectors: digital production technology eliminating setup waste, regulatory pressure compressing plastic-to-fiber transition timelines, and fulfillment economics forcing dimensional optimization.
Digital printing on corrugated substrates is integrating versioned graphics capabilities directly into e-commerce supply chains. Mass-market retailers and direct-to-consumer brands are adopting short-run production for seasonal and regional campaigns without plate costs. This technology is integrating personalization economics into protective packaging that previously required minimum order quantities of 10,000 units.
California's SB 54 extended producer responsibility framework mandates 25% source reduction and 65% recycling rates by weight by 2032. Multinational consumer goods companies are accelerating paperboard expansion and film reduction to avoid compliance penalties. The beverage multipack segment is most affected, with brands reformulating collation strategies around fiber-based carriers.
Third-party logistics providers are consolidating packaging specification authority previously held by brand procurement teams. Amazon's Frustration-Free Packaging certification and dimensional weight pricing are displacing traditional retail-ready formats in favor of ship-in-own-container designs. This concentration is most visible in Illinois and Ohio fulfillment clusters where 3PL operators now dictate corrugated grade specifications.
North America Secondary Packaging Market Segmentation
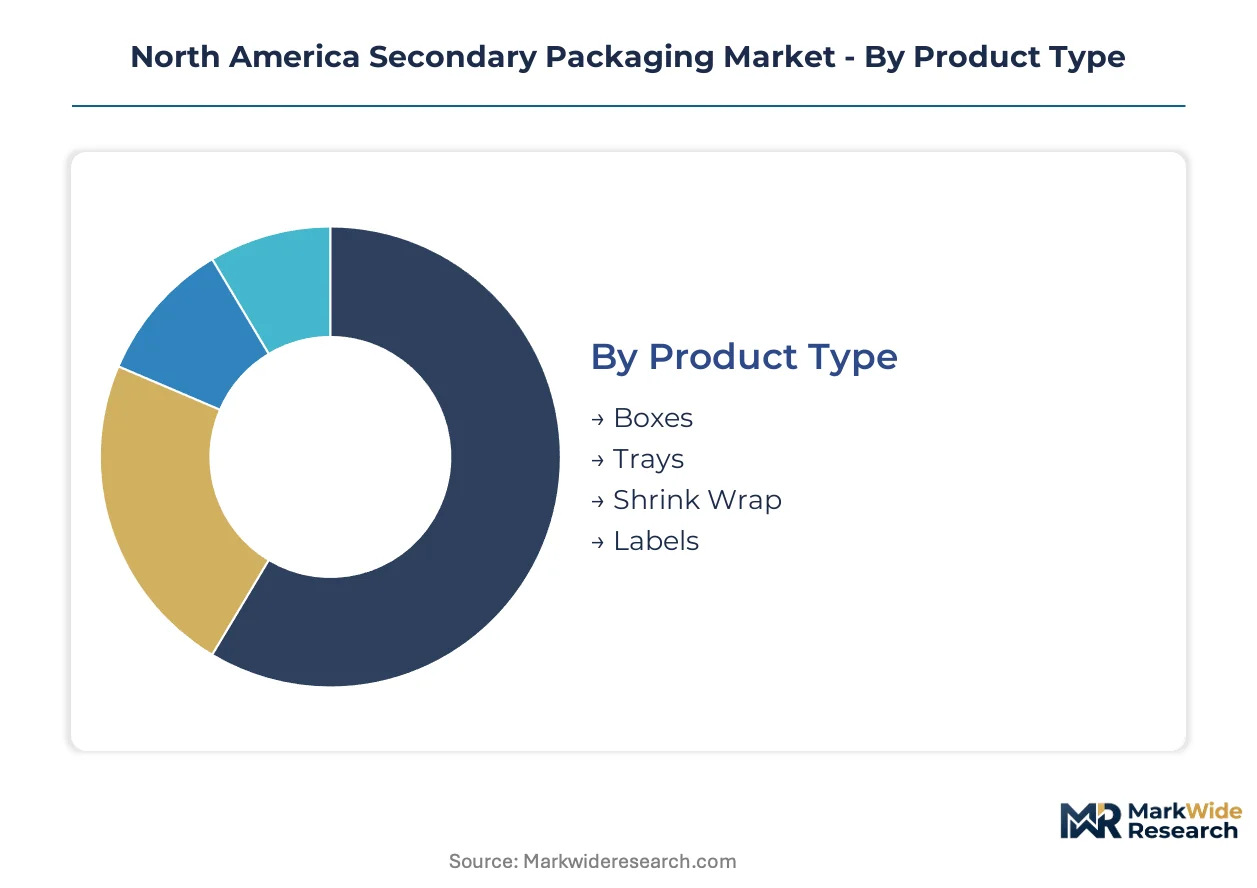
Secondary packaging specifications diverge sharply between high-velocity e-commerce fulfillment and regulated pharmaceutical distribution. Understanding these segment boundaries clarifies where capital deployment aligns with volume concentration versus margin protection.
Product Type:
Standardization dominates at the commodity end while customization premiums concentrate in protective formats engineered for dimensional weight compliance.
- Boxes:Corrugated fiberboard enclosures employing 23- to 42-pound basis weight linerboard with A, B, C, E, or F flute profiles. Demand clusters in Great Lakes distribution hubs where Michigan, Ohio, and Illinois fulfillment centers optimize for parcel carrier dimensional weight penalties.
- Shrink Wrap:Collation films replacing paperboard multipacks in beverage and personal care categories. California's SB 54 extended producer responsibility mandates are compressing adoption timelines as brands reformulate around fiber-based alternatives to avoid compliance penalties.
- Trays:Paperboard or molded pulp platforms for retail-ready display and transport stability. Quick-service restaurant supply chains specify these for combo meal consolidation.
- Labels:Pressure-sensitive or shrink-sleeve formats for secondary identification and regulatory marking. Pharmaceutical serialization requirements in the United States drive specification complexity.
Leading the category by volume: Boxes. Growing fastest: Shrink Wrap.
Material:
Recycled content mandates are rebalancing procurement weights toward post-consumer fiber streams and away from virgin substrates.
- Paperboard:Unbleached kraft and bleached white-top linerboard grades. EPA recycled fiber guidelines are expanding virgin substitution in corrugated medium across southeastern United States integrated mills.
- Plastic:PE, PP, and PET films for collation and stretch applications. Emerging state-level packaging taxes on non-recycled film content create material selection friction for shrink-wrap-dependent categories.
- Metal:Steel strapping and aluminum clips for heavy-load unitization. Industrial machinery and automotive parts distribution specify these for pallet security.
- Glass:Limited secondary use in premium spirits and cosmetics protective overwrap. Fragility concerns restrict deployment beyond niche applications.
Paperboard commands the greatest tonnage. Plastic faces the steepest regulatory headwinds.
End User:
Volume scale concentrates in consumables replenishment while compliance complexity clusters in regulated categories.
- Food & Beverage:Grocery retail and direct-to-consumer fulfillment drive corrugated consumption. Amazon's Frustration-Free Packaging certification is displacing traditional retail-ready formats in favor of ship-in-own-container designs.
- Pharmaceuticals:Child-resistant and tamper-evident specifications dominate. FDA serialization mandates and temperature integrity requirements shape material selection.
- Personal Care:Collation strategies are shifting from paperboard multipacks to film bundles for pallet cube efficiency. Shelf-ready display requirements persist in club retail channels.
- Electronics:Anti-static and cushioning specifications for high-value device protection. E-commerce return rates drive investment in damage-resistant formats.
Food & Beverage generates the highest absolute demand. Pharmaceuticals extract the strongest compliance premiums.
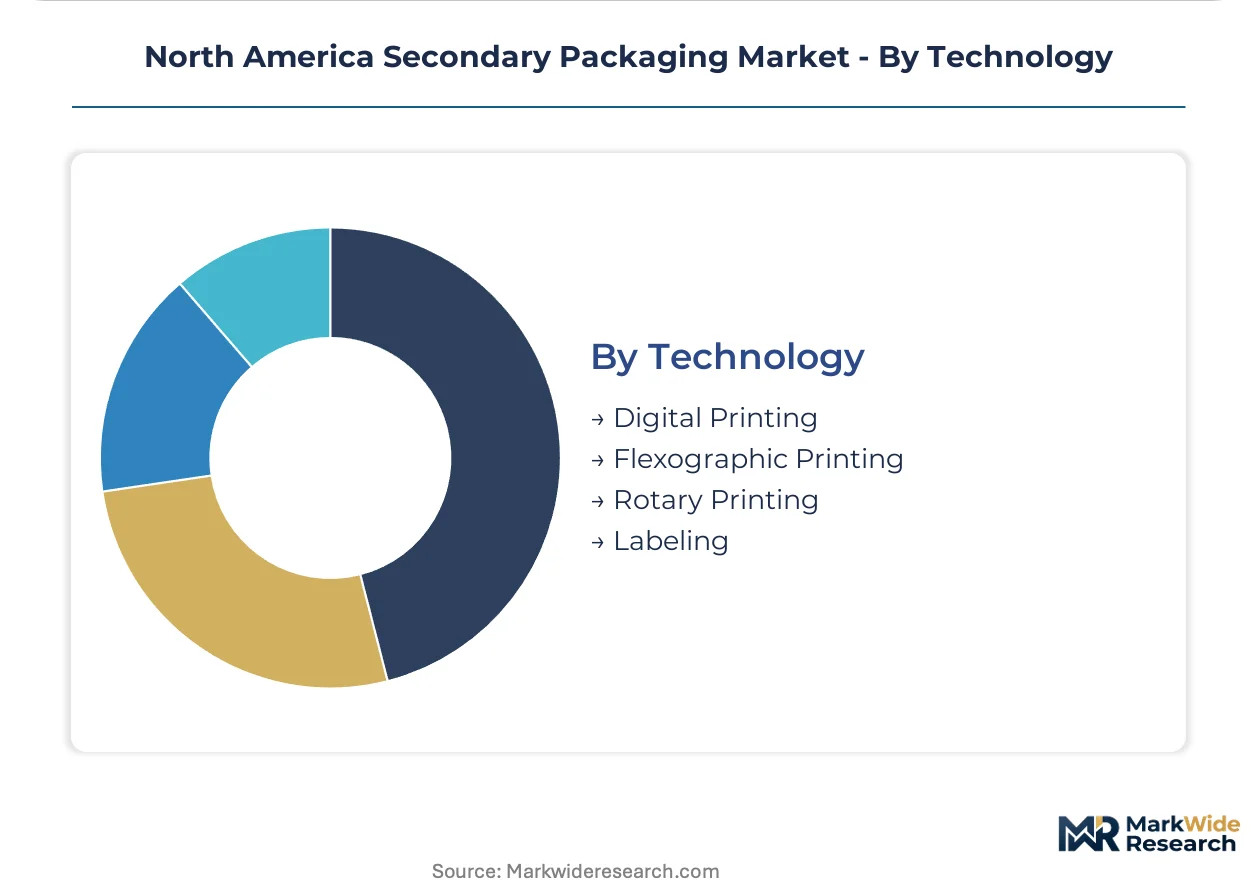
Technology:
Setup cost economics separate high-volume rotary applications from short-run digital deployment.
- Digital Printing:Inkjet and toner-based imaging without plate changeover. Mass-market retailers adopt versioned graphics for seasonal campaigns previously requiring 10,000-unit minimums.
- Flexographic Printing:Photopolymer plate imaging for long-run corrugated and film applications. Containerboard mills integrate these lines for grocery and beverage case production.
- Rotary Printing:Cylinder-based offset and gravure for highest-volume label and carton work. Pharmaceutical and personal care brands specify these for color consistency at scale.
- Labeling:Pressure-sensitive applicators and shrink-sleeve systems for secondary identification. 3PL consolidation in Illinois and Ohio is centralizing specification authority for e-commerce parcel marking.
Flexographic retains the largest installed base. Digital is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Great Lakes manufacturing corridor where Michigan, Ohio, and Illinois fulfillment centers process the highest e-commerce parcel volumes. EPA recycled content mandates and California's SB 54 extended producer responsibility framework are reshaping procurement specifications across the continent.
United States
Great Lakes distribution hubs in Michigan, Ohio, and Illinois optimize corrugated specifications for dimensional weight compliance. EPA recycled fiber guidelines push post-consumer content substitution in linerboard grades. Southeastern integrated mills in Georgia and Alabama control kraft linerboard supply chains.
Canada
Ontario and British Columbia extended producer responsibility frameworks drive compliant packaging service demand. Health Canada pharmaceutical serialization requirements shape label and carton specifications. Toronto-Waterloo corridor distribution centers adopt automated void-fill systems for cross-border fulfillment.
Mexico
Nuevo León automotive parts distribution specifies steel strapping for heavy-load unitization. Mexico City Metro consumer goods fulfillment drives corrugated consumption for retail replenishment. Northern border states concentrate maquiladora export packaging operations serving US retailers.
North America Secondary Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated producers add containerboard machine lines to capture e-commerce-driven demand. Four major players control the majority of North American kraft linerboard capacity, creating supply vulnerability during maintenance cycles. Two strategic archetypes prevail: integrated pulp-to-box operators with captive fiber supply, and specialized equipment providers focused on automated protective systems. Competitive intensity centers on vertical integration depth and geographic proximity to Great Lakes fulfillment clusters.
Within the integrated producer tier, International Paper Company and WestRock exemplify scale-driven positioning through southeastern US mill networks. Sealed Air Corporation occupies a differentiated position among protective packaging specialists, anchoring the automated void-fill segment where dimensional weight economics drive procurement decisions. These three entities represent the structural poles of the competitive landscape: fiber-based substrate control, recycling infrastructure ownership, and fulfillment-optimization equipment.
| Leading Market Players |
|---|
| Amcor PLC |
| International Paper Company |
| WestRock |
| Ball Corporation |
| Crown Holdings Inc. |
| Smurfit WestRock |
| Sealed Air Corporation |
| Packaging Corporation of America |
| Graphic Packaging Holding Co. |
| Others |
Pricing and Supply Chain Analysis
Integrated pulp-to-box operators with captive southeastern US mill networks anchor supply-side pricing discipline, while independent sheet feeders face margin compression from OCC bale volatility and concentrated linerboard sourcing. This ownership pattern concentrates pricing power among four major producers while fragmenting downstream negotiation leverage for converters serving Great Lakes fulfillment clusters.
Pricing Analysis
Volume concentration in commodity corrugated cases competes with margin protection in protective formats engineered for dimensional weight compliance. Three-tier pricing structure across premium certified, standard industrial, and economy spot grades separates Amazon Frustration-Free Packaging specifications from generic retail-ready formats. Pricing pressure stems from parcel carrier dimensional weight penalties forcing box-sizing optimization investments. Third-party logistics providers in Illinois and Ohio exhibit highest price sensitivity due to specification authority consolidation, while pharmaceutical serialization mandates render healthcare buyers least sensitive.
Supply Chain Analysis
Old corrugated container supply rests on municipal recycling streams across the southeastern United States, while virgin kraft pulp feeds from southeastern integrated mills in Georgia and Alabama. Linerboard medium, starch adhesives, and digital printing inks constitute critical input dependencies. Single-source vulnerability concentrates in kraft linerboard capacity controlled by four integrated producers during planned maintenance cycles. Distribution runs through direct mill-to-converter arrangements for high-volume grocery and beverage accounts, with independent distributors serving short-run digital printing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
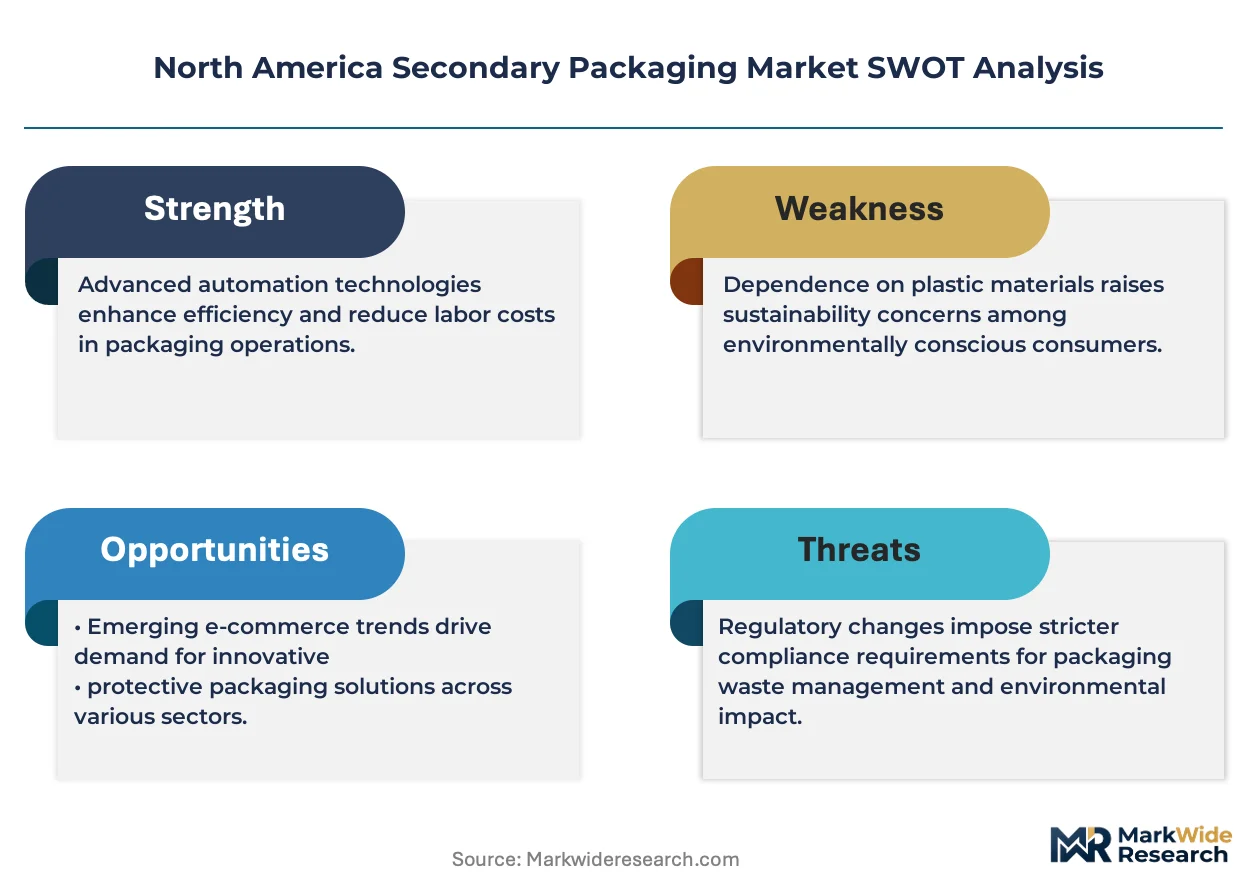
This market functions as a vertical-integration race where backward control over post-consumer fiber streams determines cost position against EPA recycled content mandates. Players are pursuing captive recycling infrastructure as the decisive upstream lever.
For Market Incumbents: Hedge against plastic-to-fiber transition timelines by diversifying material technology portfolios beyond corrugated concentration. Acquire automated void-fill equipment specialists before 3PL consolidation locks in protective packaging specifications. California SB 54 compliance deadlines and Illinois-Ohio fulfillment hub expansion represent the twin threat vectors requiring dual-track capacity positioning. For New Entrants and Emerging Players: Regional quick-service restaurant chains with combo meal tray requirements represent an underserved buyer archetype bypassed by national corrugated contracts. Target Ontario and British Columbia EPR compliance services ahead of federal Canadian harmonization. Digital printing-enabled short-run personalization for seasonal campaigns offers the most penetrable entry wedge against rotary-dominated grocery supply chains. For Investors and Strategic Acquirers: OCC bale price spikes above historical bands are the leading indicator that independent sheet feeder distress will accelerate consolidation opportunities. Five-to-ten year viability favors integrated producers with captive fiber supply over converter-only operations exposed to linerboard margin squeezes. Watch for Amazon Frustration-Free Packaging certification adoption rates among mid-market CPG brands as the inflection signal for ship-in-own-container format dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Buildout | EPA recycled fiber guidelines in the United States mandate post-consumer content substitution. |
| Automated Void-Fill Equipment Acquisition | Parcel carrier dimensional weight penalties in Michigan and Ohio drive protective system demand. |
| Digital Printing Capability Expansion | Short-run corrugated personalization eliminates plate costs for seasonal CPG campaigns. |
| Extended Producer Responsibility Compliance Services | California SB 54 mandates 25% source reduction and 65% recycling rates by weight targets. |
| Great Lakes Distribution Hub Proximity Investment | Illinois and Ohio fulfillment center concentration dictates corrugated grade specification authority. |
Research Methodology
SEC 10-K filings, EPA recycled content guideline documentation, and American Forest & Paper Association production statistics formed the secondary backbone for supply-side capacity assessment. Primary interviews with containerboard mill procurement directors, corrugated converter plant managers, and third-party logistics specification engineers in Michigan, Ohio, and Illinois were combined with secondary validation. Bottom-up shipment data triangulation against top-down capacity utilization estimates anchored volume modeling.
Historical linerboard price trendlines and e-commerce parcel volume growth patterns established baseline trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, material grade, end-use industry, and printing technology adoption. CAGRs were derived from regression analysis against fulfillment center expansion pipelines and regulatory compliance deadline schedules. Old corrugated container price volatility indices and dimensional weight penalty rate changes served as industry-specific forecast inputs.
Revisions become necessary when California SB 54 enforcement timelines accelerate, integrated mill maintenance cycles disrupt linerboard supply, or parcel carrier pricing structures materially shift dimensional weight thresholds. Forecasts reflect documented assumptions about regulatory compliance cost pass-through rates and fiber substitution elasticity. OCC price volatility, 3PL specification authority consolidation, and state-level plastic packaging tax expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
North America Child Resistant Packaging Market