
 Supermarkets Market | 2026-2036
Supermarkets Market Size, Share, and Industry Trends Forecast 2026-2036
Supermarkets Market Analytics
Market Context
European private-label manufacturing capacity is broadening as discounters expand continental sourcing networks. ALDI leverages captive label development to sustain margin compression in core grocery categories. Walmart anchors North American distribution through dense supercenter placement and automated fulfillment integration. Carrefour competes via multi-format flexibility across Latin American and Middle Eastern metropolitan corridors.
Technical Definition and Structural Segments
A supermarket constitutes a self-service retail facility exceeding 2,000 square meters, operating refrigerated display cases maintaining 0-4°C for perishables alongside ambient shelving for packaged goods, with primary commercial purpose of consolidating weekly household provisioning into single-trip destination shopping. Hypermarkets within the Store Format segment dominate absolute transaction volume while discount stores capture fastest household penetration among price-sensitive demographics. Dairy Products within Product Category command repeat-visit frequency, whereas loyalty programs under Promotional Strategy concentrate data assets that enable personalized pricing and inventory optimization.
Regulatory Frame and Forward Outlook
The EU Green Deal and REACH frameworks mandate packaging recyclability thresholds and chemical disclosure for food-contact materials, directly elevating compliance costs for private-label suppliers. FDA nutrition labeling modernization in the United States reshapes front-of-pack claim strategies and reformulation priorities for processed categories. Stakeholders must monitor divergence between European extended producer responsibility schemes and American state-level plastic restriction patchworks when allocating capital across sourcing geographies.
Market Dynamics
Organized retail penetration into tier-two Indian cities and German packaging waste mandates under EU Green Deal compliance are compressing margins while expanding addressable household bases for modern grocery formats.
Growth Catalysts
- EU Green Deal packaging recyclability thresholds:German retailers are retrofitting supply chains to meet extended producer responsibility schemes, accelerating private-label supplier consolidation and captive sourcing investments.
- Urban household dietary pivot toward prepared offerings:Working professionals in Indian metropolitan corridors are shifting weekly provisioning patterns toward ready-to-cook and fresh meal components, driving basket size expansion.
- Automated fulfillment integration:Dense supercenter placement across North American markets is integrating robotic picking systems and micro-fulfillment centers into existing footprints, compressing last-mile delivery windows.
Market Restraints
- Refrigerated display case energy costs:Maintaining 0-4°C perishable zones across facilities exceeding 2,000 square meters exposes operators to electricity price volatility in European markets.
- Private-label supplier concentration in Central Europe:Discounter captive manufacturing networks create dependency risk when continental sourcing disruptions occur.
- Chemical disclosure mandates under REACH:Food-contact material compliance documentation requirements extend product development timelines for processed categories.
Strategic Opportunities
- Tier-two city penetration in India:Organized modern retail is establishing first-mover positions in secondary urban corridors where traditional kirana stores dominate weekly provisioning.
- Multi-format flexibility in Latin American corridors:Hypermarket-discount hybrid concepts are capturing price-sensitive demographics without sacrificing fresh assortment depth.
- Loyalty program data monetization:Personalized pricing engines and inventory optimization algorithms are creating ancillary revenue streams from transaction data assets.
Industry Challenges
- Refrigeration technician scarcity:Maintaining 0-4°C display case fleets requires specialized HVAC-R skills that compete with industrial cold chain operators for talent.
- Front-of-pack claim reformulation:FDA nutrition labeling modernization demands R&D investment to maintain shelf positioning while meeting disclosure thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supermarkets Market |
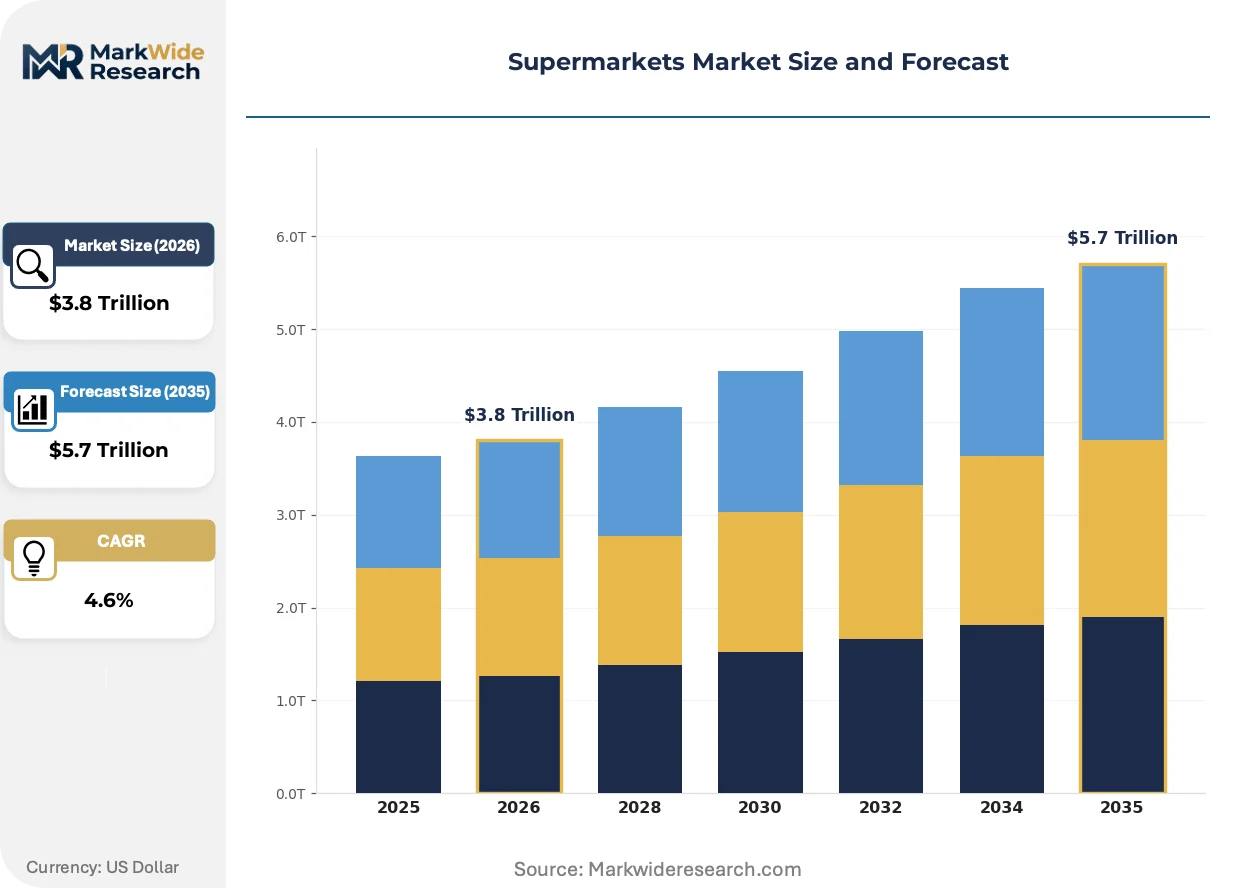
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.7 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Fruits, Vegetables, Dairy Products, Bakery Items Customer Type: Families, Singles, Students, Seniors Store Format: Hypermarkets, Discount Stores, Convenience Stores, Specialty Stores Promotional Strategy: Buy-One-Get-One, Discounts, Loyalty Programs, Seasonal Offers |
| Companies Covered | ALDI, Costco, Walmart, Tesco, Carrefour, Kroger, Publix, Schwarz Group, Albertsons Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supermarkets Market Evolving Landscape
Digital infrastructure is embedding itself into physical grocery footprints, transforming how retailers capture household provisioning decisions and optimize perishable turnover through predictive systems.
Computer vision shelf-monitoring systems are integrating real-time inventory tracking with automated replenishment triggers. Tier-one operators in North American and Western European markets are deploying camera arrays above ambient shelving and refrigerated cases to reduce stockout frequency and labor hours. This technology is integrating demand forecasting with supplier order automation, compressing the replenishment cycle from days to hours for high-velocity categories.
REACH chemical disclosure expansions are forcing reformulation roadmaps across private-label processed food portfolios. ECHA substance restrictions on food-contact materials are elevating testing costs and extending supplier qualification timelines. Dairy and ready-meal categories face the steepest compliance burden, with German and French retailers accelerating supplier audits to preempt enforcement actions.
Weekly single-trip consolidation is fragmenting into multiple micro-visit patterns among urban professional households. Quick-commerce dark stores and convenience-forward supermarket formats are capturing top-up shopping occasions that hypermarkets previously dominated. This behavioral shift is most visible in Indian metropolitan corridors and Middle Eastern city centers, where delivery apps and small-format proximity stores are displacing bulk provisioning rituals.
Supermarkets Market Segmentation
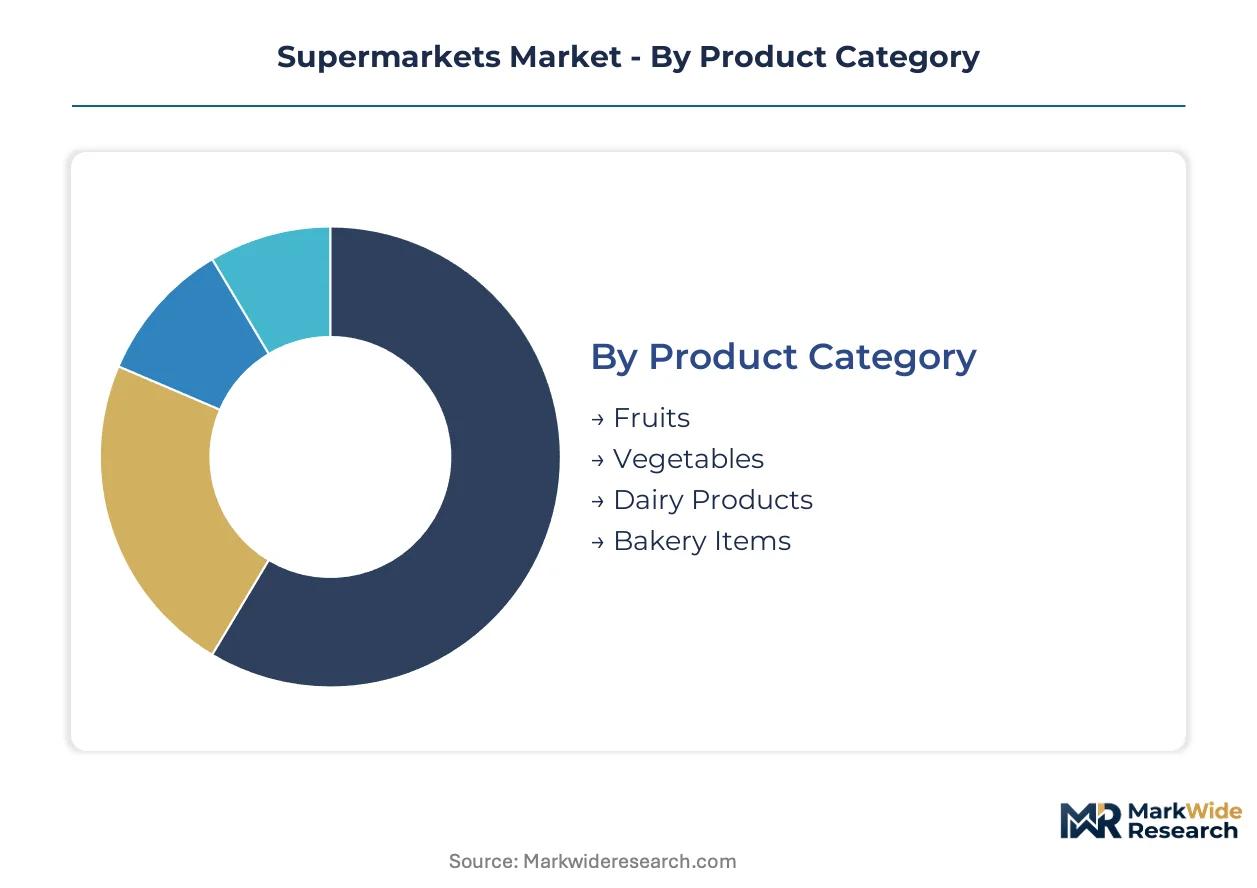
Supermarket operators calibrate assortment depth, store footprint, and pricing architecture against distinct household provisioning patterns. Segmentation reveals where refrigerated infrastructure investments concentrate and which promotional mechanics compress margin versus drive traffic.
Product Category:
Dairy Products and ready-meal portfolios face the steepest REACH compliance burden for food-contact material documentation, while fresh produce navigates pesticide residue thresholds under national food safety regimes.
- Dairy Products:Refrigerated SKUs spanning fluid milk, cheese, and yogurt command weekly repeat-visit frequency and anchor perimeter department traffic. German and French retailers audit supplier qualification timelines most aggressively under ECHA substance restrictions. Margin pressure intensifies as private-label processors absorb extended testing costs for packaging recyclability.
- Fruits:Perishable inventory with compressed turnover cycles drives predictive ordering system deployment. Indian organized retail concentrates procurement modernization here as tier-two city households shift from wet markets to temperature-controlled displays. FSSAI residue testing protocols extend supplier onboarding for imported varieties.
- Vegetables:Local sourcing radius constraints dominate procurement economics for leafy and root categories. Ambient shelving requirements are minimal but cold chain integrity from farm to display case determines shrink rates.
- Bakery Items:In-store production footprints compete with central commissary supply depending on real estate costs and labor availability. Par-baked frozen inputs reduce skilled baker dependency.
Dairy Products sits at the top of the volume ranking, with Fruits climbing the fastest as organized retail penetrates Indian secondary cities.
Customer Type:
Household composition dictates basket size, trip frequency, and sensitivity to promotional mechanics across format types.
- Families:Weekly single-trip consolidation into hypermarket destinations with bulk-pack preference and price-per-unit calculation discipline. Automated fulfillment integration captures this segment through subscription replenishment for staples.
- Singles:Convenience-forward formats and quick-commerce dark stores displace traditional provisioning rituals. Smaller pack sizes and ready-to-cook components expand basket margin.
- Students:Price elasticity concentrates demand in discount store channels and promotional periods. Digital coupon redemption rates exceed population average.
- Seniors:Loyalty program participation and assisted shopping services retain this demographic against pharmacy and dollar store encroachment.
Families generate the largest absolute transaction value, with Singles expanding most quickly through proximity format proliferation.
Store Format:
Capital deployment and regulatory exposure vary dramatically by square footage and refrigeration intensity.
- Hypermarkets:Facilities exceeding 10,000 square meters consolidate full weekly provisioning with extensive refrigerated cases maintaining 0-4°C across dairy, meat, and produce zones. Energy cost volatility in European markets compresses returns on legacy footprints.
- Discount Stores:Limited assortment depth and private-label concentration sustain margin compression in core grocery categories. ALDI and Lidl captive sourcing networks dominate Central European supply.
- Convenience Stores:Extended hours and proximity capture top-up occasions previously dominated by larger formats. Refrigerated beverage and ready-meal cases dominate square footage allocation.
- Specialty Stores:Ethnic or organic positioning commands premium pricing with narrower SKU breadth and higher supplier qualification standards.
Hypermarkets hold the volume crown, with Discount Stores gaining share fastest among price-sensitive demographic expansion.
Promotional Strategy:
Data capture capabilities and margin trade-offs differentiate mechanic selection by operator scale.
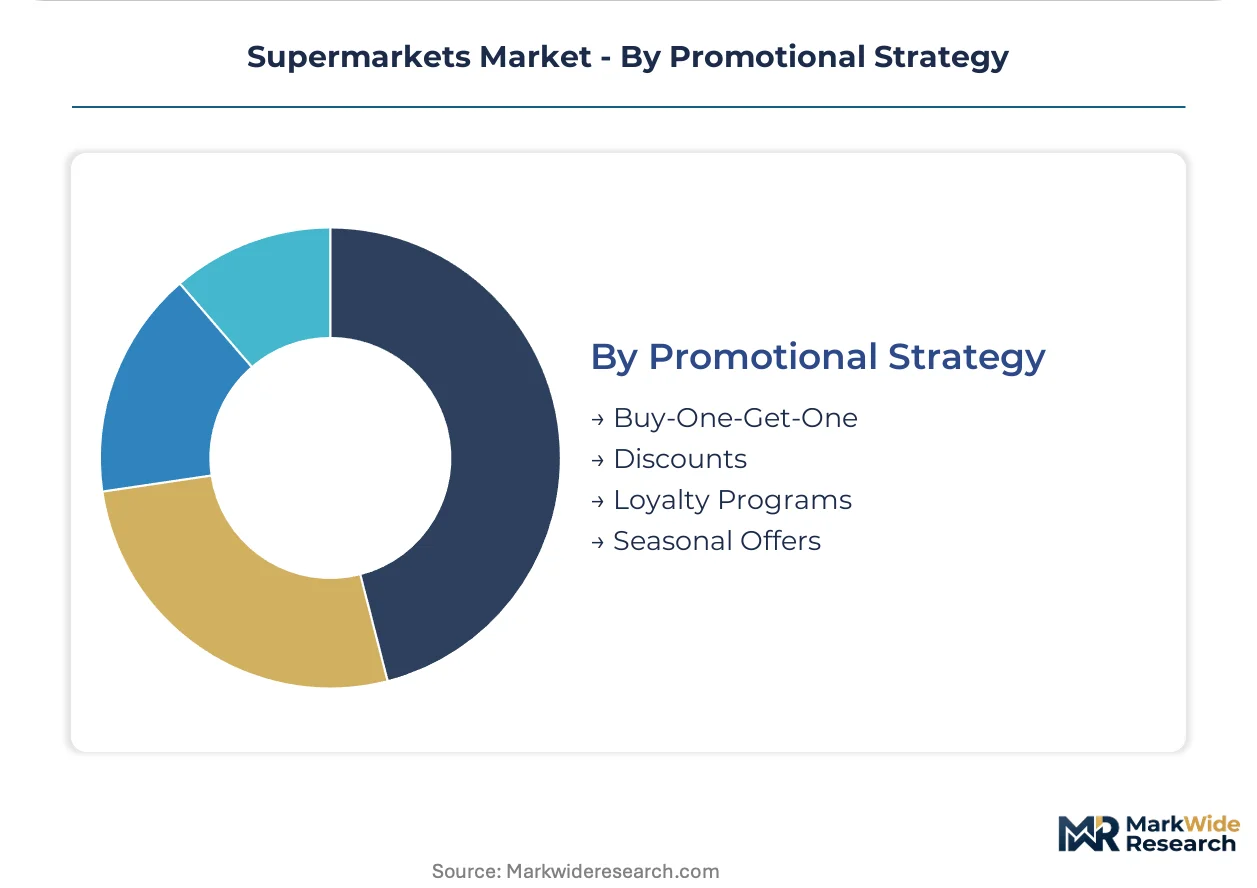
- Loyalty Programs:Transaction data assets enable personalized pricing engines and inventory optimization algorithms. Tier-one operators monetize these assets through supplier-funded targeted offers.
- Discounts:Temporary price reductions on known-value items drive traffic without permanent price repositioning.
- Buy-One-Get-One:Inventory clearance vehicle for near-expiry perishables with minimal margin recovery.
- Seasonal Offers:Calendar-driven assortment rotation captures holiday provisioning concentration.
Loyalty Programs anchor the strategic priority ranking, with Discounts deployed most frequently for competitive response velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces the strictest packaging compliance costs among major markets, while India offers the steepest household penetration runway for organized formats. These divergent regulatory and growth profiles shape capital allocation across geographies.
United States
Hypermarket operators integrate robotic fulfillment systems into existing supercenter footprints to compress delivery windows. FDA nutrition labeling modernization forces reformulation investments across processed private-label portfolios. The Dallas-Fort Worth metroplex anchors automated distribution hub expansion for central U.S. coverage.
Germany
EU Green Deal extended producer responsibility schemes elevate compliance expenditures for packaging recyclability. ECHA substance restrictions under REACH extend supplier qualification timelines for food-contact materials. The Rhine-Ruhr corridor concentrates discounter captive sourcing networks and private-label manufacturing capacity.
India
Tier-two city households shift weekly provisioning from traditional kirana stores to temperature-controlled modern retail formats. FSSAI residue testing protocols extend supplier onboarding for imported fresh produce varieties. Bangalore and Hyderabad anchor organized retail penetration into southern secondary urban corridors.
China
Urban professional households fragment single-trip consolidation into multiple micro-visit patterns via quick-commerce platforms. SAMR food safety inspections intensify documentation requirements for cold chain integrity. The Yangtze River Delta cluster drives proximity format proliferation around Shanghai and Hangzhou metropolitan zones.
Brazil
Hypermarket-discount hybrid concepts capture price-sensitive demographics without sacrificing fresh assortment depth. ANVISA sanitary surveillance mandates elevate cold chain documentation for perishable imports. São Paulo state anchors multi-format experimentation and private-label development for Latin American markets.
Supermarkets Market Competitive Landscape
German discounters anchor one tier through captive private-label manufacturing networks; North American supercenter operators hold scale-driven density advantages through automated fulfillment integration. Market structure tilts toward consolidated national champions in developed markets while emerging economies sustain fragmented regional competition. Three archetypes dominate: discount specialists with backward-controlled supply chains, full-service hypermarket operators with data-rich loyalty ecosystems, and convenience-forward proximity formats capturing top-up occasions. Competitive moves concentrate on supplier consolidation to absorb compliance costs and micro-fulfillment technology deployment to compress last-mile economics.
Within the discount specialist tier, ALDI and Schwarz Group exemplify backward integration strategies that insulate margin from packaging regulation cost pass-through. Walmart anchors the supercenter archetype through dense geographic placement and robotic picking system integration. Carrefour occupies a multi-format flexibility position across Latin American and Middle Eastern metropolitan corridors where hybrid concepts capture heterogeneous household provisioning patterns.
| Leading Market Players |
|---|
| ALDI |
| Costco |
| Walmart |
| Tesco |
| Carrefour |
| Kroger |
| Publix |
| Schwarz Group |
| Albertsons Companies |
| Others |
Value Network & Pricing Analysis
Private-label concentration against branded premium tiers creates a bifurcated margin architecture across European and North American markets, with discounters capturing cost-sensitive households through captive sourcing while full-service operators defend premium positioning via loyalty-data monetization and fresh assortment depth.
Pricing Analysis
Retailer markup layers vary dramatically by format scale and private-label penetration. Hypermarket operators deploy three-tier pricing structure across premium, standard, and economy levels, with organic and specialty certifications commanding shelf-position premiums. Pricing pressure stems from EU Green Deal compliance cost pass-through into packaging and energy-intensive refrigeration. Students and price-elastic households concentrate demand in discount channels where ALDI and Lidl compress margins through backward-controlled supply networks.
Supply Chain Analysis
REACH certification and ECHA substance qualification gates create supplier consolidation pressure across German and French retail networks. Sourcing concentrates in Germany, France, and Poland for private-label manufacturing, with India emerging for fresh produce procurement modernization. Cold chain infrastructure, food-contact materials, and specialized HVAC-R technician labor represent critical input dependencies. Single-source vulnerability runs through Central European discounter captive networks. Distribution runs through regional distribution centers feeding supercenter and convenience footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where urban household provisioning shifts toward prepared and fresh specifications, rewarding operators with perimeter-department depth and data-rich personalization engines over pure price competition.
For Market Incumbents: Extend loyalty program data assets into predictive inventory systems and personalized pricing engines to defend against quick-commerce dark store encroachment. Deepen backward integration into private-label manufacturing to absorb EU Green Deal packaging compliance costs. Capture tier-two Indian city expansion through temperature-controlled format rollout ahead of kirana store modernization. For New Entrants and Emerging Players: Quick-commerce platform partnerships offer the lowest-friction route into urban professional households fragmenting weekly provisioning into micro-visits. Target Indian tier-two corridors where organized retail penetration remains below metropolitan saturation. Deploy convenience-forward small-format concepts with refrigerated ready-meal depth to capture top-up occasions. For Investors and Strategic Acquirers: Consolidation pressure builds where private-label supplier networks face REACH compliance documentation burdens and energy cost volatility. Long-term viability favors operators with captive sourcing scale and multi-format flexibility across heterogeneous regional corridors. Watch tier-two Indian household provisioning shift from traditional to temperature-controlled retail as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Deployment | Robotic picking integration compresses last-mile delivery windows for North American supercenter networks. |
| Private-Label Supplier Consolidation | Captive manufacturing absorption of ECHA compliance costs protects margin in German discounter channels. |
| Quick-Commerce Platform Partnership | Dark store networks capture fragmented urban provisioning patterns in Indian and Middle Eastern corridors. |
| Multi-Format Hybrid Concept Rollout | Hypermarket-discount combinations serve price-sensitive Brazilian households without fresh assortment sacrifice. |
| Loyalty Data Monetization Expansion | Personalized pricing engines create ancillary revenue from transaction assets at Kroger and Tesco scale. |
Research Methodology
Direct dialogue with supermarket category managers, private-label procurement directors, cold chain logistics operators, and retail technology vendors grounded qualitative findings. Secondary validation drew from FSSAI compliance filings, EU ECHA substance restriction updates, Nielsen retail audit data, and SEC 10-K disclosures from listed operators. Bottom-up store-format modeling triangulated against top-down household expenditure pattern analysis.
Bottom-up volume estimates by product category and store format reconciled with top-down macroeconomic consumption trends across the projection horizon. Segmentation dimensions spanned product category, customer type, store format, and promotional strategy. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated EU Green Deal implementation timelines and Indian organized retail penetration rates.
Regulatory enforcement variance, energy price volatility, and quick-commerce platform competitive intensity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on household provisioning behavior continuity and compliance cost pass-through elasticity. A model refresh is warranted upon material change in Indian tier-two city modern retail adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Pizza Oven Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Rotisseries Market
Food Service
United States Cafes & Bars Market
Food Service
Europe Cloud Kitchen Market
Food Service
Global Vending Machine Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Charbroiler Market
Food Service
Global Sushi Restaurants Market
Food Service
Workplace Service Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Kamado Grill Market
Food Service
Global Food Retail Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Plates Market
Food Service
Commercial Tandoor Oven Market