
 Kamado Grill Market | 2026-2036
Kamado Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Kamado Grill Market Insights
Backyard cooking enthusiasts is reorganizing demand away from entry-level charcoal equipment toward premium, thermally efficient kamado systems. Komodo Kamado leverages its handcrafted ceramic construction and ultra-premium positioning to command aspirational price points. Big Green Egg sustains dominant brand recognition through proprietary accessories and a cult-like owner community. Kamado Joe differentiates via its Divide & Conquer flexible cooking system and continuous incremental innovation in airflow control.
A kamado grill is a thick-walled, egg-shaped cooker traditionally fabricated from refractory ceramic with wall thicknesses of one to two inches, engineered to retain radiant heat across temperatures from 225°F to over 750°F for smoking, roasting, and searing applications. Modern variants incorporate stainless steel bands, cast-iron dampers, and multi-level grate systems to expand cooking versatility. Traditional Kamado units occupy the heritage-driven premium tier where margin pools remain deepest, while Portable Kamado formats are gaining fastest among apartment dwellers and tailgating segments constrained by space. Ceramic dominates material selection for thermal mass performance, though Steel variants compete aggressively on weight and transportability for camping and RV applications.
EPA guidelines on particulate emissions from residential wood-burning equipment influence venting and combustion efficiency standards for kamado manufacturers selling into the United States. CE marking requirements under EU safety directives govern thermal insulation performance and structural stability for European market access. The FDA's indirect food contact material regulations apply to ceramic glazes and metal coatings used in cooking surfaces. Stakeholders must monitor evolving municipal fire codes and balcony grilling restrictions in dense urban jurisdictions, as these local ordinances increasingly determine addressable market scope for large-format units.
Market Dynamics
Residential outdoor cooking is reorganizing around thermal efficiency mandates and balcony grilling restrictions in dense urban cores, compressing demand toward portable formats while premium ceramic units retain margin concentration in suburban markets.
Growth Catalysts
- EPA particulate emissions guidelines:Manufacturers are engineering cleaner combustion chambers and optimized venting systems to maintain US market access. This drives R&D investment in airflow control mechanisms.
- Refractory ceramic thermal mass:Backyard enthusiasts value temperature stability for low-and-slow smoking applications. Ceramic wall construction enables precise heat retention across extended cook cycles.
- Australian backyard entertainment culture:Replacement cycles accelerate in this market as consumers upgrade from kettle grills to kamado systems. Premium positioning commands sustained demand velocity.
Market Restraints
- Refractory ceramic supply concentration:High-purity clay deposits and specialized kiln capacity cluster in East Asian manufacturing zones. Input cost volatility constrains margin flexibility for Western assemblers.
- Municipal balcony grilling ordinances:Dense urban jurisdictions in Germany and the Netherlands restrict open-flame cooking on multi-unit residential structures. Large-format kamado units face addressable market compression.
- Steel kamado substitution:Weight-reduced metal variants compete aggressively on transportability for camping and RV segments. Ceramic thermal advantages erode among mobile user bases.
Strategic Opportunities
- Apartment dweller segment in Japan:Compact kamado formats remain underpenetrated in Tokyo and Osaka metro corridors. Miniaturized units with reduced footprint unlock urban demand pools.
- EU Green Deal product efficiency incentives:Member state rebate programs for energy-efficient residential equipment create procurement tailwinds. CE-marked ceramic units qualify for subsidy eligibility.
- Direct-to-consumer channel expansion:Bypassing traditional outdoor retail networks reduces distributor margin capture. Subscription accessory programs deepen customer lifetime value.
Industry Challenges
- Artisan ceramic firing expertise:Master kiln operators with multi-decade experience concentrate in legacy manufacturing regions. Succession planning gaps threaten production consistency.
- Cross-jurisdictional certification timelines:Simultaneous FDA glaze compliance, EPA emissions validation, and CE thermal insulation testing extend product launch cycles. Parallel regulatory tracks strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kamado Grill Market |
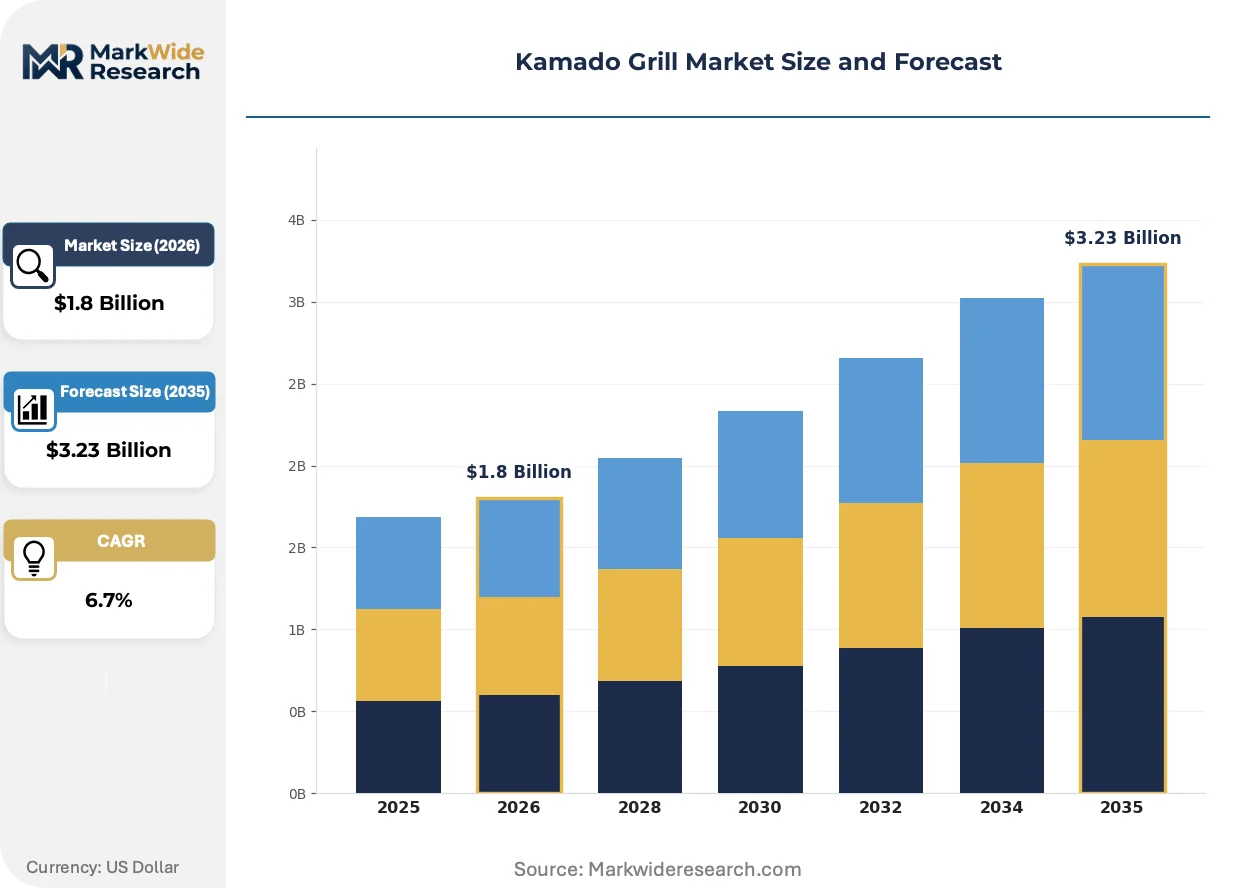
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Kamado, Modern Kamado, Portable Kamado, Hybrid Kamado Material: Ceramic, Steel, Cast Iron, Composite Size: Small, Medium, Large, Extra Large End User: Residential, Commercial, Catering Services, Outdoor Enthusiasts |
| Companies Covered | Komodo Kamado, Coyote, Big Green Egg, Pit Boss, Char-Griller, Kamado Joe, Blaze Outdoor Products, Grilla Grills, Primo Grills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kamado Grill Market Trends and Innovations
Product architecture is splitting between heritage ceramic craft and engineered metal alternatives, while regulatory pressure on combustion efficiency and urban fire codes reshape certification priorities and format specifications.
Multi-level grate systems with flexible height adjustment are bifurcating cooking surface configuration from fixed single-tier designs. Competition-grade barbecue teams and serious hobbyists adopt these systems fastest. The technology is bifurcating price tiers between entry-level fixed-grate units and premium adjustable platforms.
REACH chemical safety regulations in Europe are tightening scrutiny on ceramic glazes and metal coatings used in indirect food contact applications. Manufacturers must reformulate surface treatments or face market withdrawal. German and French import channels enforce compliance most stringently, driving supplier consolidation toward certified coating vendors.
After-sales service unbundling is fragmenting traditional warranty bundling as third-party repair networks and replacement part marketplaces displace manufacturer-controlled service channels. Independent pitmaster communities source dampers, gaskets, and fireboxes through direct digital channels. This pattern concentrates in the United States where owner forums drive DIY maintenance culture.
Kamado Grill Market Segmentation
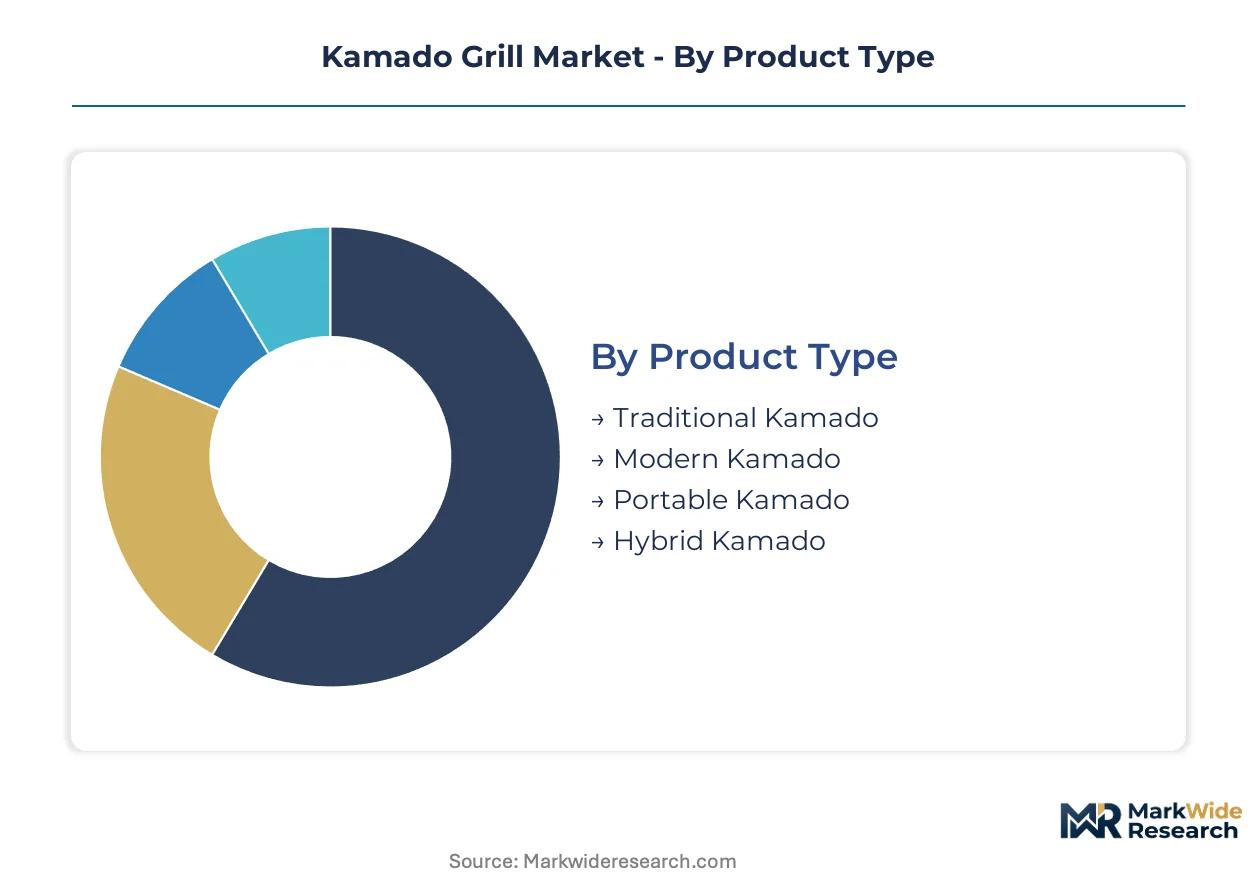
Kamado grill segmentation reveals divergent manufacturing footprints and demand patterns across product architectures. Material selection and format specifications determine whether production clusters in East Asian ceramic kilns or Western metal fabrication facilities.
Product Type:
Traditional and modern variants dominate domestic manufacturing in Japan and the United States, while portable formats increasingly source from export-oriented assembly in Vietnam and Thailand.
- Traditional Kamado:Hand-fired refractory ceramic construction with wall thickness exceeding two inches delivers superior thermal mass for low-and-slow smoking. Heritage manufacturing in Japan's Aichi Prefecture and domestic US craft workshops supplies premium backyard enthusiasts in Australia and Germany who prioritize temperature stability over transportability.
- Modern Kamado:Engineered ceramic composites with stainless steel banding and precision-machined dampers integrate computer-aided design with artisan firing techniques. North American and Western European demand concentrates among technology-adopting residential users seeking smartphone-compatible temperature monitoring accessories.
- Portable Kamado:Compact formats under 18 inches diameter target apartment balconies and tailgating applications. Asian contract manufacturers dominate supply.
- Hybrid Kamado:Dual-fuel architectures combining charcoal combustion with propane ignition assist appeal to convenience-oriented entry buyers. Production splits between Chinese metalworking hubs and Mexican maquiladoras.
Traditional Kamado holds the largest share; momentum sits with Portable Kamado.
Material:
Cost tier stratification separates premium ceramic systems from mid-market metal alternatives, with composite formulations emerging as a margin-compression response to clay supply volatility.
- Ceramic:High-purity refractory clay with alumina-silica formulations provides unmatched heat retention for competition barbecue teams. Japanese Shigaraki and Iga deposits supply heritage manufacturers; American-sourced clay serves domestic kilns in Georgia and Missouri facing EPA emissions compliance for wood-fired curing processes.
- Steel:Double-walled stainless steel construction reduces weight by 60% versus ceramic equivalents while sacrificing thermal stability. Korean and Taiwanese sheet metal fabrication serves RV and camping segments across the American Southwest and Australian Outback where transportability outweighs precision smoking requirements.
- Cast Iron:Dense iron construction offers intermediate thermal mass at reduced fragility. Chinese foundries dominate supply for budget-conscious residential buyers.
- Composite:Ceramic-fiber reinforced polymers and advanced refractory concretes attempt to replicate ceramic performance at lower firing costs. European R&D clusters in Germany and Italy pilot these formulations.
Ceramic commands the premium tier; composite formulations are climbing the fastest as kiln operators seek input cost relief.
Size:
Volume distribution reflects suburban lot dimensions and municipal fire code restrictions that constrain large-format deployment in dense metropolitan cores.
- Small:Under 15-inch cooking diameter serves single-person households and balcony-constrained urban apartments in Tokyo, Berlin, and New York. Japanese manufacturers specialize in miniaturized ceramic craft for this segment.
- Medium:15-18 inch diameter represents the standard family configuration across Australian suburban backyards and American Midwest patios. Production scales efficiently across Chinese ceramic hubs and domestic US facilities.
- Large:18-24 inch diameter targets serious hobbyists and competition barbecue teams requiring multi-zone cooking. German and Austrian import channels show strongest demand velocity for this specification.
- Extra Large:Exceeding 24 inches, these units serve commercial catering and restaurant applications. Limited production concentrates in specialized Japanese kilns and American craft workshops.
Medium size captures the highest unit volume; large formats are gaining share fastest among upgrade-motivated replacement cycles.
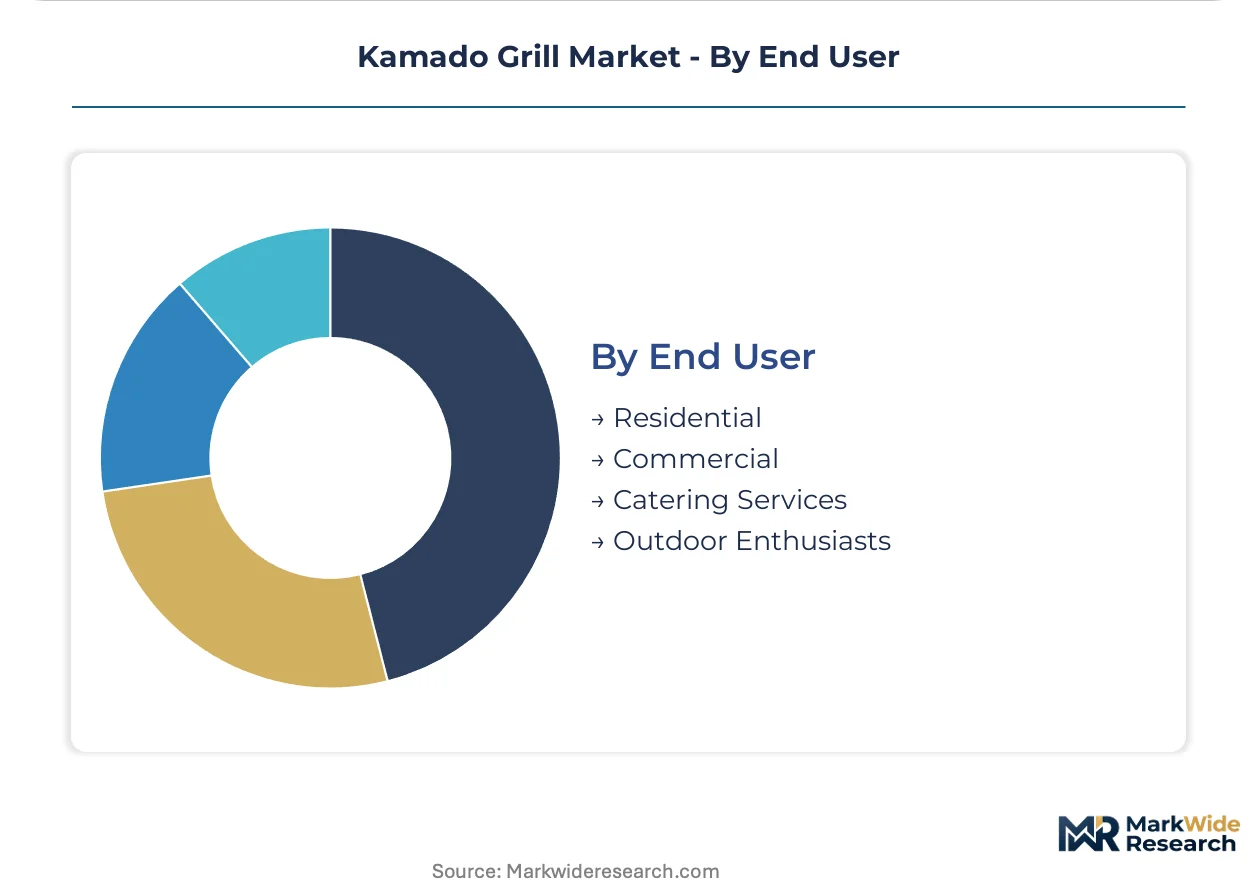
End User:
Customer type determines channel configuration, with residential direct-to-consumer growth displacing traditional outdoor retail while commercial procurement consolidates through foodservice distributors.
- Residential:Backyard cooking enthusiasts drive replacement demand from kettle grills and gas units toward kamado systems. Australian and American suburban markets concentrate premium ceramic purchases; European urban buyers skew toward compact steel formats.
- Commercial:Restaurants and barbecue joints utilize kamado architecture for signature smoked menu items. Health department ventilation requirements in California, Texas, and Florida shape specification priorities for this segment.
- Catering Services:Mobile food operators require transportable units with rapid heat recovery for event service. Steel and portable formats dominate this application.
- Outdoor Enthusiasts:Camping, overlanding, and tailgating users prioritize weight reduction and durability over thermal precision. This segment shows strongest affinity for steel construction and hybrid fuel flexibility.
Residential end use maintains dominant share; catering services are expanding most quickly as event-based food culture recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese ceramic kilns in Aichi Prefecture export heritage kamado units to premium buyers in Australia and Germany, establishing the dominant trade-flow corridor for high-thermal-mass cooking equipment.
United States
Backyard entertainment culture in Georgia and Missouri drives replacement demand from kettle grills toward ceramic kamado systems. EPA emissions guidelines for wood-fired curing processes shape compliance requirements for domestic kiln operators. Atlanta-based assembly facilities source refractory clay from American deposits while navigating municipal fire codes in dense urban corridors.
Germany
Barbecue enthusiast communities in Bavaria and North Rhine-Westphalia sustain import velocity for large-format units exceeding 18 inches diameter. CE marking requirements under EU safety directives govern thermal insulation performance for market access. Frankfurt import channels enforce REACH chemical safety regulations on ceramic glazes most stringently.
Australia
Suburban backyard dimensions in Sydney and Melbourne support medium-format kamado deployment as standard family configurations. Australian Competition and Consumer Commission product safety standards apply to ceramic structural stability. Queensland distributors report fastest upgrade cycle velocity from entry-level equipment to premium ceramic systems.
Japan
Heritage manufacturing in Shigaraki and Iga deposits supplies global demand for hand-fired refractory ceramic construction. METI standards for traditional craft certification protect artisan kiln operator expertise. Tokyo and Osaka metro corridors remain underpenetrated for compact formats targeting apartment dwellers.
Netherlands
Municipal balcony grilling ordinances in Amsterdam and Rotterdam restrict open-flame cooking on multi-unit residential structures. Dutch Building Decree fire safety regulations compress addressable market scope for large-format units. Eindhoven-based distributors pivot toward portable steel variants for urban buyers.
Kamado Grill Market Competitive Landscape
Player mix skews toward heritage craft specialists and engineered metal fabricators competing across thermal performance and transportability vectors. Market structure concentrates margin pools in premium ceramic tiers while steel variants fragment mid-market price bands. Two strategic archetypes dominate: artisan kiln operators with multi-decade firing expertise, and Asian contract manufacturers optimizing weight-reduced metal construction. Competitive moves center on direct-to-consumer channel expansion and accessory ecosystem development to deepen customer lifetime value.
Within the heritage craft tier, Komodo Kamado and Big Green Egg exemplify ultra-premium positioning through proprietary ceramic construction and cult-like owner communities. Kamado Joe occupies a position bridging artisan tradition with continuous incremental innovation in airflow control mechanisms. These three anchors represent divergent paths for sustaining margin concentration against steel substitution pressure.
| Leading Market Players |
|---|
| Komodo Kamado |
| Coyote |
| Big Green Egg |
| Pit Boss |
| Char-Griller |
| Kamado Joe |
| Blaze Outdoor Products |
| Grilla Grills |
| Primo Grills |
| Others |
Pricing and Supply Chain Analysis
Steel kamado substitution for refractory ceramic units redraws manufacturing geography toward East Asian metal fabrication hubs while compressing price premiums previously sustained by thermal performance advantages. This material pivot simultaneously erodes margin pools in heritage ceramic tiers and opens volume pathways in transportability-driven segments.
Pricing Analysis
Generational pricing gaps separate hand-fired traditional kamado units from engineered modern variants and mass-market steel alternatives. Three-tier pricing structure across premium ceramic, mid-market metal, and economy cast-iron levels stratifies buyer access. Price differentiation hinges on thermal certification grade and artisan kiln origin. Cost compression in steel tiers is intensifying because Korean and Taiwanese fabricators optimize sheet-metal efficiency. RV and camping buyers exhibit highest price sensitivity; competition barbecue teams show least.
Supply Chain Analysis
Japan and the United States anchor heritage ceramic production, while Vietnam and Thailand supply portable format assembly. High-purity refractory clay from Shigaraki and Iga deposits feeds Japanese kilns; domestic US facilities draw from Georgia and Missouri clay beds. Supply chain risk centers on single-source vulnerability for master kiln operator expertise. Distribution runs through outdoor retail networks, direct-to-consumer channels, and foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kamado grill demand is reorganizing around EPA emissions compliance and balcony grilling restrictions, creating dual inflection points for product architecture and channel strategy.
For Market Incumbents: Fortify ceramic thermal performance advantages through proprietary glaze formulations and kiln operator apprenticeship programs. Deepen backward integration into American clay deposits to offset East Asian supply volatility. Prioritize CE marking investment for EU Green Deal subsidy eligibility. For New Entrants and Emerging Players: Differentiate on compact format miniaturization for Tokyo and Osaka apartment corridors. Target underpenetrated Japanese urban demand with sub-15-inch diameter units. Pursue direct-to-consumer launch with subscription accessory programs to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward artisan kiln operators with multi-decade firing expertise and established METI craft certification. Long-term viability rests on succession planning for master operator knowledge transfer. Monitor municipal fire code relaxation in dense European jurisdictions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Bypasses outdoor retail margin capture and deepens customer lifetime value through accessory subscriptions. |
| EU Green Deal Certification Investment | CE marking and energy efficiency qualification unlocks member state rebate programs for residential procurement. |
| Compact Format Miniaturization | Sub-15-inch units penetrate Tokyo and Osaka metro corridors constrained by balcony grilling ordinances. |
| Artisan Kiln Operator Apprenticeship | METI-certified craft programs address succession gaps threatening production consistency in heritage manufacturing. |
| Steel Variant Weight Optimization | Korean and Taiwanese fabrication expertise serves RV and camping segments prioritizing transportability over thermal precision. |
Research Methodology
Initial hypotheses were tested against primary input from kamado grill manufacturers, outdoor retail category managers, competition barbecue team captains, and municipal fire code enforcement officers, and refined through secondary validation. Trade data from USITC and Eurostat, EPA emissions compliance filings, CE marking registration databases, and METI traditional craft certification records anchored quantitative triangulation. Bottom-up unit economics and top-down category sizing were reconciled across analysis approaches.
Variance decomposition across product type, material grade, size specification, and end-user segment shaped projection architecture. CAGRs were derived from segment-level demand elasticity modeling and replacement cycle velocity analysis. Ceramic thermal performance benchmarks, steel weight reduction trajectories, and municipal ordinance diffusion patterns informed scenario weighting throughout the forecast period.
Material uncertainties — refractory clay deposit depletion rates, master kiln operator retirement waves, and balcony grilling ordinance enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and consumer preference persistence. Recalibration cycles align with material shifts in EPA guidelines and EU Green Deal implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Rice Cooker Market
Food Service
India Inflight Catering Market
Food Service
Shaker Bottles Market
Food Service
Restaurant Takeout Market
Food Service
Global Sushi Restaurants Market
Food Service
Global Waffle Maker Market
Food Service
Global Vending Machine Market
Food Service
Food Service Pasta Market
Food Service
GCC Online Grocery Market
Food Service
Mobile Food Services Market
Food Service
Gourmet Street Food Market
Food Service
Countertop Pressure Fryer Market
Food Service
Gas Fryers Market
Food Service
Bottled Water Cooler Market
Food Service
Food Away from Home Market
Food Service
Egypt Food Service Market