
 Europe Blueberry Market | 2026-2036
Europe Blueberry Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blueberry Market Analysis
Spanish and Portuguese berry growers is realigning toward year-round greenhouse production to offset seasonal import dependence. Driscoll's leverages proprietary cultivar development to sustain premium positioning across Northern European retail channels. Hortifrut anchors its competitive stance through integrated sourcing from its Peruvian and Moroccan farm networks. Atlantic Blue specializes in organic and conventional fresh segments, occupying a distinct niche in Iberian Peninsula distribution.
Europe blueberries encompass Vaccinium corymbosum and related species cultivated for fresh consumption, processing, and nutraceutical extraction, typically harvested at 10-14°Brix soluble solids for optimal shelf stability and flavor retention. Fresh blueberries dominate value capture due to per-unit premiums and shorter supply chains, while frozen blueberries represent the fastest-expanding preservation format driven by industrial bakery and smoothie manufacturing demand. The foodservice end user segment channels substantial volume through centralized procurement agreements with hotel and restaurant chains, whereas nutraceutical applications extract anthocyanin compounds for supplement formulations.
EU Green Deal agricultural standards and EFSA residue monitoring protocols shape cultivation practices, mandating integrated pest management and traceability documentation for market access. REACH chemical regulations and national implementations of the EU F-Gas Regulation constrain cold chain infrastructure choices, elevating compliance costs for storage and transport operators. Stakeholders must monitor evolving CSRD sustainability disclosure requirements and their downstream effects on procurement specifications from major retail consolidators.
Market Dynamics
EU Green Deal agricultural mandates are compressing cultivation timelines while forcing capital redeployment toward integrated pest management and water-efficient infrastructure across Iberian and Northern European growing regions.
Growth Catalysts
- REACH chemical regulations:ECHA's residue limits are accelerating adoption of biological pest control agents among Dutch and Polish growers, opening premium retail slots for compliant output.
- Foodservice procurement centralization:Hotel and restaurant chains across Germany and France are consolidating blueberry purchasing through dedicated produce distributors, stabilizing offtake volumes.
- Controlled-environment agriculture:Spanish greenhouse operators are deploying supplemental LED lighting to extend harvest windows, reducing import dependence during traditional off-seasons.
Market Restraints
- Moroccan supply concentration:European processors rely on single-origin frozen fruit from Moroccan farm networks, exposing margin stability to North African climatic volatility and logistics bottlenecks.
- F-Gas Regulation compliance costs:Cold chain operators face elevated capital requirements for replacing hydrofluorocarbon-based refrigeration with approved alternatives under EU phase-down schedules.
- Anthocyanin extraction substitution:Synthetic colorant alternatives from fermentation-derived sources are capturing share in industrial bakery applications where visual specification tolerates non-fruit inputs.
Strategic Opportunities
- Portuguese organic acreage expansion:Underdeveloped certified organic hectarage in the Alentejo region offers first-mover positioning for growers meeting EFSA traceability documentation standards.
- Nutraceutical anthocyanin isolation:Supplement formulators in Switzerland and Germany are contracting dedicated high-pigment cultivar blocks for standardized extract production.
- CSRD disclosure tailwinds:Large retail consolidators are rewriting procurement specifications to favor suppliers with documented carbon footprinting, advantaging early-compliant Iberian operations.
Industry Challenges
- Integrated pest management expertise scarcity:Growers transitioning from conventional chemistries face recruitment difficulties for agronomists trained in biological control agent deployment and monitoring protocols.
- Multi-year cultivar conversion capex:Shifting highbush blocks to proprietary licensed varieties requires upfront licensing fees and extended non-productive establishment periods before commercial harvest.
- EFSA residue testing timeline compression:Batch release delays at analytical laboratories are extending inventory holding periods for exporters targeting just-in-time retail replenishment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blueberry Market |
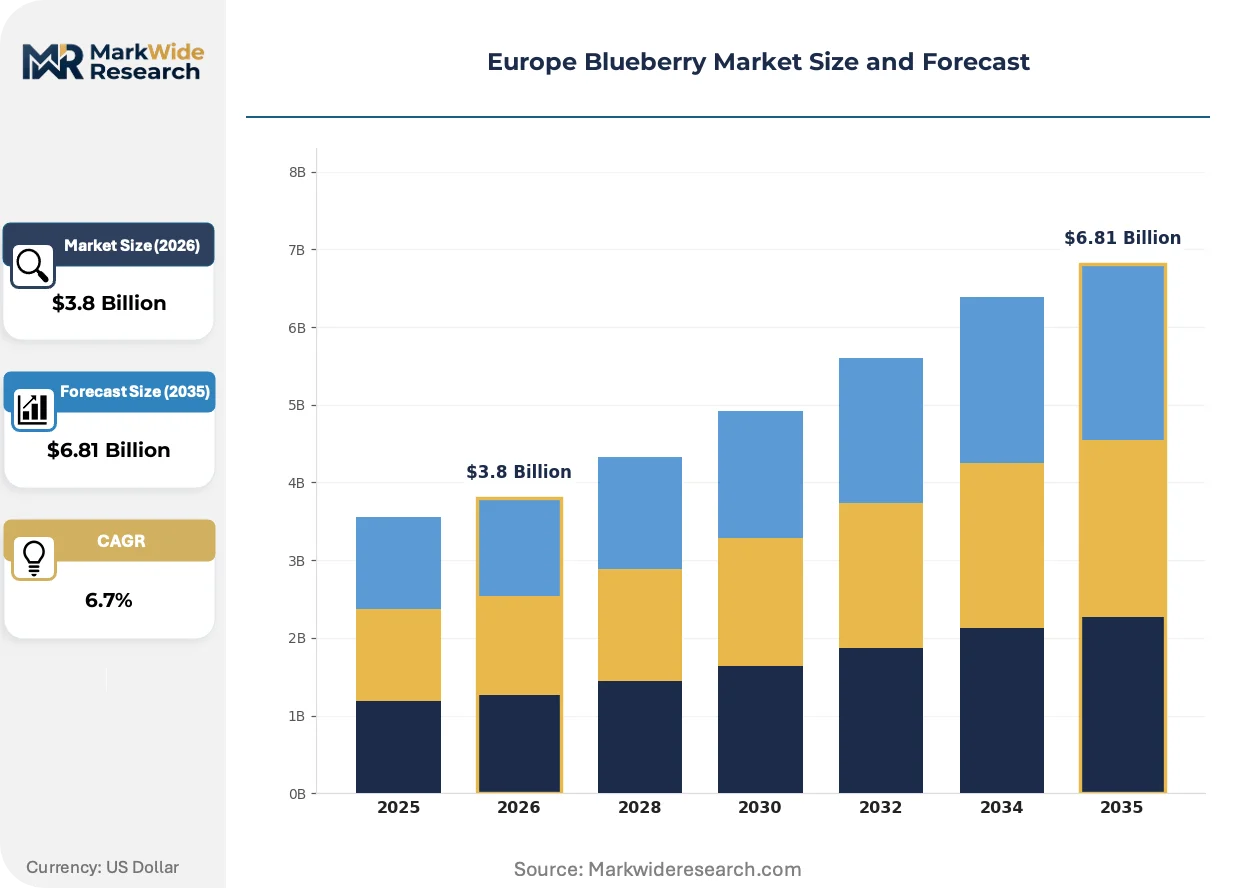
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Blueberries, Frozen Blueberries, Dried Blueberries, Blueberry Purée Distribution Channel: Supermarkets, Online Retail, Direct Sales, Farmers' Markets End User: Food Industry, Retail Consumers, Foodservice, Nutraceuticals Packaging Type: Plastic Containers, Vacuum Sealed Bags, Glass Jars, Cardboard Boxes |
| Companies Covered | Blue Diamond Growers, Berries South Africa, Hortifrut, Fresh Del Monte Produce, Dole Food Company, Driscoll's, Atlantic Blue, Naturipe Farms, Fall Creek Farm & Nursery, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blueberry Market Emerging Trajectories
Biological cultivation protocols and digital monitoring infrastructure are displacing conventional management practices across European blueberry operations, while regulatory disclosure requirements reshape downstream procurement specifications.
Precision irrigation systems with soil-moisture sensor networks are absorbing capital allocation from traditional overhead sprinkler infrastructure. Dutch and Belgian growers deploying these systems report water use efficiency gains that satisfy EU Green Deal sustainability metrics. The technology is absorbing compliance verification burdens that previously required manual documentation, compressing audit preparation cycles for export certification.
CSRD sustainability disclosure mandates are forcing retail consolidators to demand granular farm-level carbon and water data from suppliers. EFRAG implementation guidance requires scope 3 emissions reporting that captures agricultural input footprints. German and French supermarket chains are responding by tiering supplier contracts around verified environmental performance, with preferential shelf placement contingent on documented integrated pest management adoption.
Centralized procurement by foodservice aggregators is consolidating buyer power across European hospitality channels. Traditional wholesale market intermediaries in Italy and Spain are losing volume to direct contracts between grower cooperatives and restaurant chain headquarters. This concentration is most visible in Germany, where hotel breakfast program specifications now bypass regional distributors in favor of national produce agreements with traceability guarantees.
Europe Blueberry Market Segmentation
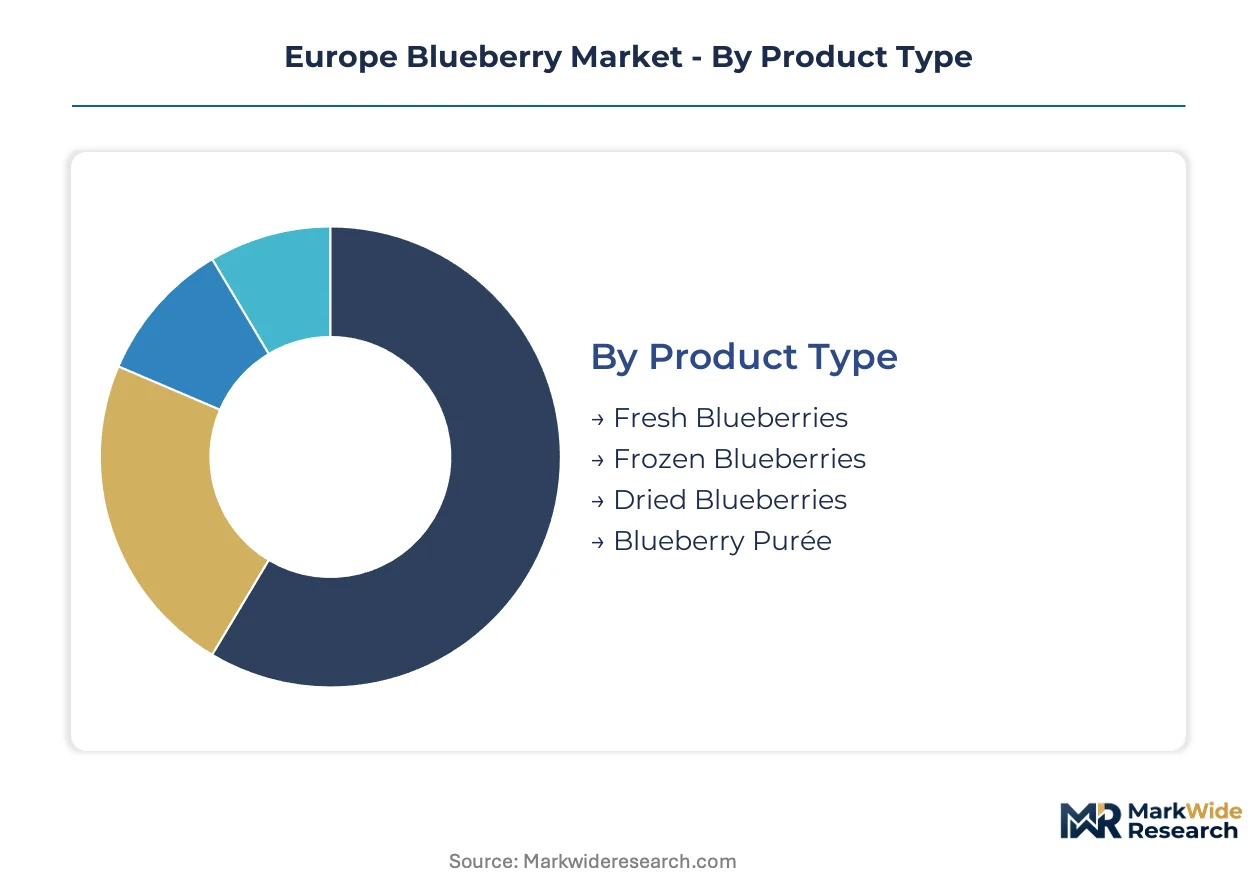
European blueberry segmentation reveals divergent margin profiles across preservation formats and channel structures. Fresh and frozen formats command distinct supply chain investments, while foodservice and nutraceutical end uses impose contrasting specification regimes on growers.
Product Type:
Standardization dominates at the commodity frozen tier, while fresh blueberries carry customization through cultivar selection and harvest-timing protocols.
- Fresh Blueberries:Harvested at 10-14°Brix soluble solids for shelf stability, these berries move through rapid-turn retail and foodservice channels in Germany and France. Premium positioning depends on licensed proprietary cultivars and cold-chain integrity under EU F-Gas Regulation compliance.
- Frozen Blueberries:Industrial processors in Poland and the Netherlands drive volume, with Moroccan farm networks supplying bulk raw material for bakery and smoothie manufacturing. IQF technology preserves cellular structure for downstream formulation flexibility.
- Dried Blueberries:Snack and cereal ingredient applications concentrate demand through German retail consolidators.
- Blueberry Purée:Beverage and baby food manufacturers in Spain and Italy specify aseptic packaging for extended ambient stability.
Leading the category by volume: Frozen Blueberries. Expanding most quickly: Fresh Blueberries.
Distribution Channel:
Cost-to-serve economics separate centralized supermarket procurement from fragmented direct sales infrastructure.
- Supermarkets:German and French retail chains anchor continental volume through national produce agreements with traceability guarantees. CSRD disclosure mandates are rewriting procurement specifications to favor suppliers with documented carbon footprinting.
- Online Retail:Dutch and Belgian e-grocery platforms are absorbing last-mile delivery complexity for time-pressed urban consumers, though cold-chain integrity adds per-unit cost.
- Direct Sales:Grower cooperatives in Portugal's Alentejo region bypass intermediaries for restaurant chain headquarters contracts.
- Farmers' Markets:Seasonal outlets in Italian and Spanish urban centers capture premium positioning through proximity narratives.
Supermarkets dominate absolute volume. Online Retail climbs the fastest as logistics infrastructure matures.
End User:
Application maturity separates established food manufacturing from emerging nutraceutical extraction demand.
- Food Industry:Bakery and dairy processors across Germany and Poland specify frozen fruit for formulation consistency, with anthocyanin retention standards governing supplier qualification.
- Foodservice:Hotel breakfast programs and restaurant chains in Germany now consolidate purchasing through dedicated produce distributors, stabilizing offtake volumes with traceability requirements.
- Retail Consumers:Health-conscious shoppers in France and the Netherlands prioritize antioxidant-rich fresh consumption, driving premium shelf placement.
- Nutraceuticals:Swiss and German supplement formulators contract dedicated high-pigment cultivar blocks for standardized anthocyanin extract production.
Food Industry leads by volume. Nutraceuticals shows steepest expansion trajectory as extraction technology commercializes.
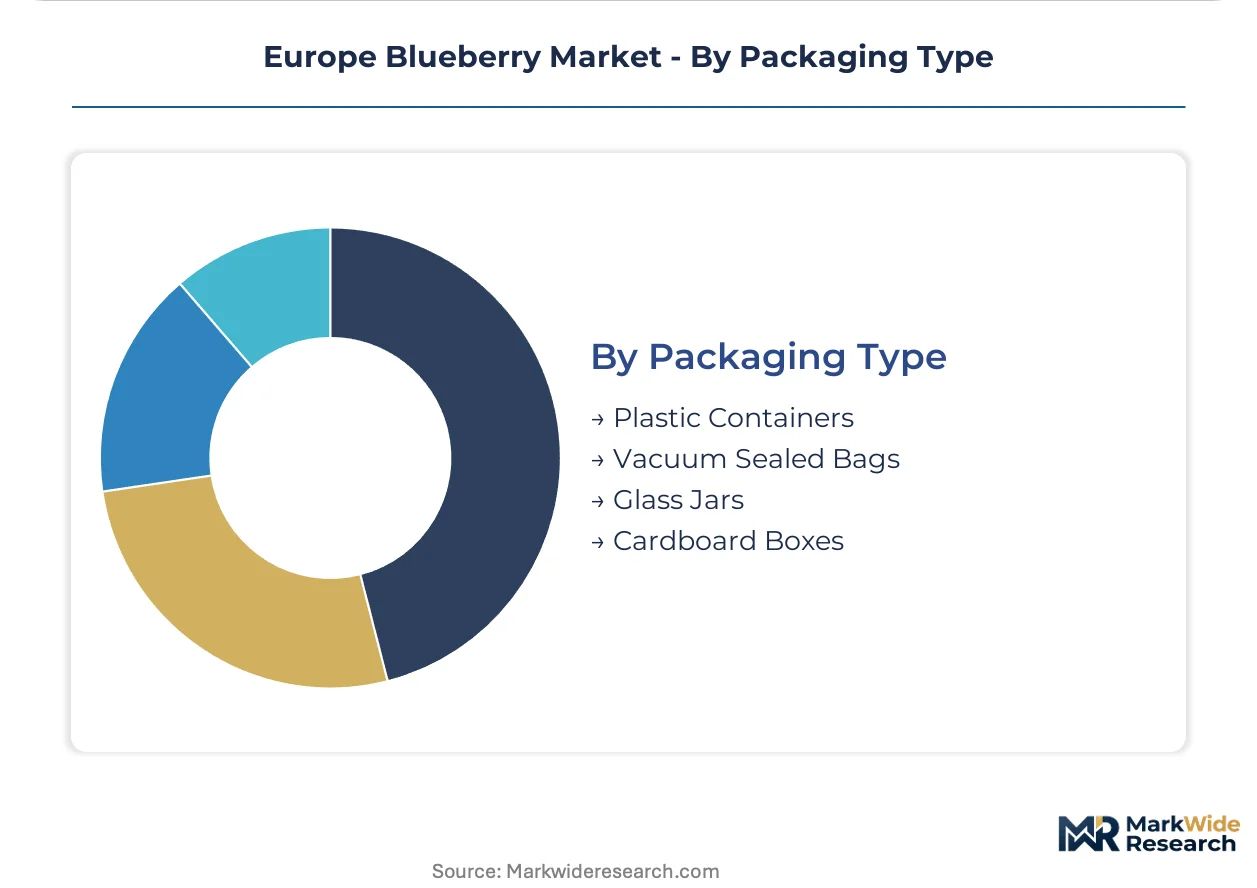
Packaging Type:
Volume scale and margin protection dictate material selection across the shelf-life spectrum.
- Plastic Containers:Clamshell formats dominate fresh retail in German and French supermarkets, with recycled content mandates rising under EU Green Deal circular economy provisions.
- Vacuum Sealed Bags:Modified atmosphere packaging extends frozen blueberry shelf life for industrial bakery customers in Poland and the Netherlands.
- Glass Jars:Premium positioning in Italian and Spanish gourmet retail channels carries higher unit economics and breakage risk.
- Cardboard Boxes:Bulk frozen shipments to processing facilities prioritize cube efficiency over shelf appeal.
Plastic Containers lead by volume. Vacuum Sealed Bags gain share fastest as frozen format penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan farm networks and Iberian greenhouse clusters anchor continental supply during Northern European off-seasons. German retail chains and Polish processing facilities concentrate downstream demand. The EU Green Deal reshapes cultivation protocols across Mediterranean and Atlantic growing zones.
Germany
Hotel breakfast programs and retail chains drive fresh blueberry procurement through national produce agreements with traceability mandates. EFSA residue monitoring protocols govern import acceptance at Rotterdam and Hamburg entry points. Berlin-based foodservice aggregators consolidate purchasing for hospitality chains across the Rhine-Ruhr industrial corridor.
Spain
Greenhouse operators in Almería and Huelva deploy supplemental LED lighting to extend harvest windows and reduce Moroccan import dependence. EU F-Gas Regulation compliance costs elevate cold chain infrastructure investment for Murcia-based exporters. The Valencia logistics cluster channels volume toward French and German supermarket distribution centers.
Poland
Industrial processors in Greater Poland Voivodeship drive frozen blueberry demand for bakery and smoothie manufacturing applications. REACH chemical regulations accelerate biological pest control adoption among Mazovian growers seeking premium retail slots. Warsaw consolidators coordinate frozen fruit shipments from Moroccan farm networks.
Netherlands
Dutch precision agriculture specialists deploy soil-moisture sensor networks to satisfy EU Green Deal water efficiency metrics. Rotterdam cold storage terminals face F-Gas Regulation retrofit timelines for hydrofluorocarbon phase-down. South Holland greenhouse clusters supply year-round volume to Belgian and German retail channels.
Portugal
Alentejo region growers expand certified organic hectarage to capture CSRD-driven procurement preferences from French retail consolidators. EFSA traceability documentation requirements filter export eligibility for Lisbon-area packing facilities. The Ribatejo sub-region attracts capital for integrated pest management infrastructure.
Europe Blueberry Market Vendor Landscape
Global majors compete with regional champions across proprietary cultivar licensing and integrated sourcing networks. The vendor base separates into three tiers: multinational berry marketers with transcontinental farm networks, Mediterranean greenhouse specialists with seasonal window advantages, and cooperative structures with direct foodservice contracts. Two dominant competitive moves reshape positioning: backward integration into licensed variety development and strategic expansion of controlled-environment acreage.
Within the multinational tier, Driscoll's exemplifies proprietary cultivar strategy through premium positioning across Northern European retail channels. Hortifrut anchors integrated sourcing archetypes through Peruvian and Moroccan farm network control. Atlantic Blue occupies a distinct niche position in organic and conventional fresh segments across Iberian Peninsula distribution. These three represent divergent responses to EU Green Deal compliance requirements and CSRD disclosure mandates.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Berries South Africa |
| Hortifrut |
| Fresh Del Monte Produce |
| Dole Food Company |
| Driscoll's |
| Atlantic Blue |
| Naturipe Farms |
| Fall Creek Farm & Nursery |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap growers in Portugal's Alentejo and Spain's Huelva provinces anchor supply discipline through patient capital allocation, insulating pricing from quarterly earnings pressure while concentrating quality premiums among EFSA-certified organic blocks. Their multi-generational ownership horizons compress price volatility during Moroccan import surges, creating tiered margin stability across conventional and certified supply tiers.
Pricing Analysis
Warranty and quality guarantees bundle differently across fresh versus frozen tiers, with German supermarket chains demanding full traceability documentation as a standard inclusion rather than premium add-on. Three-tier pricing structure across premium licensed cultivars, standard highbush varieties, and economy-grade frozen blocks captures value through harvest-timing precision and cold-chain integrity certifications. Pricing pressure stems from Moroccan greenhouse volume expansion during European winter windows, compressing Iberian premium capture. Foodservice aggregators exhibit highest price sensitivity through centralized procurement leverage, while Swiss nutraceutical formulators tolerate steep premiums for standardized anthocyanin content.
Supply Chain Analysis
EFSA residue documentation and EU Green Deal traceability standards gate market access, filtering export eligibility through certified packing facilities in Lisbon, Valencia, and Rotterdam. Supply concentrates in Morocco, Spain, and Portugal for fresh winter volume, with Poland and the Netherlands anchoring frozen processing capacity. Cultivar licensing fees, supplemental LED infrastructure, and biological pest control inputs constitute critical cost dependencies. Single-origin Moroccan concentration exposes margin stability to North African climatic volatility and logistics bottlenecks. Distribution runs through Rotterdam cold storage terminals and German retail consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic hectarage scarcity in Portugal's Alentejo and Ribatejo sub-regions props pricing premiums, constraining rapid supply response to foodservice and nutraceutical demand expansion.
For Market Incumbents: Lock in proprietary cultivar licensing agreements with Fall Creek Farm & Nursery and Driscoll's genetics programs to defend premium positioning against Moroccan volume competition. Secure backward integration into controlled-environment greenhouse acreage in Huelva and Almería to compress seasonal import dependence. Prioritize EFSA traceability documentation infrastructure to capture CSRD-driven procurement preferences from German retail consolidators. For New Entrants and Emerging Players: Enter via Portuguese organic certification programs in underdeveloped Alentejo hectarage, exploiting first-mover positioning before incumbent capacity expansion. Target Swiss and German nutraceutical formulators with dedicated high-pigment cultivar blocks, the most penetrable premium segment. Deploy direct foodservice contracts with hotel breakfast program aggregators as primary go-to-market channel, bypassing wholesale intermediary compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor Mediterranean greenhouse operators with EU F-Gas Regulation-compliant cold chain infrastructure and existing EFSA certification documentation. Five-to-ten-year viability hinges on water rights security under EU Green Deal agricultural mandates. Watch Moroccan climatic volatility indices and Iberian reservoir levels as inflection indicators for supply-constrained pricing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Cultivar Licensing | Driscoll's genetics programs command premium shelf placement in German and French retail chains. |
| Controlled-Environment Expansion | Spanish LED-supplemented greenhouse acreage reduces Moroccan import dependence during winter windows. |
| Organic Certification Investment | Alentejo region growers capture CSRD-driven procurement preferences from French retail consolidators. |
| Direct Foodservice Contracting | Bypassing Italian and Spanish wholesale intermediaries stabilizes offtake volumes with traceability guarantees. |
| Nutraceutical Supply Agreements | Swiss supplement formulators contract dedicated blocks for standardized anthocyanin extract production. |
Methodological Framework
EU agricultural statistics, EFSA residue monitoring databases, and customs trade records formed the secondary backbone, cross-referenced against primary interviews with Spanish greenhouse operators, Portuguese organic certifiers, German supermarket category buyers, Dutch cold storage terminal managers, and Swiss nutraceutical formulators. Bottom-up hectarage and yield estimates triangulated against top-down consumption surveys across the analysis window.
Historical production trendlines across Moroccan, Spanish, and Portuguese growing regions informed projection frameworks, with segmentation modeling across fresh, frozen, dried, and purée formats plus foodservice, retail, and nutraceutical end uses. CAGRs derived from volume-weighted average growth across preservation formats and channel structures, incorporating EU Green Deal compliance cost trajectories and F-Gas Regulation retrofit timelines as structural inputs.
Revisions become necessary when Moroccan climatic shocks, EFSA residue protocol amendments, or CSRD disclosure requirement expansions materialize beyond modeled assumptions. Forecasts reflect documented supply concentration risks and regulatory compliance cost trajectories. A model refresh is warranted upon material change in Iberian water allocation policies or German retail consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Jujube Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
North America Olive Market