
 North America Pea Protein Ingredients Market | 2026-2036
North America Pea Protein Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pea Protein Ingredients Market Analytics
The gap between premium isolate grades and commodity flour tiers is broadening as food manufacturers impose stricter solubility and color specifications on higher-purity inputs. Cargill, Incorporated leverages its North American oilseed infrastructure to secure raw yellow pea supply chains that competitors cannot easily replicate. PURIS Proteins anchors its position through backward integration into organic pea farming across the upper Midwest. Roquette Frères differentiates via proprietary wet-fractionation technology that yields superior emulsion stability in meat analog applications.
Pea protein ingredients comprise protein fractions extracted from Pisum sativum through dry or wet milling, followed by alkaline solubilization and isoelectric precipitation to achieve protein concentrations ranging from 50% in flour to over 85% in isolate form. These ingredients function primarily as emulsifiers, gelling agents, and nutritional fortifiers in formulated foods seeking to replace or extend animal-derived proteins. Isolate commands the dominant margin pool due to its functional superiority in beverages and dairy alternatives, while textured formats are gaining traction fastest among meat alternative processors seeking fibrous mouthfeel replication. Concentrate occupies a mature middle position serving bakeries and snack manufacturers where cost sensitivity outweighs performance demands.
The FDA oversees allergen disclosure requirements for pea-derived ingredients under the Food Allergen Safety, Treatment, Research, and Education Act, while Health Canada mandates bilingual labeling and purity standards through its Food Directorate. USDA Organic certification and Non-GMO Project verification create dual gatekeeping layers that determine channel access for premium-positioned suppliers. Stakeholders must monitor evolving positions from both regulators on novel protein safety assessments as cell-cultured and precision-fermented alternatives enter competitive framing.
Market Dynamics
The FDA's updated allergen labeling guidance for legume-derived ingredients is tightening compliance requirements and forcing suppliers to reconfigure certification workflows, while plant-based meat manufacturers accelerate isolate-grade purchases that concentrate demand in specific processing corridors.
Growth Catalysts
- Regulatory clarity from FDA:The Food Allergen Safety, Treatment, Research, and Education Act provides a federal framework that reduces state-by-state labeling fragmentation, enabling standardized interstate distribution of pea protein isolates.
- Meat alternative formulation:Food-tech manufacturers in California's corridor demand higher-purity isolates for fibrous mouthfeel replication in analog products, pulling supply toward isolate-grade capacity expansion.
- Organic certification layering:USDA Organic and Non-GMO Project verification create dual gatekeeping that locks in premium channel access for certified suppliers serving clean-label retail.
Market Restraints
- Yellow pea input volatility:Weather-driven yield fluctuations in the upper Midwest and Canadian prairies create raw material price instability that compresses margin predictability for fractionators.
- Allergen cross-contamination risk:Shared processing infrastructure with major allergens triggers costly segregation protocols and extends batch release timelines under FDA inspection regimes.
- Soy protein substitution:Established soy isolate infrastructure and lower unit economics in mature applications displace pea protein in cost-sensitive bakery and nutrition bar segments.
Strategic Opportunities
- Precision fermentation convergence:Hybrid formulations combining pea protein base with fermentation-derived functional ingredients unlock novel texture profiles that pure plant extracts cannot achieve.
- Midwest processing belt expansion:Underdeveloped fractionation capacity in Nebraska and Iowa offers greenfield sites with proximity to organic pea farming operations and rail-linked distribution.
- IRA clean energy incentives:Renewable energy tax credits reduce operational expenditure for energy-intensive wet-fractionation facilities, improving project returns for new isolate plants.
Industry Challenges
- FDA compliance timeline compression:Accelerated allergen disclosure deadlines strain quality assurance teams and force parallel validation of alternative testing methodologies.
- Fractionation engineer scarcity:Specialized expertise in isoelectric precipitation and membrane filtration for plant proteins remains concentrated among a narrow cohort of process developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pea Protein Ingredients Market |
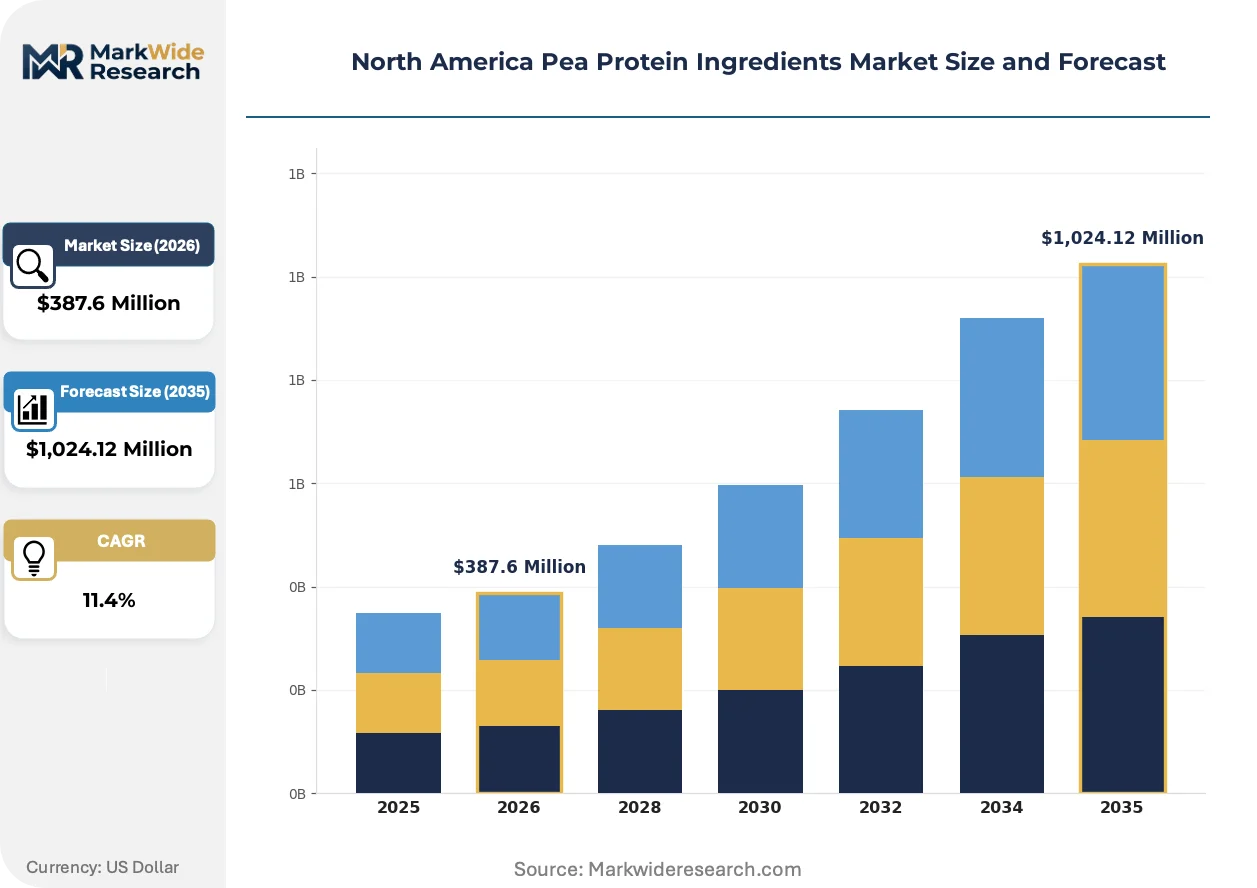
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour Application: Beverages, Snacks, Meat Alternatives, Dairy Alternatives End User: Food Manufacturers, Nutraceutical Companies, Dietary Supplement Providers, Bakeries Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Bunge Limited, Cargill, Incorporated, Ingredion Incorporated, Roquette Frères, Glanbia PLC, The Scoular Company, PURIS Proteins, Axiom Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pea Protein Ingredients Market Evolving Landscape
Wet-fractionation technology is overtaking dry milling as the dominant processing paradigm, while regulatory pressure on allergen disclosure intensifies and procurement patterns among food manufacturers concentrate around functional performance specifications rather than commodity pricing.
Proprietary wet-fractionation systems with closed-loop water recovery are overtaking conventional alkaline extraction in new capacity investments. Meat alternative manufacturers in California and Illinois specify these systems for superior emulsion stability in high-moisture extrusion. The technology is overtaking legacy dry-milled concentrates in premium applications, compressing the addressable market for 50-60% protein flour grades.
Health Canada's bilingual labeling mandate through its Food Directorate is tightening purity standard enforcement for cross-border suppliers. The industrial consequence is accelerated investment in dedicated pea-only production lines to eliminate allergen co-processing risks. Canadian natural health product manufacturers are most affected, responding by sourcing exclusively from facilities with third-party gluten-free and peanut-free certifications.
Direct contracting between isolate-grade suppliers and plant-based meat startups is displacing traditional ingredient distributor relationships. Food-tech ventures in Austin, Toronto, and Los Angeles negotiate multi-year offtake agreements with specified solubility and color metrics. This pattern is most visible in the alternative seafood segment, where fibrous texture requirements demand batch-to-batch consistency that spot market purchasing cannot guarantee.
North America Pea Protein Ingredients Market Segmentation
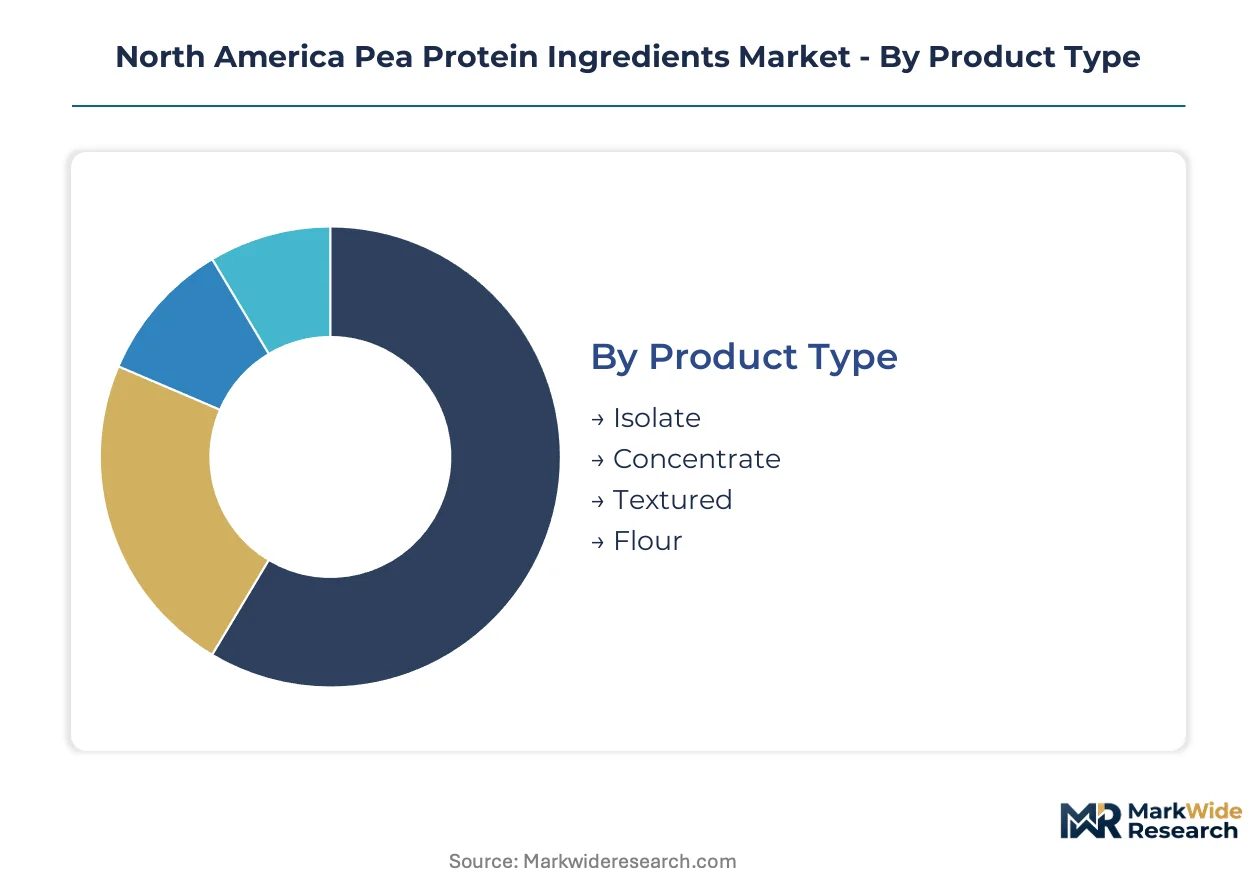
Pea protein ingredient purchasing patterns diverge sharply across functional grades and end-use specifications. Manufacturers in California's food-tech corridor and the Midwest's processing belt drive demand concentration toward isolate-grade materials with defined solubility metrics.
Product Type:
Volume concentrates in commodity flour and concentrate tiers, while premium margins accrue to isolate and textured formats serving performance-critical applications.
- Isolate:Protein concentrations exceeding 85% enable superior emulsion stability in beverages and dairy alternatives. California meat alternative manufacturers specify isolate-grade inputs for fibrous mouthfeel replication in high-moisture extrusion systems. FDA allergen labeling compliance costs compress margins for non-certified suppliers.
- Textured:Extruded formats deliver fibrous structural integrity for plant-based meat applications. Illinois and Texas food-tech ventures negotiate multi-year offtake agreements with specified hydration and bite-force metrics. Wet-fractionation technology investments concentrate capacity expansion in this tier.
- Concentrate:50-70% protein grades serve cost-sensitive bakery and snack applications where functional demands remain moderate.
- Flour:Whole-milled fractions below 50% protein content anchor commodity pricing in animal feed and basic fortification uses.
Today's leader: Isolate. Tomorrow's challenger: Textured.
Application:
Meat alternative formulation pulls supply toward isolate-grade capacity, while beverage applications impose the strictest solubility and color specifications.
- Meat Alternatives:High-moisture extrusion demands batch-to-batch consistency in protein hydration and gelation profiles. Direct contracting between Austin and Toronto startups and fractionators displaces traditional distributor relationships. USDA Organic certification creates channel gatekeeping for clean-label retail placement.
- Beverages:Ready-to-drink formulations require cold-water solubility below 50 microns particle size and neutral flavor masking. Health Canada bilingual labeling mandates tighten purity enforcement for cross-border suppliers.
- Dairy Alternatives:Yogurt and cheese analogs leverage pea protein for gelation and fat mimetic properties.
- Snacks:Puffed and extruded formats utilize concentrate grades where cost sensitivity outweighs performance specifications.
Meat alternatives command premium pricing. Beverages impose the tightest technical barriers to entry.
End User:
Food manufacturers dominate procurement volume, while nutraceutical and supplement channels extract premium pricing for certified organic inputs.
- Food Manufacturers:Plant-based meat and dairy processors in California, Illinois, and Texas drive isolate-grade demand concentration. Multi-year supply agreements with specified functional metrics replace spot market purchasing.
- Nutraceutical Companies:Capsule and powder formulations demand allergen-free certification and third-party gluten-free verification.
- Dietary Supplement Providers:Sports nutrition applications prioritize leucine content and digestibility scores over cost optimization.
- Bakeries:Concentrate grades serve bread and pastry fortification where water absorption and crumb structure matter.
Food manufacturers set volume terms. Nutraceutical companies define certification standards.
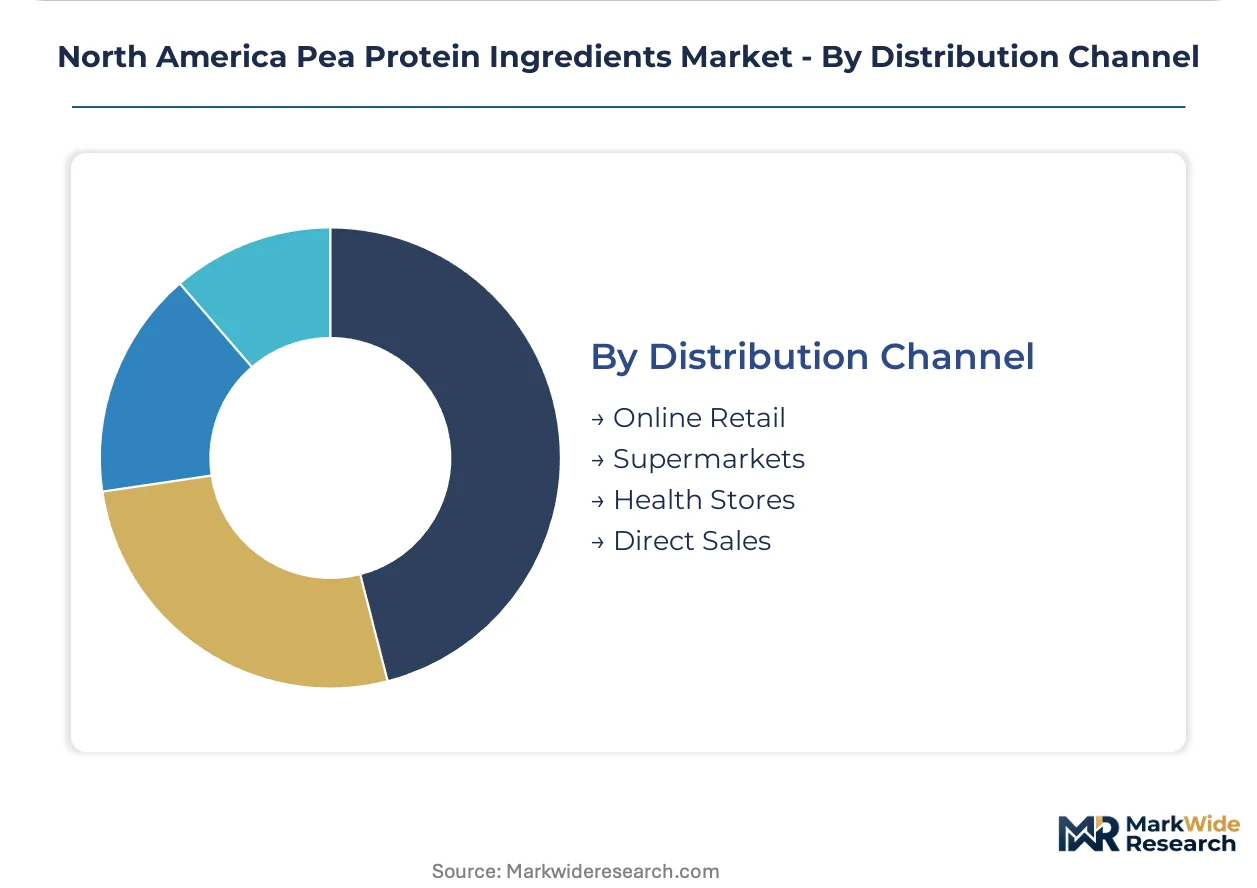
Distribution Channel:
Direct sales capture premium isolate contracts, while online retail expands access for small-batch nutraceutical buyers.
- Direct Sales:Multi-year offtake agreements between fractionators and meat alternative manufacturers specify solubility, color, and microbiological thresholds. Procurement teams in Los Angeles and Toronto negotiate directly with PURIS and Roquette facilities.
- Online Retail:E-commerce platforms enable small nutraceutical and supplement brands to access certified organic isolate in sub-ton quantities.
- Supermarkets:Mass retail channels concentrate flour and concentrate grades for consumer baking and basic fortification.
- Health Stores:Specialty retail prioritizes Non-GMO Project verified and USDA Organic labeled products for clean-label consumers.
Direct sales lock in volume commitments. Online retail fragments the long tail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the dominant share of pea protein ingredient demand, while Canada anchors organic raw material supply chains through prairie farming operations. Mexico's emerging food processing sector presents untapped offtake potential for isolate-grade suppliers.
United States
California's food-tech corridor and Illinois meat alternative manufacturers drive isolate-grade procurement with specified solubility metrics. The FDA's Food Allergen Safety, Treatment, Research, and Education Act tightens labeling compliance for cross-state distribution. Austin and Los Angeles startups negotiate multi-year direct contracts with fractionators for batch-to-batch consistency.
Canada
Prairie organic pea farming in Saskatchewan and Manitoba secures backward-integrated supply for premium ingredient production. Health Canada's Food Directorate mandates bilingual labeling and purity standards that accelerate dedicated production line investments. Toronto food-tech ventures source exclusively from third-party certified gluten-free and peanut-free facilities.
Mexico
Central Mexico's growing meat processing industry creates demand for textured pea protein in hybrid product formulations. The country's national food safety regulator aligns with North American trade standards to facilitate cross-border ingredient flows. Guadalajara and Mexico City food manufacturers test isolate incorporation in traditional protein applications.
North America Pea Protein Ingredients Market Competitive Landscape
Top-tier vendors anchor wet-fractionation capacity, while commodity flour processors occupy downstream tiers. The vendor base stratifies across three functional layers: oilseed conglomerates with captive yellow pea supply, specialist fractionators with proprietary extraction technology, and regional millers serving animal feed and basic fortification. Dominant competitive moves include backward integration into organic farming operations and technology licensing agreements for closed-loop water recovery systems.
Among North American agribusiness conglomerates, Cargill, Incorporated and Archer Daniels Midland Company exemplify scale-driven supply chain control through oilseed infrastructure leverage. Roquette Frères occupies a position representing European technology specialists with proprietary wet-fractionation capabilities. PURIS Proteins anchors the organic-certified tier through in-house farming operations across the upper Midwest. These three archetypes illustrate how competitive positioning diverges between raw material security, processing technology, and certification layering strategies.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bunge Limited |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Roquette Frères |
| Glanbia PLC |
| The Scoular Company |
| PURIS Proteins |
| Axiom Foods, Inc. |
| Others |
Value Network & Pricing Analysis
Wet-fractionation technology adoption is simultaneously compressing production costs for isolate-grade suppliers and concentrating capacity among operators with capital to deploy closed-loop water recovery systems, creating a bifurcation where certified organic processors command pricing power over commodity flour producers.
Pricing Analysis
Contract-based long-term offtake agreements dominate isolate-grade transactions, with price differentiation resting on USDA Organic certification and specified solubility metrics. Three-tier pricing structure across premium, standard, and economy levels separates certified organic isolate from conventional isolate from commodity flour. Cost compression in the flour tier is intensifying because soy protein substitution erodes volume commitments. Bakeries and animal feed formulators exhibit the highest price sensitivity, while California meat alternative manufacturers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
USDA Organic and Non-GMO Project verification create dual gatekeeping that restricts upstream supplier pools to certified prairie farming operations in Canada and the upper Midwest United States. The supply chain draws from yellow pea cultivation in Saskatchewan, Manitoba, and North Dakota, with wet-fractionation inputs including membrane filtration systems and isoelectric precipitation chemicals. Single-source vulnerability concentrates in shared processing infrastructure with major allergens, triggering costly segregation protocols. Distribution runs through direct sales contracts for isolate-grade materials, with commodity flour moving via traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Iowa and Nebraska processing capacity offers lower operational expenditure under IRA clean energy incentives compared to California's food-tech corridor, rewarding fractionators who locate near organic farming operations while serving coastal formulation demand.
For Market Incumbents: Acquire organic pea farming acreage in the upper Midwest to secure captive raw material supply against weather-driven yield volatility. Expand wet-fractionation capacity in rail-linked Nebraska sites to reduce logistics costs for isolate-grade output. PURIS Proteins' backward integration model demonstrates how in-house farming locks in premium channel access.
For New Entrants and Emerging Players: Food-tech distributors in Austin and Toronto represent the most accessible channel partners for isolate-grade market entry. Target Mexico's emerging meat processing sector where textured pea protein demand remains underpenetrated and regulatory alignment with North American standards facilitates cross-border flows. Negotiate white-label supply agreements with established fractionators to bypass capital-intensive processing investments.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional millers serving animal feed and basic fortification, yet these assets face structural displacement from wet-fractionation technology convergence. Mid-cap fractionators with proprietary membrane filtration expertise offer superior long-term viability across a five-to-ten-year window. Monitor FDA positions on novel protein safety assessments as the inflection signal for competitive reframing against cell-cultured alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Farming | PURIS Proteins secures non-replicable raw material security through upper Midwest acreage control. |
| Wet-Fractionation Capacity Expansion | Roquette Frères leverages proprietary technology to meet California meat alternative manufacturers' emulsion stability specifications. |
| Direct Sales Contracting | Isolate suppliers displace distributors by negotiating multi-year offtake agreements with Austin and Los Angeles startups. |
| IRA Clean Energy Facility Siting | Renewable tax credits improve project returns for Nebraska and Iowa wet-fractionation plant investments. |
| Allergen-Free Certification Investment | Third-party gluten-free and peanut-free verification unlocks Toronto nutraceutical manufacturer procurement. |
Research Methodology
Direct dialogue with fractionation plant managers, organic farming cooperative representatives, food-tech procurement leads, and FDA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from USDA Organic certification databases, FDA Food Allergen Safety Act guidance documents, Health Canada Food Directorate labeling mandates, and rail freight flow data. Bottom-up and top-down triangulation reconciled capacity expansion announcements with end-use demand modeling across meat alternative, beverage, and nutraceutical channels.
Bottom-up volume modeling tracked isolate, textured, concentrate, and flour grades through application-specific demand curves, while top-down analysis anchored aggregate market expansion to protein substitution trends in animal-derived categories. Segmentation dimensions included product type, application, end user, and distribution channel, with organic certification status as a cross-cutting qualifier. CAGRs were derived from curve-fitting historical procurement patterns against projected plant-based meat capacity additions. Forecast inputs incorporated wet-fractionation technology adoption rates and IRA incentive program participation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA positions on legume allergen disclosure and precision fermentation competitive entry. Model assumptions reflect documented regulatory frameworks and disclosed capacity investments. A model refresh is warranted upon material change in FDA novel protein safety assessment timelines or significant Midwest organic pea crop failure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Superfood Powders Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market