
 Adulteration Tester Market | 2026-2036
Adulteration Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Adulteration Tester Market Outlook
Aftermarket service revenue is reconfiguring margin pools away from hardware sales toward calibration contracts and remote diagnostics. Thermo Fisher Scientific leverages its installed base of laboratory instruments to lock in recurring service streams. Agilent Technologies anchors its position through chromatography platform standardization across pharmaceutical quality labs. PerkinElmer differentiates by specializing in spectroscopy modules tailored for food authenticity verification.
An adulteration tester is an analytical instrument or consumable kit designed to detect fraudulent substitution, dilution, or contamination in raw materials and finished products, typically achieving detection thresholds in the parts-per-million to parts-per-billion range depending on the matrix and analyte. The device serves industrial and regulatory users by preventing economic fraud, protecting public health, and ensuring label-claim compliance across supply chains. Digital analyzers now capture the dominant share of product-type revenue as laboratories automate high-throughput screening workflows. Chromatography and spectroscopy technologies command premium positioning due to their specificity in complex matrices like botanical extracts and refined oils. Chemical reagents retain volume leadership in field-deployed manual testing where infrastructure constraints limit capital equipment adoption.
The FDA enforces food safety modernization requirements that mandate hazard analysis and preventive controls, directly expanding demand for in-house adulteration screening capabilities among US food manufacturers. EFSA and national regulators under the EU Green Deal framework are tightening authenticity verification standards for organic and geographical indication products, forcing supply chain investments in traceable testing documentation. China's SAMR has intensified post-market surveillance of infant formula and traditional medicine ingredients, accelerating replacement of outdated wet-chemistry methods with certified instrumental platforms. Stakeholders must weigh capital intensity against regulatory audit frequency when selecting between portable field devices and centralized laboratory systems.
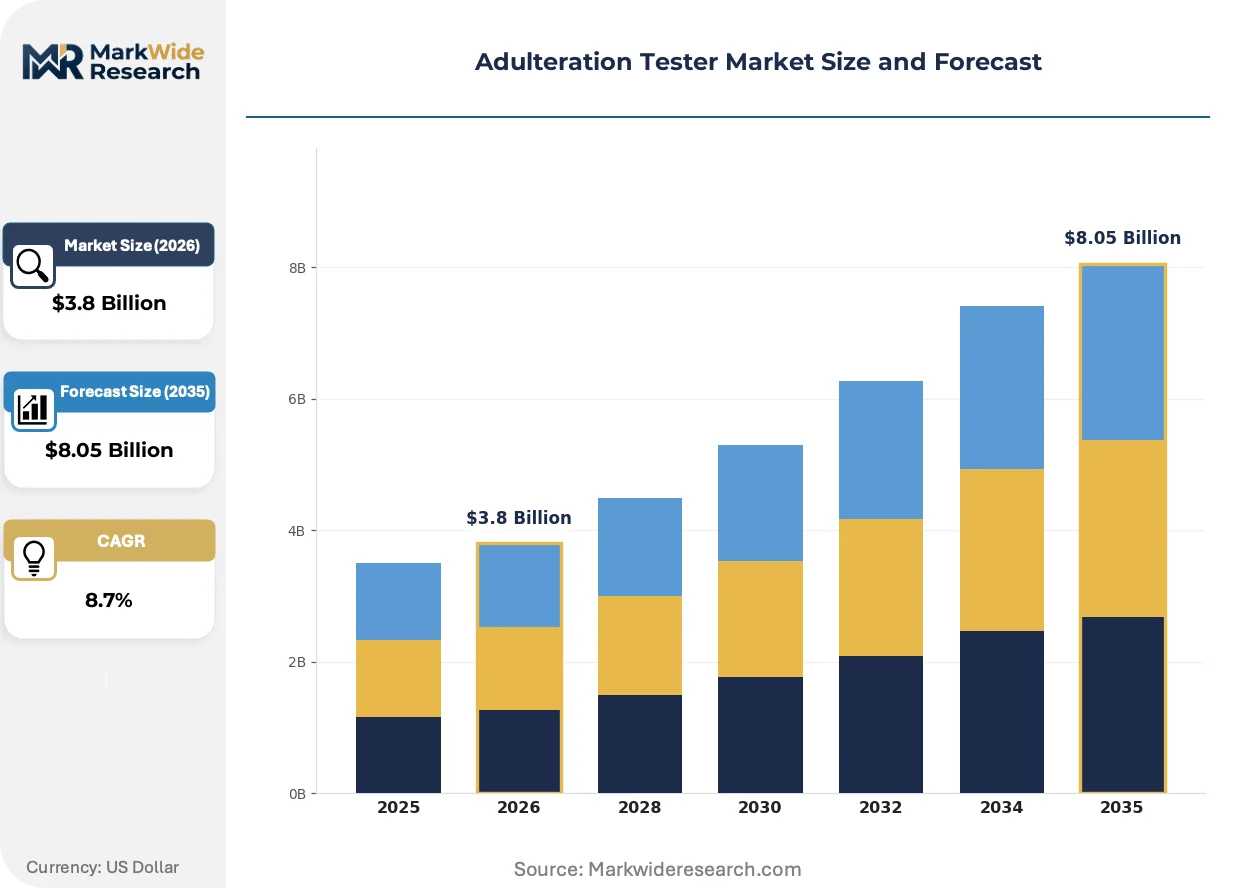
Market Dynamics
Portable sensor miniaturization and AI-integrated detection platforms are compressing detection timelines from days to minutes, forcing capital reallocation away from centralized laboratory infrastructure toward distributed field-deployable systems across food and pharmaceutical supply chains.
Growth Catalysts
- FSSAI mandatory testing protocols:India's food safety regulator mandates systematic adulteration screening for packaged foods and edible oils, compelling domestic manufacturers to expand in-house analytical capabilities beyond third-party outsourcing models.
- Pharmaceutical export corridors:India's API and formulation export hubs require certified instrumental platforms to meet US FDA and EMA documentation standards for batch release and customs clearance.
- AI-integrated spectroscopy:Machine learning algorithms trained on spectral libraries enable non-expert operators to identify complex adulterants in botanical extracts and refined oils without chromatographic separation.
Market Restraints
- Reference standard costs:Certified reference materials for adulterant quantification command premium pricing, particularly for rare botanical markers and emerging synthetic substitutes, elevating per-test consumable expenses.
- Capital intensity of chromatography:High-performance liquid chromatography and mass spectrometry platforms require substantial upfront investment plus controlled-environment infrastructure, limiting adoption in resource-constrained field settings.
- Regulatory fragmentation:Divergent certification requirements between China's SAMR, India's FSSAI, and US FDA create compliance complexity for multinational manufacturers seeking harmonized testing protocols.
Strategic Opportunities
- Rural dairy cooperatives:India's cooperative dairy sector remains underpenetrated by instrumental platforms, presenting white space for portable milk adulteration detectors with simplified user interfaces and localized calibration.
- EU Green Deal traceability mandates:EFSA's tightening authenticity verification for organic and geographical indication products forces supply chain investments in documented testing workflows, creating demand for integrated data-logging systems.
- Blockchain-converged verification:Integration of spectroscopic fingerprints with distributed ledger technology enables immutable provenance records, commanding premium positioning in high-value botanical and specialty food segments.
Industry Challenges
- Spectroscopy expertise scarcity:Interpretation of complex spectral data requires analytical chemists with matrix-specific training, creating recruitment bottlenecks for quality control departments in secondary cities and rural processing zones.
- Legacy wet-chemistry integration:Established facilities face operational friction when retrofitting automated digital platforms alongside manual titration and colorimetric workflows, disrupting standard operating procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adulteration Tester Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Test Kits, Digital Analyzers, Mobile Devices, Laboratory Instruments Technology: Chromatography, Spectroscopy, Sensors, Chemical Reagents End User: Manufacturers, Quality Control Labs, Research Institutions, Food Safety Agencies Application: Food & Beverage Testing, Pharmaceutical Testing, Chemical Analysis, Environmental Monitoring |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Inc., PerkinElmer Inc., Shimadzu Corporation, Bruker Corporation, Waters Corporation, Eurofins Scientific SE, Merck KGaA, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adulteration Tester Market Strategic Shifts
Miniaturized detection hardware and cloud-connected analytics are compressing the traditional laboratory-to-field capability gap, enabling real-time supply chain verification without sample transport delays or centralized processing bottlenecks.
Handheld Raman and near-infrared spectrometers is collapsing the cost and expertise barriers that previously confined high-specificity testing to centralized laboratories. Dairy processors in China's Hebei and Shandong provinces deploy these devices at receiving docks to screen incoming raw milk for melamine, urea, and synthetic protein adulterants before unloading. The technology compresses detection turnaround from 48-hour laboratory queues to 30-second dockside decisions, eliminating rejected batch holding costs and enabling supplier payment release upon immediate clearance.
China's SAMR intensified post-market surveillance of infant formula and traditional medicine ingredients through mandatory batch-testing documentation and unannounced facility inspections. The policy forces domestic manufacturers to replace outdated wet-chemistry methods with certified instrumental platforms traceable to national metrology standards. Infant formula producers in Heilongjiang and Inner Mongolia now face audit failure risk if unable to produce chromatographic or spectroscopic data packets for every production lot, accelerating capital deployment toward integrated laboratory information management systems.
Service unbundling from hardware sales is restructuring buyer-supplier relationships across pharmaceutical quality laboratories. Thermo Fisher Scientific and Agilent Technologies now offer calibration contracts and remote diagnostics as standalone subscriptions, decoupling recurring revenue from new instrument placement cycles. This model penetrates most deeply in India's pharmaceutical export corridor, where US FDA inspection frequency and EMA audit requirements create persistent demand for uptime guarantees and documented maintenance records independent of capital expenditure timing.
Adulteration Tester Market Segmentation
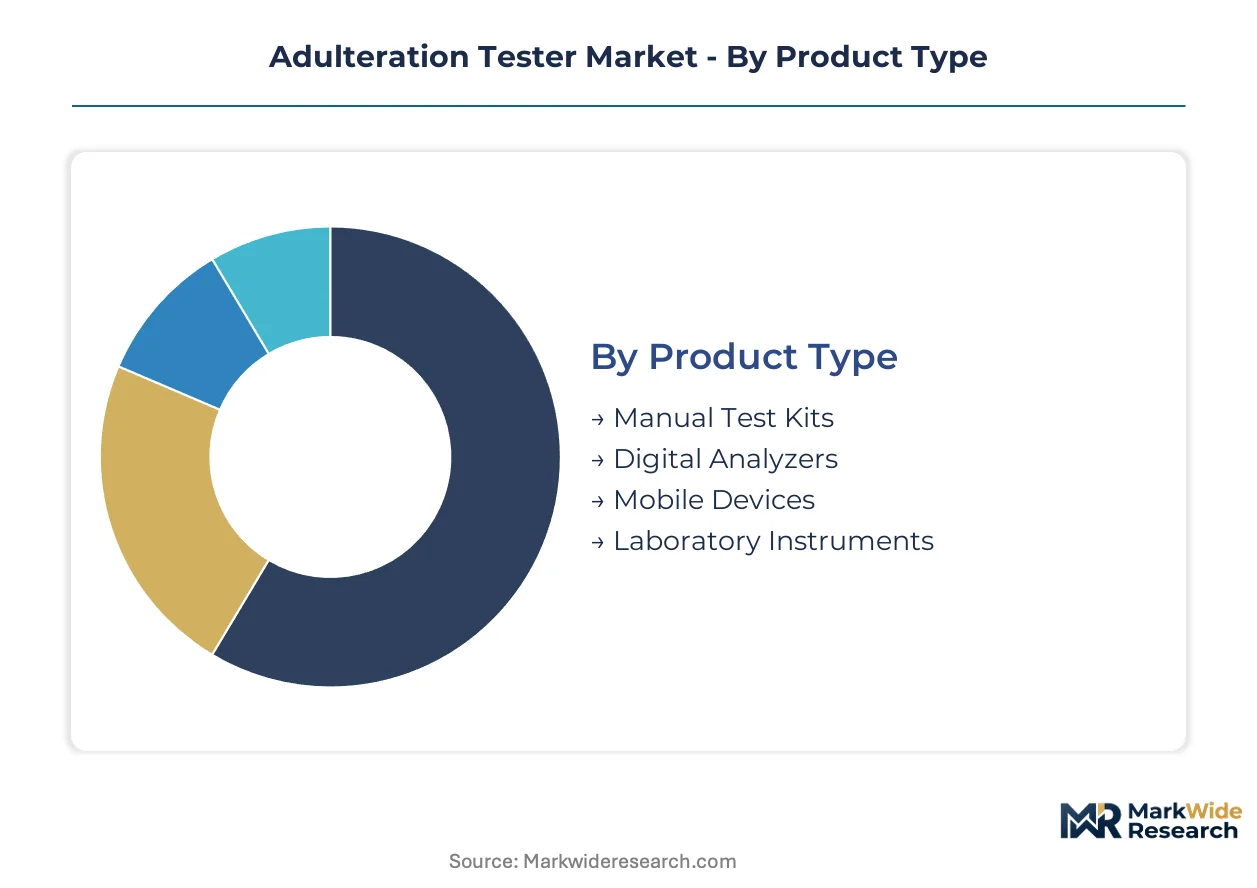
Adulteration testing requirements diverge sharply between rapid field screening and laboratory-grade quantification, driving distinct procurement patterns across product categories. Technology selection hinges on detection threshold specifications, operator expertise availability, and regulatory documentation mandates.
Product Type:
Portable solutions dominate field deployments where infrastructure constraints limit capital equipment adoption, while centralized laboratories prioritize throughput and regulatory traceability.
- Digital Analyzers:Automated platforms integrate spectroscopic or chromatographic modules with embedded software for spectral library matching. Demand concentrates in India's pharmaceutical export corridor where US FDA and EMA documentation standards require batch-release data packets with instrument traceability to national metrology standards.
- Manual Test Kits:Colorimetric and titration-based consumables require minimal operator training and function without electrical infrastructure. These retain volume leadership across Southeast Asian food manufacturing clusters where quality control budgets face capital constraints and wet-chemistry workflows remain entrenched.
- Mobile Devices:Smartphone-connected sensors and handheld Raman units enable dockside screening with cloud data logging.
- Laboratory Instruments:High-performance liquid chromatography and mass spectrometry platforms deliver parts-per-billion detection thresholds for complex matrices.
Established volume favors Manual Test Kits; emerging adoption favors Digital Analyzers.
Technology:
Detection specificity and speed trade-offs determine technology selection across pharmaceutical, food, and environmental applications.
- Spectroscopy:Near-infrared and Raman systems enable non-destructive screening without sample preparation. China's dairy processors in Hebei and Shandong provinces deploy handheld units at receiving docks to screen raw milk for melamine and synthetic protein adulterants before unloading, compressing turnaround from 48-hour laboratory queues to 30-second decisions.
- Chromatography:Liquid and gas chromatography platforms separate complex mixtures with quantitative precision. These command premium positioning in botanical extract verification where EFSA's EU Green Deal authenticity mandates require documented testing workflows for organic and geographical indication products.
- Sensors:Electrochemical and optical miniaturized units target rapid field deployment with simplified user interfaces.
- Chemical Reagents:Wet-chemistry consumables persist where capital equipment adoption faces infrastructure barriers.
Spectroscopy gains share fastest in food authenticity applications; Chromatography anchors pharmaceutical quality control.
End User:
Procurement authority and budget scale vary substantially across integrated manufacturers versus third-party service providers.
- Quality Control Labs:Independent and in-house analytical facilities manage high-throughput screening for multiple clients or production lines. India's FSSAI mandatory testing protocols for packaged foods and edible oils compel domestic manufacturers to expand in-house capabilities beyond third-party outsourcing models.
- Manufacturers:Integrated food and pharmaceutical producers invest in captive testing capacity to protect batch release timelines. China's SAMR intensified post-market surveillance of infant formula forces Heilongjiang and Inner Mongolia producers to deploy certified instrumental platforms with integrated laboratory information management systems.
- Food Safety Agencies:Regulatory bodies conduct surveillance sampling and enforcement testing.
- Research Institutions:Academic and government laboratories develop reference methods and spectral libraries.
Quality Control Labs capture the steepest expansion trajectory; Manufacturers retain the largest installed base.
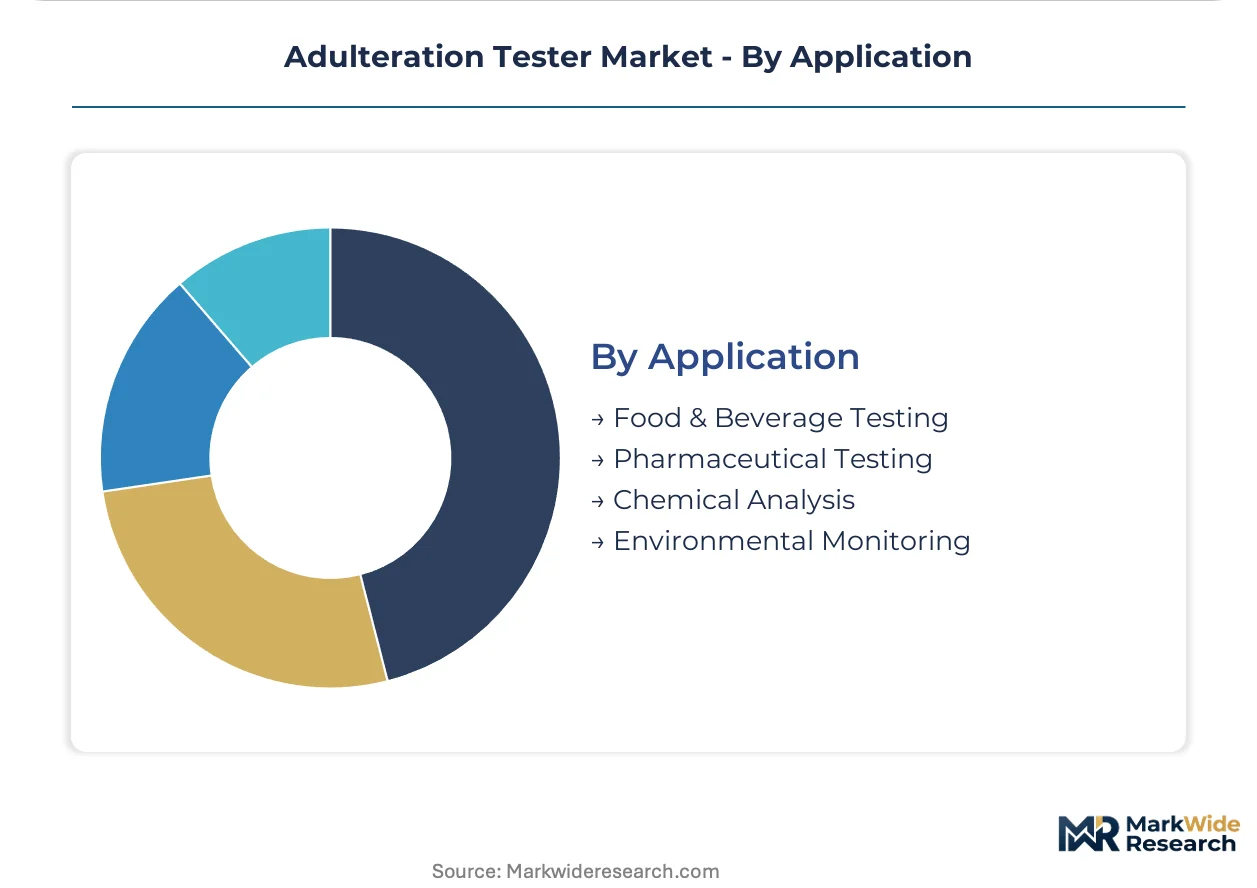
Application:
Regulatory enforcement intensity and supply chain complexity create divergent technology requirements across verticals.
- Food & Beverage Testing:Dairy, edible oil, and botanical extract screening drives portable sensor adoption. China's dairy processing belt and India's cooperative dairy sector present white space for simplified milk adulteration detectors with localized calibration.
- Pharmaceutical Testing:Active pharmaceutical ingredient and formulation verification demands chromatographic specificity. India's API export hubs require certified platforms to meet US FDA and EMA documentation standards for customs clearance.
- Chemical Analysis:Industrial raw material verification spans petrochemical and specialty chemical supply chains.
- Environmental Monitoring:Water and soil contamination screening employs sensor networks and laboratory confirmation.
Food & Beverage Testing leads volume deployment; Pharmaceutical Testing commands highest per-unit pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's cooperative dairy sector exhibit acute price sensitivity, driving manual test kit volumes, while pharmaceutical exporters in Germany and the United States absorb premium chromatography pricing without elasticity.
United States
FDA enforcement of food safety modernization requirements mandates hazard analysis and preventive controls, compelling domestic food manufacturers to expand in-house adulteration screening capabilities. The agency's inspection frequency for pharmaceutical facilities accelerates demand for documented maintenance records and uptime guarantees. Quality control laboratories in New Jersey and Massachusetts anchor the pharmaceutical testing cluster.
China
SAMR intensified post-market surveillance of infant formula and traditional medicine ingredients through mandatory batch-testing documentation. Dairy processors in Hebei and Shandong provinces deploy handheld Raman spectrometers at receiving docks to screen raw milk for melamine and synthetic protein adulterants. The policy forces replacement of wet-chemistry methods with certified instrumental platforms traceable to national metrology standards.
India
FSSAI mandatory testing protocols for packaged foods and edible oils compel domestic manufacturers to expand analytical capabilities beyond third-party outsourcing models. The country's pharmaceutical export corridor requires certified platforms to meet US FDA and EMA documentation standards for batch release and customs clearance. API hubs in Telangana and Gujarat drive chromatography platform deployment.
Germany
EFSA tightening of authenticity verification standards for organic and geographical indication products under the EU Green Deal framework forces supply chain investments in traceable testing documentation. The country's chemical and pharmaceutical manufacturing base sustains demand for high-specificity chromatography and mass spectrometry systems. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate quality control laboratory capacity.
Japan
METI industrial standards and PMDA pharmaceutical regulations enforce stringent contaminant thresholds, sustaining premium positioning for laboratory-grade detection platforms. Food manufacturers face intensifying domestic and export market pressure for documented authenticity verification. The Kanto region around Tokyo anchors both pharmaceutical quality control and food safety testing infrastructure.
Adulteration Tester Market Competitive Environment
Capability concentration sits with laboratory instrument specialists; scale advantage sits with diversified analytical platform conglomerates. The market structures around three tiers: full-platform conglomerates with chromatography and spectroscopy portfolios, mid-scale specialists with modular detection systems, and regional service providers with calibration and maintenance networks. Dominant competitive moves include service unbundling from hardware sales and AI-integrated detection platform development.
Among diversified analytical conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. occupy positions anchoring the premium tier through installed base leverage and recurring service contracts. PerkinElmer Inc. exemplifies the specialist archetype with focused spectroscopy module development. Shimadzu Corporation and Bruker Corporation represent the precision instrument fabrication tier with geographic diversification across Asia-Pacific and European markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| PerkinElmer Inc. |
| Shimadzu Corporation |
| Bruker Corporation |
| Waters Corporation |
| Eurofins Scientific SE |
| Merck KGaA |
| Danaher Corporation |
| Others |
Value Chain & Pricing Dynamics
Shanghai-rotterdam maritime freight corridors transmit cost volatility through spectroscopy module supply chains, compressing margins for chromatography platform distributors while amplifying price differentiation between certified reference material tiers and generic consumable alternatives.
Pricing Analysis
Calibration contracts and remote diagnostics subscriptions now drive lifetime value beyond initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-traceable chromatography systems from FSSAI-compliant field units and unbranded manual test kits. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in economy-tier consumables is intensifying because Indian dairy cooperatives negotiate volume discounts for localized reagent formulations. Pharmaceutical exporters in Telangana and Gujarat exhibit lowest price sensitivity, absorbing premium positioning for EMA-documentation platforms.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities enable Southeast Asian distributors to stock handheld Raman units despite working capital constraints. Manufacturing concentrates in Germany, Japan, and the United States for precision optical components, while China and India dominate electrochemical sensor assembly. Raw material dependencies include rare-earth optical crystals, high-purity silicon photodetectors, and stabilized reagent chemistries. Single-source vulnerability sits with germanium-based infrared detectors from limited foundry capacity. Distribution runs through authorized service networks that bundle installation validation with regulatory documentation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adulteration testing penetration remains below saturation across India's cooperative dairy sector and Southeast Asian food manufacturing clusters, creating runway for portable sensor deployment as FSSAI and SAMR inspection frequency accelerates.
For Market Incumbents: Entrench installed base leverage through multi-year calibration subscriptions that lock pharmaceutical quality labs into recurring revenue streams. Deepen backward integration into certified reference material production to defend margin position against emerging reagent specialists. Threat substitution from AI-integrated smartphone sensors demands accelerated development of cloud-connected analytics platforms. For New Entrants and Emerging Players: Rural dairy cooperatives in India's Maharashtra and Karnataka states represent the most penetrable entry point for simplified milk adulteration detectors with localized calibration protocols. EU Green Deal traceability mandates for organic botanical extracts create secondary white space in documented testing workflows. Go-to-market execution should anchor through regional service partnerships that bundle regulatory documentation training with hardware placement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical conglomerates seeking to divest non-core spectroscopy modules. Long-term viability across the analysis window favors platforms with AI-integrated detection capabilities and recurring service revenue concentration. Acquisition archetypes include mid-scale specialists with modular food-authenticity systems. Monitor SAMR batch-testing documentation enforcement intensity as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Detection Platform Development | Machine learning algorithms trained on spectral libraries enable non-expert operators to identify complex adulterants without chromatographic separation. |
| Calibration Contract Unbundling | Standalone service subscriptions decouple recurring revenue from new instrument placement cycles in India's pharmaceutical export corridor. |
| Blockchain-Converged Verification Integration | Spectroscopic fingerprint linkage with distributed ledger technology commands premium positioning in high-value botanical segments. |
| Rural Dairy Cooperative Penetration | Simplified user interfaces and localized calibration protocols address underpenetrated cooperative sectors in India. |
| Certified Reference Material Backward Integration | In-house production of rare botanical markers defends margin position against consumable cost pressure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports. Quality control laboratory managers, pharmaceutical regulatory affairs leads, food safety agency inspectors, and spectroscopy platform engineers provided operational perspective. Secondary validation drew from FDA warning letters, EFSA scientific opinions, SAMR inspection bulletins, FSSAI compliance circulars, and SEC 10-K instrument segment disclosures. Bottom-up demand modeling triangulated against top-down market sizing across technology and end-user dimensions.
Forecast inputs include instrument placement rates, consumable attach ratios, and service contract renewal probabilities across the projection horizon. Segmentation dimensions span product type, detection technology, end-user category, and application vertical with regional regulatory cluster differentiation. CAGRs were derived from growth driver elasticity analysis and technology substitution curve modeling. Industry-specific inputs incorporate FSSAI mandatory testing protocol implementation timelines and SAMR post-market surveillance inspection frequency.
Practitioners should monitor regulatory enforcement intensity, reference material cost trajectories, and AI-detection accuracy benchmarks for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Meat Speciation Testing Service Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Meat Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
US Consumer Product Safety Testing Market