
 Middle East and Africa Decor Paper Market | 2026-2036
Middle East and Africa Decor Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Decor Paper Market Foresight
Melamine-impregnated paper is restructuring the economics of decorative surfacing across the Middle East and Africa, displacing direct-printed laminates and lower-grade vinyl wraps in cost-sensitive applications. Schattdecor leverages its global design archive to sustain premium positioning in the region's furniture export sector. Ahlstrom-Munksjö anchors technical supply for high-performance grades serving the UAE's hospitality fit-out market. SURTECO GmbH competes through backward integration into base paper production, controlling input costs amid volatile pulp flows.
Decor paper comprises specialty cellulose sheets, typically 60–120 gsm, saturated with thermosetting resins and finished with gravure-printed designs for lamination onto wood-based panels. Its primary purpose is to provide durable, aesthetically controllable surfaces for furniture, flooring, and interior cladding without requiring solid timber or stone. Printed paper dominates volume flows across the region, though specialty paper carries the widest margin pools where anti-microbial or scratch-resistant formulations command specification premiums. The furniture end-use industry leads absolute consumption, while construction-linked laminated paper is growing fastest as Saudi giga-projects and Egyptian social housing expand panelized building methods.
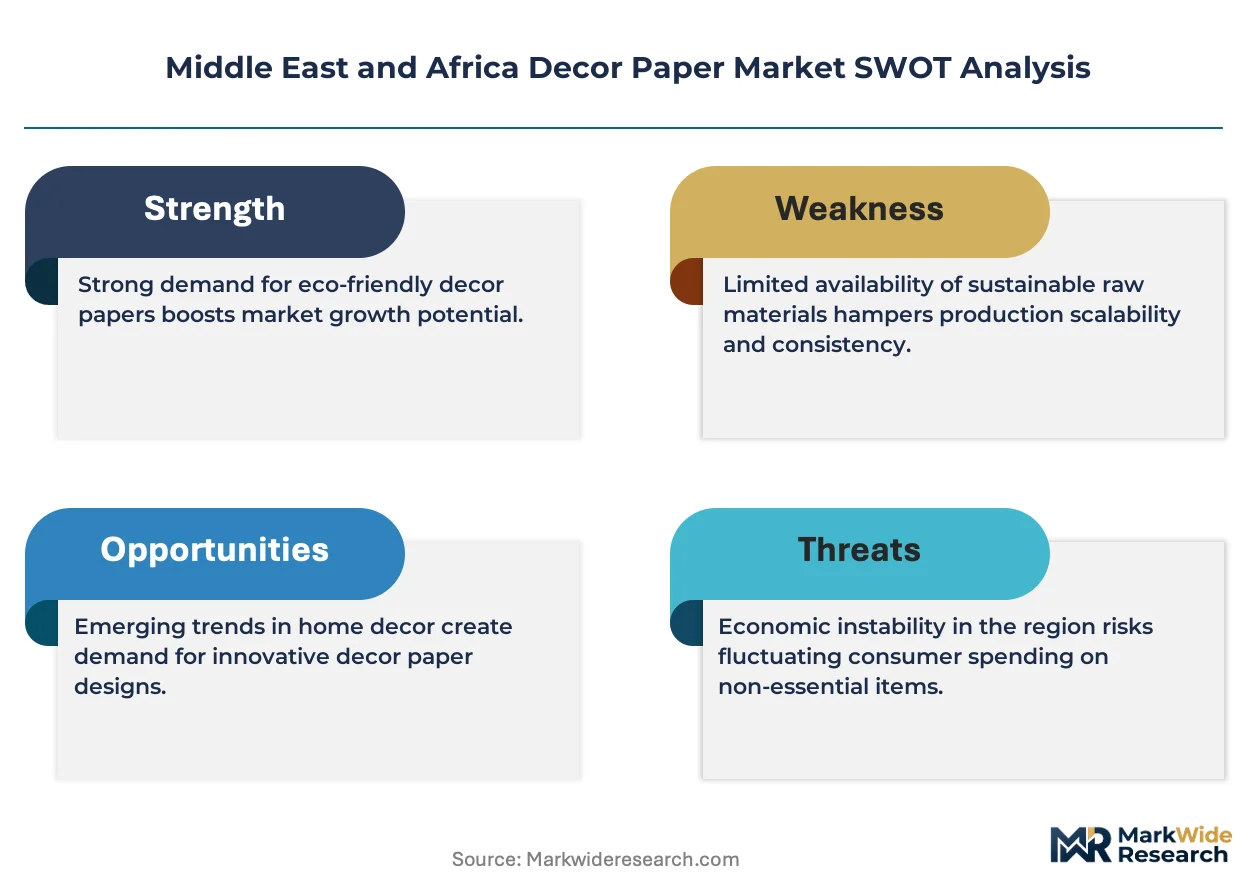
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce formaldehyde emission thresholds that filter import access and favor certified European-origin suppliers. The UAE's Estidama Pearl Rating System extends material disclosure requirements to interior finishes, reshaping procurement specifications for green building compliance. Stakeholders must monitor how Egypt's new industrial licensing framework and Nigeria's nascent standards harmonization alter competitive access across North and West African corridors.
Market Dynamics
Melamine-faced chipboard is displacing solid wood across residential furniture manufacturing in South Africa, compressing demand cycles and forcing decor paper suppliers to align with panel producers' just-in-time resin saturation schedules.
Growth Catalysts
- SASO formaldehyde emission thresholds:Saudi Arabia's tightening standards filter import access, favoring certified European-origin suppliers with established testing protocols.
- Giga-project construction:Saudi Arabia's Riyadh and Jeddah corridor generates sustained offtake for laminated surfacing materials in hospitality and residential towers.
- Gravure-printed design sophistication:Advances in cylinder engraving enable photorealistic wood grain replication at lower cost than veneer alternatives.
Market Restraints
- Pulp price volatility:Specialty cellulose base paper costs fluctuate with global softwood pulp flows, compressing margin pools for non-integrated converters.
- European supplier concentration:Premium decor paper grades rely on a narrow base of certified producers, creating bottleneck risk during demand surges.
- Vinyl wrap substitution:Lower-grade vinyl alternatives capture cost-sensitive flooring applications in North African price-driven markets.
Strategic Opportunities
- Egyptian social housing expansion:Panelized building methods in Cairo and Alexandria corridors create entry points for standard-grade printed paper suppliers.
- Estidama Pearl Rating System:UAE green building codes extend material disclosure requirements to interior finishes, rewarding low-emission resin formulations with specification preference.
- Anti-microbial formulations:Healthcare and hospitality fit-outs in Dubai and Abu Dhabi drive specification premiums for scratch-resistant, hygiene-optimized surfacing.
Industry Challenges
- Resin chemistry expertise gap:Formulating low-formaldehyde melamine-urea systems requires polymer scientists scarce in regional labor markets.
- Estidama certification timelines:Product disclosure documentation and third-party verification extend sales cycles by four to six months for new entrants.
- Legacy panel press incompatibility:Older Saudi and Egyptian chipboard lines lack precision temperature control for thin-paper lamination, limiting grade penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Decor Paper Market |
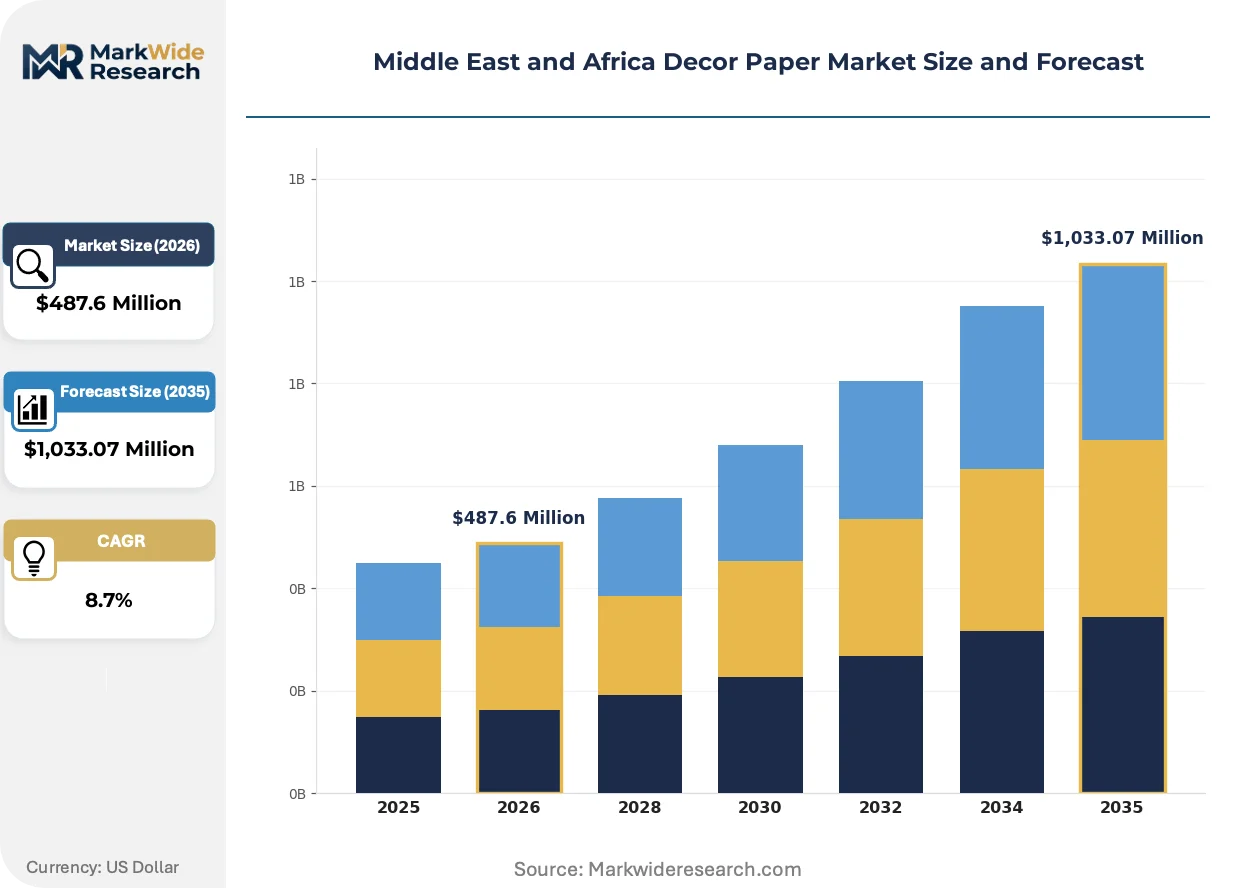
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Paper, Self-Adhesive Paper, Laminated Paper, Specialty Paper End Use Industry: Furniture, Construction, Automotive, Consumer Electronics Thickness: Thin, Medium, Thick, Extra Thick Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | KÄMMERER Paper GmbH, SURTECO GmbH, Ahlstrom-Munksjö, Schattdecor, Felix Schoeller Group, Impress Surfaces GmbH, Stora Enso, TOPPAN INC., CHIYODA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Decor Paper Market Shifts & Advancements
Digital design archives and low-emission resin chemistry are converging to redefine specification criteria across Middle East and Africa construction and furniture manufacturing.
Electron beam-cured coatings are integrating into high-traffic hospitality surfacing specifications. UAE hotel fit-out contractors specify these finishes for lobby and corridor applications requiring abrasion resistance beyond conventional melamine. The technology is integrating scratch-resistant performance into thinner paper gauges, reducing raw material input per square meter while maintaining durability ratings.
Estidama certification requirements are extending from building envelope to interior finish specifications. Developers in Abu Dhabi and Dubai now mandate material disclosure for laminated panels equal to structural components. Hospitality and healthcare verticals face the steepest compliance burden, driving procurement officers toward pre-certified European suppliers with established documentation trails.
Buyer concentration among Saudi giga-project developers is compressing supplier qualification timelines. Emaar, NEOM, and Red Sea Global now require decor paper mills to complete technical audits within ninety days versus historical six-month cycles. This concentration is forcing regional distributors to carry certified inventory on speculation, shifting working capital requirements from manufacturers to channel partners.
Middle East and Africa Decor Paper Market Segmentation
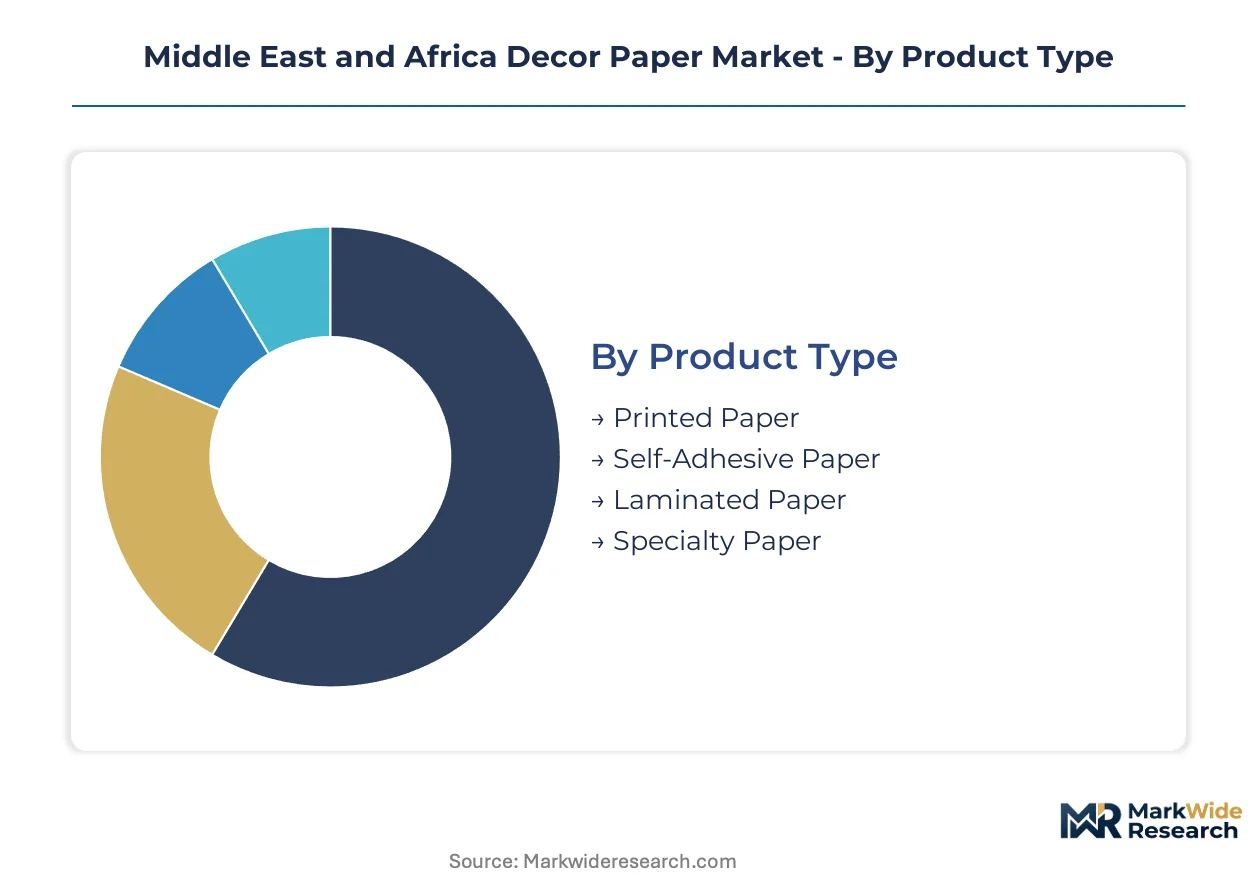
Decor paper suppliers across the Middle East and Africa navigate distinct procurement logics across furniture manufacturers, construction contractors, and automotive tier suppliers. Segment-specific requirements for resin saturation, design fidelity, and emission certification create divergent margin structures that reshape competitive positioning.
Product Type:
Buyers differentiate primarily by surface performance requirements and regulatory compliance burden rather than unit cost alone.
- Printed Paper:Gravure-printed cellulose sheets carry wood-grain and solid-color designs for standard melamine lamination. Demand concentrates in Saudi giga-project panel production where specification volume outweighs premium formulation requirements.
- Laminated Paper:Pre-impregnated sheets with cured resin layers enable single-press application onto chipboard and MDF. Egyptian social housing contractors favor this grade for accelerated construction timelines in Cairo and Alexandria corridors.
- Self-Adhesive Paper:Pressure-sensitive decorative films serve refurbishment and aftermarket applications where hot-press infrastructure is unavailable.
- Specialty Paper:Anti-microbial and scratch-resistant formulations command specification premiums in UAE hospitality fit-outs under Estidama disclosure mandates.
Printed paper leads volumes today; specialty paper is gaining share fastest.
End Use Industry:
Application-specific durability standards and certification timelines segment buyers by procurement sophistication and technical audit tolerance.
- Furniture:Residential and commercial manufacturers specify decor paper for melamine-faced chipboard surfacing. South African producers absorb rising volumes as solid wood displacement accelerates in Johannesburg and Cape Town manufacturing clusters.
- Construction:Panelized building systems in Saudi Arabia's Riyadh-Jeddah corridor generate sustained offtake for laminated surfacing in hospitality and residential towers. NEOM and Red Sea Global procurement compresses supplier qualification cycles.
- Automotive:Interior trim applications require heat-resistant formulations with low volatile organic compound emissions.
- Consumer Electronics:Device housing and appliance panels demand thin-gauge papers with precise color matching for brand consistency.
Furniture commands absolute consumption; construction-linked applications show steepest expansion trajectory.
Thickness:
Panel press capability and end-use abrasion exposure determine thickness selection across regional manufacturing bases.
- Thin:60–80 gsm sheets suit high-volume furniture production with precision temperature control. UAE and Saudi panel lines with modern short-cycle presses favor this grade for material efficiency.
- Medium:80–100 gsm balances durability and cost for standard residential furniture across North African markets.
- Thick:100–120 gsm serves high-traffic commercial applications requiring enhanced edge integrity.
- Extra Thick:Above 120 gsm formulations target post-forming and complex contour applications in premium furniture and automotive interiors.
Medium thickness dominates unit volumes; thin gauges are climbing fastest as press technology modernizes.
Distribution Channel:
Order scale, certification documentation requirements, and inventory risk tolerance separate buyers by channel preference.
- Direct Sales:Major Saudi giga-project developers and UAE hospitality contractors procure through mill-direct relationships. Emaar, NEOM, and Red Sea Global mandate technical audits within ninety-day windows, forcing distributors to carry certified inventory on speculation.
- Distributors:Regional stockists serve mid-tier furniture manufacturers in Egypt and South Africa with shorter lead times and smaller minimum order quantities.
- Offline Retail:Physical trade counters supply aftermarket refurbishment and small-batch producers across North African price-sensitive markets.
- Online Retail:Digital procurement platforms gain traction among independent furniture workshops seeking design catalog access without distributor intermediaries.
Direct sales anchor premium-grade volumes; distributor channels are expanding most quickly in standard-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh-Jeddah corridor anchors decor paper consumption across the Middle East and Africa, with Saudi giga-projects generating sustained panel demand and UAE green building codes reshaping procurement specifications.
Saudi Arabia
NEOM and Red Sea Global developments absorb laminated surfacing materials at scale. SASO formaldehyde emission thresholds filter import access toward certified European-origin suppliers. Jeddah's panel manufacturing cluster faces compressed supplier qualification cycles as developer procurement teams mandate ninety-day technical audit windows.
United Arab Emirates
Dubai and Abu Dhabi hospitality fit-outs specify anti-microbial and scratch-resistant paper grades under Estidama Pearl Rating System mandates. MOHAP disclosure requirements extend to interior finishes, forcing procurement officers toward pre-certified suppliers with established documentation trails. Sharjah's furniture export sector gravitates toward gravure-printed designs for cost-competitive veneer replication.
South Africa
Johannesburg and Cape Town manufacturing clusters displace solid wood with melamine-faced chipboard in residential furniture. SABS emission standards parallel European certification protocols, favoring established import channels. Local panel producers align with just-in-time resin saturation schedules from decor paper distributors.
Egypt
Cairo and Alexandria social housing corridors adopt panelized building methods, creating entry points for standard-grade printed paper suppliers. The country's new industrial licensing framework alters competitive access for foreign mills. Egyptian chipboard lines with older press configurations limit thin-paper grade penetration due to temperature control constraints.
Nigeria
Lagos and Kano furniture manufacturing absorbs cost-sensitive decor paper grades for domestic market surfacing. Nascent standards harmonization efforts reshape import quality thresholds. Nigerian distributors carry speculative inventory to serve mid-tier producers lacking direct mill relationships.
Middle East and Africa Decor Paper Market Competitive Landscape
Backward integration into base paper production dominates the current landscape as converters seek input cost control amid volatile pulp flows. The vendor base clusters around three tiers: integrated European mills with certified emission protocols, regional distributors carrying speculative inventory for qualification-shortened procurement cycles, and Asian-origin suppliers competing on standard-grade price points. Strategic archetypes include resin chemistry specialists, design-archive holders, and scale-driven base paper producers. M&A activity and capacity expansion in low-emission resin formulation represent the dominant competitive vectors.
Among German-origin integrated producers, KÄMMERER Paper GmbH and SURTECO GmbH occupy positions emphasizing upstream control over specialty cellulose inputs. Ahlstrom-Munksjö represents the technical-grade specialist archetype serving high-performance hospitality specifications. These three exemplify how European certification trails and resin chemistry capabilities create defensive positioning against price-driven Asian competition in premium segments.
| Leading Market Players |
|---|
| KÄMMERER Paper GmbH |
| SURTECO GmbH |
| Ahlstrom-Munksjö |
| Schattdecor |
| Felix Schoeller Group |
| Impress Surfaces GmbH |
| Stora Enso |
| TOPPAN INC. |
| CHIYODA |
| Others |
Supply & Pricing Matrix
Specialty cellulose pulp flows from Nordic and Brazilian mills through Rotterdam and Jeddah logistics hubs into three pricing tiers segmented by SASO certification status and resin formulation complexity. European-origin suppliers with established emission testing protocols capture premium positioning, while Asian converters compete on standard-grade spot pricing in Egyptian and Nigerian distributor channels.
Pricing Analysis
Input-cost pass-through from volatile softwood pulp markets compresses margin pools for non-integrated converters serving North African price-driven segments. Pricing stratifies across premium, standard, and economy tiers where anti-microbial formulations command specification premiums in UAE hospitality fit-outs under Estidama mandates. Cost compression in standard-grade printed paper intensifies as vinyl wrap substitutes capture flooring applications. Egyptian social housing contractors exhibit highest price sensitivity; Saudi giga-project developers prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Johannesburg orchestrate hub-and-spoke patterns serving furniture manufacturers and construction contractors. Supply concentrates in Germany, Austria, and Finland for certified premium grades, while China and India feed standard-grade flows. The chain draws from specialty cellulose pulp, melamine resin precursors, and gravure cylinder engraving services. Single-source vulnerability runs through European base paper mills with SASO certification. Distribution runs through mill-direct relationships for Saudi developers and speculative inventory carried by regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as Estidama disclosure mandates and SASO emission thresholds shift procurement toward pre-certified European suppliers with established documentation trails.
For Market Incumbents: Deploy backward integration into base paper production to defend margin position against pulp price volatility. Reinforce certification investment in low-formaldehyde melamine-urea systems to maintain specification access under tightening Saudi and UAE standards. Channel control through Jeddah and Dubai distribution hubs limits Asian competitor penetration in premium segments.
For New Entrants and Emerging Players: Regional distributors serving mid-tier Egyptian furniture manufacturers represent the most penetrable entry channel. Target Cairo and Alexandria social housing corridors with standard-grade printed paper offerings priced below European certified alternatives. A go-to-market angle anchored to accelerated construction timelines and just-in-time resin saturation schedules aligns with local panel producer workflows.
For Investors and Strategic Acquirers: Consolidation pressure builds where resin chemistry expertise scarcity intersects with compressed supplier qualification timelines at Saudi giga-project developers. Long-term viability favors integrated mills with captive pulp supply and established SASO testing protocols. The signal to watch is Egyptian industrial licensing framework implementation altering foreign mill competitive access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Paper Production | Captive cellulose supply insulates margin pools from Nordic pulp price volatility. |
| Low-Emission Resin Formulation Certification | SASO and Estidama compliance unlocks specification access in Saudi and UAE premium segments. |
| Regional Distribution Hub Expansion | Jeddah and Johannesburg warehousing compresses lead times for just-in-time panel producer schedules. |
| Anti-Microbial Grade Development | Scratch-resistant formulations command hospitality fit-out premiums under MOHAP disclosure mandates. |
| Digital Design Archive Investment | Gravure cylinder libraries enable photorealistic wood grain replication at lower cost than veneer alternatives. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each major national market. Primary interviews with decor paper mill technical directors, Saudi giga-project procurement officers, UAE hospitality fit-out contractors, Egyptian panel plant managers, and South African furniture manufacturer purchasing leads combined with secondary validation. Secondary sources include SASO and SABS regulatory filings, customs trade data for cellulose base paper flows, and hospitality sector specification databases. Bottom-up demand modeling from end-use consumption and top-down supply validation from mill capacity data were triangulated.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, end-use industry, thickness grade, and distribution channel. The analytical framework modeled furniture, construction, automotive, and consumer electronics verticals separately with distinct resin saturation and certification requirements. CAGRs were derived from regression against panel production forecasts and green building code implementation timelines. Industry-specific inputs included NEOM and Red Sea Global construction schedules, Estidama Pearl Rating System adoption curves, and Egyptian social housing unit completion targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pulp price volatility, Egyptian regulatory implementation timing, and Nigerian standards harmonization progress. Forecasts reflect documented assumptions around SASO enforcement consistency and giga-project execution schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Paper Chemical Market
Paper Products
Paper Glass Market
Paper Products
Household Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Thermal Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Solar Paper Market
Paper Products
Clay Coated Paper Market
Paper Products
Global Carpet Backing Material Market
Paper Products
Digital Printing Paper Market
Paper Products
Abaca Pulp Market
Paper Products
Stone Paper Market
Paper Products
Americas Stone Paper Market
Paper Products
Chemical Pulp Market
Paper Products
Solid Bleached Board Market
Paper Products
Plywood Market