
 Unbleached Kraft Pulp Market | 2026-2036
Unbleached Kraft Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Unbleached Kraft Pulp Market Outlook
Recycled containerboard is broadening its addressable market as unbleached kraft pulp retains superior tensile strength for heavy-duty corrugated applications. UPM-Kymmene Corporation leverages its integrated Finnish mills to sustain cost advantages in specialty pulp grades. Sappi Limited anchors its competitiveness through dissolving wood pulp co-production that shares kraft cooking infrastructure. International Paper Company dominates North American linerboard supply chains with captive kraft pulp capacity.
Unbleached kraft pulp consists of wood fibers cooked under alkaline conditions without subsequent bleaching, yielding a brown-colored pulp with high burst strength and tear resistance measured above 18 mN·m²/g in standard market grades. The material serves primarily as the structural backbone of corrugated packaging, sack paper, and wrapping grades where durability outweighs aesthetic requirements. Market pulp shipments occupy the largest value pool as merchant supply to independent converters grows faster than captive integrated consumption. Specialty pulp commands premium positioning where customized fiber morphologies address technical textile and advanced filtration end uses. Recycled pulp competes aggressively on cost but faces supply constraints from collection infrastructure limitations in key consuming regions.
EPA effluent guidelines under the Clean Water Act limit absorbable organic halogen discharge from pulp bleaching sequences, indirectly favoring unbleached kraft processes that bypass chlorine-based stages entirely. FDA food-contact substance notifications govern unbleached kraft migration limits for direct food packaging applications in the United States. Stakeholders must monitor evolving extended producer responsibility frameworks that could reallocate collection and recycling costs across virgin and recycled pulp value chains.
Market Dynamics
The EU Single-Use Plastics Directive is forcing packaging converters across Germany, France, and Italy to eliminate plastic liners in favor of fiber-based alternatives, redirecting merchant pulp flows toward corrugated and sack paper grades.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandated phase-out of plastic food containers and beverage cups in member states by 2030 creates structural demand pull for unbleached kraft barrier coatings.
- E-commerce fulfillment infrastructure:Heavy-duty corrugated specifications for bulk shipping containers require the tear resistance that unbleached kraft pulp delivers above recycled alternatives.
- Nordic pulp-to-packaging clusters:Integrated mill-converter networks in Finland and Sweden compress logistics costs and secure supply continuity for European brand owners.
Market Restraints
- Softwood fiber supply concentration:Scandinavian and Russian boreal forest dependence creates geographic vulnerability to harvest restrictions and trade flow disruptions.
- Energy cost volatility:Kraft cooking and chemical recovery processes consume substantial natural gas and electricity, exposing margins to European energy price spikes.
- Recycled containerboard substitution:Post-consumer fiber collection improvements in Germany and the Netherlands narrow the performance gap for lightweight corrugated applications.
Strategic Opportunities
- Poland and Czech Republic packaging expansion:Central European manufacturing relocation from Western Europe drives greenfield corrugated plant investments requiring merchant pulp supply.
- Advanced filtration media:Customized fiber morphologies for industrial liquid filtration command premium positioning above commodity packaging grades.
- EU Green Deal carbon border adjustments:Embedded emissions accounting favors low-carbon Nordic pulp production against higher-intensity imports.
Industry Challenges
- Recovery boiler maintenance cycles:Extended downtime for chemical recovery infrastructure disrupts continuous production schedules and delivery commitments.
- FDA food-contact notification timelines:Migration testing and substance notification delays for new barrier coating formulations extend product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unbleached Kraft Pulp Market |
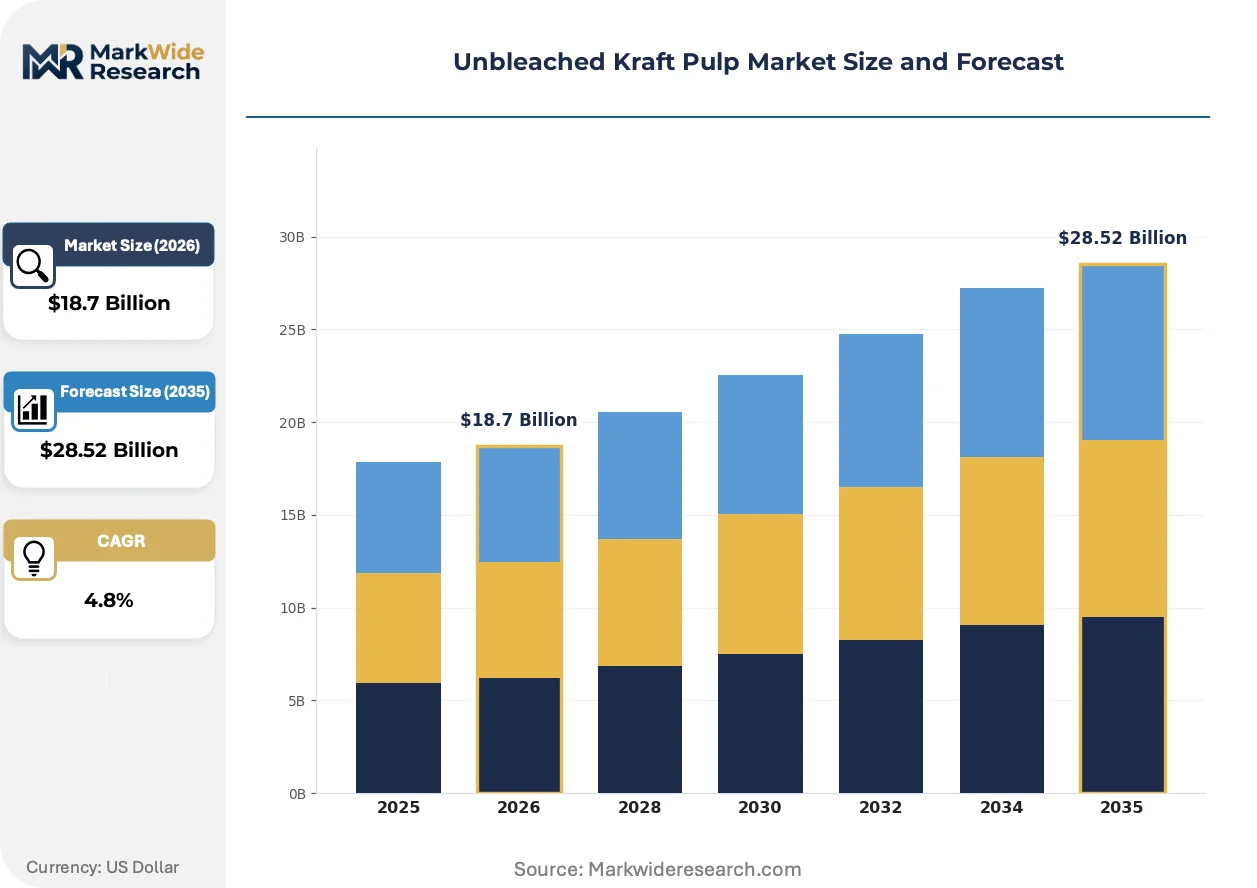
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Market Pulp, Specialty Pulp, Converted Pulp, Recycled Pulp End Use Industry: Packaging, Paper Products, Construction, Textiles Distribution Channel: Direct Sales, Online Retail, Distributors, Exporters Grade: Coated, Uncoated, Semi-Chemical, High Yield |
| Companies Covered | UPM-Kymmene Corporation, Sappi Limited, International Paper Company, Resolute Forest Products, Smurfit Kappa Group, WestRock Company, Canfor Corporation, Mondi Group, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unbleached Kraft Pulp Market Strategic Shifts
Process intensification and digital fiber design are compressing development cycles while regulatory carbon accounting reshapes sourcing geography. Three developments warrant particular attention.
Continuous kraft cooking with extended delignification is unifying yield optimization and strength retention in a single reactor configuration. Specialty packaging producers in Belgium and the Netherlands are retrofitting digesters to capture this efficiency gain. The technology is unifying what were previously separate capital-intensive process stages, reducing specific energy consumption per ton.
REACH authorization requirements for formaldehyde-based wet-strength resins are accelerating migration to polyamide-epichlorohydrin alternatives in food-contact applications. Finnish and Swedish mills face reformulation timelines to maintain EU market access. The corrugated sector is absorbing most compliance costs through specification adjustments rather than price pass-through.
Direct mill-to-converter digital procurement platforms are compressing spot market transaction cycles and reducing inventory carrying requirements. Independent box plants in Northern Italy and Southern Germany are adopting these channels fastest. The shift is most visible among mid-sized converters seeking to minimize working capital exposure to pulp price volatility.
Unbleached Kraft Pulp Market Segmentation
Unbleached kraft pulp serves both standalone merchant markets and vertically integrated packaging systems. Segmentation reveals where value capture concentrates versus where volume commoditization pressures margins.
Product Type:
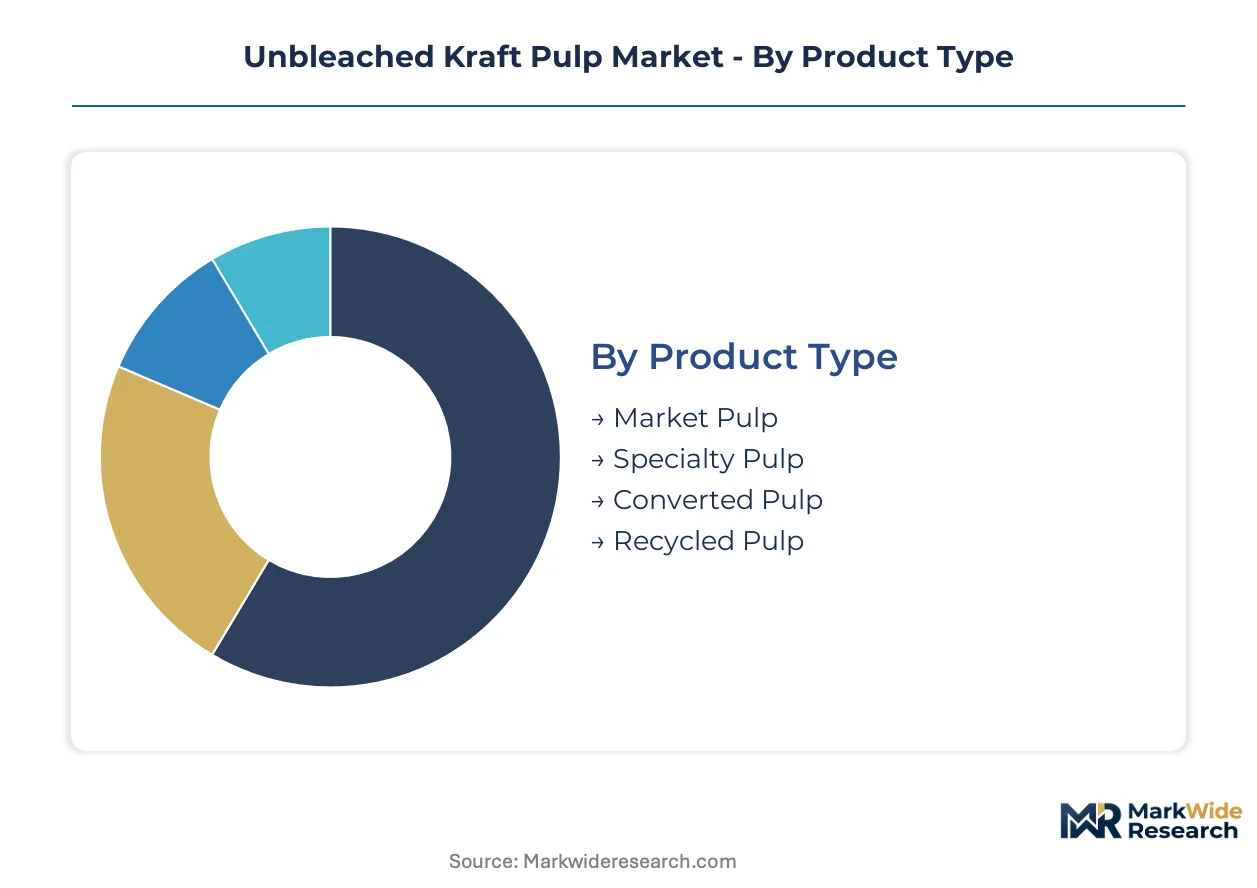
Standalone merchant supply dominates revenue pools while embedded captive production shapes cost structures across integrated packaging networks.
- Market Pulp:Merchant-grade pulp sold to independent converters carries standardized burst strength specifications above 18 mN·m²/g. Demand concentrates in Germany and Italy where corrugated plants lack upstream integration and rely on spot and contract purchases from Nordic suppliers.
- Specialty Pulp:Customized fiber morphologies for technical textiles and filtration media command premium positioning through controlled coarseness and length distribution. Finnish mills leverage extended delignification to serve Belgian filtration producers with batch-specific properties.
- Converted Pulp:Semi-processed grades for direct box plant consumption reduce converter capital requirements.
- Recycled Pulp:Post-consumer fiber recovery competes on cost but faces collection infrastructure constraints in Southern European markets.
Volume placements concentrate in market pulp; the faster expansion belongs to specialty pulp.
End Use Industry:
Application-driven demand splits between high-volume packaging flows and smaller technical segments where fiber engineering justifies price premiums.
- Packaging:Corrugated containerboard and sack paper absorb the majority of unbleached kraft output. E-commerce fulfillment specifications in Poland and the Czech Republic favor heavy-duty grades with superior tear resistance for bulk shipping applications.
- Paper Products:Wrapping grades and protective paperboard serve industrial and consumer goods protection.
- Construction:Building paper and sheathing applications utilize moisture-resistant unbleached kraft as temporary weather barriers.
- Textiles:Nonwoven fiber applications in geotextiles and industrial wipes require customized pulp properties.
Packaging commands absolute volume leadership; textiles and filtration applications are climbing the fastest as technical specifications tighten.
Distribution Channel:
Channel structure reflects customer scale and inventory risk tolerance across merchant and integrated supply chains.
- Direct Sales:Long-term contracts link major Nordic producers to large corrugated converters in Northern Italy and Southern Germany. These arrangements compress price volatility exposure and secure supply continuity for multi-year packaging contracts.
- Distributors:Regional stockholding intermediaries serve mid-sized box plants with fragmented demand patterns.
- Online Retail:Digital procurement platforms are compressing spot market transaction cycles for independent converters.
- Exporters:Cross-border shipments from Finnish and Swedish ports reach Mediterranean and Central European markets.
Direct sales anchor volume stability; digital channels are gaining share fastest among mid-tier converters minimizing working capital exposure.
Grade:
Grade differentiation separates commodity packaging flows from performance-critical applications where surface and structural properties command price separation.
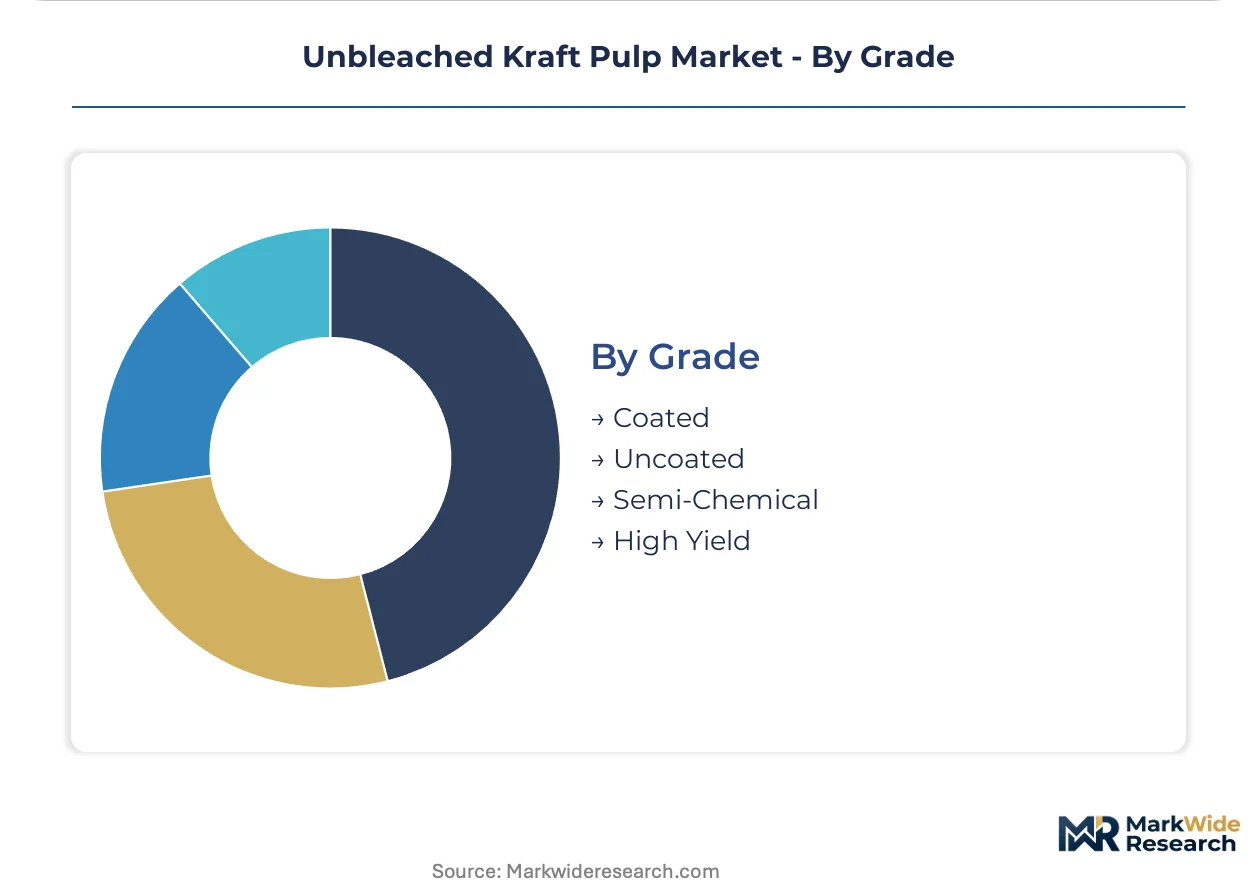
- Uncoated:Standard brown kraft pulp retains natural lignin content and alkaline cooking residues. This grade serves cost-sensitive corrugated applications across Central European markets where appearance requirements remain secondary to structural performance.
- Coated:Surface-treated grades enable barrier properties for food-contact and moisture-sensitive applications. REACH authorization pressures on formaldehyde-based wet-strength resins are accelerating reformulation toward polyamide-epichlorohydrin alternatives in Belgian and Dutch converter networks.
- Semi-Chemical:Hybrid cooking processes yield intermediate properties for specific linerboard specifications.
- High Yield:Mechanical-chemical pulping maximizes fiber recovery for lower-strength applications.
Uncoated grades dominate tonnage placement; coated grades show the steepest expansion trajectory as food-contact barrier requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant pulp demand concentrates in Germany and Italy where independent corrugated converters lack upstream integration. Nordic producers anchor supply through long-term contracts. Regulatory frameworks in multiple jurisdictions are redirecting material flows toward fiber-based packaging alternatives.
Finland
Integrated pulp-to-packaging clusters in Kotka and Rauma compress logistics costs for European brand owners. The EU Green Deal carbon border adjustment mechanism favors low-carbon Finnish production against higher-intensity imports. UPM-Kymmene leverages captive kraft capacity to serve German linerboard converters through direct mill linkages.
Sweden
Sack paper specifications for industrial applications drive specialty pulp demand from Belgian filtration producers. REACH authorization timelines for formaldehyde-based wet-strength resins are accelerating reformulation toward polyamide-epichlorohydrin alternatives. Stora Enso Oyj anchors supply continuity through extended delignification retrofits at Sundsvall mills.
Germany
Corrugated plants in Bavaria and North Rhine-Westphalia rely on spot and contract purchases from Nordic suppliers for heavy-duty grades. The EU Single-Use Plastics Directive mandates phase-out of plastic food containers by 2030, redirecting merchant flows toward barrier-coated kraft. E-commerce fulfillment infrastructure in Leipzig-Halle logistics corridors requires tear-resistant specifications.
United States
Heavy-duty corrugated specifications for bulk shipping containers absorb unbleached kraft output from Southern mill complexes. FDA food-contact substance notifications govern migration limits for direct food packaging applications. International Paper dominates linerboard supply chains with captive pulp capacity serving independent box plants across the Southeast.
Poland
Central European manufacturing relocation from Western Europe drives greenfield corrugated plant investments requiring merchant pulp supply. The country's national environmental regulator enforces wastewater discharge standards that indirectly favor unbleached processes bypassing chlorine-based stages. Poznań and Łódź industrial zones concentrate converter demand for e-commerce packaging grades.
Unbleached Kraft Pulp Market Competitive Environment
Capacity expansion dominates the current landscape as producers retrofit digesters for continuous kraft cooking with extended delignification. The vendor base clusters around three strategic archetypes: integrated forest products groups with captive pulp-to-packaging control, specialty pulp merchants serving technical textile and filtration end uses, and North American linerboard specialists with backward integration into kraft cooking infrastructure. M&A activity and geographic expansion into Central European converter networks represent the dominant competitive moves.
Among Nordic integrated producers, UPM-Kymmene Corporation and Stora Enso Oyj exemplify the pulp-to-packaging archetype through Finnish mill networks. Sappi Limited occupies a position within the specialty tier through dissolving wood pulp co-production sharing kraft cooking infrastructure. International Paper Company anchors the North American scale-driven segment with captive capacity serving independent converters.
| Leading Market Players |
|---|
| UPM-Kymmene Corporation |
| Sappi Limited |
| International Paper Company |
| Resolute Forest Products |
| Smurfit Kappa Group |
| WestRock Company |
| Canfor Corporation |
| Mondi Group |
| Stora Enso Oyj |
| Others |
Value Chain & Pricing Dynamics
Performance-grade divergence between specialty filtration pulp and commodity packaging grades manifests in contract structures and logistics configurations across Nordic supply networks. Merchant buyers in Germany and Italy absorb premium positioning for customized fiber morphologies while spot markets clear standard brown kraft through digital procurement platforms.
Pricing Analysis
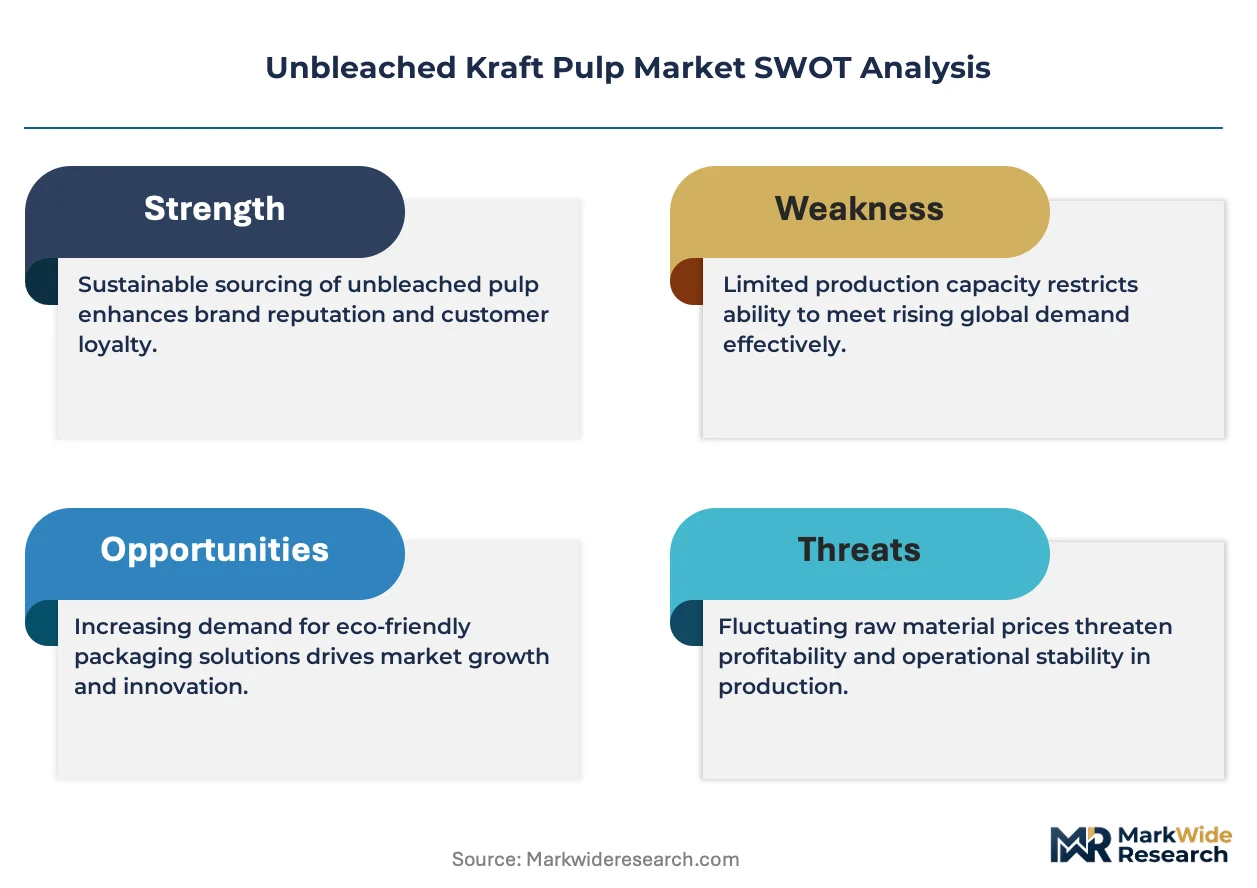
Volume-vs-margin split separates merchant-grade market pulp from specialty filtration grades commanding premium positioning through controlled coarseness specifications. Three-tier pricing structure across premium, standard, and economy levels reflects burst strength thresholds and REACH compliance status for wet-strength resin formulations. Cost compression in standard uncoated grades is intensifying because recycled containerboard narrows the performance gap for lightweight corrugated applications. Independent converters in Southern Germany exhibit highest price sensitivity through spot market digital procurement, while Belgian filtration producers lock in long-term contracts for batch-specific fiber properties.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal carbon border adjustment mechanism are reshaping sourcing patterns toward low-carbon Nordic production. Supply concentrates in Finland, Sweden, and Russia's boreal forest zones, with Finnish integrated clusters drawing from captive softwood fiber basins. Chemical recovery infrastructure and natural gas feedstocks constitute critical input dependencies. Single-source vulnerability runs through Scandinavian chemical recovery boiler maintenance cycles that disrupt continuous production. Distribution runs through direct mill-to-converter contracts for large German linerboard plants and regional distributors serving fragmented Italian box plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unbleached kraft pulp represents a vertical-integration race where control over chemical recovery infrastructure and captive fiber supply determines cost position. Players are pursuing upstream consolidation of boreal forest concessions and downstream packaging asset integration.
For Market Incumbents: Extend continuous kraft cooking retrofits across Finnish and Swedish mill networks to unify yield optimization with strength retention in single-reactor configurations. Defend against recycled containerboard substitution by locking in multi-year supply contracts with German e-commerce fulfillment infrastructure operators. Prioritize extended delignification investments that compress specific energy consumption per ton.
For New Entrants and Emerging Players: Capture greenfield corrugated plant demand in Poland and the Czech Republic where Central European manufacturing relocation outpaces local pulp supply. Target specialty filtration media applications in Belgium and the Netherlands where REACH authorization timelines for formaldehyde-based resins create reformulation windows. Lead with polyamide-epichlorohydrin wet-strength alternatives as a food-contact compliance wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty pulp merchants given EU Single-Use Plastics Directive demand pull for barrier-coated grades. Long-term viability over the coming decade hinges on carbon intensity differentials favoring low-carbon Nordic production against higher-emission imports. Watch for FDA food-contact notification delays as inflection indicators for new barrier coating commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Kraft Cooking Retrofit | Finnish mills capture yield-strength unification through extended delignification reactor upgrades. |
| Backward Integration into Fiber Supply | UPM-Kymmene and Stora Enso secure boreal forest concessions against harvest restriction risks. |
| Barrier Coating Reformulation | Belgian converters pivot from formaldehyde resins to polyamide-epichlorohydrin for REACH compliance. |
| Digital Procurement Platform Adoption | Northern Italian box plants compress spot market transaction cycles and inventory carrying costs. |
| Central European Greenfield Expansion | Polish corrugated investments absorb merchant pulp supply from Nordic exporters. |
Study Parameters
Multi-period observation of Nordic pulp shipment volumes, energy cost differentials, and REACH regulatory timelines anchored the trend analysis, supplemented by interviews with Finnish mill operations directors, German corrugated plant procurement managers, Belgian filtration media technical directors, and Italian box plant owners. Secondary validation drew from EU ETS carbon price data, EPA effluent guideline filings, FDA food-contact substance notification databases, and customs trade flow records. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand drivers for fiber-based packaging substitution.
Segment-weighting across product type, end-use industry, distribution channel, and grade dimensions structured the analytical framework over the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment infrastructure expansion, EU regulatory phase-out timelines, and energy price volatility assumptions. Industry-specific forecast inputs included chemical recovery boiler capacity utilization rates and extended producer responsibility framework cost allocation scenarios.
The model holds under stable EU carbon border adjustment implementation and Nordic energy price normalization; deviation in Russian boreal forest trade flow disruptions or formaldehyde REACH authorization delays would shift supply-demand balances. Forecasts reflect documented assumptions on substitution elasticity between virgin and recycled pulp grades. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Leatheroid Paper Market
Paper Products
Thermal Paper Market
Paper Products
North America Decor Paper Market
Paper Products
Digital Printing Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Specialty Paper Market
Paper Products
Global Copier Paper Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Global Paper Chemical Market
Paper Products
Paper Making Machine Market