
 Sunscreen Ingredients Market | 2026-2036
Sunscreen Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Sunscreen Ingredients Market Insights
The FDA's revised sunscreen monograph is pivoting the cost-of-entry calculus for new UV filter approvals in the United States. BASF leverages its integrated photostability testing infrastructure to sustain leadership in organic filter supply. Croda International anchors its position through captive sourcing of titanium dioxide feedstock. Evonik Industries differentiates via silica-based encapsulation technology that extends mineral filter efficacy in high-SPF formulations.
Sunscreen ingredients comprise active UV filters, photostabilizers, and functional excipients engineered to absorb or scatter ultraviolet radiation across the 280-400 nm spectrum, with titanium dioxide and zinc oxide providing physical blocking while avobenzone and octocrylene deliver chemical absorption pathways. Physical filters command premium positioning as reef-safe mandates spread across coastal jurisdictions, whereas chemical filters face reformulation pressure from benzophenone contamination concerns. SPF level stratification concentrates margin pools in very high SPF tiers where filter loading requirements multiply raw material intensity per unit.
Regulatory oversight spans the FDA's OTC monograph system, the European Commission's Cosmetics Regulation under ECHA scientific committee review, and Australia's TGA sunscreens standard, with each framework dictating permissible filter concentrations and labeling protocols that directly determine product marketability. REACH compliance in Europe adds toxicological documentation burdens that favor suppliers with established substance dossiers. Stakeholders must monitor pending FDA monograph finalization and parallel state-level restrictions in Hawaii and Key West on oxybenzone and octinoxate to anticipate filter obsolescence timelines and redirect R&D investment toward GRASE-designated alternatives.
Market Dynamics
The FDA's pending monograph finalization is compressing formulation cycles as manufacturers pre-position photostable mineral alternatives ahead of anticipated GRASE determinations. This regulatory uncertainty is redistributing R&D budgets toward encapsulation technologies and titanium dioxide surface modifications that satisfy both efficacy and environmental compliance thresholds.
Growth Catalysts
- Reef-safe mandates:Coastal jurisdictions in Florida and Hawaii are banning oxybenzone and octinoxate, forcing brand reformulation toward zinc oxide and titanium dioxide mineral filters.
- Photostability testing infrastructure:Advanced in-house irradiation chambers at major suppliers are shortening validation timelines for new organic UV filter combinations.
- Premium skincare procurement:Clean beauty brands are specifying encapsulated mineral actives with verified non-nano particle dimensions, creating pull-through demand for specialized excipient grades.
Market Restraints
- Feedstock concentration:High-purity titanium dioxide supply concentrates among Chinese chloride-process producers, exposing formulators to export quota volatility.
- Regulatory friction:REACH dossier requirements for new UV filters in Europe demand multi-year toxicological studies that delay commercialization timelines.
- Substitution pressure:Wearable UV monitoring devices and clothing with embedded UPF ratings are capturing discretionary sun protection spending from topical products.
Strategic Opportunities
- Encapsulation technology convergence:Silica-based shell architectures combined with responsive polymer release mechanisms are enabling single-filter solutions for broad-spectrum claims.
- Underpenetrated dermocosmetic channel:Medical-grade sunscreen dispensed through dermatology clinics commands reimbursement pathways in Germany and France.
- Blue light defense extension:HEV filter additives targeting digital screen exposure are opening adjacent claims beyond traditional UV protection.
Industry Challenges
- Photostability chemist scarcity:Formulators capable of designing filter combinations that maintain efficacy across 8-hour wear profiles command premium compensation and lengthen hiring cycles.
- Validation capex intensity:In-vivo SPF testing facilities require irradiance-calibrated solar simulators and statistical panel designs that demand seven-figure capital commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sunscreen Ingredients Market |
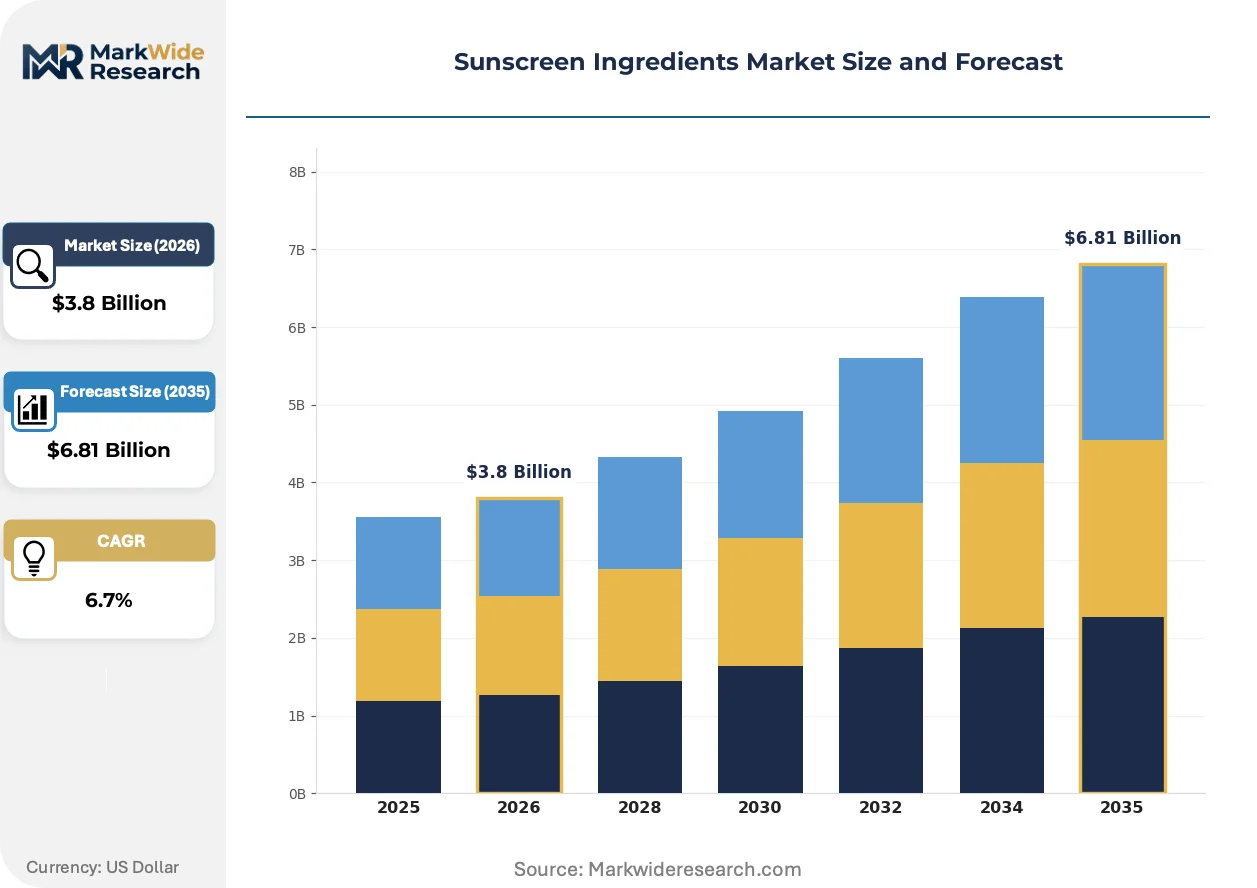
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Physical Filters, Chemical Filters, Antioxidants, Emollients Application Form: Lotions, Creams, Gels, Sprays SPF Level: Low SPF, Medium SPF, High SPF, Very High SPF Target Market: Adults, Children, Sensitive Skin, Outdoor Enthusiasts |
| Companies Covered | L'Oréal SA, Croda International, BASF, Galaxy Surfactants, Symrise AG, Evonik Industries, Ashland Inc., Sensient Technologies, Royal DSM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sunscreen Ingredients Market Trends and Innovations
Encapsulation architectures are displacing conventional filter dispersion methods as the primary mechanism for achieving photostability and skin-feel optimization simultaneously. This shift is compressing the advantage window for suppliers lacking surface-modification capabilities.
Sol-gel silica encapsulation is modularizing mineral UV filter production by enabling discrete shell-thickness control that separates photoprotection performance from aesthetic finish. Cosmetic chemists at prestige brands are specifying 50-200 nm shell dimensions to balance transparency with efficacy. The technology is modularizing supplier value chains by decoupling raw mineral sourcing from functional performance engineering.
REACH authorization procedures under ECHA review are extending approval timelines for novel organic filters, forcing European formulators toward existing substance inventories. The regulatory burden favors suppliers with pre-registered substance dossiers covering titanium dioxide nano-forms and zinc oxide variants. Small and mid-sized brands are consolidating procurement around GRASE-designated filters to avoid authorization uncertainty.
Direct-to-consumer sampling programs are compressing traditional distributor channels as ingredient suppliers build technical service relationships with indie beauty founders. Sephora Clean at Sephora and Credo Beauty certification requirements are transmitting upstream to raw material specifications. This channel pivot concentrates most visibly in California and New York, where venture-backed skincare startups prioritize speed-to-shelf over legacy supply relationships.
Sunscreen Ingredients Market Segmentation
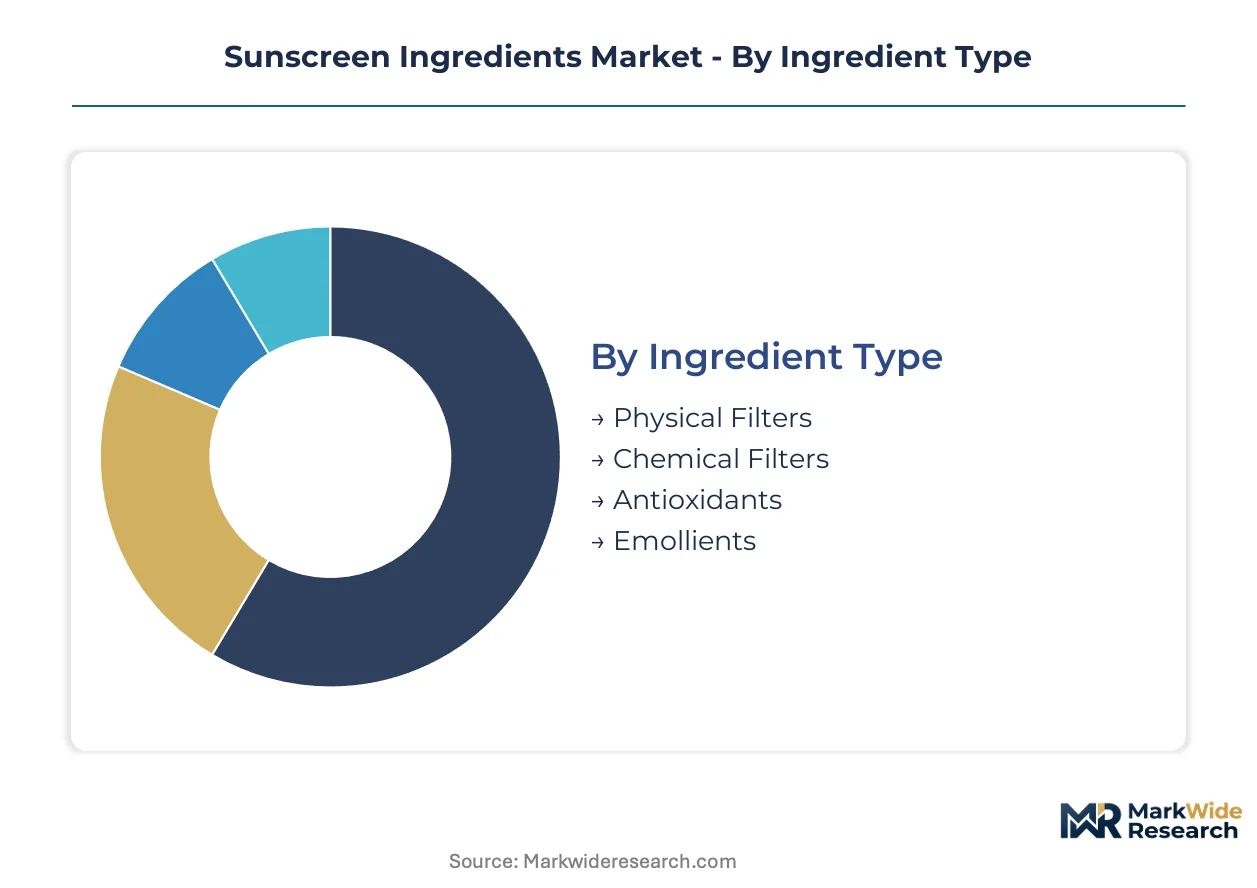
Ingredient type determines raw material procurement strategy and regulatory compliance burden. Application form dictates manufacturing equipment requirements and distribution channel selection. SPF level stratification concentrates margin pools and R&D investment intensity.
Ingredient Type:
Volume production concentrates in chemical filters while premium positioning gravitates toward physical mineral alternatives.
- Physical Filters:Titanium dioxide and zinc oxide scatter UV radiation through particle-mediated reflection. Demand from Hawaii and Florida coastal jurisdictions is accelerating as reef-safe mandates eliminate oxybenzone and octinoxate alternatives. FDA GRASE determinations favoring mineral filters are reshaping supplier capacity allocation toward chloride-process titanium dioxide.
- Chemical Filters:Avobenzone, octocrylene, and homosalate absorb UV radiation through molecular excitation. European formulators face REACH authorization delays that compress commercialization timelines for novel organic molecules. Photostability testing infrastructure at major suppliers shortens validation cycles for filter combinations.
- Antioxidants:Vitamin E and green tea polyphenols neutralize free radicals generated during UV exposure. Clean beauty certifications at Sephora and Credo Beauty mandate verified antioxidant sourcing.
- Emollients:Silicones and esters optimize spreadability and water resistance in finished formulations. Encapsulation technologies integrate emollient phases with active mineral cores.
Mature deployment sits with chemical filters. Newer deployment is concentrated in physical filters.
Application Form:
Manufacturing scale favors lotion formats while innovation investment targets spray delivery systems.
- Lotions:Oil-in-water emulsions dominate mass-market production with established filling line compatibility. SPF 30-50 variants command shelf space at major retailers.
- Creams:Thicker viscosity formulations target dry skin and pediatric applications. German and French dermocosmetic channels specify medical-grade cream bases.
- Gels:Alcohol-based or hydrogel matrices appeal to oily skin segments and male grooming lines. Transparent dry-down properties enable facial application under makeup.
- Sprays:Aerosol and pump-dispensed formats accelerate beach and sport usage occasions. FDA inhalation exposure concerns are tightening particle size specifications.
Volume leadership belongs to lotions. Fastest technology evolution is occurring in sprays.
SPF Level:
Raw material intensity multiplies with SPF tier, concentrating supplier margins in very high protection categories.
- Low SPF:SPF 6-15 formulations serve daily moisturizers with incidental sun exposure claims. Tinted and makeup-integrated products dominate this tier.
- Medium SPF:SPF 15-30 represents the mass-market standard for general population use. Price competition is most intense at this level.
- High SPF:SPF 30-50 requires elevated filter loading and photostabilizer concentrations. Australian TGA labeling protocols mandate specific testing validation.
- Very High SPF:SPF 50+ formulations demand complex filter combinations and silica encapsulation to maintain aesthetic acceptability. Premium skincare brands specify this tier for anti-aging positioning.
Mass-market penetration peaks at medium SPF. Premium brand expansion concentrates in very high SPF.
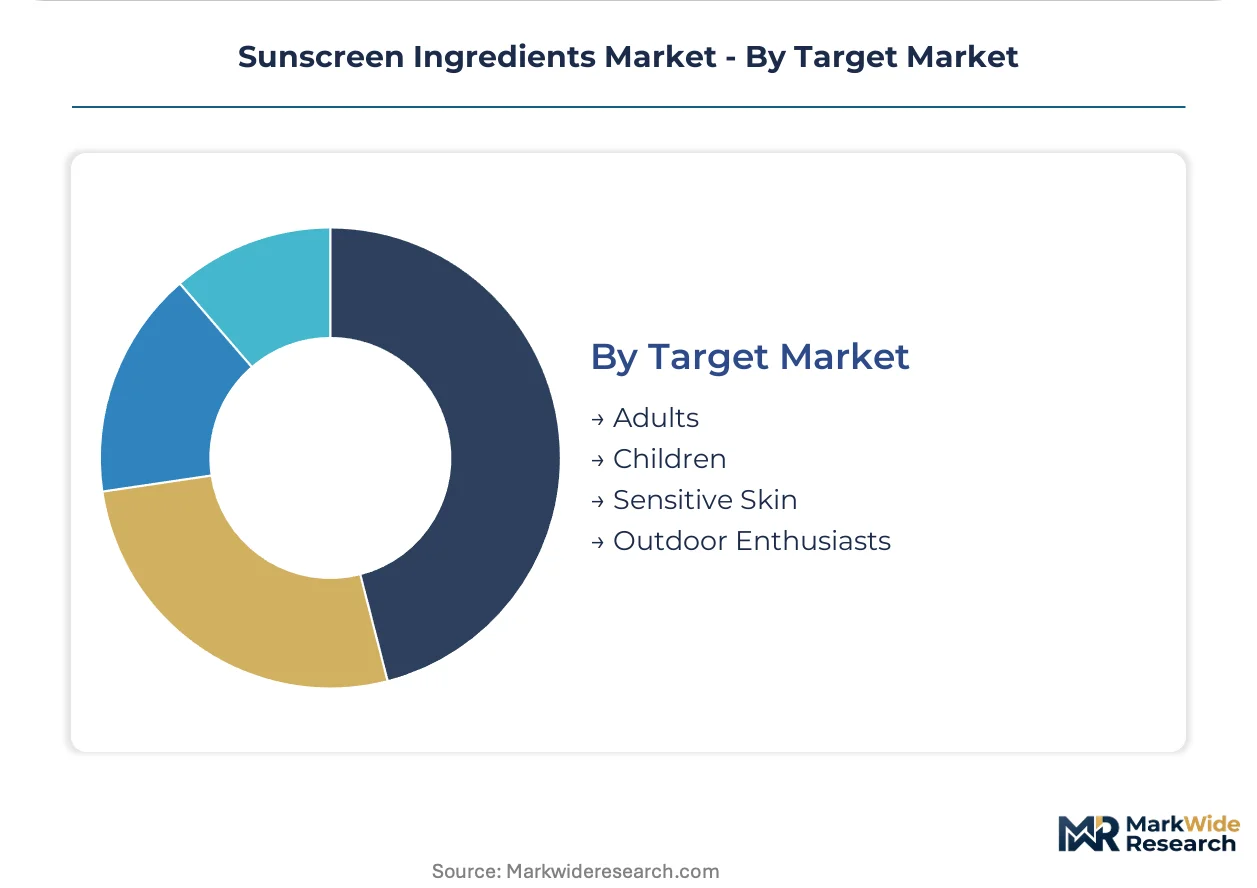
Target Market:
Adult segments drive volume while sensitive skin and pediatric categories command formulation complexity premiums.
- Adults:General population formulations span mass-market to prestige price points. Anti-aging claims integrate sunscreen with retinol and peptide actives.
- Children:Pediatric formulations exclude certain chemical filters and prioritize mineral-only compositions. Tear-free and hypoallergenic specifications constrain excipient selection.
- Sensitive Skin:Fragrance-free and non-comedogenic certifications require purified mineral grades and limited preservative systems. Dermatology clinic dispensing in Germany and France validates clinical positioning.
- Outdoor Enthusiasts:Sport and marine formulations emphasize water resistance and photostability across extended wear periods. Athlete-specific distribution channels include running specialty and surf retail.
Established demand centers on adult segments. Fastest formulation innovation is occurring in sensitive skin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Fujian and Guangdong provinces concentrate titanium dioxide processing capacity for mineral filter exports. Coastal manufacturing clusters in these zones benefit from duty exemptions on imported chloride-process feedstock. The resulting cost structure shapes procurement patterns for formulators across Southeast Asian markets.
United States
Domestic manufacturers are expanding photostable mineral filter capacity to serve Hawaii and Florida reef-safe mandates. The FDA's pending monograph finalization is compressing formulation cycles as brands pre-position GRASE-designated alternatives. New Jersey and California host the densest clusters of encapsulation technology providers serving prestige skincare brands.
Germany
Dermocosmetic dispensing through dermatology clinics creates reimbursement pathways for medical-grade sunscreen formulations. REACH authorization procedures under ECHA review extend approval timelines for novel organic filters. The Rhine-Ruhr industrial corridor concentrates photostability testing infrastructure serving European formulators.
China
Chloride-process titanium dioxide producers in Shandong and Jiangsu provinces control high-purity feedstock supply for mineral filter manufacturing. Export quota volatility from these regions exposes formulators to raw material cost fluctuations. The Yangtze River Delta hosts surface-modification specialists supplying encapsulated mineral actives to clean beauty brands.
Australia
The TGA sunscreens standard mandates specific testing validation for SPF 30-50 formulations targeting outdoor enthusiast segments. Domestic brands emphasize water resistance claims for sport and marine applications. Sydney and Melbourne anchor formulation R&D clusters serving Asia-Pacific export markets.
France
Prestige skincare headquarters in Paris and Lyon drive demand for encapsulated mineral actives with verified non-nano particle dimensions. ANSM oversight of cosmetic ingredient safety adds documentation burdens favoring suppliers with established substance dossiers. The Provence-Alpes-Côte d'Azur region concentrates antioxidant sourcing operations for clean beauty certifications.
Sunscreen Ingredients Market Competitive Landscape
German chemical conglomerates anchor one tier; British specialty chemical firms hold formulation expertise advantages. The supplier base concentrates among integrated multinationals with captive photostability testing infrastructure and regional specialists with surface-modification capabilities. Three archetypes dominate: mineral filter producers with chloride-process feedstock control, encapsulation technology licensors, and organic filter suppliers with REACH-registered substance dossiers. Capacity expansion and strategic technology licensing represent the primary competitive vectors.
Among integrated chemical suppliers, BASF, Croda International, and Evonik Industries exemplify the mineral-to-encapsulation value chain control archetype. BASF represents German-based conglomerate positioning with integrated photostability infrastructure. Croda International occupies British specialty chemical positioning with captive titanium dioxide sourcing relationships. Evonik Industries anchors German silica-based encapsulation specialization for high-SPF mineral formulations.
| Leading Market Players |
|---|
| L'Oréal SA |
| Croda International |
| BASF |
| Galaxy Surfactants |
| Symrise AG |
| Evonik Industries |
| Ashland Inc. |
| Sensient Technologies |
| Royal DSM |
| Others |
Pricing and Supply Chain Analysis
Chloride-process titanium dioxide feedstock indices in Shandong and Jiangsu provinces cascade through mineral filter supply chains into three-tier pricing structures across premium, standard, and economy levels. Coastal formulators in Florida and Hawaii absorb freight premiums for reef-safe mineral grades while inland manufacturers leverage contract offtake to lock in chloride-process supply from Yangtze River Delta surface-modification specialists.
Pricing Analysis
Short lead-time premiums for encapsulated mineral actives run 15-25% above contract baselines as clean beauty brands compress development cycles. Three-tier pricing structure across premium, standard, and economy levels separates GRASE-designated encapsulated grades from conventional mineral dispersions and unmodified chemical filter commodities. Cost compression in high-SPF mineral tiers is intensifying because titanium dioxide nano-form registration costs amortize across smaller batch volumes. Mass-market lotion manufacturers exhibit highest price sensitivity; prestige skincare houses with Sephora Clean at Sephora certification requirements show least.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and New Jersey warehouse surface-modified mineral actives for just-in-time delivery to formulators. Supply concentrates in China for chloride-process titanium dioxide feedstock, Germany for photostability testing infrastructure, and the United States for encapsulation technology licensing. Raw material dependencies span high-purity titanium dioxide from Shandong chloride-process plants, zinc oxide from Australian smelters, and silica precursors from German chemical conglomerates. Single-source vulnerability in Chinese export quota administration exposes formulators to feedstock disruption. Distribution runs through specialty chemical distributors with technical service capabilities for indie beauty brand support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral filter capacity expansion lags reef-safe mandate implementation timelines, propping pricing power for suppliers with captive chloride-process feedstock. Supply constraints in photostability testing infrastructure extend validation bottlenecks.
For Market Incumbents: To counter REACH authorization delays for novel organic filters, BASF and Evonik Industries should deepen backward integration into chloride-process titanium dioxide feedstock and expand in-house irradiation chamber capacity in New Jersey. Certification investment in FDA GRASE designation documentation creates switching costs for clean beauty brand procurement. For New Entrants and Emerging Players: Indie beauty founders with venture backing in California and New York represent the most penetrable buyer archetype for silica encapsulation technology licensors. Direct technical service relationships bypass legacy distributor markups. White-space targets include medical-grade dermocosmetic dispensing through German dermatology clinics and blue light defense additive formulations for digital-native skincare lines. For Investors and Strategic Acquirers: Distressed-cycle entries favor surface-modification specialists with REACH-registered titanium dioxide nano-form dossiers in the Rhine-Ruhr corridor. Long-term viability hinges on FDA monograph finalization resolving GRASE designation uncertainty. The signal to watch is state-level reef-safe mandate expansion beyond Hawaii and Florida into California and the Caribbean.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloride-Process Feedstock | Croda International's captive titanium dioxide sourcing insulates margin from Chinese export quota volatility. |
| Encapsulation Technology Licensing | Evonik Industries' silica-based shell architectures command royalty streams from prestige skincare formulators. |
| Photostability Testing Infrastructure Expansion | BASF's irradiation chamber investments shorten validation timelines for FDA monograph pre-positioning. |
| Direct-to-Consumer Technical Service | Supplier relationships with Sephora Clean at Sephora certified brands compress traditional distribution channels. |
| Blue Light Defense Additive Development | HEV filter extensions beyond UV protection open adjacent claims for digital screen exposure segments. |
Research Methodology
Multi-period observation of FDA monograph comment filings, REACH authorization timelines, and reef-safe mandate legislative tracking anchored the trend analysis, supplemented by interviews with photostability testing directors, clean beauty brand formulators, dermatology clinic procurement managers, and specialty chemical distribution executives. Secondary validation drew from FDA docket records, ECHA substance dossier databases, Hawaii and Florida state legislative registers, and customs trade data for titanium dioxide and zinc oxide imports. Bottom-up mineral filter production estimates triangulated against top-down sunscreen formulation demand projections.
Input-output matrices modeled ingredient type, application form, SPF level, and target market dimensions across the projection horizon. CAGRs derived from filter loading intensity curves by SPF tier and price elasticity estimates for premium versus mass-market segments. Forecast inputs incorporated chloride-process capacity expansion announcements, FDA monograph finalization probability weighting, and coastal jurisdiction mandate adoption trajectories.
Revisions become necessary when FDA GRASE determinations exclude currently marketed filters, Chinese export quotas tighten beyond historical volatility bands, or wearable UV monitoring device adoption accelerates substitution away from topical products. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methanol to Gasoline Market
Chemicals
Industrial Odor Management Market
Chemicals
Whitening Ingredients Market
Chemicals
Maleic Acid Market
Chemicals
Malic Acid Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Bakers Ammonia Market
Chemicals
Uranyl Carbonate Market
Chemicals
Hexachloroethane Market
Chemicals
Chloroplatinic Acid Market
Chemicals
India Methanol Market
Chemicals
Global Organobromine Market
Chemicals
Potassium Fluoride Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Sodium Cyanide Market
Chemicals
RDX and HMX Market