
 Chloroplatinic Acid Market | 2026-2036
Chloroplatinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Chloroplatinic Acid Market Outlook
Modular packaging in smaller-volume bottles and custom containers is hardening as the standard configuration for laboratory and specialty electronics buyers. Johnson Matthey leverages its platinum-group metal refining heritage to control high-purity supply chains for catalyst-grade material. BASF SE anchors European demand through its chemical synthesis and automotive catalyst customer base. Heraeus competes by extending vertical reach from precious metal trading into formulated chloroplatinic acid solutions.
Chloroplatinic acid (H2PtCl6) is a reddish-brown crystalline compound typically supplied as hexahydrate, formed by dissolving platinum in aqua regia followed by hydrochloric acid treatment; it serves primarily as a platinum precursor for heterogeneous and homogeneous catalysis, electroplating baths, and nanoparticle synthesis. The application dimension shows catalyst demand commanding the largest volume share, while electronics plating represents the fastest-expanding margin pool as semiconductor interconnect specifications tighten. Among product types, chloroplatinic acid solution dominates routine industrial procurement, whereas powder and hydrate forms capture premium pricing from research institutions requiring precise stoichiometry.
EPA hazardous waste rules and OSHA permissible exposure limits govern handling, storage, and worker safety protocols for chloroplatinic acid facilities in the United States, while REACH registration requirements in Europe constrain import volumes and mandate full substance dossiers for market access. China's SAMR enforces GB standards for chemical purity and labeling that affect both domestic producers and foreign suppliers. Stakeholders must monitor evolving precious metal sourcing disclosure rules and assess dual-sourcing strategies as regulatory compliance costs reshape competitive economics.
Market Dynamics
Platinum-group metal recovery mandates in Germany are compressing virgin material availability and forcing catalyst manufacturers toward closed-loop refining partnerships. This regulatory pressure is redrawing supply economics across pharmaceutical and electronics plating value chains.
Growth Catalysts
- REACH registration dossiers:European chemical manufacturers must submit full substance data for chloroplatinic acid import authorization, creating captive demand for compliant regional suppliers.
- Semiconductor interconnect miniaturization:Advanced packaging nodes below 7nm require ultra-high-purity platinum precursors for barrier seed layers.
- China:Domestic chemical synthesis capacity expansion and captive electronics manufacturing base concentrate procurement volume in East Asian supply chains.
Market Restraints
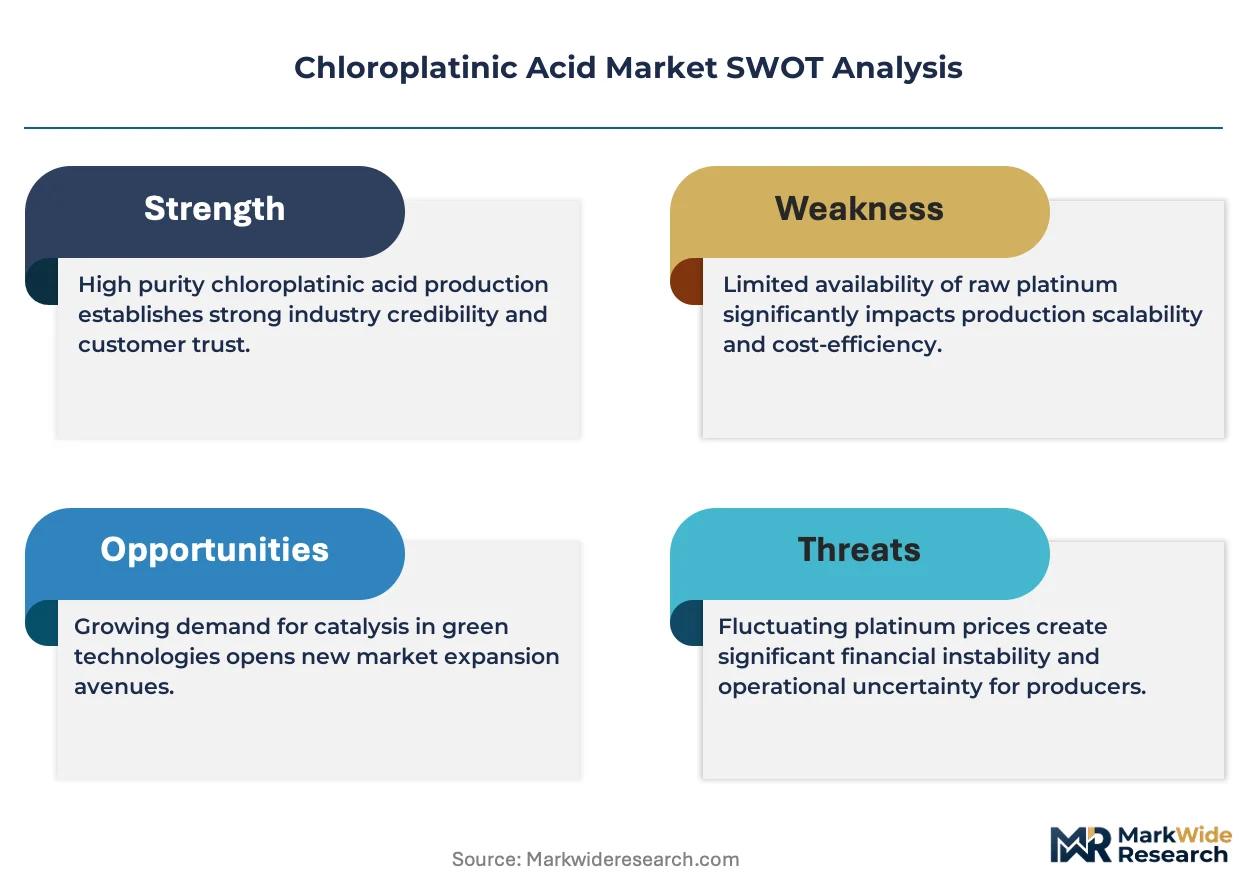
- Platinum price volatility:London Bullion Market Association spot pricing transmits directly to chloroplatinic acid input costs, compressing margin predictability for formulated product distributors.
- Single-source refining concentration:High-purity hexachloroplatinic acid production clusters in three integrated precious metal refiners, creating supply interruption exposure.
- Hexavalent platinum toxicity classification:OSHA permissible exposure limits and EPA hazardous waste rules impose costly containment infrastructure on U.S. handling facilities.
Strategic Opportunities
- India:PLI scheme incentives for semiconductor fabrication and specialty chemicals manufacturing create first-mover positioning for catalyst-grade material suppliers.
- Closed-loop refining services:Spent catalyst take-back programs align with tightening EU critical raw materials autonomy objectives.
- Pharmaceutical continuous manufacturing:Flow chemistry adoption in active pharmaceutical ingredient synthesis expands homogeneous catalysis demand for precision platinum precursors.
Industry Challenges
- Platinum-group metal assay certification:Multi-week analytical turnaround for purity verification delays batch release and extends working capital cycles.
- Legacy electroplating bath infrastructure:Converting sulfuric acid-based systems to chloroplatinic acid formulations requires tank material upgrades and process revalidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloroplatinic Acid Market |
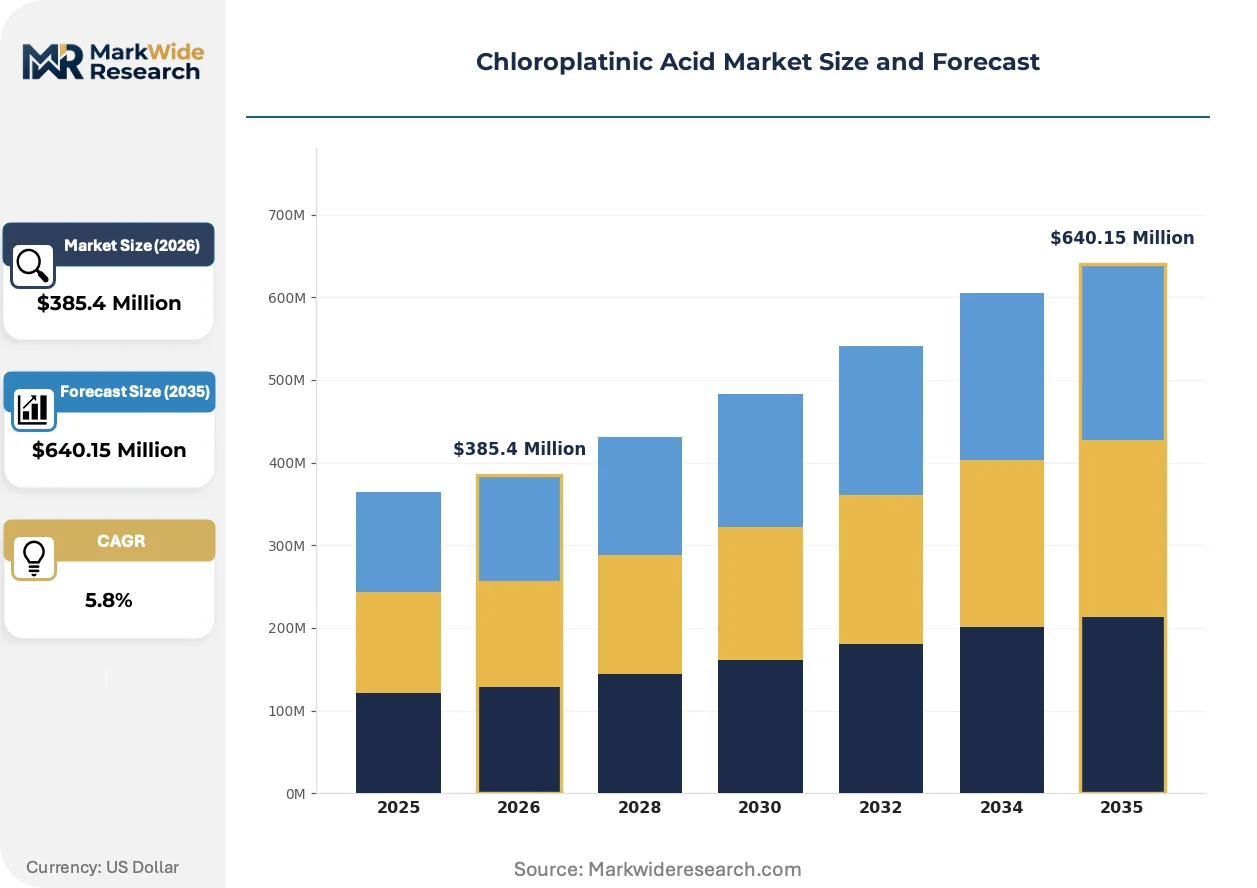
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Chloroplatinic Acid, Chloroplatinic Acid Hydrate, Chloroplatinic Acid Solution, Chloroplatinic Acid Powder Application: Catalyst, Electronics, Laboratory Reagents, Chemical Synthesis End User: Pharmaceuticals, Automotive, Electronics Manufacturers, Research Institutions Packaging Type: Drums, Bottles, Tanks, Custom Containers |
| Companies Covered | Tokyo Chemical Industry, Yogi Dye Chem Industries, ESPI Metals, Toronto Research Chemicals, Shanghai Xinglu Chemical Technology, Johnson Matthey, American Elements, BASF SE, Heraeus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloroplatinic Acid Market Strategic Shifts
Process intensification and regulatory disclosure requirements are fragmenting traditional bulk supply models. Manufacturers now compete on traceability architecture and formulation customization rather than scale economies alone.
Continuous flow synthesis of chloroplatinic acid hexahydrate is modularizing production footprints. Specialty chemical producers in Switzerland and Germany are adopting skid-mounted reactors that slash batch cycle times from days to hours. This unit operation compression enables regional micro-facilities that co-locate with pharmaceutical catalyst formulators, shrinking logistics exposure for high-value platinum inventory.
EU CSRD sustainability reporting mandates now require full precious metal provenance disclosure from mine to formulated product. Chemical manufacturers serving European automotive catalyst customers must implement blockchain-tracked supply chain documentation. This compliance burden favors integrated refiners with captive smelting assets over traders reliant on spot market sourcing.
Research institutions are consolidating procurement through cooperative purchasing consortia. University systems in the United States now negotiate multi-year framework agreements for high-purity hydrate rather than transactional spot buying. This buyer concentration is squeezing distributor margins while rewarding direct manufacturer relationships with certified analytical data packages.
Chloroplatinic Acid Market Segmentation
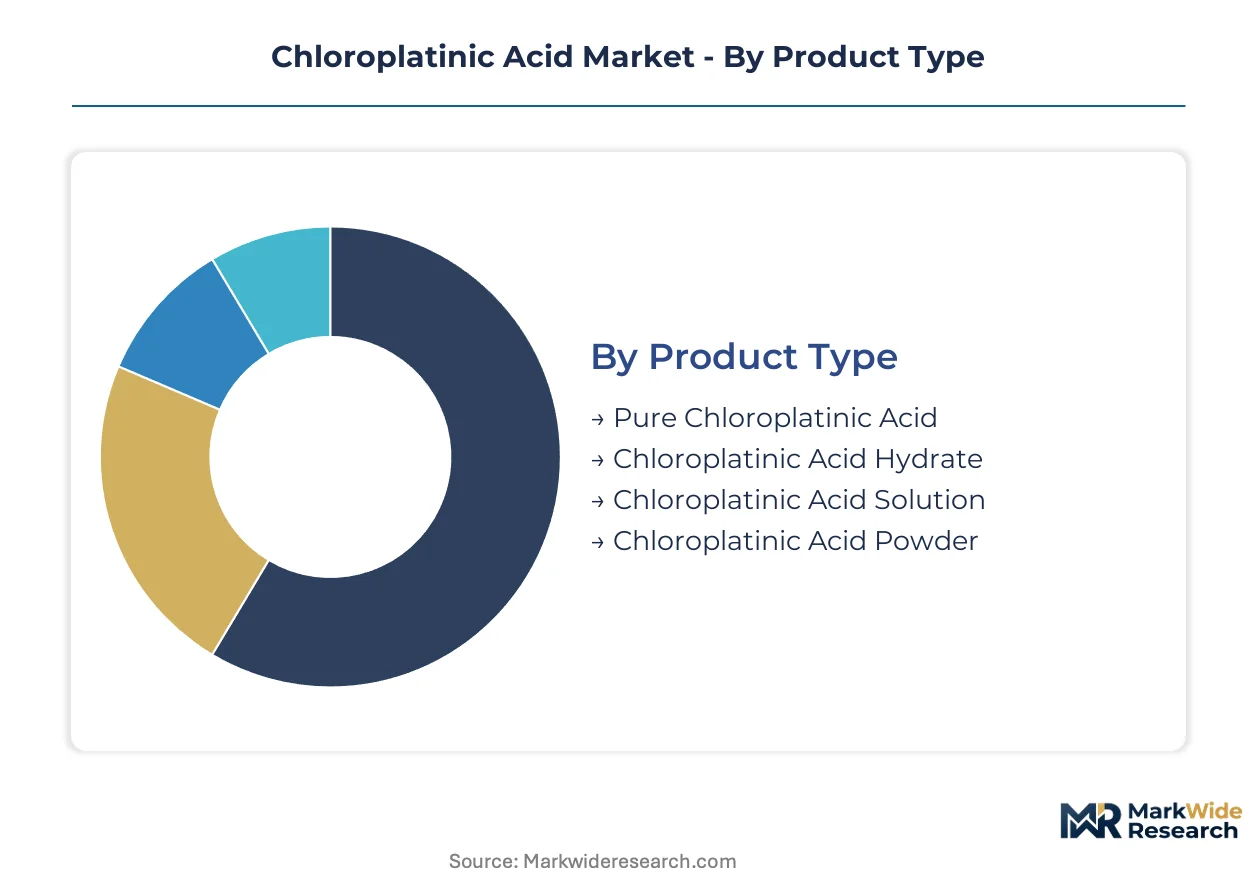
Segmentation in the chloroplatinic acid market reveals how platinum precursor specifications diverge across catalyst formulators, electronics platers, and research buyers. Each segment carries distinct purity thresholds, packaging requirements, and regulatory documentation burdens that reshape supplier economics.
Product Type:
Purity grades and physical form drive procurement decisions, with hydrate and solution formats commanding divergent logistics and handling protocols.
- Chloroplatinic Acid Solution:Aqueous formulations at standardized molar concentrations dominate routine industrial procurement for electroplating baths and continuous catalyst manufacturing. Demand concentrates in China's electronics manufacturing zones where semiconductor interconnect plating requires consistent batch-to-batch platinum content.
- Chloroplatinic Acid Hydrate:Crystalline hexahydrate (H2PtCl6·6H2O) delivers precise stoichiometry for pharmaceutical homogeneous catalysis and nanoparticle synthesis protocols. Research institutions in Germany and Switzerland specify this form for flow chemistry applications where water-of-crystallization accuracy affects reaction kinetics.
- Pure Chloroplatinic Acid:Anhydrous or minimally hydrated material serves specialized pyrolysis applications requiring exact platinum loading.
- Chloroplatinic Acid Powder:Spray-dried or milled particulate enables dry-blending with support materials in catalyst precursor manufacturing.
Volume sits with Chloroplatinic Acid Solution; growth tilts toward Chloroplatinic Acid Hydrate.
Application:
End-use specifications fragment the market into divergent purity, packaging, and documentation tiers.
- Catalyst:Heterogeneous and homogeneous catalysis consumes the largest volume share, spanning automotive emission control, petrochemical processing, and pharmaceutical active ingredient synthesis. REACH registration dossiers in Europe and EPA hazardous waste rules in the United States impose full substance documentation on suppliers serving this segment.
- Electronics:Semiconductor barrier seed layers and advanced packaging interconnects require ultra-high-purity precursors with sub-ppb metallic impurity profiles. Miniaturization below 7nm nodes in South Korean and Taiwanese fabrication facilities is accelerating specification tightening for this segment.
- Chemical Synthesis:Platinum-catalyzed hydrogenation and oxidation reactions in fine chemical manufacturing.
- Laboratory Reagents:Analytical standards and research-grade material for academic and government laboratories.
Revenue concentrates in Catalyst applications; Electronics represents the steepest expansion trajectory.
End User:
Customer scale and procurement sophistication separate bulk contract buyers from spot-market purchasers.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers specify catalyst-grade material with full batch analytical data packages and ICH Q3D elemental impurity compliance. Continuous manufacturing adoption in India under PLI scheme incentives is expanding homogeneous catalysis demand.
- Electronics Manufacturers:Integrated device foundries and OSATs negotiate multi-year framework agreements with direct refiner relationships, bypassing distributor margins.
- Automotive:Emission catalyst formulators with closed-loop platinum recovery partnerships.
- Research Institutions:University consortia in the United States now consolidate procurement through cooperative purchasing agreements.
Contract volume flows to Pharmaceuticals; Electronics Manufacturers are consolidating procurement fastest.
Packaging Type:
Inventory value density and handling safety requirements determine container economics.
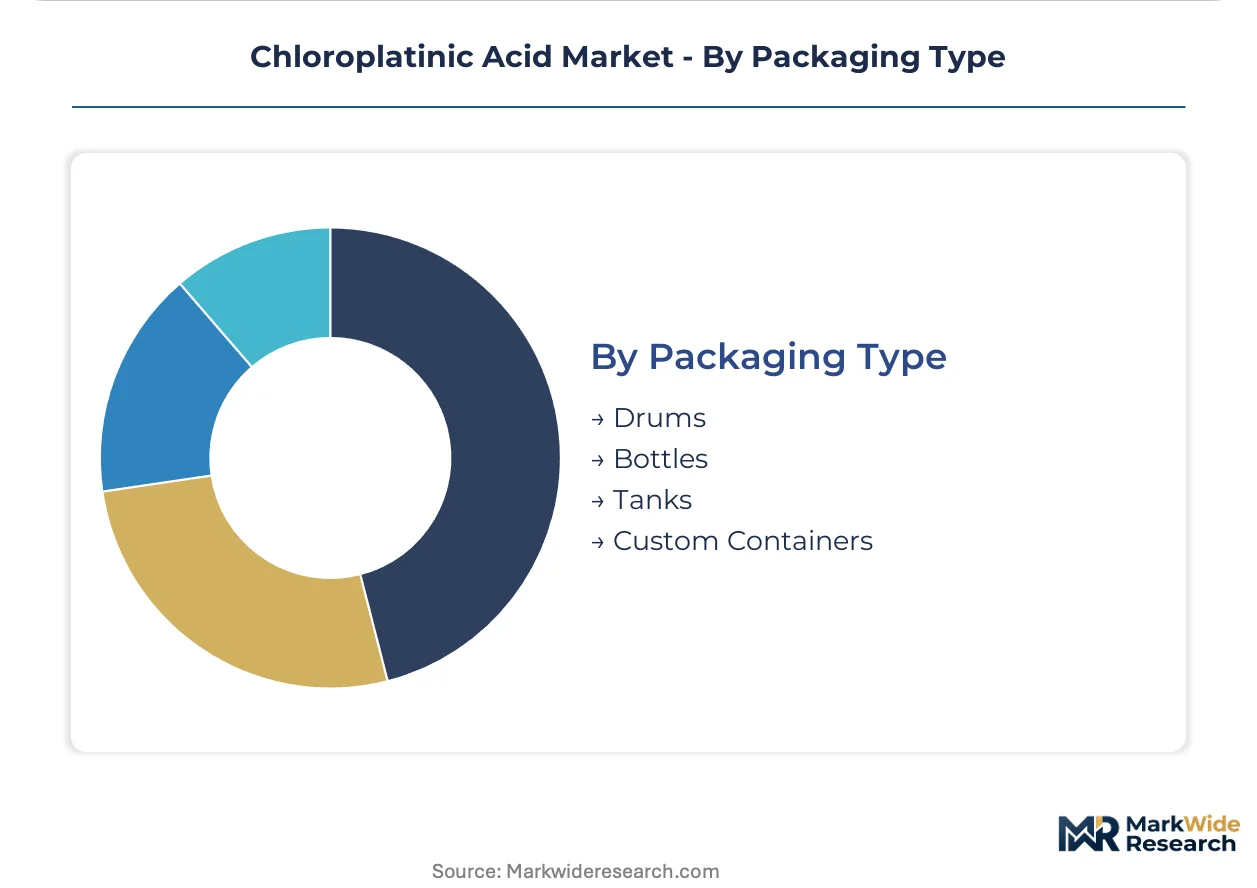
- Bottles:Amber glass or fluoropolymer containers in 100mL to 5L volumes serve laboratory and pilot-scale electronics plating operations. Modular packaging in smaller volumes is hardening as standard for specialty buyers requiring frequent batch turnover.
- Custom Containers:Dedicated fluoropolymer-lined totes and single-use bags with platinum-content certification reduce cross-contamination risk for pharmaceutical catalyst formulators.
- Drums:Stainless or fluoropolymer-lined 200L drums for mid-volume chemical synthesis customers.
- Tanks:Bulk ISO tanks and dedicated tanker deliveries for integrated electroplating facilities.
Shipment value clusters in Bottles; Custom Containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate chloroplatinic acid demand through captive electronics manufacturing and chemical synthesis clusters. Germany's platinum-group metal recovery mandates are compressing virgin material flows and rewiring European supply economics. India's PLI scheme incentives for semiconductor fabrication are catalyzing new procurement channels for catalyst-grade precursors.
China
Semiconductor interconnect plating and pharmaceutical homogeneous catalysis absorb the largest procurement volumes in Jiangsu and Shanghai manufacturing corridors. SAMR enforces GB standards for chemical purity and labeling that constrain both domestic producers and foreign suppliers seeking market access. Suzhou and Wuxi electronics clusters specify ultra-high-purity platinum precursors for advanced packaging nodes below 7nm.
Germany
Automotive emission catalyst formulators and pharmaceutical flow chemistry adopters drive catalyst-grade hydrate demand across the Rhine-Ruhr and Bavarian chemical belts. REACH registration requirements mandate full substance dossiers for chloroplatinic acid import authorization, creating captive demand for compliant regional refiners. Ludwigshafen and Leverkusen host integrated precious metal recovery partnerships that align with tightening EU critical raw materials autonomy objectives.
United States
Research institutions consolidating procurement through cooperative purchasing consortia and electronics manufacturers negotiating direct refiner relationships fragment traditional distributor channels. EPA hazardous waste rules and OSHA permissible exposure limits govern handling, storage, and worker safety protocols for domestic facilities. Greater Boston and Silicon Valley semiconductor clusters require sub-ppb metallic impurity profiles for barrier seed layer applications.
India
Active pharmaceutical ingredient manufacturers adopting continuous manufacturing and emerging semiconductor fabrication under PLI scheme incentives expand homogeneous catalysis demand. CDSCO and BIS regulate chemical import quality and labeling standards affecting foreign supplier market entry. Gujarat and Maharashtra chemical corridors are attracting first-mover catalyst-grade material suppliers seeking framework agreements with domestic formulators.
Switzerland
Specialty chemical producers adopting skid-mounted continuous flow reactors for chloroplatinic acid hexahydrate synthesis serve pharmaceutical catalyst formulators with compressed batch cycle times. Swissmedic and REACH-aligned chemical regulations impose full provenance documentation burdens on suppliers. Basel and Zurich micro-facilities co-locate with research-intensive formulators, shrinking logistics exposure for high-value platinum inventory.
Chloroplatinic Acid Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions in the chloroplatinic acid market. The vendor base clusters around three integrated precious metal refiners controlling high-purity hexachloroplatinic acid production, with regional chemical distributors and specialty formulators occupying mid-tier positions. Strategic archetypes include captive refiners with smelting assets, solution formulators with customized packaging capabilities, and research-grade suppliers with certified analytical data packages. Dominant competitive moves center on closed-loop refining partnerships for spent catalyst recovery and blockchain-tracked supply chain documentation for EU CSRD compliance.
Among diversified chemical conglomerates with precious metal refining heritage, Johnson Matthey and BASF SE exemplify the integrated refiner archetype, leveraging captive smelting assets and platinum-group metal trading operations to control high-purity supply chains. Heraeus occupies a position within the specialty solutions tier, extending precious metal trading reach into formulated chloroplatinic acid products for pharmaceutical and electronics customers. These three anchors represent distinct competitive vectors: backward integration into primary refining, downstream formulation customization, and vertical reach across trading-to-solution value chains.
| Leading Market Players |
|---|
| Tokyo Chemical Industry |
| Yogi Dye Chem Industries |
| ESPI Metals |
| Toronto Research Chemicals |
| Shanghai Xinglu Chemical Technology |
| Johnson Matthey |
| American Elements |
| BASF SE |
| Heraeus |
| Others |
Value Chain & Pricing Dynamics
Continuous flow synthesis adoption in Switzerland and Germany compresses batch cycle times from days to hours, simultaneously lowering unit production costs and concentrating supply among refiners with skid-mounted reactor capabilities. This technology shift rewards integrated precious metal processors with captive smelting assets while squeezing trader margins that lack in-house hexahydrate production.
Pricing Analysis
Short lead-time premiums command substantial markups over contract-scheduled deliveries, with spot inventory availability driving acute price differentiation between urgent pharmaceutical catalyst orders and planned electronics plating procurement. Three-tier pricing structure across premium certified-hydrate, standard solution-grade, and economy bulk-contract levels stratifies the market. Cost compression in standard solution tiers is intensifying because Chinese electronics manufacturers consolidate procurement through multi-year framework agreements. Research institutions exhibit the highest price sensitivity due to grant-funded budget constraints, while semiconductor foundries prioritize purity certification over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's SAMR enforcement of GB standards are reshaping sourcing patterns toward regional micro-facilities co-located with downstream formulators. Supply concentrates in Germany, China, and Switzerland, with high-purity hexachloroplatinic acid production clustering among three integrated precious metal refiners. Raw material flows draw from South African platinum mining concentrates, recycled automotive catalyst scrap, and Russian refined sponge. Single-source refining concentration creates supply interruption exposure from geopolitical disruption or smelter outages. Distribution runs through direct refiner relationships with pharmaceutical and electronics manufacturers, bypassing traditional chemical distributors for high-volume contract buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation around EU CSRD provenance documentation and REACH registration dossiers is forcing consolidation among smaller traders lacking captive analytical certification capabilities. This pressure eliminates marginal players unable to fund blockchain-tracked supply chain infrastructure.
For Market Incumbents: Cement market position by deepening backward integration into spent catalyst recovery partnerships that align with EU critical raw materials autonomy objectives. Invest in ISO-certified analytical laboratories to compress multi-week platinum assay turnaround times that currently delay batch release. Defend against emerging Swiss and German micro-facility competitors by locking pharmaceutical formulators into exclusive multi-year framework agreements with guaranteed hydrate purity specifications. For New Entrants and Emerging Players: Launch via cooperative purchasing consortia relationships with U.S. university systems that are consolidating procurement away from transactional spot buying. Target India's Gujarat and Maharashtra chemical corridors where PLI scheme incentives for semiconductor fabrication and continuous pharmaceutical manufacturing are expanding homogeneous catalysis demand. Penetrate through certified analytical data packages that match incumbent documentation standards at competitive pricing for research-grade hydrate volumes. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified precious metal conglomerates seeking closed-loop refining capabilities and EU regulatory compliance infrastructure. Long-term viability hinges on positioning within the 5-10 year window before platinum-group metal recovery mandates tighten further across European pharmaceutical value chains. Target acquisition archetype: mid-tier solution formulators with established SAMR compliance for China market access and existing pharmaceutical customer relationships. The signal to watch is accelerating semiconductor interconnect miniaturization below 7nm nodes driving specification tightening for ultra-high-purity precursors.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-loop Refining Partnership | Aligns with Germany's platinum-group metal recovery mandates and EU critical raw materials autonomy objectives. |
| Blockchain-tracked Supply Chain Documentation | Satisfies EU CSRD sustainability reporting mandates requiring full precious metal provenance disclosure from mine to product. |
| Skid-mounted Continuous Flow Reactor Deployment | Enables Swiss and German micro-facilities to co-locate with pharmaceutical catalyst formulators, shrinking logistics exposure. |
| Multi-year Framework Agreement Negotiation | Locks in pharmaceutical and electronics procurement consolidating away from transactional spot buying and distributor channels. |
| ISO-certified Analytical Laboratory Investment | Compresses platinum-group metal assay certification turnaround that currently delays batch release and extends working capital cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with precious metal refinery plant managers, pharmaceutical procurement leads, electronics plating technical directors, and specialty chemical distribution channel partners. ECHA REACH registration dossiers, EPA hazardous waste rule filings, SAMR GB standard publications, and SEC 10-K disclosures from diversified chemical conglomerates provided validation benchmarks. Bottom-up demand modeling across catalyst formulators and electronics manufacturers triangulated against top-down platinum precursor consumption estimates.
Granularity-level modeling disaggregated volume and value across product type (solution, hydrate, powder, pure acid), application (catalyst, electronics, chemical synthesis, laboratory reagents), and end user (pharmaceuticals, electronics manufacturers, automotive, research institutions) dimensions. Regional production hub clustering and packaging format logistics were incorporated as cross-cutting variables. CAGRs were derived from segment-level growth trajectory analysis weighted by platinum price scenario assumptions and regulatory compliance cost trajectories. Forecast inputs included semiconductor interconnect miniaturization roadmaps and pharmaceutical continuous manufacturing adoption curves.
The model assumes a particular technology adoption path; alternative pathways for continuous flow synthesis modularization would alter the outlook if adoption accelerates beyond Swiss and German pilot facilities. Forecasts reflect documented assumptions around platinum price volatility, REACH registration enforcement stringency, and China domestic synthesis capacity expansion timelines. Supply interruption scenarios from single-source refining concentration or geopolitical disruption to Russian refined sponge flows could revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Hydrogen Chloride Market
Chemicals
North America Construction Chemicals Market
Chemicals
Chromium Trioxide Market
Chemicals
Triethanolamine Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
SLS and LABSA Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
Phenothiazine Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Diethylenetriamine (DETA) Market