
 Global Organobromine Market | 2026-2036
Global Organobromine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organobromine Market Analysis
Electronics OEM procurement of halogenated flame retardants is collapsing as construction material buyers expand their share of organobromine offtake. Albemarle Corporation leverages its vertically integrated bromine extraction in Arkansas and Jordan to sustain cost leadership across tetrabromobisphenol-A supply chains. ICL Group anchors its position through Dead Sea brine operations and specialized phosphorus-bromine hybrid formulations. Lanxess competes by dominating polymer-additive blending capabilities in Europe and Asia.
Organobromine compounds comprise carbon-bromine covalent bonds synthesized through bromination of hydrocarbon feedstocks, with bromine content typically ranging from 30% to 85% by weight depending on substitution degree and molecular architecture. These compounds function primarily as flame retardants, chemical intermediates, and biocidal agents across industrial manufacturing. Brominated flame retardants lead product type demand by volume, though brominated solvents generate superior margin pools in precision electronics cleaning applications. Construction and electronics applications split downstream consumption, with textiles representing a mature, price-sensitive segment where reactive fixation technologies command premium positioning over additive treatments.
EPA toxicity assessments and REACH authorization lists in Europe are forcing reformulation away from certain polybrominated diphenyl ethers, while China's MEE enforces emission controls on brominated waste streams from derivative manufacturing. India's BIS certification requirements for fire safety in building materials are expanding addressable demand for compliant retardant systems. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized product portfolios offer superior risk-adjusted returns.
Market Dynamics
REACH authorization lists and EPA toxicity assessments are forcing simultaneous reformulation across legacy polybrominated diphenyl ether portfolios while Dead Sea and Arkansas brine concentration sustains supply-side oligopoly. This regulatory-supply tension compresses margins for non-integrated compounders.
Growth Catalysts
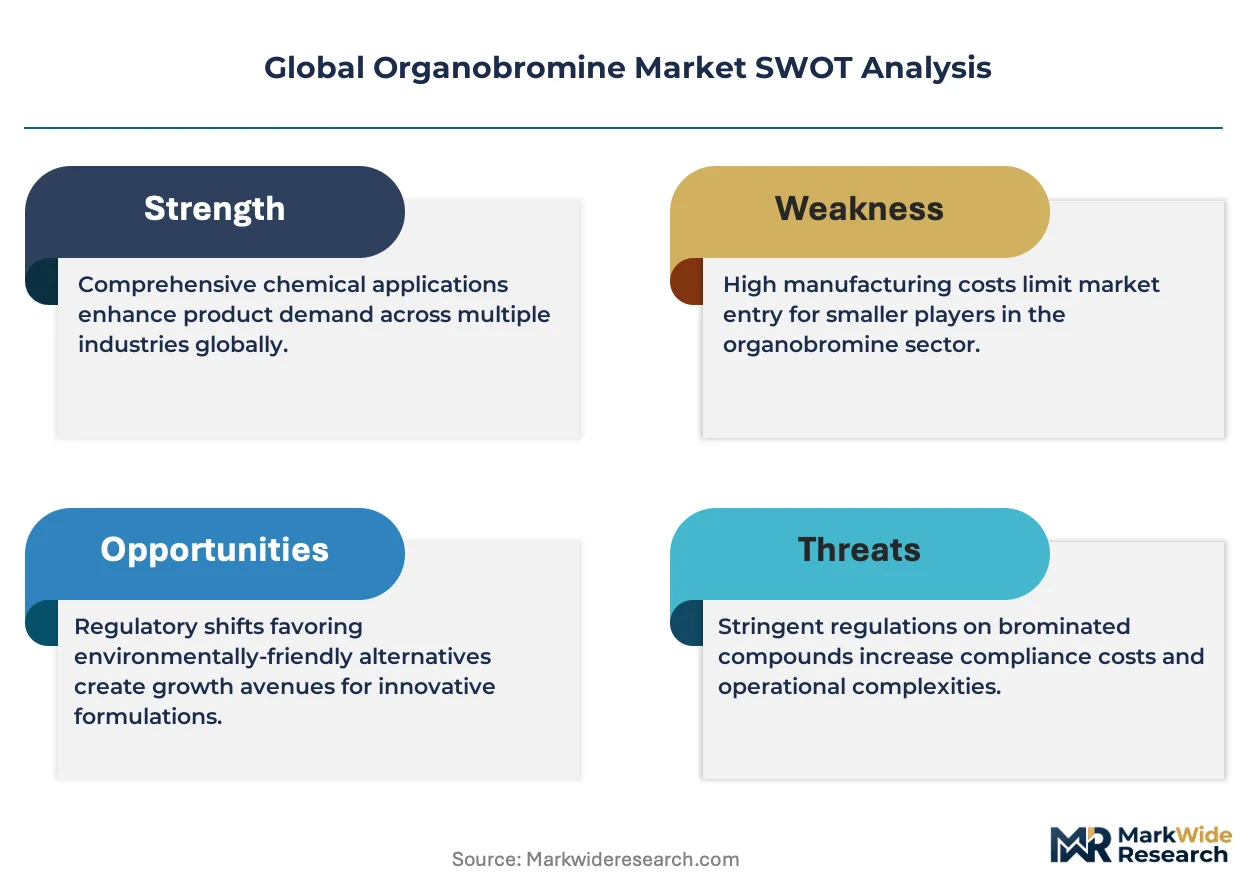
- India's BIS Certification:Mandatory fire safety standards for building materials are expanding addressable demand for compliant retardant systems in construction supply chains.
- Phosphorus-Bromine Hybrid Formulations:Reactive fixation technologies command premium positioning in textiles by replacing additive treatments with covalent bonding approaches.
- Automotive Lightweighting:Thermoplastic polymer demand from electric vehicle battery enclosures and interior components requires flame retardant loadings that organobromine compounds deliver efficiently.
Market Restraints
- Bromine Feedstock Concentration:Arkansas and Dead Sea operations control over 70% of global elemental bromine extraction, creating geographic supply vulnerability.
- Polymeric Substitution Threat:Reactive and inherently flame-retardant polymers are capturing share in electronics housings where additive loading was previously standard.
- REACH Authorization Friction:ECHA's sunset dates for decaBDE and related congeners force costly reformulation timelines without grandfathering provisions.
Strategic Opportunities
- China's Dual Carbon Goals:MEE emission controls on brominated waste streams create first-mover advantage for closed-loop recycling infrastructure investments.
- Precision Electronics Cleaning:Brominated solvents generate superior margin pools in semiconductor fabrication equipment maintenance versus commodity flame retardant applications.
- Polymeric Reactive Alternatives:Covalent incorporation of bromine into polymer backbones escapes REACH restriction scope while maintaining fire performance.
Industry Challenges
- Regulatory Divergence Management:Stakeholders must configure either centralized or regionalized product portfolios across EPA, REACH, and MEE compliance frameworks with incompatible substance lists.
- Legacy Equipment Integration:Existing compounding and extrusion infrastructure requires retrofit for reactive formulation processing, extending capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organobromine Market |
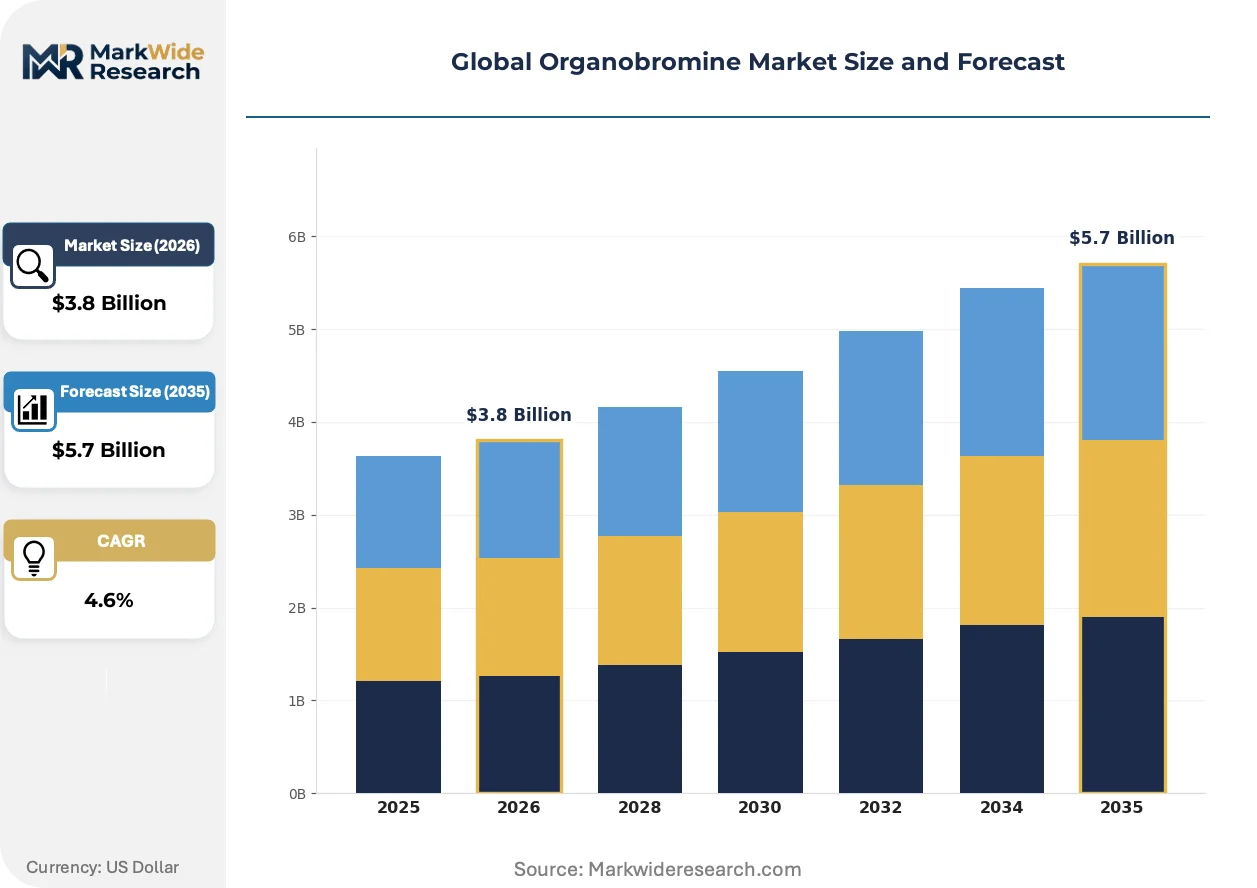
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brominated Flame Retardants, Brominated Solvents, Bromine Derivatives, Brominated Insecticides Application: Textiles, Electronics, Construction, Agriculture End User: Manufacturers, Distributors, Retailers, OEMs Form: Liquid, Solid, Powder, Gas |
| Companies Covered | Albemarle Corporation, ICL Group, Lanxess, Tosoh Corporation, Gulf Resources, Inc., TETRA Technologies, Inc., Jordan Bromine Company, Honeywell International Inc., Solaris Chemtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organobromine Market Emerging Trajectories
Reactive fixation chemistry and polymer-integrated bromination are displacing legacy additive loading across multiple end-use verticals. Regulatory fragmentation between jurisdictions is accelerating formulation diversification.
Polymeric brominated flame retardants with covalent carbon-bromine bonding are displacing small-molecule additives in electronics applications. OEMs in circuit board and connector manufacturing are adopting these systems to preempt REACH authorization triggers. This displacement is compressing volume demand for tetrabromobisphenol-A in traditional additive applications while expanding reactive chemical intermediate demand.
ECHA's expanded candidate list and sunset date acceleration under REACH are forcing inventory phase-outs across European compounders. Manufacturers are redirecting R&D expenditure toward authorization-exempt molecular architectures. Electronics and construction material suppliers with EU exposure are most affected, responding through dual-track formulation portfolios that segregate compliant and legacy product lines by geography.
Specification-driven procurement is consolidating buyer power among tier-one electronics OEMs and construction material distributors. Long-term offtake agreements with bromine producers are replacing spot market purchasing for volume consumers. This shift is most visible in China and the United States, where downstream concentration in automotive and building supply chains enables direct producer relationships that bypass traditional chemical distributor networks.
Global Organobromine Market Segmentation
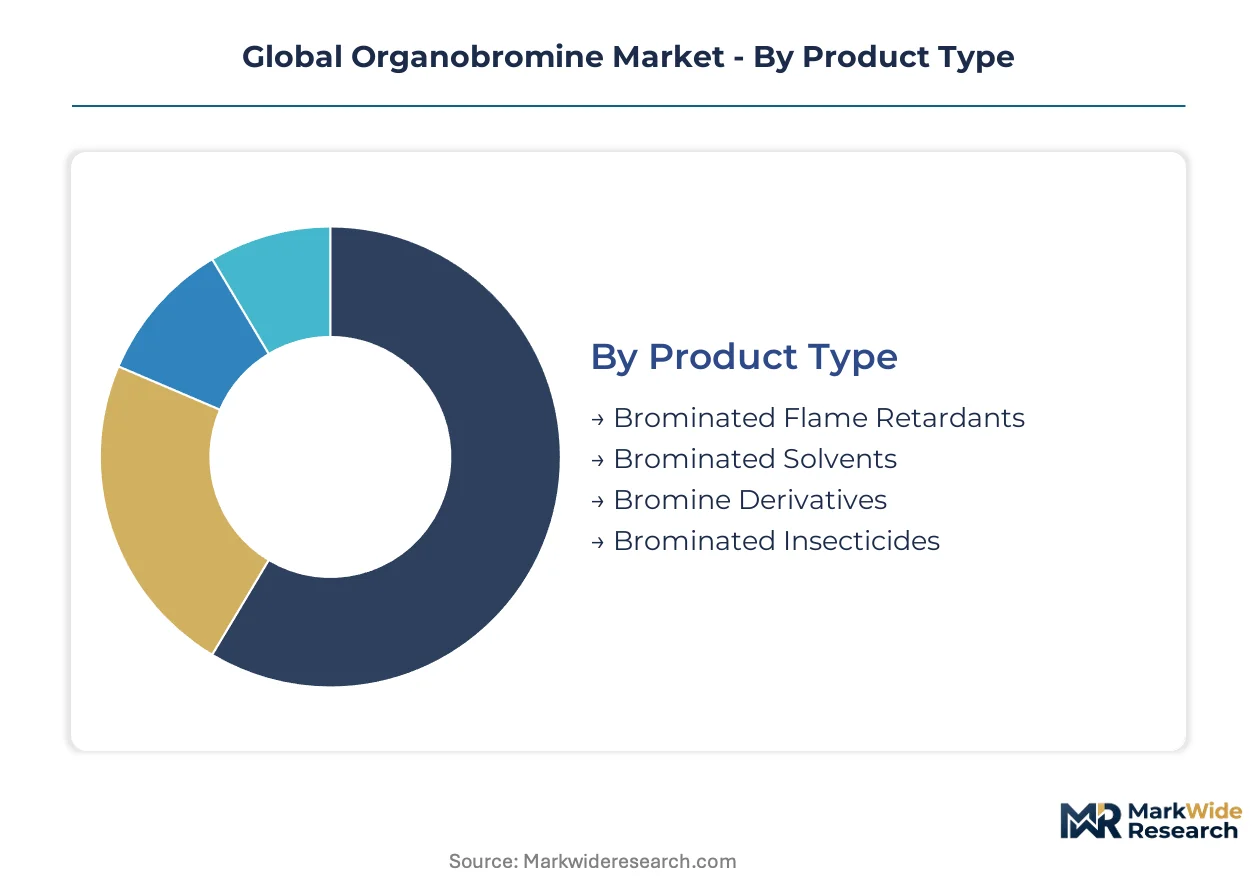
Organobromine market segmentation reveals divergent margin structures across product chemistry and downstream application. Product type and application splits determine pricing power, while form and end-user channels shape distribution economics and working capital intensity.
Product Type:
Margin concentration clusters in specialty formulations where bromine content exceeds 50% by weight and regulatory compliance adds certification premiums.
- Brominated Flame Retardants:These compounds incorporate 30-85% bromine by weight through substitution reactions on aromatic or aliphatic backbones. Demand from circuit board laminates and construction insulation in China and the United States sustains volume leadership despite REACH-driven reformulation pressures on legacy polybrominated diphenyl ethers.
- Brominated Solvents:Precision electronics cleaning applications in semiconductor fabrication generate superior margin pools versus commodity flame retardants. N-Methyl-2-pyrrolidone alternatives face EPA toxicity scrutiny, extending solvent lifecycle in critical equipment maintenance protocols.
- Bromine Derivatives:Pharmaceutical intermediates and agrochemical precursors command specification premiums through CDSCO and FDA impurity thresholds.
- Brominated Insecticides:Methyl bromide phase-out under Montreal Protocol constraints has restricted this segment to quarantine and pre-shipment applications.
The dominant share belongs to brominated flame retardants, while brominated solvents are climbing the fastest on margin expansion in precision manufacturing.
Application:
Application splits track fire safety code adoption intensity and electronics manufacturing density across national industrial bases.
- Electronics:High-layer-count circuit boards and electric vehicle battery enclosures require flame retardant loadings that organobromine delivers efficiently. OEM procurement consolidation in China and South Korea is shifting volume toward long-term offtake agreements with direct bromine producers.
- Construction:India's BIS certification mandates for building materials are expanding addressable demand for compliant retardant systems in insulation and structural composites.
- Textiles:Reactive fixation technologies command premium positioning over additive treatments in protective apparel and upholstery applications.
- Agriculture:Soil fumigation applications face regulatory compression from methyl bromide alternatives and integrated pest management adoption.
Electronics holds the revenue concentration, though construction is gaining share fastest on regulatory mandate expansion in India and the United States.
End User:
Channel structure determines pricing transparency and technical service requirements across the value chain.
- OEMs:Tier-one electronics and automotive manufacturers leverage direct producer relationships that bypass traditional distributor networks, compressing margins for intermediate compounders.
- Manufacturers:Construction material and textile producers require formulation support for reactive integration and compounding line retrofits.
- Distributors:Regional chemical distributors retain relevance in fragmented construction supply chains and emerging market penetration.
- Retailers:Limited to consumer-facing biocidal and specialty chemical applications with low volume contribution.
OEMs command the dominant procurement volume, while manufacturers are expanding their technical service requirements fastest.
Form:
Physical state determines handling infrastructure, transportation economics, and integration compatibility with customer processes.
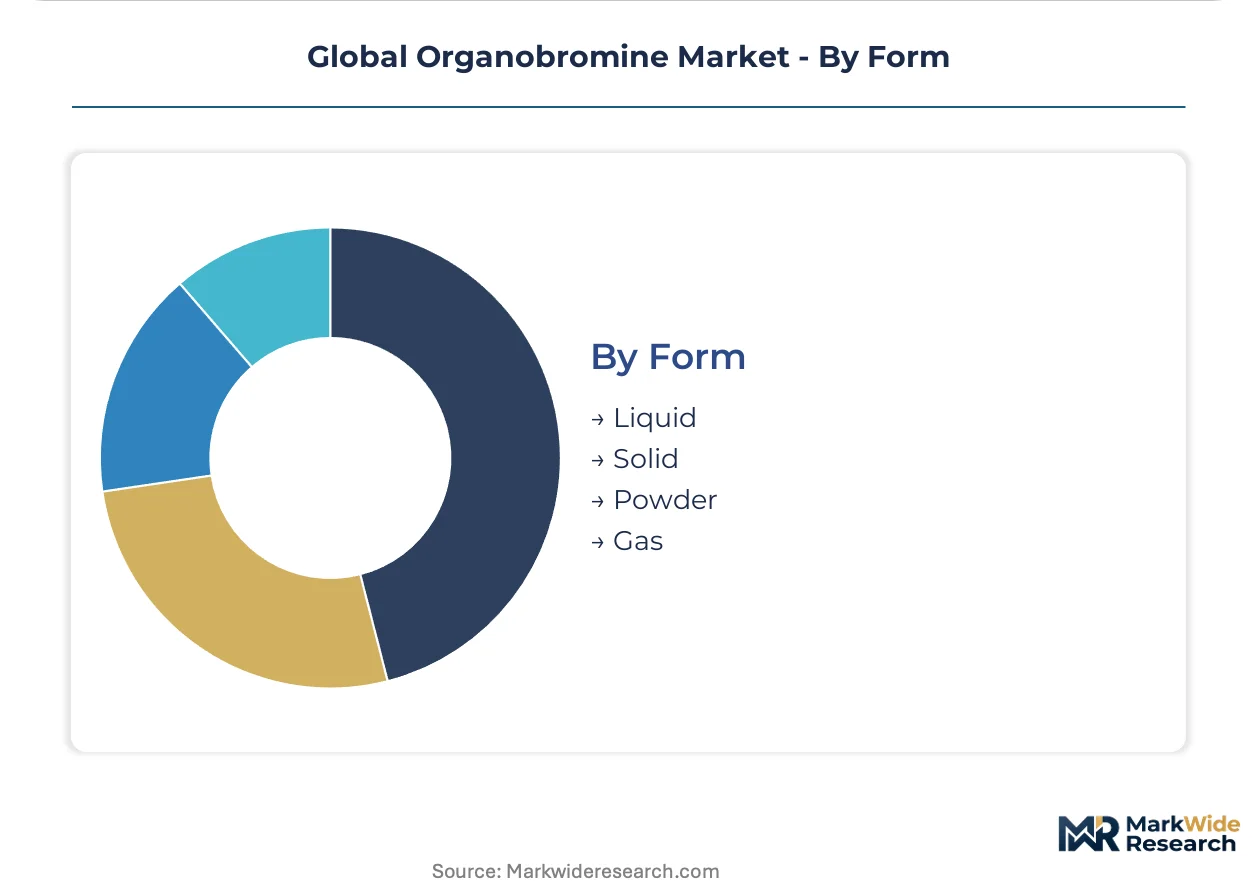
- Liquid:Brominated solvents and reactive intermediates ship in bulk tankers for electronics and pharmaceutical manufacturing integration.
- Solid:Pelletized flame retardants feed directly into thermoplastic extrusion lines for automotive and construction polymer compounding.
- Powder:Fine particle grades require dust control infrastructure but enable uniform dispersion in textile finishing and coating applications.
- Gas:Restricted to methyl bromide fumigation with declining volume under phase-out protocols.
Solid formulations dominate shipment volumes, while liquid forms are expanding most quickly on precision electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel and Port of Rotterdam bromine terminals anchor Atlantic basin chemical logistics, while Dead Sea brine pipelines and Arkansas brine field rail spurs concentrate upstream supply infrastructure.
United States
Electric vehicle battery enclosure manufacturing in Michigan and Tennessee drives flame retardant consumption from thermoplastic compounders. EPA toxicity assessments under TSCA Section 6 accelerate reformulation away from legacy polybrominated diphenyl ethers. The Arkansas bromine extraction corridor feeds directly into Gulf Coast polymer additive blending facilities.
China
High-layer-count circuit board fabrication in Guangdong and Jiangsu provinces sustains organobromine intermediate demand despite dual carbon emission reduction targets. MEE enforcement actions on brominated waste streams from derivative manufacturing force closed-loop recycling investments. The Shandong Peninsula hosts concentrated bromine salt lake processing capacity serving domestic electronics supply chains.
Germany
Automotive lightweighting programs from BMW and Volkswagen in Bavaria and Baden-Württemberg require flame retardant loadings for battery housing thermoplastics. ECHA sunset dates under REACH authorization lists force inventory phase-outs of decaBDE congeners without grandfathering. The Cologne-Düsseldorf chemical corridor specializes in reactive brominated polymer formulation for export markets.
India
BIS certification mandates for fire safety in building materials expand addressable demand across Maharashtra and Gujarat construction supply chains. CDSCO impurity thresholds for pharmaceutical bromine derivatives create specification premiums for compliant manufacturers. The Mumbai-Pune industrial belt concentrates textile finishing operations adopting reactive fixation technologies.
Israel
Dead Sea brine concentration operations supply over one-third of global elemental bromine extraction through integrated pipeline networks. Specialized phosphorus-bromine hybrid formulations from Negev Desert chemical complexes serve European electronics OEMs. The Beersheba-Dead Sea industrial corridor anchors ICL Group's integrated extraction and derivative manufacturing footprint.
Global Organobromine Market Vendor Landscape
Concentration sits with vertically integrated brine extractors controlling upstream feedstock access. The market structure reflects oligopolistic supply-side dynamics where Arkansas and Dead Sea operations command over two-thirds of global elemental bromine output. Three strategic archetypes dominate: captive brine operators with backward integration into extraction, specialty compounders with formulation blending capabilities, and regional distributors serving fragmented construction supply chains. Competitive moves center on long-term offtake agreements with tier-one electronics OEMs and reactive polymer R&D partnerships that preempt regulatory authorization triggers.
Among integrated brine operators, Albemarle Corporation and ICL Group exemplify the extraction-to-derivative archetype through their Arkansas and Dead Sea captive supply positions. Lanxess occupies a position within the European formulation blending tier, leveraging polymer-additive integration capabilities. These three anchors represent divergent geographic and vertical strategies: North American brine concentration, Middle Eastern solar evaporation infrastructure, and European compounding specialization.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group |
| Lanxess |
| Tosoh Corporation |
| Gulf Resources, Inc. |
| TETRA Technologies, Inc. |
| Jordan Bromine Company |
| Honeywell International Inc. |
| Solaris Chemtech |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between tier-one electronics OEMs and Dead Sea or Arkansas brine operators lock in both supply access and price visibility across the forecast horizon, insulating volume buyers from spot market volatility while compressing margins for non-integrated compounders caught between fixed input costs and reformulation-driven demand shifts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by bromine content percentage and REACH compliance certification. Premium tiers capture specification-grade reactive polymers for European electronics OEMs, while standard grades serve construction insulation markets in India and the United States. Price differentiation hinges on vertical integration depth and CDSCO impurity thresholds for pharmaceutical derivatives. Pricing pressure stems from phosphorus-bromine hybrid formulations capturing share in textile applications. Construction material distributors exhibit highest price sensitivity; semiconductor fabrication equipment maintenance buyers show lowest sensitivity due to solvent purity requirements.
Supply Chain Analysis
Strait of Hormuz transit underwrites elemental bromine movement from Dead Sea extraction complexes to European and Asian derivative manufacturing hubs. Geographic supply concentration centers on Israel, the United States, and China, with Jordan contributing through joint venture operations. Raw material dependencies span Dead Sea brine concentration, Arkansas subsurface brine fields, and Shandong Peninsula salt lake deposits. Single-source vulnerability from the Arkansas-Jordan extraction duopoly creates structural risk for non-integrated compounders. Distribution runs through Houston Ship Channel terminals and Port of Rotterdam chemical logistics for Atlantic basin delivery, with direct rail spurs feeding Gulf Coast polymer additive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized brine chemistry expertise and captive extraction infrastructure represent scarce capabilities that concentrate competitive advantage among incumbent operators, leaving formulation-dependent compounders exposed to input cost volatility and regulatory authorization timelines.
For Market Incumbents: Secure long-term offtake agreements with automotive battery enclosure manufacturers in Michigan and Tennessee before phosphorus-bromine hybrid formulations mature. Deepen backward integration into closed-loop recycling infrastructure to preempt MEE emission enforcement in China. Defend against polymeric substitution threats by accelerating reactive fixation R&D partnerships with European textile finishers. For New Entrants and Emerging Players: Lead with precision electronics cleaning solvents as the most penetrable segment, where N-Methyl-2-pyrrolidone alternatives face EPA toxicity scrutiny and incumbent brominated solvent producers command premium positioning. Target India's BIS-certified construction supply chains through reactive polymer formulation services that bypass REACH authorization complexity. Establish go-to-market presence via technical service partnerships with Maharashtra and Gujarat insulation manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward specialty compounders with demonstrated reactive polymer formulation capabilities and existing CDSCO or FDA certification pathways. Long-term viability across the next decade rests on regulatory agility rather than scale economies alone. Watch ECHA sunset date acceleration as the primary inflection signal for portfolio reconfiguration toward authorization-exempt molecular architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Captive supply from Arkansas or Dead Sea operations insulates margin compression from oligopolistic feedstock pricing. |
| Reactive Polymer R&D Partnership | Covalent bromination architectures escape REACH authorization scope while maintaining fire performance specifications. |
| Closed-Loop Recycling Infrastructure | MEE emission controls on brominated waste streams create first-mover advantage in China derivative manufacturing. |
| Long-term Supply Agreement with OEMs | Direct relationships with tier-one electronics manufacturers in Guangdong bypass distributor networks and stabilize volume. |
| Certification Investment for BIS Compliance | Mandatory fire safety standards in Indian building materials expand addressable demand for compliant retardant systems. |
Methodological Framework
A spread of perspectives from plant managers at bromine extraction facilities, procurement leads at electronics OEMs, distribution channel partners in construction supply chains, and technical R&D directors at specialty compounders converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA toxicity assessment databases. Bottom-up volume modeling across product types and applications triangulated against top-down macroeconomic indicators to establish market sizing.
Segmentation dimensions modeled include bromine content grade tier, end-use industry vertical, physical form factor, and regional production hub concentration. CAGRs were derived through regression analysis of historical consumption patterns and forward projection of regulatory mandate timelines across the analysis window. Industry-specific forecast inputs incorporated ECHA sunset date schedules, BIS certification rollout pace, and electric vehicle battery enclosure thermoplastic demand curves.
The analysis sits within stated boundaries; outcomes outside sustained Dead Sea and Arkansas brine concentration economics, or accelerated phosphorus-bromine hybrid substitution rates, would require recalibration. Forecasts reflect documented assumptions regarding REACH authorization scope, MEE enforcement intensity, and OEM procurement consolidation trajectories. Practitioners should keep alternative scenarios live as regulatory divergence between EPA, ECHA, and MEE frameworks evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tanning Agents Market
Chemicals
Phosphotungstic Acid Market
Chemicals
Ferric Chloride Market
Chemicals
Periodic Acid Market
Chemicals
Chlorosilane Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Gas Sweetening Chemicals Market
Chemicals
Fine Chemicals Market
Chemicals
Etidronic Acid Market
Chemicals
Tromethamine Market
Chemicals
Copper Oxychloride Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Fluorine Derivatives Market
Chemicals
Elemental Fluorine Market
Chemicals
Global Methylene Chloride Market
Chemicals
Sodium Azide Market