
 Saudi Arabia E-Commerce Eyewear Market | 2026-2036
Saudi Arabia E-Commerce Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia E-Commerce Eyewear Market Analytics
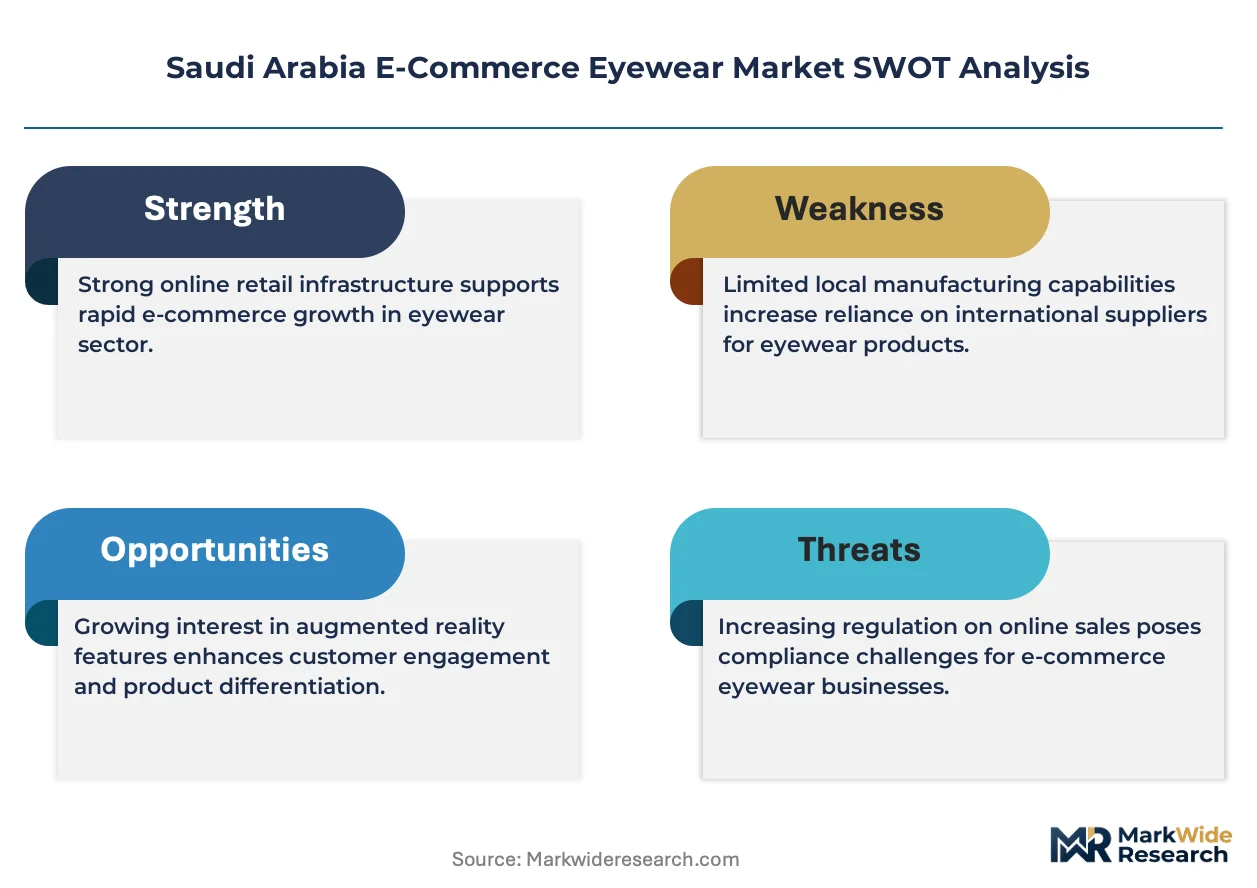
Asset-light marketplace leasing models are reshaping competitive entry in Saudi Arabia's online eyewear sector. Eyewa leverages direct brand partnerships to sustain inventory flexibility without heavy capital deployment. Magrabi anchors its position through vertical integration into optical clinics and lens laboratories. Amazon KSA competes by extending Prime logistics infrastructure into same-day eyewear fulfillment across major cities.
E-commerce eyewear encompasses prescription lenses, frames, sunglasses, and contact lenses sold through digital platforms, with product fulfillment dependent on pupillary distance measurement accuracy and lens index specifications ranging from standard 1.50 to high-index 1.74 materials. The primary commercial purpose centers on replacing traditional optical retail with remote vision correction access, reducing consumer time costs while requiring precise digital fitting tools. Prescription glasses dominate current transaction volume due to recurring replacement cycles and insurance reimbursement familiarity, while virtual try-on technology captures the fastest growth trajectory as smartphone camera accuracy improves and consumer comfort with facial scanning deepens. Online marketplaces concentrate margin pools through commission structures on third-party optical brands, whereas brand websites retain higher per-unit profitability through direct consumer relationships.
SFDA regulates contact lenses and prescription devices as medical products, requiring registration and quality documentation that elevates compliance costs for new entrants. The CITC framework governs data collection from virtual try-on applications, influencing how platforms store biometric facial measurements. E-prescription standards from the Ministry of Health are gradually digitizing the traditional optometrist authorization pathway. Stakeholders must monitor how regulatory convergence between health data privacy and medical device classification will reshape platform operating requirements and partnership structures with licensed eye care professionals.
Market Dynamics
SFDA medical device registration requirements are compressing market entry timelines while simultaneously elevating quality barriers that favor established optical platforms with in-house compliance capabilities over marketplace-only entrants.
Growth Catalysts
- Young urban professionals:This demographic cluster in Riyadh and Jeddah drives transaction velocity through smartphone-native purchasing behavior and same-day delivery expectations.
- SFDA registration framework:Tightening compliance standards for contact lenses and prescription devices are filtering out substandard imports, improving consumer trust in verified digital channels.
- Virtual try-on technology:Smartphone camera accuracy improvements are reducing return rates and enabling remote fitting confidence without physical store visits.
Market Restraints
- Pupillary distance measurement accuracy:Remote measurement tools introduce prescription error risks that generate costly remake cycles and consumer dissatisfaction.
- Lens laboratory concentration:Domestic high-index lens fabrication capacity clusters in Riyadh and Jeddah, creating fulfillment bottlenecks for same-day delivery promises in secondary cities.
- Optometrist authorization dependency:Ministry of Health e-prescription standards require licensed professional validation, adding friction to pure digital purchase flows.
Strategic Opportunities
- Eastern Province urban corridors:Dammam and Khobar exhibit underpenetrated digital eyewear adoption despite comparable disposable income profiles to Riyadh.
- Biometric data integration:Convergence between virtual try-on facial scanning and personalized lens recommendation engines opens subscription-based vision management services.
- Optical clinic partnerships:CITC data governance frameworks incentivize platforms to formalize relationships with licensed eye care professionals for compliant biometric handling.
Industry Challenges
- Certified optometrist recruitment:Platforms struggle to secure sufficient licensed professionals for remote prescription verification at scale.
- Legacy ERP integration:Traditional optical retailers migrating online face complex system reconciliation between inventory management and lens laboratory order protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia E-Commerce Eyewear Market |
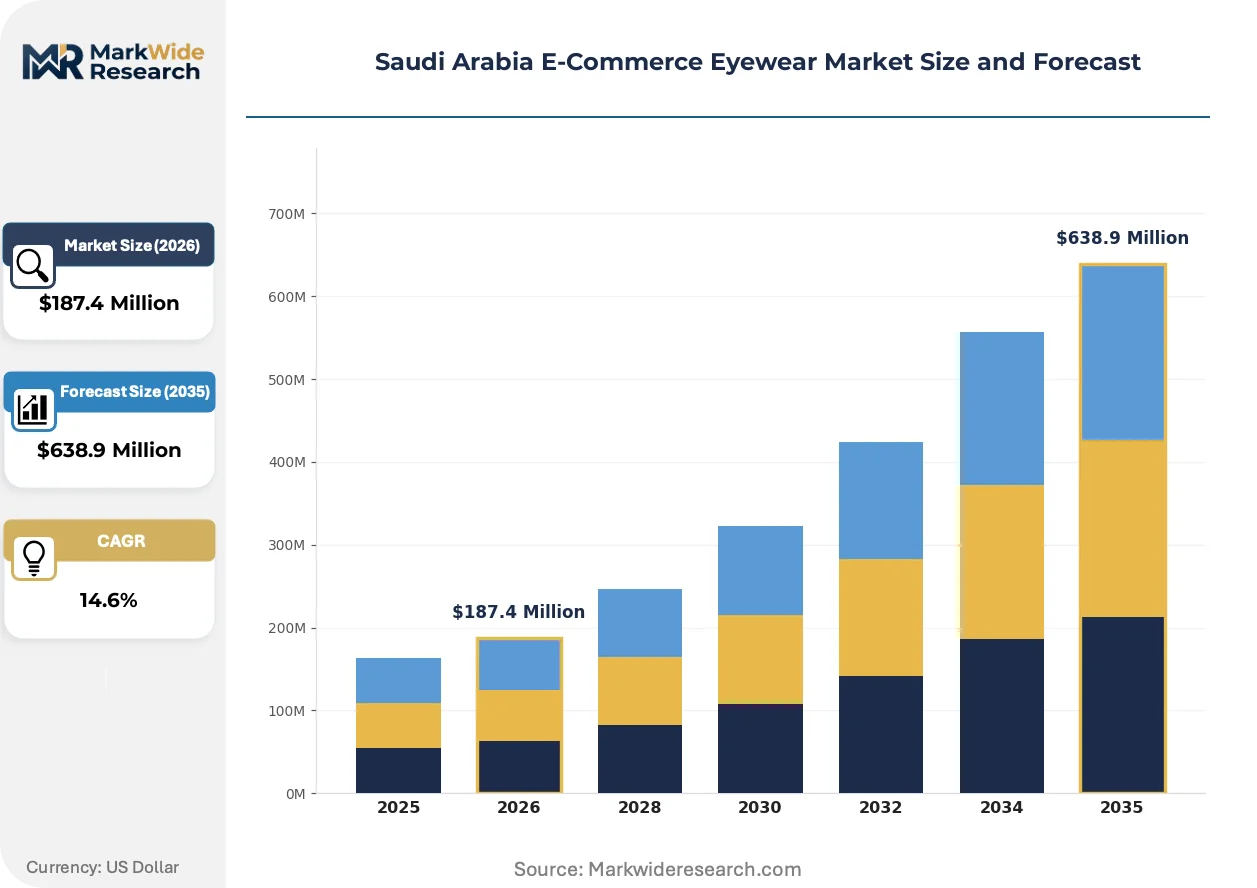
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Sunglasses, Contact Lenses, Safety Glasses Customer Type: Individuals, Retailers, Corporations, Eye Care Professionals Technology: Virtual Try-On, Augmented Reality, 3D Printing, E-Prescriptions Distribution Channel: Online Marketplaces, Brand Websites, Social Media, Affiliate Platforms |
| Companies Covered | Eyewa, Magrabi, Al Jaber Optical, Al Bassam Optical, Vision Express, Noon, Amazon KSA, EssilorLuxottica, Al Maha Optical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia E-Commerce Eyewear Market Evolving Landscape
Digital fitting accuracy is overtaking physical retail convenience as the primary competitive battleground, with biometric measurement tools and regulatory compliance automation emerging as the decisive capability differentiators.
Smartphone-based pupillary distance measurement applications are digitizing the prescription capture process that previously required in-person optometrist visits. Young urban professionals in Riyadh and Jeddah are adopting these tools at accelerating velocity, compressing the traditional multi-day optical retail journey into minutes. This capability is digitizing inventory allocation decisions, enabling platforms to route orders to lens laboratories before physical frame shipment.
SFDA medical device classification updates are tightening registration documentation requirements for silicone hydrogel contact lenses and toric prescription products. The industrial consequence elevates compliance costs disproportionately for marketplace-only sellers lacking in-house quality assurance infrastructure. Contact lens segments are responding by consolidating supplier relationships toward manufacturers with established SFDA registration histories.
Subscription-based lens replacement programs are displacing single-transaction purchasing patterns among frequent contact lens wearers. Digital platforms are capturing recurring revenue streams that traditional optical retailers dominated through in-person reorder reminders. This behavioral shift concentrates most visibly in Riyadh, where digital payment penetration and automated delivery logistics enable seamless replenishment cycles.
Saudi Arabia E-Commerce Eyewear Market Segmentation
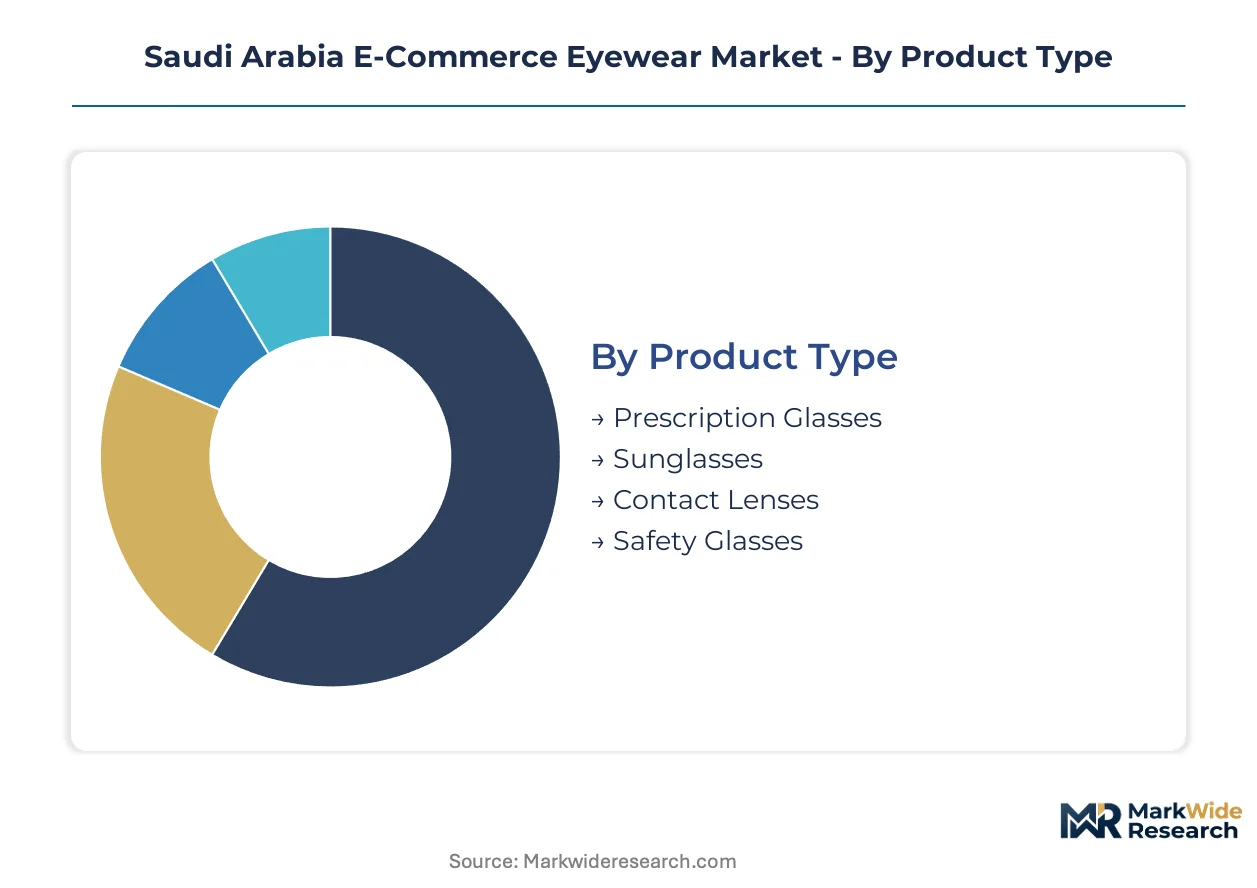
E-commerce eyewear segmentation in Saudi Arabia reflects distinct purchasing workflows, each demanding specialized digital infrastructure. Product categories, customer profiles, and enabling technologies shape platform investment priorities and margin structures differently.
Product Type:
The use-case spectrum spans daily vision correction, sun protection, aesthetic enhancement, and occupational safety, each carrying unique regulatory and fulfillment requirements.
- Prescription Glasses:These products combine optical frames with corrective lenses requiring precise pupillary distance measurements and SFDA-compliant lens index documentation. Demand concentrates among Riyadh-based young urban professionals seeking same-day delivery, driven by insurance reimbursement familiarity and recurring replacement cycles every 18-24 months.
- Contact Lenses:Silicone hydrogel and toric variants fall under SFDA medical device classification, elevating registration documentation burdens for sellers. Adoption clusters heavily in Jeddah, where digital payment penetration enables subscription-based replenishment models displacing single-transaction purchasing.
- Sunglasses:Non-prescription sun protection and prescription-compatible polarized options serve fashion-forward consumers and outdoor workers. UV protection certification drives purchase decisions.
- Safety Glasses:Industrial-grade eye protection for construction, manufacturing, and laboratory environments requires impact resistance ratings. Corporate procurement channels dominate volume.
The dominant share belongs to Prescription Glasses, while Contact Lenses is closing the gap fastest.
Customer Type:
Cost tier differentiation separates high-frequency individual purchasers from institutional buyers negotiating volume discounts and service-level agreements.
- Individuals:Smartphone-native consumers in Riyadh and Jeddah drive transaction velocity through virtual try-on adoption and same-day delivery expectations. Personal insurance coverage influences lens material selection.
- Retailers:Traditional optical shops sourcing inventory through digital wholesale channels seek frame variety without capital-intensive stockholding. These buyers prioritize return policies and minimum order flexibility.
- Corporations:Enterprise buyers procure safety eyewear and vision benefits packages, requiring bulk pricing and centralized billing. Eastern Province industrial corridors generate concentrated demand.
- Eye Care Professionals:Licensed optometrists and ophthalmologists utilize platforms for patient-directed frame selection and e-prescription fulfillment, bridging digital retail with clinical validation requirements.
Individuals command the volume base, though Corporations deliver the highest per-transaction value.
Technology:
Application maturity separates proven smartphone tools from emerging manufacturing and diagnostic capabilities still scaling toward commercial viability.
- Virtual Try-On:Smartphone camera-based facial scanning generates precise frame fit recommendations and pupillary distance estimates. Riyadh consumers show highest comfort with biometric data sharing under CITC governance frameworks.
- Augmented Reality:Real-time lens tint and frame style visualization overlays digital products onto live camera feeds, reducing return rates for sunglasses and fashion-forward purchases.
- 3D Printing:On-demand frame fabrication from digital models enables mass customization of bridge widths and temple lengths. Domestic production capacity remains limited.
- E-Prescriptions:Ministry of Health standards for digital optometrist authorization are gradually replacing paper-based validation, streamlining purchase flows while maintaining clinical oversight.
Virtual Try-On anchors current platform differentiation, while E-Prescriptions is expanding most quickly as regulatory digitization accelerates.
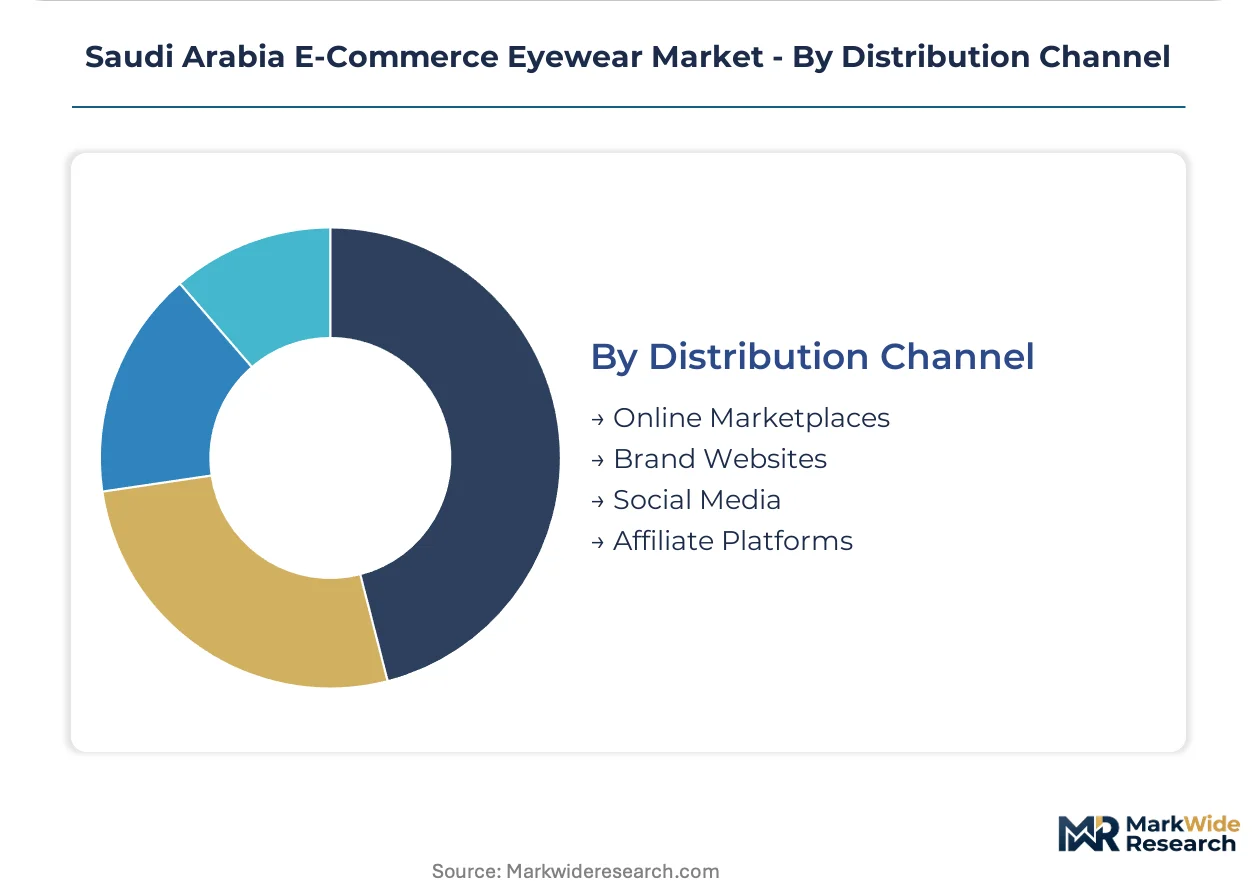
Distribution Channel:
Margin structure varies sharply between commission-based marketplace models and direct-to-consumer ownership of customer relationships.
- Online Marketplaces:Amazon KSA and regional platforms aggregate third-party optical brands, capturing margin through commission structures while outsourcing fulfillment and customer service.
- Brand Websites:Direct consumer relationships enable higher per-unit profitability and proprietary virtual try-on data collection. Eyewa exemplifies this asset-light marketplace leasing approach.
- Social Media:Instagram and TikTok commerce channels leverage influencer partnerships and shoppable content for sunglasses and fashion frames, particularly among younger demographics.
- Affiliate Platforms:Commission-based referral networks connect content creators and comparison sites with optical retailers, expanding reach without fixed marketing spend.
Online Marketplaces hold the transaction volume lead, though Brand Websites are gaining share fastest through superior unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA medical device registration incentives and CITC data governance frameworks are channeling investment toward compliant digital infrastructure across Saudi Arabia's major urban corridors.
Riyadh
Young urban professionals drive same-day delivery transaction velocity through smartphone-native purchasing behavior. SFDA registration requirements for prescription devices filter out non-compliant sellers, elevating trust in verified platforms. Digital payment penetration and automated logistics clusters in Riyadh enable seamless replenishment cycles for contact lens subscriptions.
Jeddah
Virtual try-on adoption accelerates fastest among fashion-forward consumers seeking sunglasses and aesthetic frames. CITC biometric data governance shapes how platforms store facial measurements from smartphone camera scanning. Lens laboratory capacity concentrates in Jeddah's industrial zones, supporting rapid fulfillment for high-index prescription orders.
Eastern Province
Dammam and Khobar exhibit underpenetrated digital eyewear adoption despite comparable disposable income to Riyadh. Ministry of Health e-prescription standards are gradually digitizing optometrist authorization pathways in the region. Corporate procurement of safety eyewear from Eastern Province industrial corridors generates concentrated B2B demand.
Western Region
Tourism and pilgrimage traffic in Makkah and Madinah create seasonal spikes in non-prescription sunglasses demand. SFDA contact lens classification as medical devices tightens import documentation for marketplace sellers serving transient populations. Local optical clinic networks are formalizing partnerships with digital platforms for compliant e-prescription fulfillment.
NEOM Northwest
Smart city infrastructure investments prioritize digital health integration including remote vision correction services. Regulatory sandboxes under national transformation programs test streamlined medical device registration for innovative eyewear technologies. Early-stage logistics corridors are positioning NEOM as a future fulfillment node for next-day delivery across the Red Sea coast.
Saudi Arabia E-Commerce Eyewear Market Competitive Landscape
Channel-controlling players compete with product-specialist players for margin capture across Saudi Arabia's online eyewear sector. The market structure shows moderate consolidation around vertically integrated optical groups and asset-light marketplace operators. Three archetypes dominate: vertically integrated clinic-laboratory chains, pure-play digital marketplaces with direct brand partnerships, and global logistics platforms extending fulfillment infrastructure. Competitive moves center on securing SFDA registration capabilities and building same-day delivery networks in secondary cities.
Within the vertically integrated tier, Magrabi anchors optical clinic and lens laboratory control. Eyewa exemplifies the asset-light marketplace model through direct brand partnership structures. Amazon KSA occupies the logistics-extension position, leveraging Prime infrastructure for rapid fulfillment. Each represents distinct capital deployment strategies for navigating tightening SFDA compliance requirements.
| Leading Market Players |
|---|
| Eyewa |
| Magrabi |
| Al Jaber Optical |
| Al Bassam Optical |
| Vision Express |
| Noon |
| Amazon KSA |
| EssilorLuxottica |
| Al Maha Optical |
| Others |
Value Network & Pricing Analysis
Laboratory undercapacity in Jeddah and Riyadh drives lens fabrication backlogs that compress same-day delivery margins while elevating premiums for verified SFDA-registered suppliers. This utilization squeeze rewards platforms with captive laboratory relationships and pressures marketplace-only sellers toward price concessions or extended fulfillment windows.
Pricing Analysis
SFDA registration tier creates the primary spread between premium and standard pricing tiers in Saudi Arabia's e-commerce eyewear sector. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, lens index material, and virtual try-on integration depth. Cost compression in the economy tier is intensifying because unregistered imports face escalating customs scrutiny. Corporate buyers negotiating safety eyewear bulk contracts show lowest price sensitivity, while young urban professionals purchasing fashion sunglasses exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia dominates import cost variability for optical frames and lens blanks. Manufacturing concentrates in China, Italy, and South Korea for premium acetate frames, high-index lens substrates, and silicone hydrogel contact lens polymers respectively. Domestic fulfillment hinges on Riyadh-based lens laboratories and Jeddah port clearance efficiency. Single-source vulnerability in toric lens fabrication creates bottlenecks during regulatory inspection backlogs. Distribution runs through platform-operated dark stores in major metros and third-party logistics partnerships for secondary city coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's e-commerce eyewear sector is experiencing high-growth disruption as SFDA medical device classification and biometric data governance reshape platform economics. Virtual try-on technology adoption and subscription-based contact lens replenishment are compressing traditional optical retail timelines.
For Market Incumbents: Build regulatory compliance moats through SFDA registration in-house capabilities and licensed optometrist networks. Deepen backward integration into lens laboratories to secure same-day delivery capacity against Jeddah and Riyadh utilization constraints. Formalize partnerships with CITC-compliant biometric data handlers to preempt privacy enforcement actions.
For New Entrants and Emerging Players: Pursue white-space expansion in Dammam and Khobar's underpenetrated Eastern Province corridors where disposable income matches Riyadh but digital eyewear adoption lags. Target corporate safety eyewear procurement channels with centralized billing and bulk pricing structures. Launch through social commerce channels leveraging influencer partnerships for sunglasses and fashion frame categories.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contact lens subscription platforms with automated replenishment cycles. Long-term viability favors vertically integrated clinic-laboratory chains over pure marketplace models as SFDA compliance costs escalate. Monitor e-prescription standardization velocity from the Ministry of Health as the decisive inflection signal for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Compresses market entry timelines while filtering substandard imports from marketplace listings. |
| Lens Laboratory Partnership | Secures captive fabrication capacity for same-day delivery promises in Riyadh and Jeddah. |
| Virtual Try-On Platform Integration | Reduces return rates through smartphone camera accuracy improvements and biometric fit validation. |
| Subscription Model Launch | Captures recurring revenue streams from frequent contact lens wearers displacing single-transaction patterns. |
| Eastern Province Geographic Expansion | Exploits underpenetrated Dammam-Khobar corridor with comparable income profiles to established metros. |
Research Methodology
Initial hypotheses were tested against primary input from platform operations executives, SFDA regulatory consultants, lens laboratory managers, and optical clinic network directors and refined through secondary validation. Sources included SFDA medical device registration databases, CITC data governance circulars, Ministry of Health e-prescription standards, customs import records for optical products, and platform fulfillment disclosures. Bottom-up transaction volume estimates and top-down market sizing were triangulated against laboratory capacity utilization signals.
Demand-supply balance across the analysis window was modeled through segmentation by product type, customer archetype, enabling technology, and distribution channel. CAGRs were derived from fitted growth curves calibrated against smartphone penetration trajectories, digital payment adoption rates, and virtual try-on technology diffusion patterns. Forecast inputs incorporated SFDA registration timeline assumptions and lens laboratory capacity expansion plans.
Sensitivities concentrate around SFDA enforcement intensity, e-prescription standardization velocity, and biometric data governance evolution. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation schedules. Material shifts in medical device classification scope or CITC privacy enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Europe Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
Blue Light Glasses Market
Eyewear
Eyewear Market
Eyewear
Goggles Market
Eyewear
Anti-Fog Lens Market
Eyewear
Asia-Pacific Eyewear Market
Eyewear
Glasses Frame Market
Eyewear
Face and Ear Bow Market
Eyewear
Smart Eyewear Market
Eyewear
Plano Sunglasses Market
Eyewear
United States Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Sunglasses Pouch Market