
 France Packaging Market | 2026-2036
France Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Packaging Market Foresight
France's anti-waste law for a circular economy is consolidating the cost-of-entry calculus for domestic converters. Smurfit Kappa Group PLC leverages its pan-European containerboard network to anchor corrugated supply across French agricultural exports. DS Smith PLC specializes in recycled fiber-based packaging, competing aggressively for e-commerce fulfillment contracts with Paris-based distribution centers. International Paper Company sustains its position through scale advantages in industrial paper grades serving northern France's manufacturing belt.
France packaging encompasses the design, fabrication, and supply of protective enclosures using materials ranging from molded fiber and extruded polymers to cold-rolled aluminum and borosilicate glass, with specifications typically covering barrier properties, tensile strength, and shelf-life extension. The primary purpose spans containment, preservation, information display, and logistics efficiency across supply chains. Paperboard leads among packaging materials due to France's aggressive paper recycling infrastructure and retailer sustainability mandates, while biodegradable alternatives represent the fastest-expanding category as industrial composting capacity scales around Lyon and Nantes. Bags and pouches within packaging types capture disproportionate growth from fresh produce and convenience food segments, whereas bottles and jars maintain entrenched positions in wine, spirits, and pharmaceutical liquids.
ANSM oversees pharmaceutical packaging standards, ECHA enforces REACH compliance for chemical migration limits, and France's DGCCRF monitors food-contact material safety through market surveillance campaigns. These frameworks collectively elevate testing costs and restrict polymer additives, redirecting converter investment toward approved substrates and traceability systems. Stakeholders must monitor forthcoming revisions to the EU Packaging and Packaging Waste Regulation, as delegated acts will recalibrate recyclability definitions and extended producer responsibility fees before the next compliance cycle takes hold.
Market Dynamics
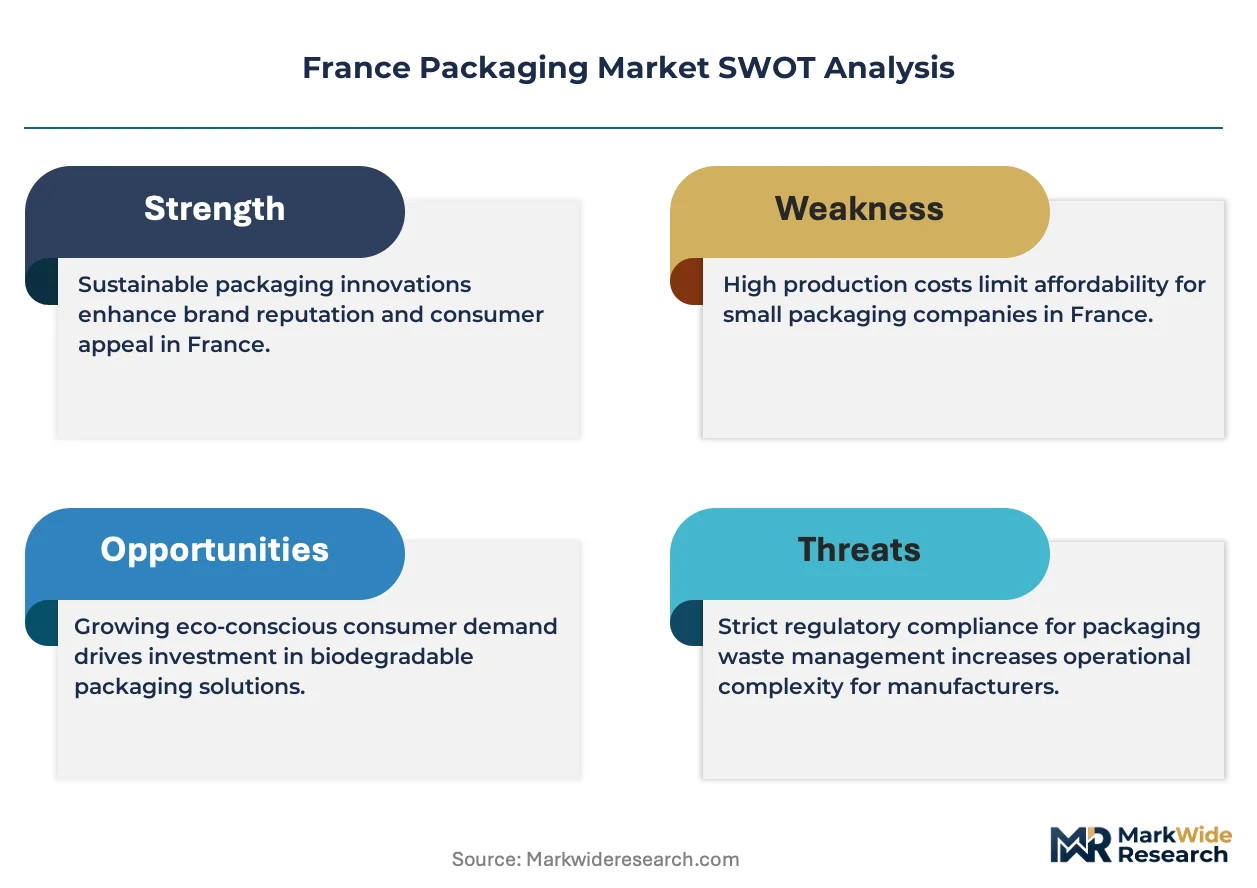
France's anti-waste law for a circular economy is compressing converter margins while redirecting capital toward approved substrates and traceability infrastructure. DGCCRF enforcement campaigns are accelerating compliance costs for food-contact materials.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclability definitions under revision are pulling investment into fiber-based solutions ahead of delegated acts taking effect.
- Île-de-France distribution corridor:E-commerce fulfillment density around Paris is generating concentrated demand for corrugated and flexible formats.
- Industrial composting scale-up:Biodegradable packaging uptake is accelerating around Lyon and Nantes as municipal processing capacity expands.
Market Restraints
- Recycled fiber cost volatility:Containerboard input prices fluctuate with European collection rates and export demand from Asian markets.
- REACH compliance friction:ECHA chemical migration limits are restricting polymer additive portfolios and extending reformulation timelines.
- Glass substitution threat:Premium wine and spirits producers retain bottle formats despite lightweighting advances in PET and aluminum.
Strategic Opportunities
- Rhône-Alpes pharma cluster:ANSM serialization requirements are opening specialized contract packaging capacity for temperature-sensitive biologics.
- Extended producer responsibility fee restructuring:Modulated eco-modulation under France's circular economy law rewards mono-material designs with lower compliance levies.
- Smart packaging convergence:NFC-enabled labels combined with blockchain traceability are penetrating high-value agricultural exports from Provence.
Industry Challenges
- Composting certification timelines:Industrial compostability validation under EN 13432 requires 6-12 month testing cycles that delay product launches.
- Retrofitting legacy filling lines:Paperboard barrier coatings demand heat-seal temperature recalibration that disrupts throughput at established beverage plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Packaging Market |
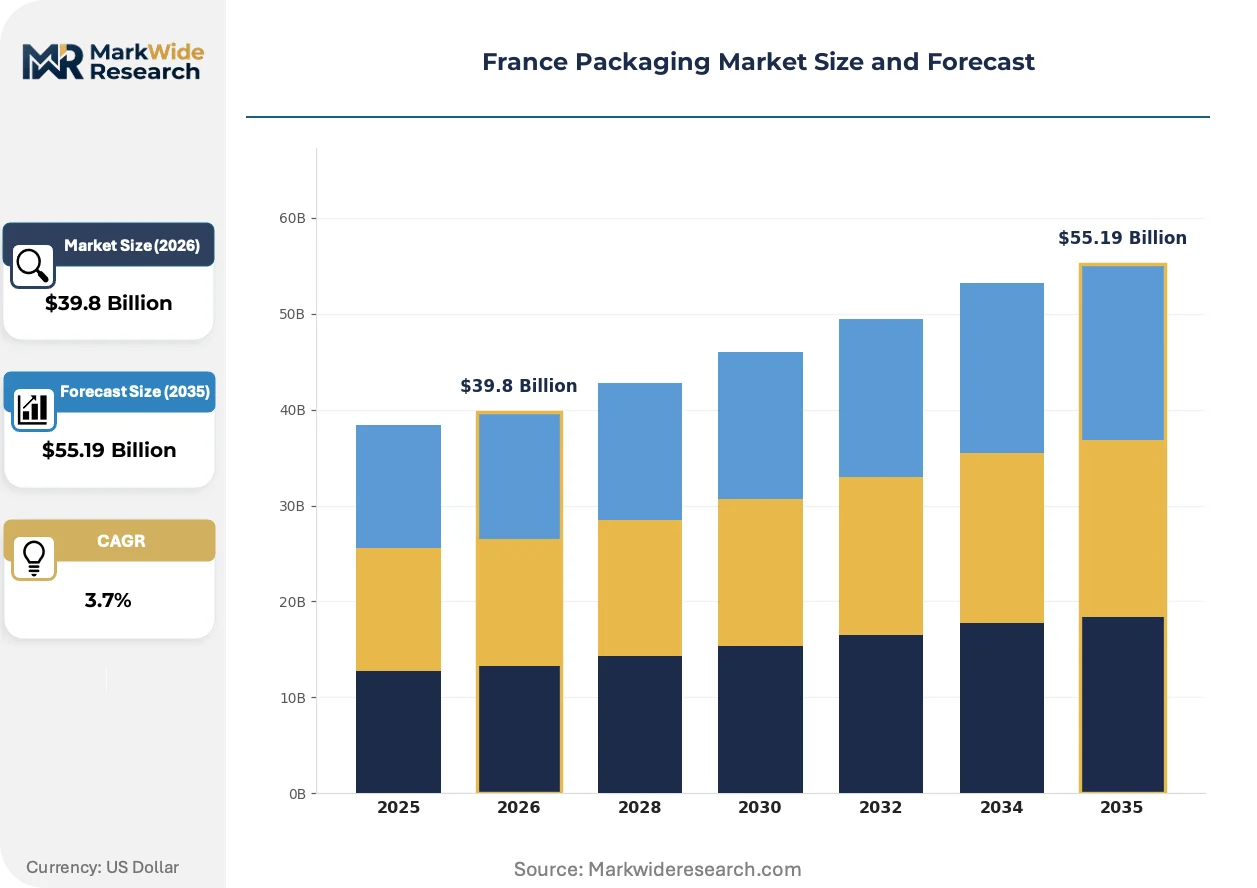
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $55.19 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Material: Plastic, Paperboard, Metal, Glass, Biodegradable, Composite End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Chemicals, Agriculture Packaging Type: Bags & Pouches, Boxes & Cartons, Bottles & Jars, Trays & Containers, Tubes, Wraps Distribution Channel: Retail Chains, Online Stores, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | International Paper Company, DS Smith PLC, Tetra Pak International SA, Smurfit Kappa Group PLC, AR Packaging Group AB, Smurfit WestRock, Mondi plc, Ball Corporation, Amcor plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Packaging Market Shifts & Advancements
Active coating technologies and digital traceability layers are compressing traditional converter value chains while opening specialized service tiers around compliance and authentication.
Water-based barrier coatings for paperboard are consolidating technical specifications across French fresh produce supply chains. Retailers in the Île-de-France corridor are mandating these formats for private-label ready meals. The technology is consolidating mid-tier converters into dedicated coating partnerships or captive supply arrangements with integrated paper mills.
France's DGCCRF has intensified market surveillance campaigns for food-contact material safety, elevating third-party testing costs for imported polymer films. Domestic converters with in-house migration testing capability are capturing share from traders lacking laboratory infrastructure. Wine and spirits exporters to Asia-Pacific markets face dual compliance burdens from both EU REACH and destination-country registration requirements.
Centralized procurement for packaging is consolidating buying power among French retail cooperatives and agricultural export consortia. Regional distribution centers around Lyon are negotiating multi-year corrugated supply agreements that displace spot-market purchasing. This concentration is most visible in the Rhône-Alpes dairy and cheese segments, where cooperative processors are standardizing pouch formats across product lines to achieve volume-scale pricing.
France Packaging Market Segmentation
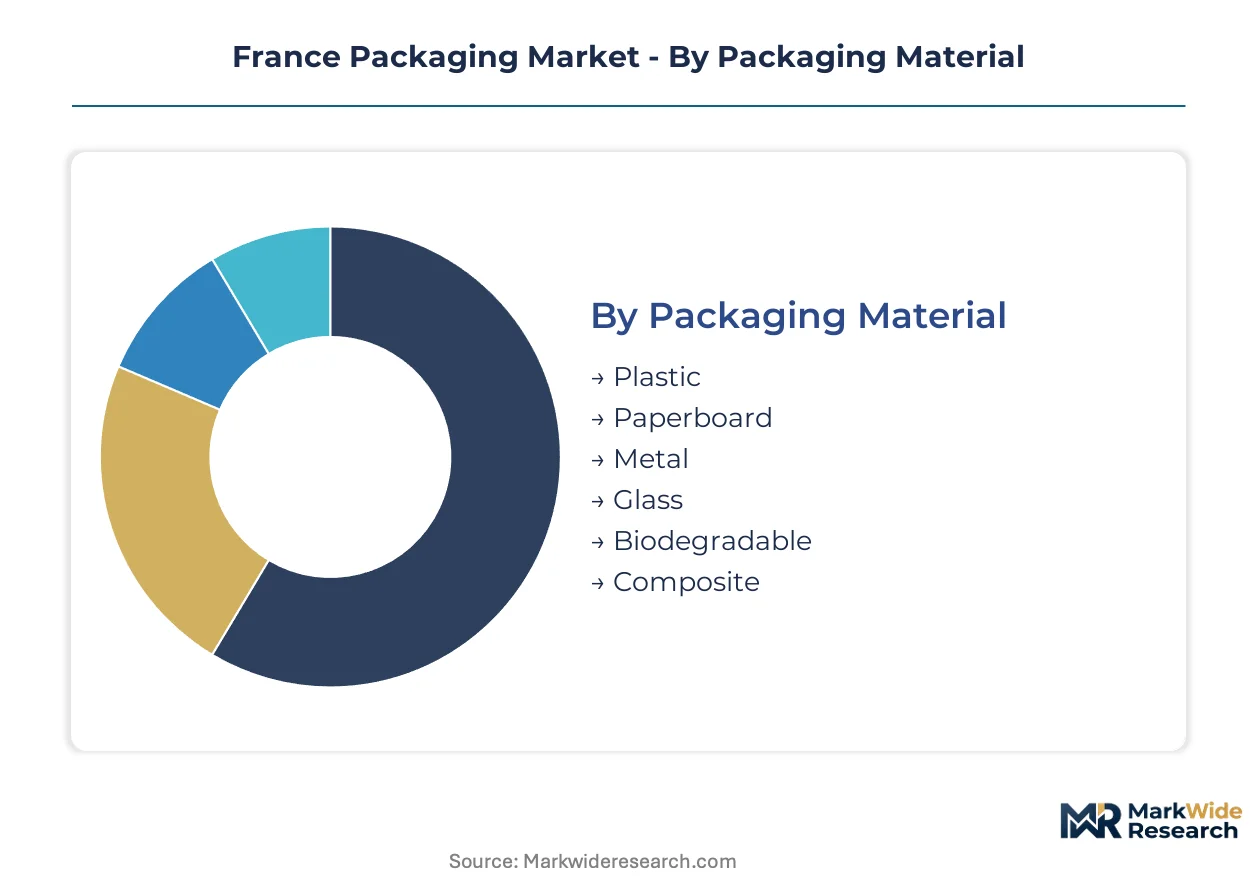
Segmentation in the France packaging market reflects divergent compliance burdens and substrate performance requirements across regulatory zones. Buyers select materials and formats based on DGCCRF enforcement exposure, ECHA migration limits, and retailer sustainability mandates rather than unit cost alone.
Packaging Material:
Purchasing decisions in this category pivot on recyclability certification and extended producer responsibility fee exposure under France's circular economy law.
- Paperboard:Recycled fiber construction with FSC chain-of-custody certification dominates fresh produce and e-commerce fulfillment. Demand concentrates in the Île-de-France corridor where retailer mandates require mono-material designs for lower eco-modulation levies.
- Plastic:Polymer films and rigid containers face tightening REACH additive restrictions. Rhône-Alpes pharmaceutical and personal care manufacturers are shifting toward bio-based alternatives to preempt compliance friction.
- Metal:Cold-rolled aluminum and tinplate serve premium wine closures and aerosol applications with established collection infrastructure.
- Glass:Borosilicate and soda-lime formats retain entrenched positions in wine, spirits, and pharmaceutical liquids despite lightweighting competition.
- Biodegradable:Industrial compostable polymers are expanding around Lyon and Nantes as municipal processing capacity scales.
- Composite:Multi-layer barrier structures face recyclability scrutiny under revised EU Packaging and Packaging Waste Regulation definitions.
Volume sits with paperboard; growth tilts toward biodegradable alternatives.
End Use Industry:
Application-specific barrier requirements and serialization mandates determine converter selection criteria across French manufacturing clusters.
- Food & Beverage:The largest demand pool spans fresh produce, dairy, ready meals, and wine exports. ANSM and DGCCRF dual oversight elevates testing costs for contact materials.
- Personal Care:Cosmetic brands in the Paris basin specify airless pumps and mono-material tubes to meet retailer sustainability scorecards.
- Pharmaceuticals:Temperature-sensitive biologics in the Rhône-Alpes cluster require specialized cold-chain packaging with serialization compliance.
- Electronics:Anti-static films and molded fiber cushions serve high-value component distribution from Grenoble semiconductor facilities.
- Chemicals:UN-certified drums and intermediate bulk containers move through Le Havre port infrastructure for export markets.
- Agriculture:Seed and fertilizer packaging in the Beauce region demands UV-stabilized woven polypropylene with extended field durability.
Food & Beverage commands absolute volume; Pharmaceuticals delivers the steepest expansion trajectory.
Packaging Type:
Format selection tracks filling line compatibility and retail shelf-space economics across French distribution channels.
- Bags & Pouches:Flexible formats capture disproportionate growth from convenience food and fresh produce segments. Stand-up pouches with spouts displace rigid containers in dairy applications.
- Boxes & Cartons:Corrugated and folding carton demand concentrates around Paris distribution centers for e-commerce fulfillment density.
- Bottles & Jars:Glass retains dominance in wine and spirits despite PET lightweighting advances; pharmaceutical liquids require borosilicate for chemical stability.
- Trays & Containers:Modified atmosphere packaging for meat and poultry operates from Brittany processing clusters.
- Tubes:Laminate and extruded plastic formats serve cosmetics and pharmaceuticals with precise dosing requirements.
- Wraps:Stretch and shrink films secure palletized loads for export through Marseille-Fos port logistics.
Boxes & Cartons generate the highest unit volumes; Bags & Pouches are climbing the fastest.
Distribution Channel:
Channel selection determines order fragmentation, lead time compression, and technical service intensity for French converters.
- Retail Chains:Centralized procurement by cooperative buying groups in the Île-de-France region standardizes specifications across private-label portfolios.
- Online Stores:Direct-to-consumer fulfillment demands damage-resistant corrugated with optimized dimensional weight for last-mile efficiency.
- Wholesale Distributors:Regional packaging merchants in Lyon and Nantes stock standard formats for small and mid-sized processors.
- Direct Sales:Large agricultural export consortia negotiate multi-year supply agreements bypassing intermediary margins.
- Specialty Stores:Premium wine merchants specify custom glass and closure combinations for limited-production allocations.
Retail Chains concentrate procurement volume; Online Stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's packaging demand concentrates around tax-advantaged industrial zones in the Île-de-France and Auvergne-Rhône-Alpes regions, where accelerated depreciation schemes for recycling infrastructure have anchored converter investment.
Île-de-France
E-commerce fulfillment density around Paris drives concentrated demand for corrugated and flexible formats. The EU Green Deal packaging mandates are pulling investment into fiber-based solutions ahead of delegated acts taking effect. Retailer sustainability scorecards in the Paris basin now require mono-material designs for lower eco-modulation levies under France's circular economy law.
Auvergne-Rhône-Alpes
Pharmaceutical and personal care manufacturers in Lyon and Grenoble are shifting toward bio-based alternatives to preempt REACH compliance friction. ANSM serialization requirements are opening specialized contract packaging capacity for temperature-sensitive biologics. The Rhône-Alpes pharma cluster is consolidating temperature-controlled packaging expertise around Saint-Étienne and Lyon-Saint-Exupéry logistics corridors.
Provence-Alpes-Côte d'Azur
NFC-enabled labels combined with blockchain traceability are penetrating high-value agricultural exports from Provence. DGCCRF enforcement campaigns for food-contact material safety are elevating third-party testing costs for imported polymer films. Marseille-Fos port logistics are driving stretch and shrink film demand for palletized export loads.
Hauts-de-France
Industrial paper grades serving northern France's manufacturing belt sustain scale advantages for containerboard producers. Recycled fiber cost volatility with European collection rates is compressing converter margins across the Lille metropolitan industrial zone. The region's proximity to Belgian and Dutch recycling infrastructure is reshaping cross-border fiber sourcing patterns.
Nouvelle-Aquitaine
Wine and spirits exporters from Bordeaux face dual compliance burdens from both EU REACH and destination-country registration requirements for Asia-Pacific markets. Glass retains dominance in premium wine formats despite lightweighting advances in PET and aluminum. The region's cooperatives are standardizing pouch formats across product lines to achieve volume-scale pricing.
France Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across France's packaging value chain. The market structure tilts toward consolidation among integrated paperboard producers while remaining fragmented in specialized flexible and rigid formats. Three archetypes dominate: pan-European containerboard networks, recycled fiber-based specialists, and diversified global packaging conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters respond to tightening recyclability definitions.
Within the pan-European network tier, Smurfit Kappa Group PLC and Smurfit WestRock exemplify scale-driven positions anchored to agricultural export corridors. DS Smith PLC occupies a recycled fiber specialization niche, while International Paper Company represents the diversified conglomerate archetype with industrial paper grade exposure. These three entities collectively illustrate the competitive tension between geographic coverage depth and substrate-specific expertise that defines converter positioning in France.
| Leading Market Players |
|---|
| International Paper Company |
| DS Smith PLC |
| Tetra Pak International SA |
| Smurfit Kappa Group PLC |
| AR Packaging Group AB |
| Smurfit WestRock |
| Mondi plc |
| Ball Corporation |
| Amcor plc |
| Others |
Supply & Pricing Matrix
FSC-certified mono-material paperboard commands 15-25% premiums over standard recycled grades in the Île-de-France corridor, with that certification ladder driving parallel supply chain bifurcation between integrated mill-converter partnerships and spot-market traders lacking chain-of-custody documentation. DGCCRF enforcement intensity and retailer eco-modulation scorecards simultaneously compress margins at the commodity tier while rewarding upstream integration into approved substrate networks.
Pricing Analysis
Short lead-time premiums of 8-12% apply to corrugated orders fulfilled within 72 hours for Paris-based e-commerce distribution centers, while spot inventory of standard containerboard trades at discounts to contract benchmarks. Three-tier pricing structure across premium certified, standard compliant, and economy non-compliant levels reflects FSC chain-of-custody, REACH additive clearance, and ANSM serialization readiness. Cost compression in the economy tier is intensifying because Asian export demand for European recovered fiber is elevating OCC input costs. Small agricultural cooperatives in Nouvelle-Aquitaine exhibit highest price sensitivity, whereas Rhône-Alpes pharmaceutical contract packers prioritize compliance certification over unit cost.
Supply Chain Analysis
Freight costs from Nordic pulp mills and Iberian containerboard plants into French converting facilities represent 8-14% of delivered material costs, with Rhône-Alpes and Hauts-de-France processors most exposed to cross-border trucking rates. Supply concentrates in Sweden, Finland, and Portugal for virgin fiber; Germany, Belgium, and the Netherlands for recovered paper collection and reprocessing. Raw material dependencies span OCC collections, softwood pulp, and bio-based barrier coatings. Single-source vulnerability sits with specialized cold-chain packaging films for pharmaceutical serialization. Distribution runs through regional merchant networks in Lyon and Nantes, with direct mill relationships displacing intermediaries among large retail cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's packaging market is consolidating around compliance-capable integrated producers, with DGCCRF enforcement and EU Packaging Waste Regulation recalibration forcing sub-scale converters toward exit or acquisition.
For Market Incumbents: Anticipate margin compression from bio-based substrate mandates by securing backward integration into barrier coating technology or captive pulp supply. Defensive positioning requires Rhône-Alpes pharmaceutical serialization capacity expansion and Île-de-France e-commerce fulfillment infrastructure to preempt DS Smith and Smurfit Kappa network extensions. Threat substitution from industrial compostable polymers demands R&D partnerships with Lyon-based municipal processing operators. For New Entrants and Emerging Players: Agricultural export consortia in Provence-Alpes-Côte d'Azur represent the most penetrable channel, with NFC-enabled traceability packaging for high-value lavender and olive oil exports offering white-space entry. Smart packaging convergence with blockchain authentication bypasses incumbent scale advantages in commodity corrugated. Go-to-market execution should anchor to Marseille-Fos port logistics relationships for palletized export load consolidation. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier flexible packaging specialists possessing in-house DGCCRF migration testing capability, given ANSM serialization mandate expansion into temperature-sensitive biologics. Long-term viability over the next decade hinges on converter positioning ahead of delegated acts recalibrating extended producer responsibility fee structures. Acquisition target archetype: Rhône-Alpes contract packers with cold-chain certification and established pharmaceutical relationships. Signal to watch: EN 13432 industrial compostability validation backlog duration as indicator of biodegradable packaging capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating Technology | Captures margin from water-based paperboard specifications mandated by Île-de-France retailers. |
| Rhône-Alpes Pharmaceutical Serialization Capacity Expansion | Addresses ANSM compliance requirements for temperature-sensitive biologics in Lyon-Saint-Étienne corridor. |
| NFC-Blockchain Traceability Partnership | Penetrates Provence agricultural export premium segment with authentication-enabled smart labels. |
| Industrial Composting Infrastructure Alliance | Secures feedstock access as Lyon and Nantes municipal processing capacity scales. |
| Direct Mill Relationship with Retail Cooperatives | Displaces spot-market purchasing through multi-year corrugated supply agreements. |
Research Methodology
Multi-period observation of DGCCRF enforcement campaign intensity, ECHA REACH restriction list updates, and retailer sustainability scorecard revisions anchored the trend analysis, supplemented by interviews with containerboard procurement directors at Paris-based e-commerce fulfillment centers, pharmaceutical packaging engineers in Lyon, and corrugated plant managers in Hauts-de-France. Secondary validation drew from EU Packaging and Packaging Waste Regulation delegated act drafts, French Environment Agency circular economy implementation reports, and FSC chain-of-custody certification databases. Bottom-up volume estimates from converting capacity utilization rates triangulated against top-down demand projections from food and beverage export trade flows.
Segment-weighting across material type, end-use industry, packaging format, and distribution channel informed the analytical framework over the projection horizon. Modeled dimensions included paperboard grade certification tier, pharmaceutical temperature-control requirements, e-commerce dimensional weight optimization, and regional industrial cluster concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects between rigid and flexible formats. Industry-specific forecast inputs comprised recovered fiber collection rate trajectories and industrial composting capacity buildout timelines around Lyon and Nantes.
Caveats apply where DGCCRF enforcement intensity, EU delegated act timing, or Asian export demand for European OCC could materially shift the outlook. Forecasts reflect assumptions regarding regulatory implementation pace and substrate substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
VCI Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Cold Chain Packaging Materials Market
Packaging Materials
Global Food Processing Seals Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
3D Printed Packaging Market