
 Global Adherence Packaging Market | 2026-2036
Global Adherence Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adherence Packaging Market Analysis
Pharmacy automation technician expertise is rotating toward smart packaging integration across developed markets. Cardinal Health Inc leverages its central-fill infrastructure to dominate institutional pharmacy adherence programs. Omnicell Inc anchors its position through robotic dispensing systems that synchronize with blister and strip pack formats. Becton, Dickinson and Company specializes in hospital-connected adherence workflows that reduce readmission risk.
Adherence packaging refers to unit-dose or multi-dose pharmaceutical containers engineered with calendarized cavities, child-resistant barriers, and moisture-stable barrier films to ensure timed, verified medication consumption. Blister packs lead volume due to their compatibility with high-speed thermoforming and established pharmacy automation, while smart packaging segments embed NFC tags and printed electronics for real-time compliance monitoring. Strip packs compete in long-term care facilities where flexible form factors accommodate complex polypharmacy regimens.
FDA serialization mandates under the Drug Supply Chain Security Act reshape packaging investment priorities in the United States, while EMA's Medical Device Regulation and EU F-Gas standards influence barrier film specifications across Europe. The analysis indicates stakeholders must evaluate whether smart packaging premiums justify pharmacy workflow reconfiguration before regulatory deadlines harden.
Market Dynamics
Central-fill pharmacy automation is compressing packaging procurement timelines as chains consolidate dispensing volume into regional hubs, forcing adherence packagers to reconfigure production lines for high-volume, serialized output.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates in the United States compel pharmacies and packagers to invest in track-and-trace infrastructure, expanding demand for compliance-ready blister and strip formats.
- Polypharmacy regimens in long-term care:Aging populations across Germany, Japan, and the United States drive calendarized multi-dose packaging for complex medication schedules in nursing facilities.
- Child-resistant barrier films:Advanced thermoformable laminates with push-through and peel-back mechanisms are penetrating pediatric and psychiatric medication segments where safety compliance is non-negotiable.
Market Restraints
- Aluminum and polymer input volatility:Cold-form foil and high-barrier film costs fluctuate with energy and petrochemical feedstock prices, squeezing converter margins on fixed-price pharmacy contracts.
- Equipment supplier concentration:High-speed thermoforming and robotic cartoning systems rely on a narrow base of German and Italian machinery builders, creating capex bottlenecks for mid-tier packagers.
- Smart packaging cost premiums:NFC-enabled blisters and printed electronics remain three to five times standard packaging costs, limiting pharmacy reimbursement justification outside pilot programs.
Strategic Opportunities
- India's pharmacy retail modernization:Organized chains in Mumbai, Delhi, and Bangalore are adopting central-fill models, creating first-mover advantage for adherence packagers with scalable serialization.
- EMA Medical Device Regulation convergence:Combination product classifications for drug-device adherence systems open reimbursement pathways in Germany, France, and the Netherlands for smart packaging with dosing verification.
- Home delivery channel expansion:Direct-to-patient pharmacy logistics in the United States and United Kingdom favor strip packs over bottles for shipping efficiency and dose accountability.
Industry Challenges
- Automation technician scarcity:Pharmacy central-fill facilities face recruitment gaps for technicians capable of integrating smart packaging serialization with existing robotic dispensing workflows.
- Legacy pharmacy management system integration:ERP and patient management platforms in independent and small-chain pharmacies require costly middleware development to support real-time adherence data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adherence Packaging Market |
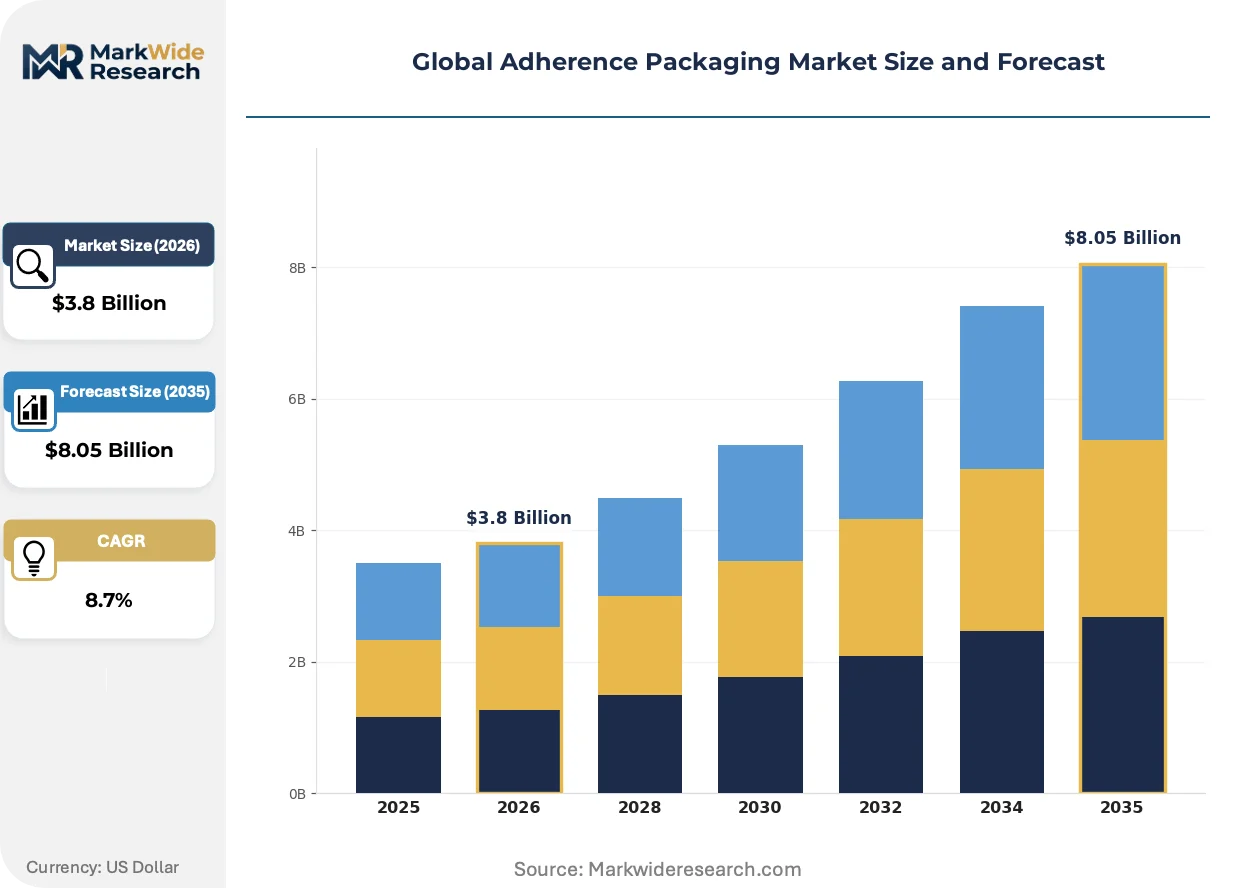
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Strip Packs, Bottles, Sachets End User: Pharmacies, Hospitals, Long-Term Care Facilities, Home Care Technology: Smart Packaging, Conventional Packaging, Eco-friendly Packaging, Tamper-evident Packaging Application: Chronic Diseases, Antibiotic Therapy, Oncology, Nutritional Supplements |
| Companies Covered | Westrock Company, Cardinal Health Inc, Omnicell Inc, Becton, Dickinson and Company, Manrex Limited, Parata Systems LLC, Jones Healthcare Group, Keystone Folding Box Co, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adherence Packaging Market Emerging Trajectories
Printed electronics and connected packaging layers are embedding compliance verification directly into pharmaceutical supply chains, transforming adherence packaging from passive containment to active therapeutic intervention.
Thermoformable barrier laminates with integrated desiccant layers are supplanting separate sachet-based moisture protection in oral solid dose packaging. European pharmacy chains and North American central-fill operators are adopting these formats at accelerating rates for high-volume generics. This consolidation is compressing supplier tiers as converters with in-house lamination capabilities capture share from assembly-only packagers.
REACH and EU F-Gas Regulation amendments are restricting fluorinated barrier films and certain adhesive chemistries in pharmaceutical packaging destined for European markets. Converters are reformulating cold-form foils and lidding materials to maintain moisture and oxygen barriers under tightened substance restrictions. German and French pharmacy suppliers are prioritizing compliant material certifications to preempt supply disruptions ahead of 2025-2027 enforcement windows.
Hospital and health system procurement is consolidating adherence packaging specifications under outcome-based pharmacy contracts that tie supplier payments to readmission reduction metrics. United States integrated delivery networks and United Kingdom NHS trusts are displacing transactional purchasing with multi-year performance agreements. This restructuring concentrates volume among packagers with clinical evidence packages and health economics capabilities.
Global Adherence Packaging Market Segmentation
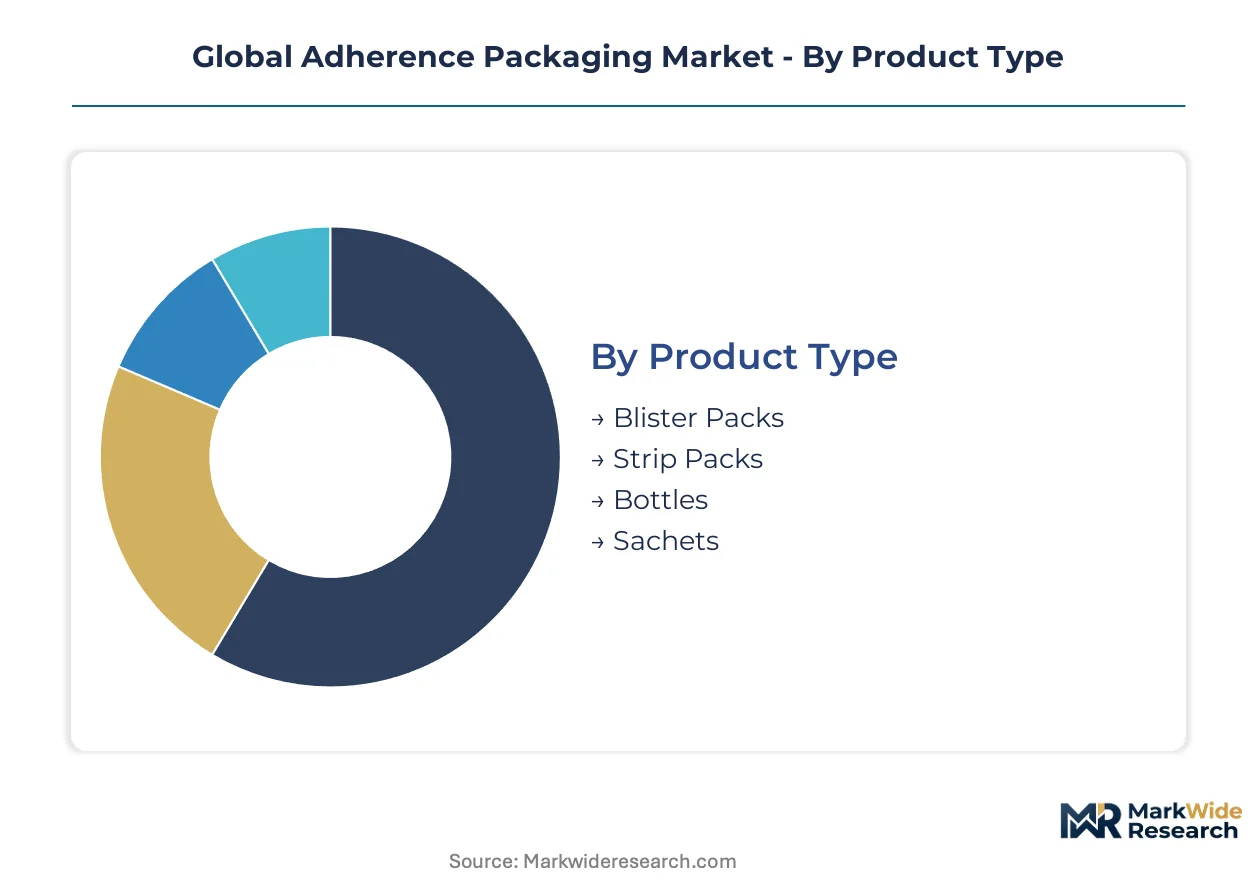
Segmentation in adherence packaging reveals how pharmacy automation preferences, regulatory serialization mandates, and patient compliance requirements fragment demand across incompatible technical specifications. Each dimension carries distinct substitution pressures that reshape procurement priorities for central-fill operators and institutional buyers.
Product Type:
Strip packs face the most acute substitution threat as thermoformable barrier laminates with integrated desiccant layers displace separate sachet-based moisture protection in oral solid dose formats.
- Blister Packs:Thermoformed cavities with cold-form foil or high-barrier film lidding dominate high-speed pharmacy automation. Demand concentrates in Germany and the United States where central-fill chains require serialized, calendarized formats compatible with robotic dispensing systems.
- Strip Packs:Flexible multi-dose pouches accommodate complex polypharmacy regimens in long-term care settings. Japan's aging nursing facility population and United Kingdom NHS trusts drive preference for strip formats that reduce medication administration errors in high-patient-ratio environments.
- Bottles:Traditional container formats persist in retail pharmacy for acute therapies and generic substitution programs where dose accountability is less critical.
- Sachets:Single-unit powder or liquid sachets serve nutritional supplements and pediatric antibiotic suspensions where precise fractional dosing is required.
Blister packs anchor the volume base while strip packs gain share at the steepest rate as long-term care polypharmacy regimens expand across developed markets.
End User:
Cost tier differentiation separates institutional procurement with outcome-based contracts from retail pharmacy transactional purchasing where reimbursement constraints limit packaging premiums.
- Pharmacies:Chain and independent dispensers represent the primary volume channel, with North American central-fill hubs and European pharmacy-led adherence programs driving specification consolidation. FDA Drug Supply Chain Security Act serialization requirements compel investment in track-and-trace infrastructure.
- Hospitals:Integrated delivery networks in the United States and United Kingdom NHS trusts are displacing transactional purchasing with multi-year performance agreements tying supplier payments to readmission reduction metrics.
- Long-Term Care Facilities:Nursing homes and assisted living operators prioritize calendarized multi-dose packaging to reduce medication administration burden for polypharmacy patients.
- Home Care:Direct-to-patient pharmacy logistics favor strip packs and smart packaging for dose accountability in remote medication management programs.
Pharmacies retain the largest procurement volume while hospitals are expanding most quickly through outcome-based contract restructuring.
Technology:
Application-driven segmentation separates passive containment formats from active therapeutic intervention systems where dosing verification justifies premium pricing.
- Smart Packaging:NFC-enabled blisters and printed electronics embed real-time compliance monitoring directly into pharmaceutical supply chains. EMA Medical Device Regulation convergence in Germany, France, and the Netherlands opens reimbursement pathways for combination drug-device adherence systems with dosing verification.
- Conventional Packaging:Standard blister and strip formats without electronic functionality serve cost-constrained pharmacy segments where reimbursement does not justify smart packaging premiums.
- Eco-friendly Packaging:Bio-based barrier films and recyclable thermoformable laminates respond to EU Green Deal requirements and REACH substance restrictions affecting fluorinated films.
- Tamper-evident Packaging:Push-through and peel-back child-resistant mechanisms penetrate pediatric and psychiatric medication segments where safety compliance is non-negotiable.
Conventional packaging dominates current volume while smart packaging climbs the fastest as pharmacy workflow reconfiguration precedes hardening regulatory deadlines.
Application:
Customer type segmentation separates chronic maintenance therapies with predictable adherence packaging demand from acute treatment categories with variable duration requirements.
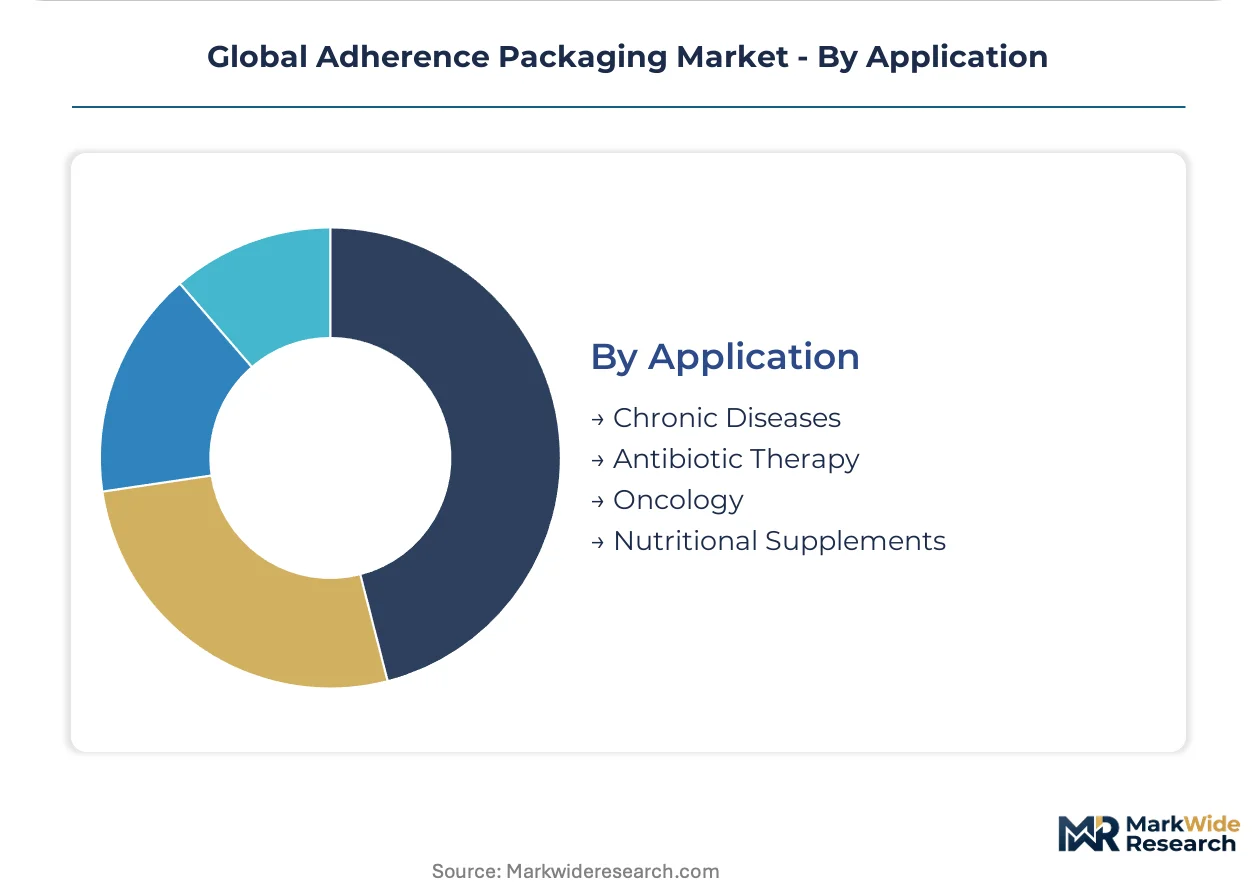
- Chronic Diseases:Cardiovascular, diabetes, and respiratory maintenance therapies require sustained multi-month adherence packaging with calendarized dosing schedules. Germany's statutory reimbursement support for pharmacy-led adherence programs concentrates demand for high-volume blister and strip formats.
- Antibiotic Therapy:Short-course treatments with strict completion requirements favor blister packs with day-labeled cavities to prevent premature discontinuation and resistance development.
- Oncology:Oral oncolytics with narrow therapeutic windows demand specialized barrier protection and in some cases smart packaging for dose verification in home administration settings.
- Nutritional Supplements:Vitamins and minerals compete on shelf differentiation with premium blister and bottle formats, though adherence features are less clinically mandated.
Chronic disease applications anchor the volume base while oncology gains share at the steepest rate as oral oncolytic portfolios expand across pharmaceutical pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes adherence packaging through pharmacy-led statutory reimbursement programs, while the United States channels demand through central-fill automation hubs and the United Kingdom prioritizes NHS outcome-based contracting. Japan and India represent divergent adoption curves—Japan through aged-care polypharmacy infrastructure, India through emerging organized retail pharmacy modernization.
United States
FDA Drug Supply Chain Security Act serialization mandates compel pharmacy chains to invest in track-and-trace capable blister and strip formats. Central-fill automation hubs in Illinois, Ohio, and Texas consolidate dispensing volume into regional facilities requiring high-speed serialized output. Cardinal Health Inc leverages its institutional infrastructure to dominate hospital-connected adherence workflows.
Germany
Statutory reimbursement support for pharmacy-led adherence programs concentrates demand for calendarized multi-dose packaging. EMA Medical Device Regulation convergence opens reimbursement pathways for combination drug-device systems with dosing verification. Baden-Württemberg and Bavaria host packaging converter clusters reformulating cold-form foils under tightened EU F-Gas substance restrictions.
United Kingdom
NHS trusts displace transactional purchasing with multi-year performance agreements tying supplier payments to readmission reduction metrics. Home delivery channel expansion favors strip packs over bottles for shipping efficiency and dose accountability. London and Southeast England anchor procurement consolidation under outcome-based pharmacy contracts.
Japan
Aging nursing facility populations drive preference for flexible strip formats reducing medication administration errors in high-patient-ratio environments. PMDA guidelines influence barrier film specifications for moisture-stable oral solid dose packaging. Kansai region converters supply calendarized multi-dose formats to long-term care operators.
India
Organized pharmacy chains in Mumbai, Delhi, and Bangalore adopt central-fill models creating first-mover advantage for adherence packagers with scalable serialization. CDSCO track-and-trace requirements for exported pharmaceuticals drive domestic packaging quality upgrades. Maharashtra and Karnataka host emerging converter capacity serving both domestic retail modernization and export compliance.
Global Adherence Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling central-fill infrastructure and hospital-connected workflows while mid-tier converters compete on barrier film formulation and serialization compliance. The market structures around three archetypes: automation-integrated distributors, high-barrier film specialists, and robotic dispensing system manufacturers. Competitive moves concentrate on strategic partnerships between packagers and pharmacy automation vendors, plus capacity expansion into India and Southeast Asia to capture retail modernization cycles.
Among North American automation-integrated distributors, Cardinal Health Inc and Omnicell Inc exemplify the infrastructure-control archetype, while Becton, Dickinson and Company represents the hospital-workflow specialization tier. These three occupy positions where pharmacy central-fill consolidation and outcome-based contracting create defensive moats around installed automation bases.
| Leading Market Players |
|---|
| Westrock Company |
| Cardinal Health Inc |
| Omnicell Inc |
| Becton, Dickinson and Company |
| Manrex Limited |
| Parata Systems LLC |
| Jones Healthcare Group |
| Keystone Folding Box Co |
| Amcor plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between North American pharmacy chains and high-barrier film converters lock in supply access while stabilizing unit costs across multi-year central-fill expansion cycles. These contracts insulate procurement teams from aluminum and polymer feedstock volatility while committing volume to German and Italian machinery lines.
Pricing Analysis
Project-based pricing dominates serialized blister and strip pack procurement, with cost differentiation driven by barrier film certification grade and customization level for robotic dispensing compatibility. Three-tier pricing structure across premium, standard, and economy levels separates smart packaging with NFC integration from conventional calendarized formats and basic generic blister packs. Pricing pressure stems from fixed-price pharmacy contracts squeezing converter margins during energy cost spikes. Retail independents exhibit highest price sensitivity, while hospital IDNs accept premiums for outcome-based contract alignment.
Supply Chain Analysis
Inventory buffers for cold-form foil and desiccant-integrated laminates stretch lead times when German machinery builders face order backlogs. Manufacturing concentrates in Germany, Italy, and the United States, with raw material sourcing drawing from petrochemical feedstocks in the Middle East and aluminum smelters in China. Single-source vulnerability runs through high-speed thermoforming equipment suppliers concentrated in Baden-Württemberg and Lombardy. Distribution runs through regional central-fill hubs and long-term care distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adherence packaging is fundamentally a service-attach opportunity where pharmacy workflow integration and compliance monitoring subscriptions expand faster than commodity blister and strip hardware sales. Recurring revenue from serialization software and real-time adherence data platforms outpaces unit-dose packaging volume growth.
For Market Incumbents: Shield installed base positions through backward integration into barrier film lamination capabilities, capturing margin from converters squeezed by fixed-price pharmacy contracts. Prioritize certification investment for EU F-Gas and REACH compliance ahead of enforcement windows to preempt supply disruptions that could displace competitors. For New Entrants and Emerging Players: Mid-tier pharmacy automation integration services represent a service-layer gap where incumbents under-serve independent chains lacking ERP middleware development resources. Target India's organized retail pharmacy modernization in Mumbai and Bangalore with scalable serialization platforms designed for CDSCO export compliance. Lead with pilot-to-scale subscription models rather than capital equipment sales. For Investors and Strategic Acquirers: High-barrier film specialists with in-house desiccant lamination capabilities and German converter certifications offer the strongest acquisition target archetype for portfolio consolidation plays. Long-term viability hinges on regulatory compliance moats deepening through EMA Medical Device Regulation convergence. Watch for FDA serialization deadline acceleration as inflection indicator for smart packaging premium justification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Lamination | Captures converter margin and secures supply continuity for pharmacy chain contracts. |
| Smart Packaging Platform Integration | Enables real-time compliance monitoring subscriptions tied to EMA reimbursement pathways. |
| Central-Fill Hub Partnership Expansion | Locks in volume commitments with Cardinal Health and Omnicell infrastructure deployments. |
| EU Regulatory Certification Program | Preempts supply disruption risk from REACH and F-Gas substance restriction enforcement. |
| India Retail Modernization Joint Venture | Positions for CDSCO-compliant serialization demand from Mumbai and Bangalore pharmacy chains. |
Methodological Framework
A standing panel of pharmacy automation technicians, central-fill operations directors, barrier film procurement managers, and hospital pharmacy GPO contract specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, EMA Medical Device Regulation technical specifications, EU F-Gas and REACH amendment filings, and pharmacy chain 10-K disclosures. Bottom-up volume modeling triangulated against top-down market sizing from equipment installation databases and converter capacity announcements.
Consistency checks validated volume and value outputs against external benchmarks including high-speed thermoforming machinery order backlogs and central-fill hub expansion announcements across the analysis window. Segmentation modeling spanned product type, end user, technology tier, and application with regional regulatory cluster as an additional dimension. CAGRs were derived from year-over-year growth rate analysis applied to base-year sizing, with forecast inputs including pharmacy automation adoption curves and polypharmacy prevalence projections in aged-care populations.
Underlying assumptions cover sustained FDA serialization enforcement, stable German machinery builder output capacity, and continued statutory reimbursement support for pharmacy-led adherence programs in Germany, with deviation risk concentrated in aluminum and polymer feedstock price volatility and automation technician recruitment gaps. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Carded Packaging Market
Packaging Materials
VCI Shrink Films Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Global Strapping Market
Packaging Materials
Packaging Laminates Market