
 Lipids Active Pharmaceutical Ingredient Market | 2026-2036
Lipids Active Pharmaceutical Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Lipids Active Pharmaceutical Ingredient Market Insights
Current Good Manufacturing Practice certification is rotating as the decisive gatekeeper for lipid API suppliers seeking entry into commercial mRNA supply chains. Merck KGaA leverages its integrated lipid manufacturing network across Germany and Switzerland to sustain high-purity phospholipid output for gene therapy applications. CordenPharma International anchors European supply through specialized cGMP facilities that produce synthetic lipids for complex drug formulations. Avanti Polar Lipids differentiates via research-grade lipid portfolios that transition into clinical-scale production.
Lipids active pharmaceutical ingredient denotes biologically derived or synthetically produced lipid molecules—phospholipids, fatty acids, glycerides, and sphingolipids—engineered to serve as functional excipients, drug carriers, or therapeutic moieties, typically characterized by defined acyl chain lengths, saturation profiles, and transition temperatures that determine membrane fusion efficiency and biodistribution. These molecules enable encapsulation of hydrophilic and hydrophobic APIs, particularly in liposomal and lipid nanoparticle architectures for nucleic acid delivery. Phospholipids dominate current revenue pools due to their indispensability in liposome and LNP formulations, while sphingolipids represent the fastest-expanding category driven by oncology and neurodegenerative research pipelines. The cardiovascular application segment retains mature volume, whereas anticancer applications command premium pricing through targeted delivery mechanisms.
The FDA enforces lipid impurity profiling and endotoxin thresholds that directly determine which suppliers qualify for commercial drug master files, while EMA's updated guidelines on nanomedicine characterization add layered documentation requirements for European market access. ISO 10993 biocompatibility standards and ICH Q3D elemental impurity guidelines further constrain raw material sourcing and finished lipid specifications. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on lipid nanoparticle critical quality attributes to preempt supply chain disruptions and qualification delays.
Market Dynamics
The FDA's tightened lipid nanoparticle characterization guidance is compressing supplier qualification timelines while mRNA therapeutic developers scramble for cGMP-certified phospholipid sources. This regulatory pressure is concentrating purchasing power among CDMOs with validated commercial drug master files.
Growth Catalysts
- Gene therapy pipeline expansion:Nucleic acid delivery platforms require ionizable lipids with defined pKa profiles. Clinical-stage mRNA vaccines for oncology indications are pulling specialized phospholipid volumes.
- EMA nanomedicine guidance:The European Medicines Agency's updated characterization requirements are standardizing lipid critical quality attributes across member states. Suppliers meeting these benchmarks gain automatic access to 27 national markets.
- Synthetic lipid chemistry advances:Solid-phase synthesis methods now enable scalable production of asymmetric phospholipids with precise acyl chain asymmetry. These molecules improve liposomal encapsulation efficiency for hydrophobic APIs.
Market Restraints
- Raw material concentration:Purified egg yolk phospholipid supply concentrates in Chinese and Argentinian agricultural processing clusters. Avian influenza outbreaks in these regions trigger immediate input cost volatility.
- Specialized equipment scarcity:Large-scale high-pressure homogenizers for liposome manufacturing face 18-month lead times from German and Japanese vendors. This capex bottleneck limits rapid capacity expansion.
- Analytical method standardization gaps:Transition temperature determination and particle size distribution protocols vary between FDA and EMA expectations. Dual-qualification testing adds 20-30% to release costs.
Strategic Opportunities
- India CDMO buildout:The country's Production Linked Incentive scheme for pharmaceuticals subsidizes greenfield lipid manufacturing facilities. CDSCO fast-track approvals for lipid-based drug products create first-mover advantages.
- Neurodegenerative sphingolipid applications:Blood-brain barrier penetration research is opening therapeutic niches for ceramide and ganglioside derivatives. These molecules command 3-4x phospholipid pricing premiums.
- Continuous manufacturing adoption:Microfluidic mixing technologies are displacing batch-based LNP production. Early adopters achieve 40% yield improvements and real-time process analytical control.
Industry Challenges
- Lipid analytical chemistry talent scarcity:Mass spectrometry specialists with lipidomics expertise command premium compensation. Universities produce fewer than 200 qualified graduates annually across North America and Europe.
- cGMP facility retrofit timelines:Converting research-scale lipid suites to commercial manufacturing requires 24-36 months. HVAC validation and cleaning verification protocols consume 40% of project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipids Active Pharmaceutical Ingredient Market |
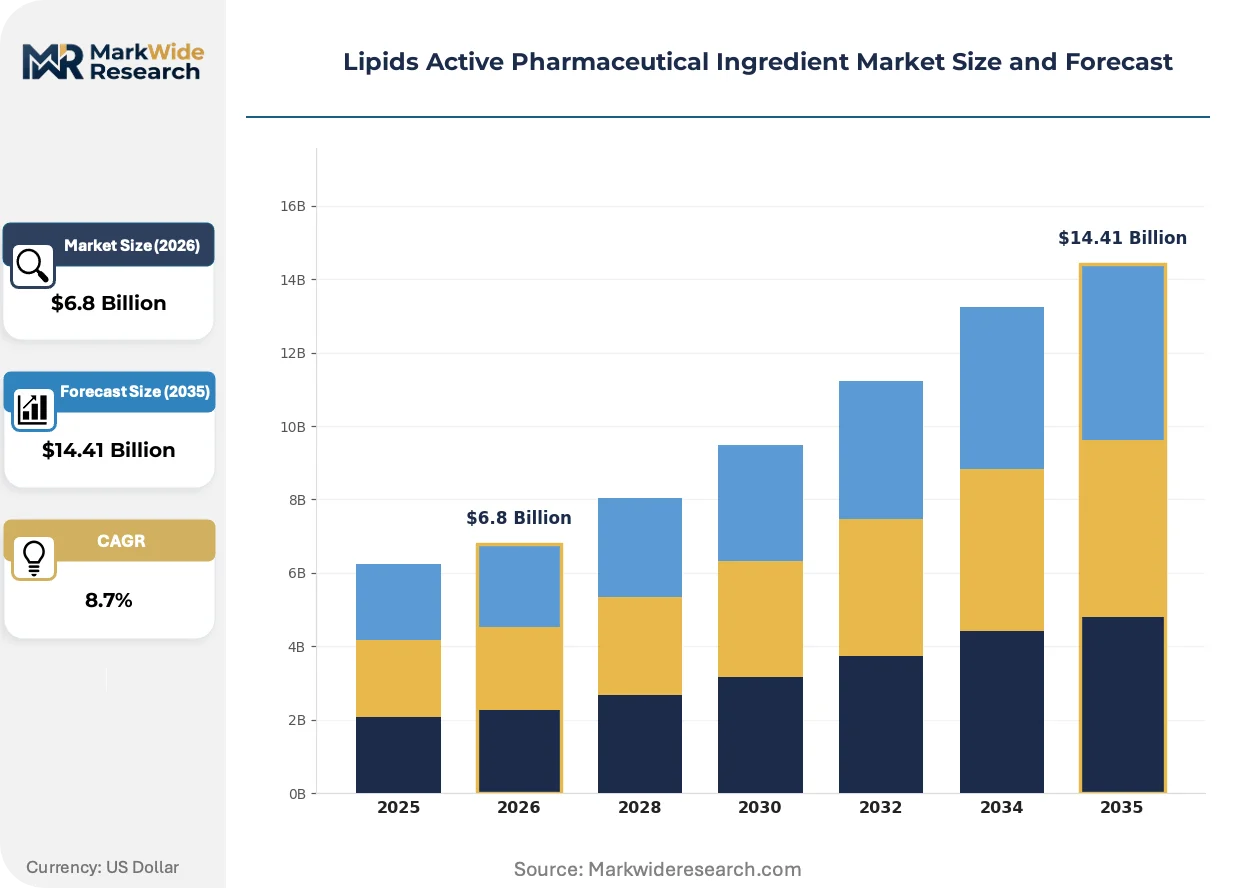
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Fatty Acids, Glycerides, Sphingolipids Application: Cardiovascular, Anticancer, Anti-inflammatory, Nutraceuticals End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions Form: Liquid, Solid, Liposome, Nanoparticles |
| Companies Covered | Merck KGaA, CordenPharma International, Avanti Polar Lipids, Sancilio & Company, Cerbios-Pharma SA, VAV Life Sciences, Cayman Chemical, Lipoid, NOF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipids Active Pharmaceutical Ingredient Market Trends and Innovations
Microfluidic manufacturing platforms and synthetic biology-derived lipids are compressing traditional batch production economics. These shifts are reshaping how suppliers compete on specification breadth versus scale efficiency.
Microfluidic mixing cartridges for lipid nanoparticle assembly are miniaturizing production footprints while maintaining tight particle size distributions. Gene therapy CDMOs in Massachusetts and North Carolina are adopting these systems for Phase III material supply. The technology is miniaturizing capital requirements for commercial-scale LNP manufacturing, enabling mid-tier players to challenge established batch-reactor operators.
REACH regulation updates on nanomaterial registration are extending documentation timelines for lipid-based drug products entering European commerce. Suppliers must now submit enhanced stability data and biodegradation profiles for novel synthetic lipids. Small molecule divisions within large pharmaceutical firms are most affected, accelerating partnerships with specialized lipid houses possessing existing registration dossiers.
Biotech procurement teams are consolidating supplier panels from 8-12 vendors to 3-4 strategic partners with full cGMP portfolios. This concentration is displacing spot-market purchasing for clinical-grade phospholipids. The shift is most visible among Boston and San Francisco-based mRNA platform companies seeking single-source accountability for commercial launches.
Lipids Active Pharmaceutical Ingredient Market Segmentation
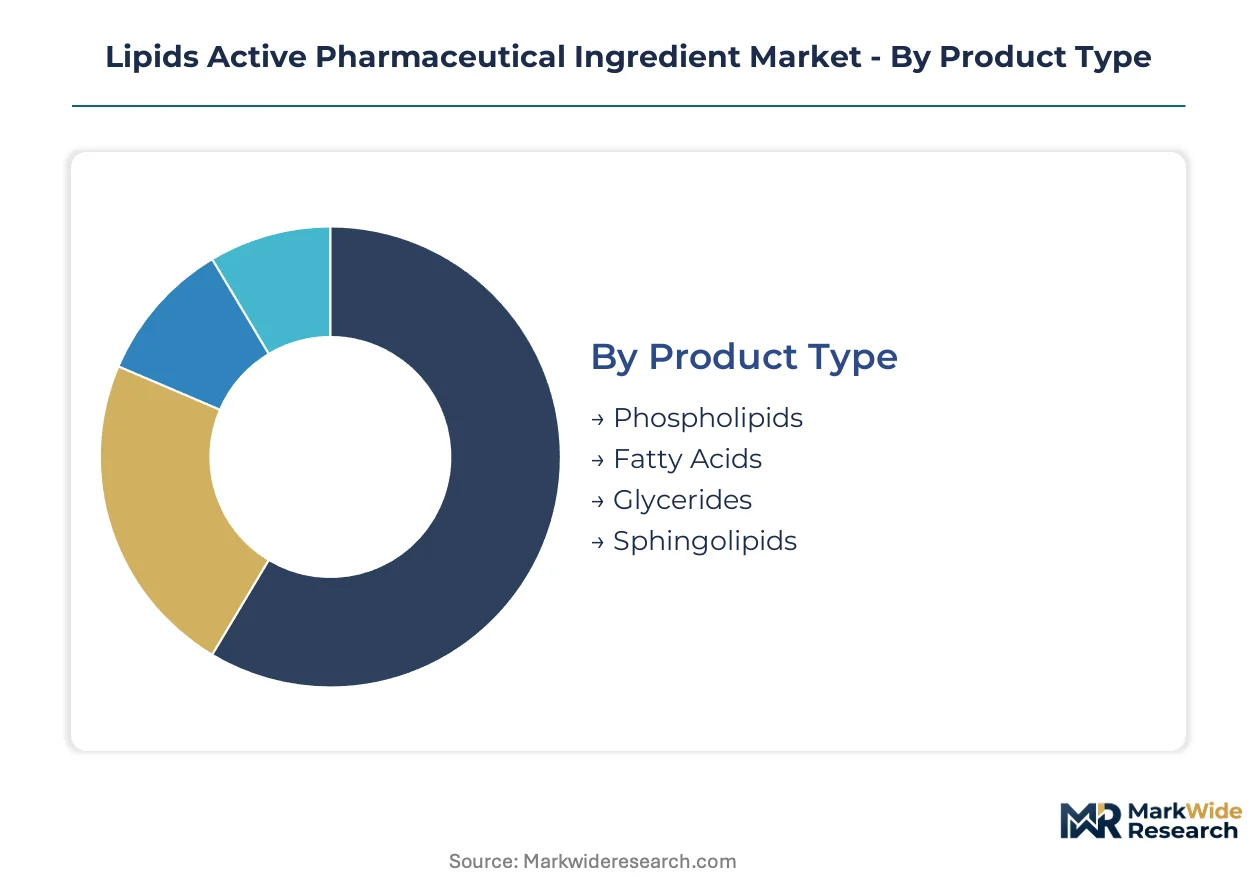
Lipid API purchasing patterns diverge sharply across product chemistries and end-use specifications. Regulatory qualification requirements for each segment create tiered entry barriers that reshape supplier competitive dynamics.
Product Type:
FDA and EMA documentation thresholds vary by molecular complexity, with ionizable lipids facing the steepest characterization demands for commercial drug master files.
- Phospholipids:Phosphatidylcholine and phosphatidylethanolamine variants with defined acyl chain saturation profiles serve as structural backbones for liposomal and LNP formulations. Demand concentrates among Massachusetts and North Carolina gene therapy CDMOs scaling Phase III material supply, constrained by egg yolk raw material sourcing volatility from Chinese and Argentinian agricultural processors.
- Sphingolipids:Ceramide and ganglioside derivatives engineered for blood-brain barrier penetration exhibit precise stereochemistry requirements. Neurodegenerative research pipelines in Basel and Boston are pulling specialized volumes, with these molecules commanding premium pricing multiples over standard phospholipid grades.
- Fatty Acids:Saturated and unsaturated chains with defined carbon lengths function as solubilizing agents and membrane modulators in oral formulations.
- Glycerides:Mono-, di-, and triglyceride mixtures provide sustained-release matrices for hydrophobic API delivery in lipid-based formulations.
Phospholipids handle the majority of throughput; sphingolipids are the fastest mover on share.
Application:
Pricing stratification across therapeutic areas reflects the technical sophistication of delivery mechanisms and the clinical value of targeted biodistribution.
- Anticancer:Liposomal doxorubicin and paclitaxel formulations leverage PEGylated phospholipid stealth layers to achieve tumor accumulation via enhanced permeability and retention effects. Premium pricing persists in this segment due to the clinical imperative for reduced cardiotoxicity and improved therapeutic indices in oncology protocols.
- Cardiovascular:Omega-3 fatty acid ethyl esters and liposomal coenzyme Q10 address dyslipidemia and heart failure indications through established pharmacological pathways. Mature volume demand characterizes this application, with pricing pressure from commoditized raw material supply chains.
- Anti-inflammatory:Liposomal corticosteroid and NSAID delivery systems target localized inflammation with reduced systemic exposure profiles.
- Nutraceuticals:Phospholipid-bound omega-3 complexes and liposomal vitamin formulations serve preventive health applications with less stringent regulatory oversight.
Anticancer commands the highest value per kilogram; nutraceuticals absorb the greatest absolute tonnage.
End User:
Procurement sophistication varies by organizational scale, with commercial-stage developers imposing cGMP qualification requirements that filter supplier pools.
- Pharmaceutical Companies:Large-cap firms with integrated manufacturing capabilities source lipids for proprietary liposomal and LNP platforms, often requiring dedicated supply agreements with full analytical method transfer.
- Biotech Firms:Clinical-stage developers prioritize speed-to-qualification over unit cost, consolidating supplier panels to 3-4 strategic partners with validated commercial drug master files.
- Contract Manufacturers:CDMOs scale phospholipid production capacity to capture mRNA therapeutic outsourcing demand, with specialized facilities in Germany and Switzerland sustaining high-purity output.
- Research Institutions:Academic and government laboratories purchase research-grade lipid portfolios that transition into clinical-scale production through technology transfer partnerships.
Contract manufacturers are expanding capacity most aggressively; research institutions remain the price-sensitive volume base.
Form:
Physical state and delivery architecture determine manufacturing equipment requirements and stability testing protocols.
- Liposome:Multilamellar and unilamellar vesicle systems with defined hydrodynamic diameters enable encapsulation of both hydrophilic and hydrophobic APIs. Manufacturing depends on large-scale high-pressure homogenizers facing 18-month lead times from German and Japanese equipment vendors.
- Nanoparticles:Solid lipid nanoparticles and lipid-polymer hybrid systems provide controlled release kinetics for poorly soluble compounds. Microfluidic mixing technologies are displacing batch-based production, with early adopters achieving yield improvements and real-time process analytical control.
- Liquid:Bulk lipid solutions and dispersions serve as formulation intermediates requiring cold-chain logistics and oxidation protection.
- Solid:Powdered lipid excipients and API-lipid co-crystals offer extended shelf stability and simplified handling in solid dosage manufacturing.
Liposome formulations dominate current commercial throughput; nanoparticle architectures are climbing the fastest on development pipeline share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and updated nanomedicine guidelines from EMA are redirecting capital flows toward certified lipid manufacturing capacity. Specialized CDMOs in Germany and Switzerland maintain high-purity phospholipid output for gene therapy applications. Raw material sourcing volatility from Chinese and Argentinian agricultural processors continues to shape regional supply security strategies.
United States
FDA tightened lipid nanoparticle characterization guidance compresses supplier qualification timelines for commercial mRNA supply chains. Massachusetts and North Carolina gene therapy CDMOs scale Phase III material supply while consolidating supplier panels to strategic partners with validated drug master files. Biotech procurement teams in Boston and San Francisco now demand single-source accountability for commercial launches.
Germany
Merck KGaA leverages integrated lipid manufacturing networks across Germany and Switzerland to sustain high-purity phospholipid output. EMA nanomedicine characterization requirements standardize critical quality attributes across member states, granting compliant suppliers automatic access to 27 national markets. Specialized cGMP facilities in southern Germany produce synthetic lipids for complex drug formulations serving European commercial demand.
India
CDSCO fast-track approvals for lipid-based drug products create first-mover advantages for domestic manufacturers. The Production Linked Incentive scheme for pharmaceuticals subsidizes greenfield lipid manufacturing facilities in Maharashtra and Gujarat. Contract manufacturers in Hyderabad and Bangalore expand phospholipid production capacity to capture mRNA therapeutic outsourcing demand from Western sponsors.
Switzerland
Swissmedic enforces lipid impurity profiling thresholds that determine supplier qualification for commercial drug master files. Basel-based neurodegenerative research pipelines pull specialized sphingolipid volumes for blood-brain barrier penetration studies. CordenPharma International anchors European supply through specialized cGMP facilities producing synthetic lipids for complex formulations.
China
Purified egg yolk phospholipid supply concentrates in Chinese agricultural processing clusters, exposing the market to avian influenza outbreak volatility. NMPA documentation requirements for novel synthetic lipids extend registration timelines for lipid-based drug products entering domestic commerce. Contract manufacturers in Jiangsu and Zhejiang provinces retrofit research-scale lipid suites to meet international cGMP standards for export markets.
Lipids Active Pharmaceutical Ingredient Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale. The vendor base stratifies between integrated chemical conglomerates with multi-continent networks and focused lipid houses with research-to-commercial transition capabilities. Three archetypes dominate: diversified life science conglomerates leveraging cross-divisional synergies, pure-play lipid specialists with deep analytical chemistry expertise, and regional CDMOs capturing geographic proximity advantages. Competitive moves center on cGMP facility retrofit acceleration and strategic consolidation of supplier panels by biotech procurement teams.
Among diversified chemical conglomerates, Merck KGaA and NOF Corporation occupy positions anchored by integrated manufacturing networks spanning multiple jurisdictions. Pure-play specialists exemplified by Avanti Polar Lipids and Cayman Chemical sit within the research-grade-to-commercial-transition tier, while European CDMOs represented by CordenPharma International and Cerbios-Pharma SA anchor contract manufacturing capacity for complex formulations. Sancilio & Company and VAV Life Sciences represent mid-scale regional players building cGMP qualification depth to capture mRNA therapeutic outsourcing flows.
| Leading Market Players |
|---|
| Merck KGaA |
| CordenPharma International |
| Avanti Polar Lipids |
| Sancilio & Company |
| Cerbios-Pharma SA |
| VAV Life Sciences |
| Cayman Chemical |
| Lipoid |
| NOF Corporation |
| Others |
Pricing and Supply Chain Analysis
Phospholipid production scale economies in Germany and Switzerland establish floor pricing that smaller batch-reactor operators cannot match without cGMP certification depth. This concentration of validated manufacturing capacity creates asymmetric bargaining power where biotech procurement teams absorb 20-30% dual-qualification testing premiums for FDA and EMA alignment.
Pricing Analysis
Certification level creates the primary spread across lipid API tiers, with cGMP-validated drug master files commanding 2-3x research-grade phospholipid pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by endotoxin thresholds and transition temperature precision. Price erosion runs through cardiovascular-grade fatty acids as commoditized omega-3 supply chains compress margins. Research institutions exhibit highest price sensitivity, while Phase III mRNA developers prioritize speed-to-qualification over unit cost.
Supply Chain Analysis
China and Argentina anchor purified egg yolk phospholipid supply through agricultural processing clusters concentrated in Jiangsu and Buenos Aires provinces. This geographic concentration draws from avian farming feedstock vulnerable to influenza outbreak volatility. Single-source vulnerability in ionizable lipid synthesis equipment from German and Japanese vendors creates 18-month capacity expansion bottlenecks. Distribution runs through specialized CDMOs with validated commercial drug master files rather than spot-market purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic biology-derived lipids pose credible substitution pressure on traditional phospholipid extraction methods, forcing incumbents to defend process chemistry moats.
For Market Incumbents: Secure backward integration into egg yolk processing or synthetic lipid chemistry to insulate against Argentinian and Chinese agricultural volatility. Anchor capacity expansion in CDSCO-fast-track jurisdictions like Maharashtra and Gujarat to capture mRNA therapeutic outsourcing flows before competitor qualification timelines compress.
For New Entrants and Emerging Players: Microfluidic manufacturing service gaps among mid-tier CDMOs create entry points for technology-licensing plays targeting North Carolina and Massachusetts gene therapy clusters. Penetrate sphingolipid segments where ceramide stereochemistry expertise commands 3-4x phospholipid pricing premiums and incumbent coverage remains thin.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play lipid specialists with research-to-commercial transition capabilities over diversified chemical conglomerates. Watch for inflection when biotech procurement panel consolidation stabilizes at 3-4 strategic partners per sponsor, signaling qualification barrier maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Facility Retrofit Acceleration | CDSCO fast-track approvals in Hyderabad compress 24-36 month conversion timelines for research-scale lipid suites. |
| Synthetic Lipid Chemistry Licensing | Asymmetric phospholipid solid-phase synthesis methods improve liposomal encapsulation efficiency for hydrophobic APIs. |
| Microfluidic Manufacturing Adoption | Gene therapy CDMOs in Massachusetts achieve 40% yield improvements displacing batch-based LNP production. |
| Regulatory Dossier Partnership | REACH-compliant registration packages from specialized lipid houses accelerate European market entry timelines. |
| Sphingolipid Portfolio Expansion | Basel-based neurodegenerative research pipelines pull specialized ceramide volumes for blood-brain barrier penetration studies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across lipid API procurement, manufacturing, and regulatory affairs functions. Primary interviews with biotech procurement managers, CDMO production heads, and FDA regulatory consultants combined with secondary validation from FDA drug master file databases, EMA nanomedicine guidance documents, and CDSCO fast-track approval records. Bottom-up phospholipid volume modeling and top-down gene therapy pipeline sizing provided cross-check triangulation.
Across the analysis window, forecasts segmented by lipid chemistry class, therapeutic application, end-user procurement sophistication, and physical formulation architecture. CAGRs derived from clinical-stage mRNA vaccine progression rates and synthetic lipid chemistry yield improvement curves. Ionizable lipid pKa profile standardization and high-pressure homogenizer capacity expansion timelines served as industry-specific forecast sensitivity inputs.
Underlying assumptions cover regulatory convergence between FDA and EMA on lipid nanoparticle critical quality attributes, with deviation risk concentrated in avian influenza outbreak frequency and analytical chemistry talent pipeline constraints. Recalibration cycles align with material shifts in nanomedicine guidance updates and CDMO capacity utilization thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market