
 Sulfonated Melamine Formaldehyde Market | 2026-2036
Sulfonated Melamine Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfonated Melamine Formaldehyde Market Outlook
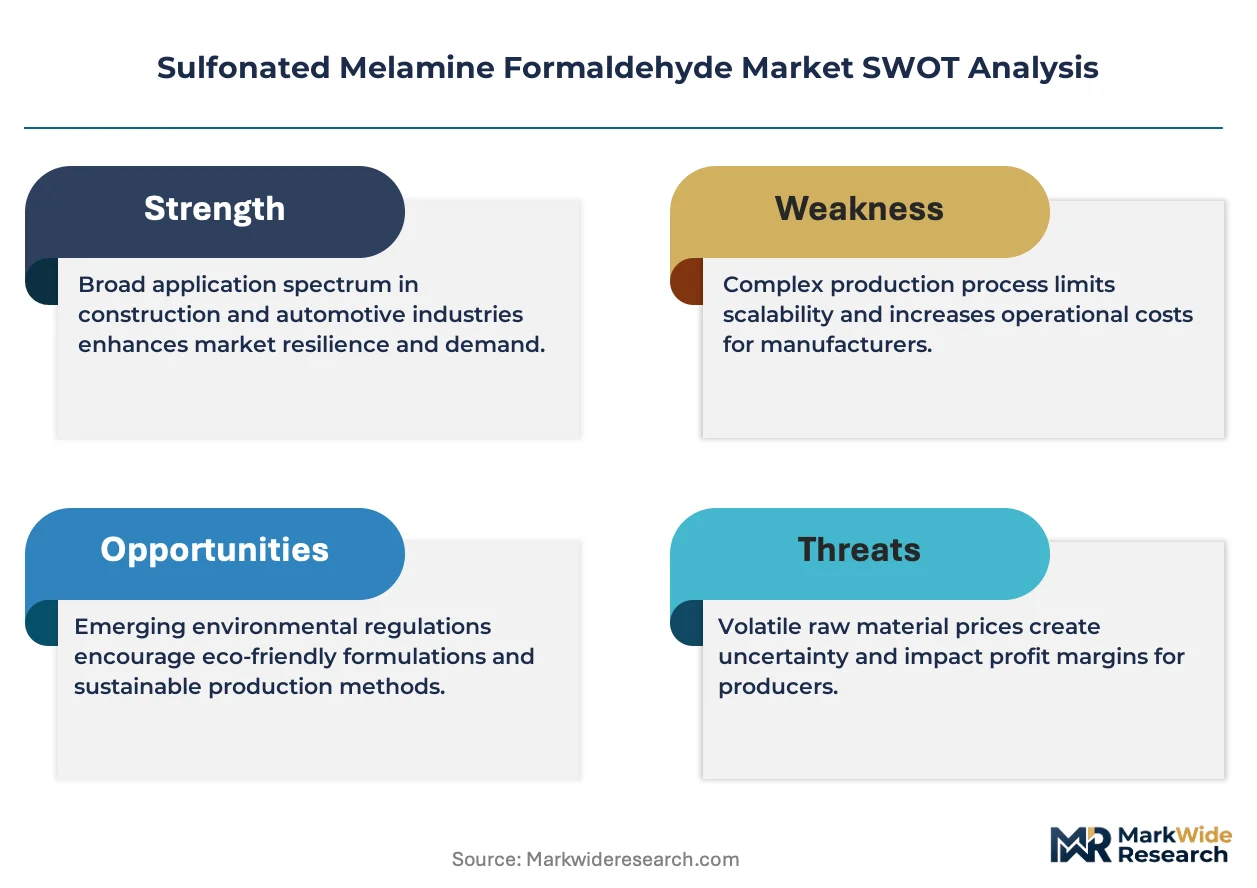
ISO 14001 environmental management certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. BASF SE leverages its integrated melamine supply chain to sustain cost advantages across European construction markets. Sika AG anchors its position through specialized admixture formulations that dominate high-performance concrete segments. Jinan Shengquan Group competes on manufacturing scale and proximity to China's domestic infrastructure demand.
Sulfonated melamine formaldehyde is a water-soluble condensate produced by sulfonating melamine-formaldehyde resin, typically yielding solids content of 20-40% with controlled molecular weight distribution for dispersant applications. Its primary industrial purpose centers on superplasticizer formulations that reduce water-cement ratios while maintaining workability in concrete and gypsum systems. Powder formulations command premium positioning due to logistics efficiency and extended shelf stability in remote construction zones. Water-based technology leads volume production but faces margin compression from energy-intensive drying avoidance requirements.
REACH registration mandates in Europe and EPA TSCA Section 5 premanufacture notification requirements in the United States constrain market entry for unqualified producers. China's GB standards administered by SAMR impose parallel testing protocols that create duplicative compliance burdens for multinational suppliers. Stakeholders must monitor evolving formaldehyde emission classifications across jurisdictions to anticipate reformulation investments and qualification timeline extensions.
Market Dynamics
Construction sector procurement is consolidating around ISO 14001-certified suppliers as formaldehyde emission thresholds tighten across major economies, bifurcating qualified from non-qualified producers and reshaping competitive positioning in concrete admixture supply chains.
Growth Catalysts
- REACH registration mandates:European ECHA compliance requirements are filtering out marginal producers and concentrating procurement among qualified resin manufacturers with established testing protocols.
- China's infrastructure stimulus:State-backed commercial construction spending is pulling sulfonated melamine formaldehyde volumes through domestic superplasticizer channels.
- Powder formulation technology:Drying efficiency improvements are extending shelf stability for remote construction zones and reducing logistics costs per active unit.
Market Restraints
- Melamine feedstock volatility:Natural gas price swings directly compress resin producer margins and destabilize contract pricing.
- Supply concentration in East China:Manufacturing gravity around Shandong province creates single-source vulnerability for international buyers.
- Polycarboxylate ether substitution:Alternative superplasticizer chemistries are capturing share in high-performance concrete segments with superior water reduction ratios.
Strategic Opportunities
- India's infrastructure build-out:National highway and metro rail expansion is generating unmet demand for certified concrete admixtures outside established supply corridors.
- EPA TSCA Section 5 pathways:Streamlined premanufacture notification procedures are opening entry channels for qualified producers into United States construction chemical markets.
- Gypsum board manufacturing convergence:Wallboard producers are integrating dispersant formulation expertise in-house, creating technology licensing opportunities for resin specialists.
Industry Challenges
- Dual carbon compliance timelines:China's MEE emission intensity targets are forcing capital-intensive retrofit investments at existing melamine condensation facilities.
- Cross-jurisdiction qualification duplication:Separate GB standards, REACH dossiers, and EPA notifications stretch regulatory affairs teams and delay market entry.
- Specialized polymer synthesis expertise scarcity:Molecular weight control for dispersant-grade resins requires chemists with condensate process experience that outpaces graduate pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfonated Melamine Formaldehyde Market |
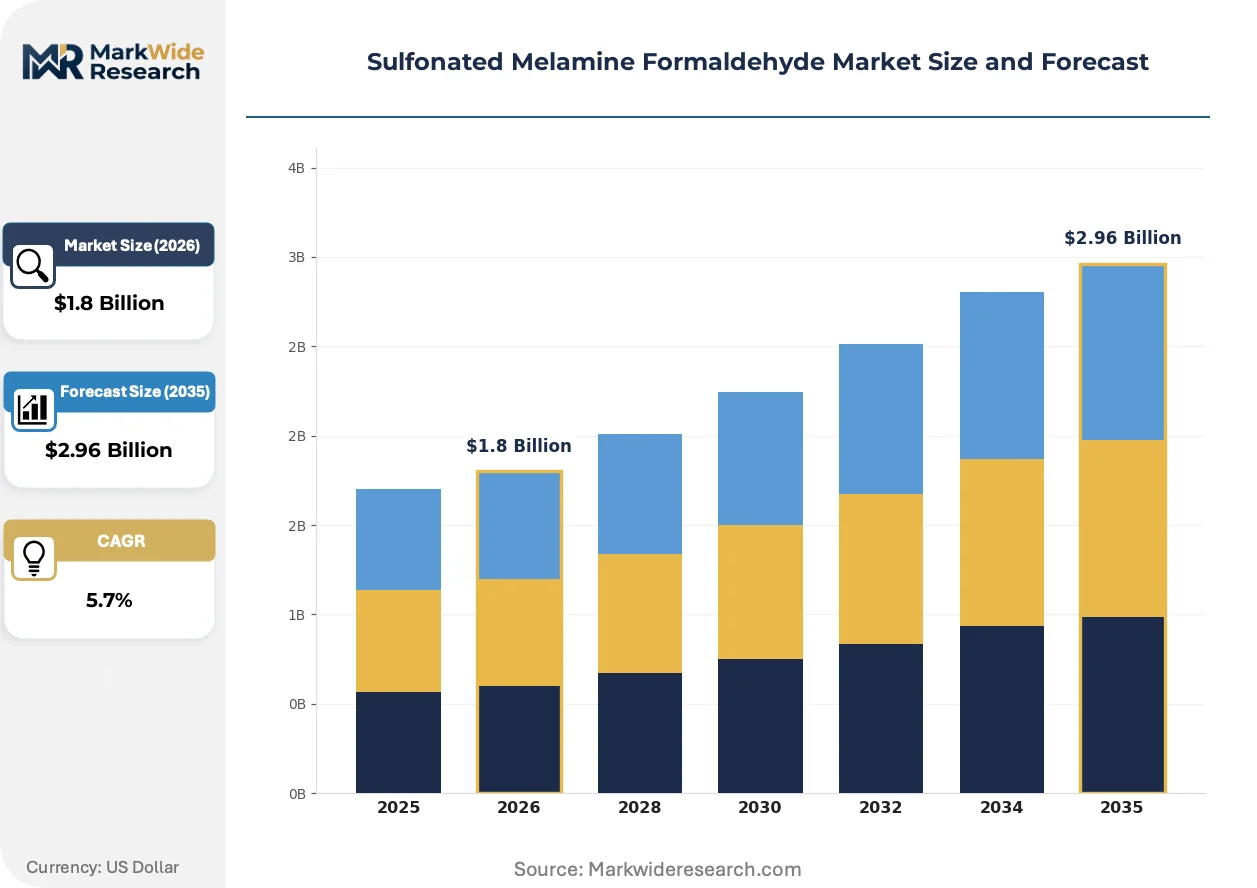
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Powders, Solutions, Granules Application: Adhesives, Coatings, Textiles, Paper End User: Construction, Automotive, Consumer Goods, Electronics Technology: Solvent-Based, Water-Based, Hot Melt, Cold Process |
| Companies Covered | AkzoNobel N.V., Sika AG, BASF SE, Jinan Shengquan Group, Shandong Shuanghe Chemical, INEOS Melamines, Georgia-Pacific Chemicals, LG Chem, Hexion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfonated Melamine Formaldehyde Market Strategic Shifts
Active reformulation investments are compressing product development cycles as emission regulations and performance specifications tighten simultaneously across construction chemical value chains.
Low-formaldehyde release resin technology is miniaturizing molecular structures through controlled condensation chemistry to maintain dispersant efficacy while meeting stricter emission classifications. European admixture formulators are adopting these modified resins fastest to preempt REACH reclassification risks. The technology is miniaturizing acceptable formaldehyde thresholds without sacrificing water-reduction performance, forcing legacy high-release products into price-competitive commodity segments.
ECHA's 2023 formaldehyde restriction proposal under REACH is compelling resin manufacturers to accelerate alternative catalyst research and reformulation testing. The industrial consequence is extended qualification timelines for new construction projects requiring CE-marked admixtures. High-performance concrete segments in Germany and France are responding fastest, with specification engineers embedding emission limits directly into tender documents ahead of mandatory enforcement.
Specification-driven procurement is replacing relationship-based purchasing as engineering firms centralize admixture selection through certified product databases. Distributor networks in North America are losing influence to direct technical sales engagement between resin producers and ready-mix concrete consolidators. This pattern is most visible in United States commercial infrastructure, where design-build contractors now mandate third-party emission certification before contract award.
Sulfonated Melamine Formaldehyde Market Segmentation
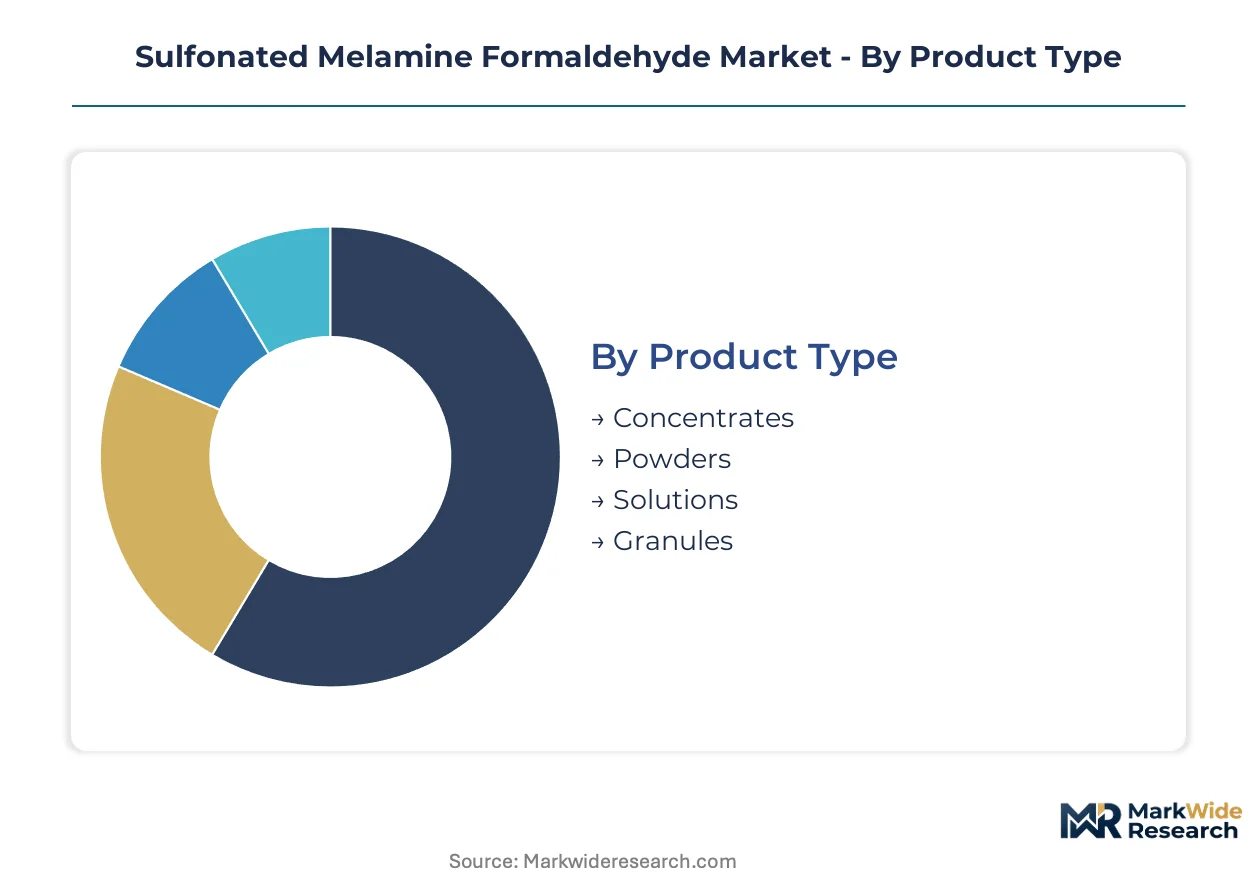
Sulfonated melamine formaldehyde procurement splits across multiple technical dimensions, each carrying distinct regulatory footprints and margin profiles. Specification engineers select segments based on emission compliance thresholds, application performance requirements, and logistics constraints.
Product Type:
REACH dossier complexity and EPA TSCA notification burdens vary sharply by physical form, concentrating procurement among suppliers with qualified testing protocols for each category.
- Concentrates:High-solids liquid formulations at 20-40% active content minimize shipping volumes for bulk admixture producers. ECHA registration requirements for liquid resins are filtering European procurement toward established suppliers with complete toxicological datasets.
- Powders:Spray-dried particles extend shelf stability beyond 24 months and slash logistics costs for remote construction zones in western China and India's Himalayan infrastructure corridors. Powder production demands energy-intensive drying, compressing margins when natural gas prices spike.
- Solutions:Ready-to-use aqueous dispersions serve small-batch concrete producers lacking in-house blending capability.
- Granules:Low-dust handling properties suit automated dosing systems in European gypsum board plants.
Powders handle the majority of throughput; concentrates are expanding most quickly in high-volume ready-mix channels.
Application:
End-use performance specifications determine molecular weight targets and sulfonation degrees, with construction-grade dispersants commanding stricter certification than industrial binders.
- Adhesives:Wood panel lamination applications in China's furniture manufacturing belt drive volume, though formaldehyde emission classifications under GB standards are forcing reformulation toward low-release variants.
- Coatings:Protective concrete surface treatments in Germany's commercial infrastructure sector specify CE-marked admixtures with documented emission profiles.
- Textiles:Crease-resistant fabric finishing in Bangladesh's garment export sector pulls modest volumes with less stringent regulatory oversight.
- Paper:Wet-strength additives for packaging grades serve saturated markets with thin margin structures.
Adhesives dominate current offtake; coatings are climbing the fastest on specification-driven procurement in European commercial construction.
End User:
Customer scale and technical sophistication create tiered service requirements, from multinational ready-mix consolidators demanding direct technical engagement to regional distributors serving fragmented buyers.
- Construction:Superplasticizer demand for high-performance concrete in China's state-backed infrastructure projects and India's metro rail expansion anchors global volume. ISO 14001 certification is becoming a mandatory tender qualification for commercial infrastructure contracts.
- Automotive:Lightweight composite binders for interior panels serve niche specifications with premium pricing but limited scale.
- Consumer Goods:Durable molded articles for household applications face substitution pressure from alternative thermoset resins.
- Electronics:Encapsulation compounds for circuit board protection require ultra-low ionic content grades with specialized purification protocols.
Construction absorbs the dominant share; electronics is gaining share fastest on semiconductor packaging demand.
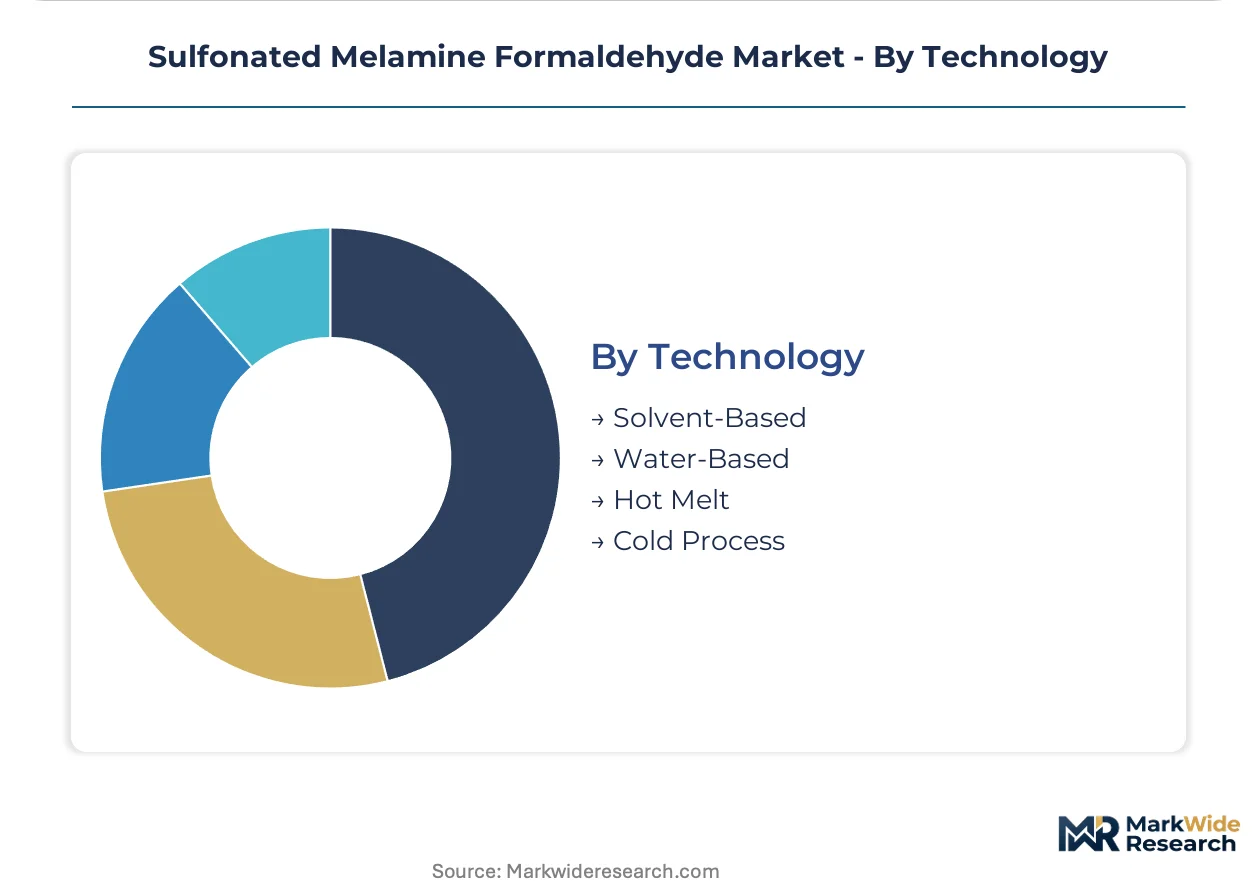
Technology:
Process chemistry selection balances energy costs against emission control investments, with water-based systems facing margin pressure from drying avoidance requirements.
- Solvent-Based:Organic carrier systems enable precise molecular weight control for specialty dispersants but face tightening volatile organic compound regulations under China's MEE emission intensity targets.
- Water-Based:Aqueous condensation dominates volume production for construction admixtures, though energy-intensive solvent recovery compresses margins at facilities lacking cogeneration capacity.
- Hot Melt:Reactive extrusion processes serve thermoplastic modification applications with rapid cycle times.
- Cold Process:Ambient-temperature sulfonation reduces energy input for small-batch specialty grades.
Water-based technology carries the bulk of production; solvent-based systems are seeing steepest expansion trajectory in high-specification coating segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ready-mix concrete consolidators and state-backed infrastructure contractors concentrate procurement in four countries where construction chemical demand aligns with tightening emission regulations and manufacturing scale.
China
State-backed highway and metro rail projects in Shandong province drive concentrated superplasticizer demand through domestic channels. SAMR-administered GB standards on formaldehyde emissions force reformulation investments at condensation facilities. Jinan and surrounding chemical clusters host integrated melamine resin production serving infrastructure contractors.
Germany
Commercial infrastructure tenders now embed REACH-compliant emission limits directly into specification documents ahead of mandatory enforcement. ECHA's 2023 formaldehyde restriction proposal accelerates alternative catalyst research among admixture formulators. The Rhine-Ruhr industrial corridor anchors qualified resin distribution for high-performance concrete segments.
United States
Design-build contractors mandate third-party emission certification before contract award, displacing relationship-based distributor networks. EPA TSCA Section 5 premanufacture notification requirements filter entry for unqualified producers. Texas and California construction markets lead specification-driven procurement through direct technical sales engagement.
India
National highway expansion and metro rail build-out generate unmet demand for certified concrete admixtures outside established supply corridors. BIS standards create parallel testing protocols that stretch regulatory affairs capacity for multinational entrants. Maharashtra and Gujarat infrastructure corridors concentrate procurement pull from state-backed contractors.
Sulfonated Melamine Formaldehyde Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive melamine supply and specialized admixture formulators with specification engineering relationships. Tiered competitive positioning separates ISO 14001-qualified suppliers from marginal producers facing ECHA and EPA compliance barriers. Two strategic archetypes dominate: backward-integrated resin manufacturers leveraging feedstock control, and application-focused specialists commanding premium positioning through formulation expertise. Capacity expansion and technology licensing represent the dominant competitive moves as emission regulations compress product development cycles.
Among European-based chemical conglomerates, BASF SE and INEOS Melamines occupy positions anchored by integrated supply chain structures. Sika AG exemplifies the formulation-specialist archetype through technical engagement with ready-mix consolidators. Jinan Shengquan Group represents the scale-driven domestic competitor archetype in China, while Shandong Shuanghe Chemical sits within the regional qualified-supplier tier serving provincial infrastructure demand.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Sika AG |
| BASF SE |
| Jinan Shengquan Group |
| Shandong Shuanghe Chemical |
| INEOS Melamines |
| Georgia-Pacific Chemicals |
| LG Chem |
| Hexion Inc. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day concentrate inventory cycles in European admixture channels signal supply-chain rigidity that amplifies pricing power for ISO 14001-qualified resin producers. Powder logistics stretching into western China and India's Himalayan corridors compress margins through energy-intensive drying costs while extending shelf-stability premiums.
Pricing Analysis
Natural gas-indexed cost-plus contracts dominate procurement between Shandong condensation facilities and European admixture formulators, with quarterly price adjustments tracking feedstock volatility. Three-tier pricing structure across REACH-certified premium, standard industrial, and unqualified economy grades separates procurement pools by emission documentation depth. Cost compression in powder grades is intensifying because melamine feedstock volatility directly passes through energy-intensive drying operations. Regional ready-mix consolidators in India exhibit highest price sensitivity, while German specification engineers prioritize emission certification over unit cost.
Supply Chain Analysis
Inventory concentration exceeding 45 days at Rotterdam distribution hubs exposes international buyers to single-source vulnerability when Shandong province production faces MEE emission intensity enforcement. Manufacturing gravity centers on China, Germany, and India, with captive melamine supply at Jinan chemical clusters anchoring feedstock security. Raw material flows draw from natural gas derivatives, formaldehyde merchant supply, and sulfonation reagents. Tariff exposure on powder formulations shipped to European construction markets compounds logistics chokepoints at Hamburg and Antwerp port clusters. Distribution runs through direct technical sales engagement with ready-mix consolidators, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH dossiers and EPA TSCA notifications constructs defensive moats that marginal producers cannot replicate without multi-year qualification timelines and toxicological dataset investments.
For Market Incumbents: Secure backward integration into captive melamine supply at Shandong and Rhine-Ruhr chemical clusters to insulate margin structures from natural gas volatility. Deepen ISO 14001 certification moats through preemptive low-formaldehyde release resin launches ahead of ECHA restriction enforcement. Polycarboxylate ether substitution in high-performance concrete segments demands rapid reformulation pipeline investment.
For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat infrastructure corridors where BIS standard compliance gaps create procurement openings for qualified multinational suppliers. Target specification-driven coating segments in German commercial construction where CE-marked admixture demand outpaces qualified resin availability. Pursue technology licensing arrangements with gypsum board manufacturers integrating dispersant formulation expertise in-house.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded melamine condensation assets lacking REACH registration completion. Long-term viability hinges on regulatory compliance scalability across dual carbon timelines and cross-jurisdiction qualification capacity. Monitor ECHA formaldehyde restriction implementation velocity as inflection indicator for reformulation investment cycles and qualified supplier consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melamine Feedstock | Captive supply from Shandong chemical clusters stabilizes margin exposure to natural gas volatility. |
| Low-Formaldehyde Release Resin Launch | Preemptive reformulation ahead of ECHA restrictions secures specification engineer preference in German tenders. |
| REACH Dossier Completion | Full toxicological datasets filter European procurement toward qualified suppliers with established testing protocols. |
| Direct Technical Sales Engagement | Bypassing distributor networks captures ready-mix consolidator relationships in Texas and California construction markets. |
| Technology Licensing to Gypsum Board Producers | Wallboard manufacturing convergence creates recurring revenue streams from in-house dispersant formulation adoption. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with admixture formulators at Sika AG and BASF SE, procurement leads at Chinese state-backed infrastructure contractors, plant managers at Shandong condensation facilities, and specification engineers at German design-build firms. Secondary validation drew from ECHA registration databases, SAMR GB standard filings, SEC 10-K chemical segment disclosures, and customs trade data tracking sulfonated resin flows. Bottom-up volume triangulation across product type, application, and end-use segments converged with top-down market sizing from construction chemical value chain analysis.
Across the analysis window, projections integrate molecular weight distribution requirements by dispersant application, emission classification tiers under evolving REACH and EPA frameworks, and regional infrastructure spending elasticity. Segmentation dimensions span physical form, end-use performance specifications, process chemistry, and customer scale tiers. CAGRs derive from elasticity modeling against construction sector output and superplasticizer substitution dynamics. Forecast inputs include melamine feedstock price trajectories and qualification timeline assumptions for cross-jurisdiction regulatory compliance.
Material uncertainties — feedstock volatility spikes, ECHA formaldehyde restriction acceleration, and polycarboxylate ether substitution thresholds — sit outside the modeled envelope and could compress volume trajectories or extend qualification timelines beyond baseline assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Titanium Fluoride Phosphate Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Disodium Adenosine Triphosphate Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Crystal Hard Wax Market