
 Global Silicone Defoamer Market | 2026-2036
Global Silicone Defoamer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Defoamer Market Foresight
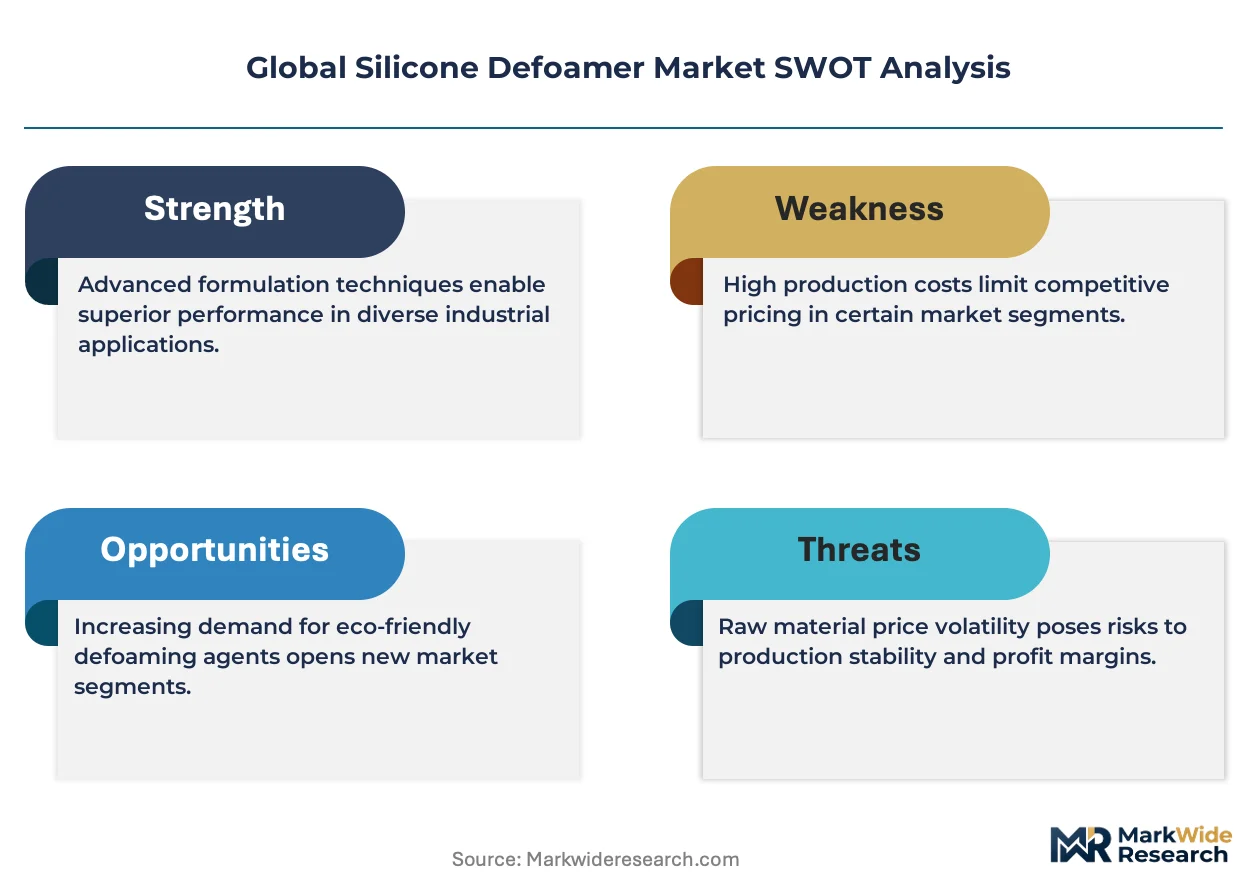
Modular packaging in intermediate bulk containers is pivoting how silicone defoamer buyers manage inventory and dosing logistics across multi-site operations. Wacker Chemie AG leverages captive silicone feedstock to sustain margin control from monomer through formulated product. Dow Inc. anchors North American supply with integrated siloxane production and regional blending capacity. BASF SE competes through broad application expertise spanning pulp processing to fermentation control.
Silicone defoamers comprise polydimethylsiloxane fluids compounded with hydrophobic silica particles, delivered as emulsions or neat oils to rupture foam lamellae in aqueous industrial systems. Their primary purpose is to suppress persistent foam in high-shear processes where organic alternatives degrade under thermal or chemical stress. Water-based emulsions command the largest volume share across pulp and paper applications, while oil-based concentrates retain premium positioning in high-temperature chemical manufacturing where thermal stability determines performance. Paints and coatings represent the fastest-growing application segment as architectural and industrial formulation lines expand waterborne resin substitution.
REACH registration requirements under ECHA govern silicone chemistry disclosure and environmental fate testing across European formulation imports. EPA effluent limitation guidelines under the Clean Water Act drive US pulp mills and refineries toward validated defoamer chemistries that meet toxicity reduction benchmarks. FDA food-contact regulations constrain silicone defoamer selection in beverage and food processing installations. Stakeholders must monitor how dual carbon targets in China and the EU Green Deal's industrial emissions framework redirect capital toward bio-based and circular feedstock alternatives.
Market Dynamics
State-led environmental audits across China's chemical manufacturing belt are forcing rapid substitution of mineral oil defoamers with silicone emulsions, compressing supplier transition windows and rewiring procurement specifications in parallel.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for silicone chemistry disclosure are compelling European formulators to validate lower-VOC emulsion grades ahead of reauthorization cycles.
- Pulp mill effluent standards:EPA guidelines under the Clean Water Act are validating silicone defoamer chemistries that meet toxicity reduction benchmarks in US paper processing corridors.
- Waterborne resin expansion:Architectural and industrial paint formulation lines are accelerating silicone defoamer adoption as solvent-based systems face phase-out pressure.
Market Restraints
- D4/D5/D6 siloxane scrutiny:ECHA's classification of certain cyclic siloxanes as substances of very high concern is constraining formulation flexibility in European imports.
- Siloxane feedstock concentration:Captive production of polydimethylsiloxane monomer resides with a limited set of integrated chemical producers, creating supply bottleneck risk.
- Mineral oil cost volatility:Crude-linked feedstock pricing for organic defoamer alternatives is distorting silicone premium justification in price-sensitive applications.
Strategic Opportunities
- India's wastewater infrastructure:Central Pollution Control Board mandates for effluent treatment plant upgrades are opening procurement channels for silicone defoamers in textile and chemical clusters.
- EU Green Deal industrial emissions framework:Carbon border adjustment mechanisms are creating preference for bio-based and circular feedstock alternatives in defoamer formulations.
- Modular IBC dosing systems:Intermediate bulk container packaging with integrated pump systems is enabling inventory pooling across multi-site chemical processing operations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silicone emulsion stability under high-shear thermal stress is concentrating among legacy technical service teams.
- Dual-registration burden:Separate FDA food-contact and EPA effluent compliance pathways are extending product validation timelines for multi-use defoamer grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Defoamer Market |
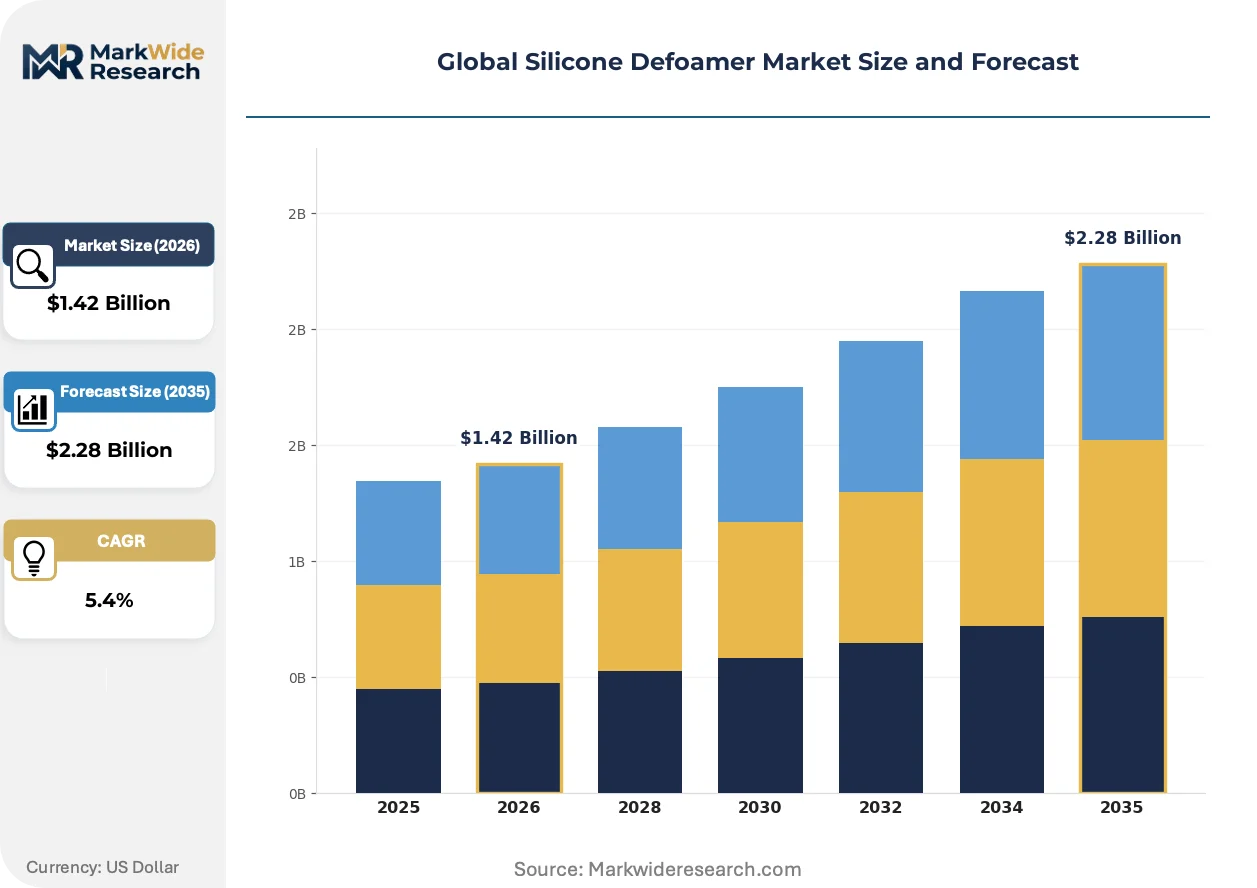
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
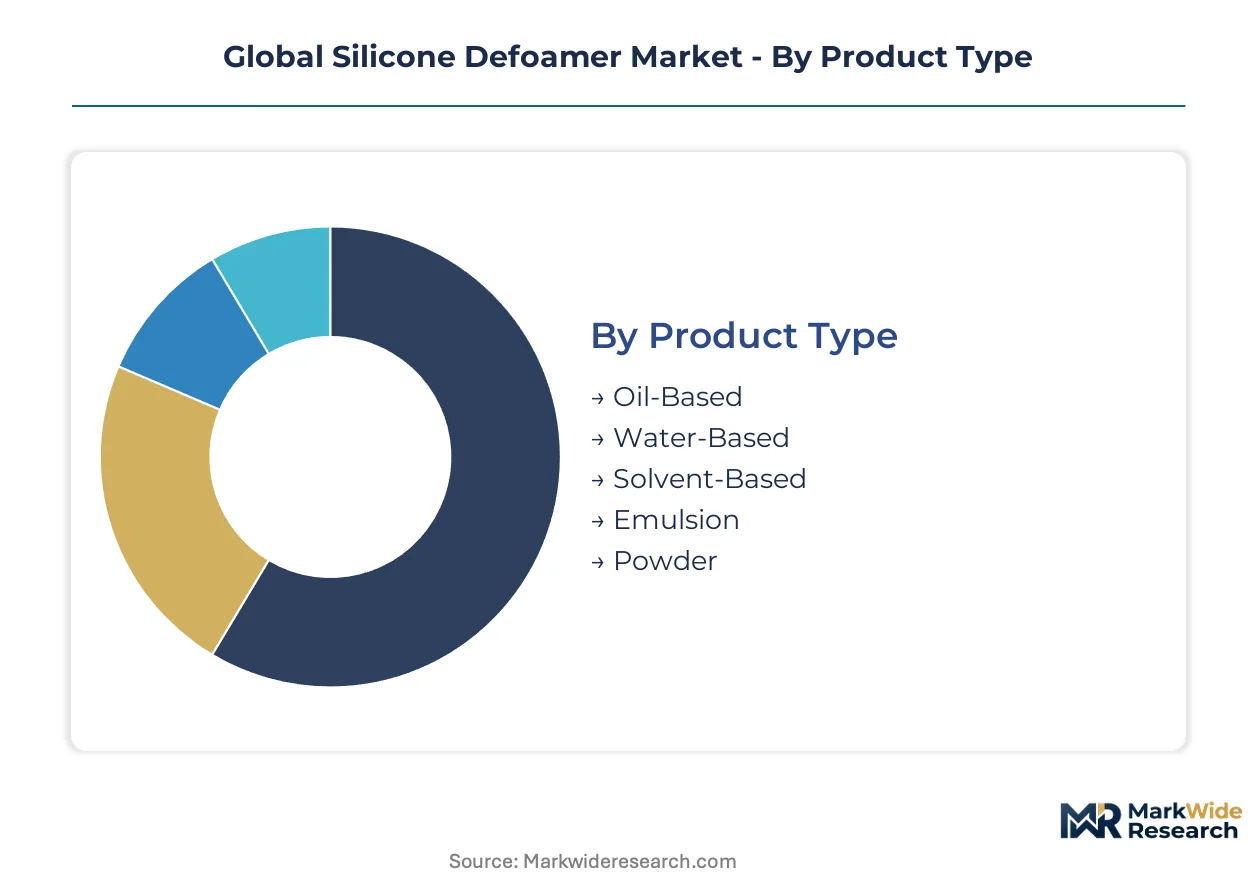
| Segmentation | Product Type: Oil-Based, Water-Based, Solvent-Based, Emulsion, Powder Application: Pulp & Paper, Paints & Coatings, Adhesives & Sealants, Textiles, Water Treatment End User Industry: Chemical Manufacturing, Food & Beverage, Electronics, Pharmaceuticals, Construction Packaging Type: Drums, Barrels, Totes, Pails |
| Companies Covered | Wacker Chemie AG, Evonik Industries AG, BASF SE, Dow Inc., Momentive Performance Materials Inc., Shin-Etsu Chemical Co. Ltd, Clariant International AG, Ashland Global Holdings Inc, Elkem Silicones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Defoamer Market Shifts & Advancements
Silicone defoamer technology is pivoting toward performance-optimized architectures that reconcile thermal stability demands with tightening environmental fate requirements across industrial wastewater and food-contact applications.
Silicone polyether copolymers with tunable hydrophilic-lipophilic balance are absorbing share in high-temperature fermentation control applications where conventional polydimethylsiloxane fluids exhibit insufficient dispersibility. Biopharmaceutical contract manufacturers are adopting these materials at accelerated pace to meet dual requirements for foam suppression and extractables validation. The technology is absorbing margin pressure from organic alternatives by enabling lower dose rates in extended-batch processes.
EPA effluent limitation guidelines are tightening toxicity testing protocols for defoamer chemistries discharged from pulp mills and petroleum refineries. Facilities in the US Gulf Coast corridor are requalifying silicone formulations to meet whole effluent toxicity benchmarks ahead of permit renewal cycles. Oil-based concentrates with validated environmental fate profiles are commanding preference over emulsion grades where thermal stability permits their deployment.
Specification-driven procurement through centralized technical buying committees is displacing decentralized chemical purchasing in multi-site paper and coatings operations. Large integrated mills are consolidating defoamer supply under single-source technical service agreements with formulation support obligations. This pattern is most visible in Germany's Rhineland chemical cluster where environmental audit consolidation is compressing supplier rosters.
Global Silicone Defoamer Market Segmentation
Silicone defoamer procurement specifications diverge sharply across process temperature, shear intensity, and regulatory exposure. Formulators must match product architecture to end-use constraints rather than applying universal solutions across industrial categories.
Product Type:
Standardization dominates at the commodity emulsion tier while oil-based concentrates retain specification-driven customization for thermal extremes.
- Oil-Based:Neat polydimethylsiloxane fluids with hydrophobic silica deliver maximum thermal stability above 150°C. Chemical manufacturing corridors in Germany's Ruhr region specify these grades for high-temperature reactor control where emulsion water content would flash off.
- Water-Based:Diluted emulsions with surfactant-stabilized silicone droplets command volume leadership across pulp mill applications. China's state environmental audits are accelerating displacement of mineral oil alternatives in Shandong province wastewater facilities.
- Solvent-Based:Silicone dispersions in hydrocarbon carriers bridge compatibility gaps in solvent-borne coating lines.
- Emulsion:Pre-diluted, pump-ready formats reduce on-site blending labor in multi-site operations.
- Powder:Solid carriers enable dry-blend incorporation into cementitious construction additives.
Most installed capacity flows through Water-Based emulsions. Expansion is steepest in Oil-Based concentrates for high-temperature chemical processing.
Application:
Volume concentration in mature pulp processing contrasts with specification intensity in emerging water treatment infrastructure.
- Pulp & Paper:Brownstock washing and bleach plant foam control consumes bulk emulsion volumes. US Gulf Coast mills under EPA effluent limitation guidelines are requalifying formulations to meet whole effluent toxicity benchmarks ahead of permit renewals.
- Paints & Coatings:Architectural and industrial formulation lines are climbing the fastest as solvent-based systems face phase-out pressure across EU member states.
- Adhesives & Sealants:High-shear mixing processes in automotive assembly plants require defoamer stability under mechanical stress.
- Textiles:Dye bath and finishing line applications in India's Tiruppur cluster face Central Pollution Control Board effluent mandates.
- Water Treatment:Municipal and industrial biological treatment basins represent emerging specification territory.
Pulp & Paper retains the largest installed base. Paints & Coatings is gaining share fastest on waterborne resin substitution.
End User Industry:
Margin structure inverts between high-volume chemical commodity buyers and validation-intensive food-contact and pharmaceutical segments.
- Chemical Manufacturing:Process reactor and distillation column foam control in Germany's BASF Ludwigshafen complex exemplifies scale procurement.
- Food & Beverage:FDA food-contact regulations constrain silicone defoamer selection in beverage processing installations.
- Electronics:Semiconductor wafer cleaning and plating bath applications require ultra-low residue specifications.
- Pharmaceuticals:Biopharmaceutical contract manufacturers are adopting silicone polyether copolymers for dual foam suppression and extractables validation.
- Construction:Concrete admixture and coating applications in China's infrastructure build-out drive drum-format procurement.
Chemical Manufacturing channels the highest volume throughput. Pharmaceutical applications are expanding most quickly on bioprocessing capacity build-outs.
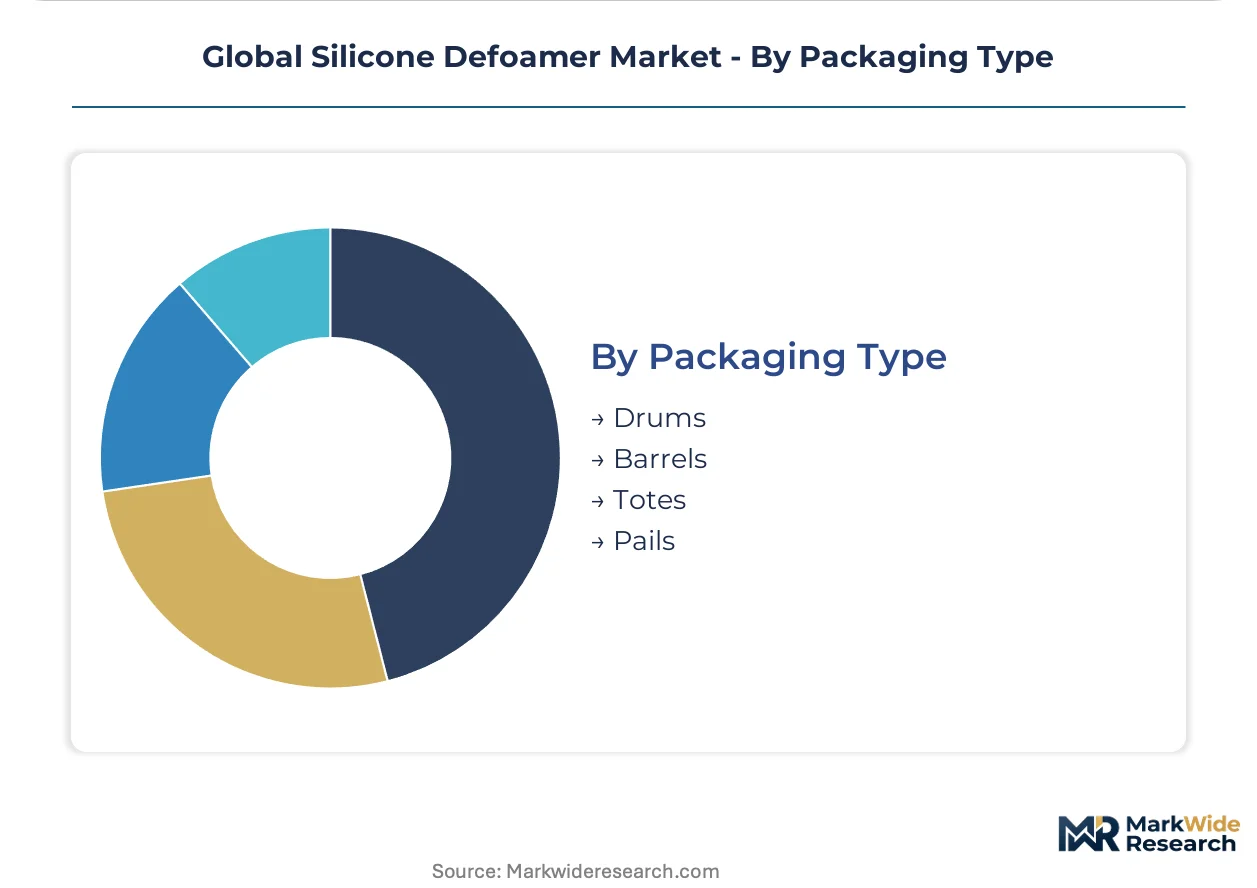
Packaging Type:
Logistics cost tiers separate bulk tanker deliveries from parcel-scale pail shipments to small formulation operations.
- Drums:Standard 55-gallon steel and polyethylene containers dominate mid-volume chemical plant replenishment cycles.
- Barrels:Intermediate capacities serve regional blending facilities with moderate throughput requirements.
- Totes:Intermediate bulk containers with integrated pump systems enable inventory pooling across multi-site paper and coatings operations in Germany's Rhineland cluster.
- Pails:Five-gallon formats address small-batch coating formulators and maintenance shops with limited storage footprint.
Drums move the highest unit volume. Totes are climbing fastest on centralized technical buying committee consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicone defoamer technology first achieved industrial scale in German chemical manufacturing during the 1950s, with the Ruhr Valley's coal-to-chemicals complexes pioneering polydimethylsiloxane synthesis for foam control in high-pressure processes.
United States
Pulp mills along the US Gulf Coast corridor and petroleum refineries in Texas and Louisiana drive bulk procurement volumes. EPA effluent limitation guidelines under the Clean Water Act are forcing requalification of defoamer formulations to meet whole effluent toxicity benchmarks ahead of permit renewal cycles. Houston-area chemical processing clusters specify oil-based concentrates for reactor control above 150°C.
Germany
The Rhineland chemical belt and Ruhr region host Europe's densest concentration of silicone defoamer formulation capacity. ECHA registration requirements under REACH compel disclosure of silicone chemistry and environmental fate testing for all imported formulations. Ludwigshafen's integrated chemical complexes anchor procurement specifications that cascade through European paper and coatings supply chains.
China
Shandong province wastewater facilities and Yangtze River Delta chemical manufacturing corridors are displacing mineral oil defoamers at the fastest pace globally. State-led environmental audits by MEE are compressing supplier transition windows and rewriting procurement specifications in parallel. Dual carbon targets are redirecting capital toward lower-emission silicone emulsion grades.
India
Textile dyeing clusters in Tiruppur and chemical processing corridors in Gujarat face Central Pollution Control Board mandates for effluent treatment plant upgrades. These regulations are opening procurement channels for silicone defoamers in applications previously served by lower-cost organic alternatives. Maharashtra's industrial zones are consolidating technical buying committees to manage multi-site defoamer supply.
Japan
Semiconductor wafer cleaning and electronics plating applications in the Kanto and Kansai regions demand ultra-low residue silicone defoamer specifications. METI industrial standards constrain formulation selection in precision manufacturing processes. Osaka-based chemical distributors are integrating modular IBC dosing systems to serve multi-site electronics assemblers.
Global Silicone Defoamer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service depth. The vendor base organizes into three tiers: integrated siloxane producers with captive monomer supply, regional blenders with formulation expertise, and commodity traders with logistics leverage. Dominant competitive moves include backward integration into siloxane feedstock and consolidation of technical service agreements under single-source contracts with large integrated mills.
Within the integrated producer tier, Wacker Chemie AG and Dow Inc. exemplify archetypes of upstream control from monomer through formulated product. BASF SE occupies a position spanning broad application expertise across pulp processing to fermentation control. These three anchors demonstrate how geographic proximity to major chemical manufacturing clusters shapes competitive positioning in specification-driven procurement environments.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Evonik Industries AG |
| BASF SE |
| Dow Inc. |
| Momentive Performance Materials Inc. |
| Shin-Etsu Chemical Co. Ltd |
| Clariant International AG |
| Ashland Global Holdings Inc |
| Elkem Silicones |
| Others |
Supply & Pricing Matrix
Dimethylsiloxane monomer spot pricing cascades through silicone defoamer value chains into three-tier pricing structures across premium, standard, and economy levels. Wacker Chemie AG and Dow Inc. leverage captive siloxane production to buffer margin compression when feedstock costs spike, while regional blenders absorb volatility through contract pass-through clauses.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated producers and large pulp mills. Price differentiation hinges on formulation certification tier and volume scale, with FDA food-contact validated grades commanding substantial premiums over industrial emulsion grades. Cost compression in standard water-based emulsions is intensifying because mineral oil alternatives are pressuring substitution economics in price-sensitive textile applications. Small coating formulators exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize extractables validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese polydimethylsiloxane monomer production. Siloxane feedstock draws from chlorosilane cracking capacity concentrated in Germany's Ruhr region and China's Yangtze River Delta. Hydrophobic silica sourcing and specialized surfactant packages rest on Japanese and German chemical suppliers. Tariff exposure on siloxane imports into India is reshaping local blending economics. Distribution runs through drum and intermediate bulk container formats to chemical manufacturing clusters, with technical service bundling increasingly standard.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone defoamer demand functions as a regulatory compounder where EPA effluent limitation guidelines under the Clean Water Act force continuous reformulation cycles across US pulp processing corridors.
For Market Incumbents: Extend technical service agreements into multi-year single-source contracts with integrated paper mills to lock out regional blenders. Deepen backward integration into hydrophobic silica production to reduce dependency on Japanese suppliers when feedstock costs spike. Defend against mineral oil substitution by validating environmental fate profiles ahead of permit renewal cycles. For New Entrants and Emerging Players: Central Pollution Control Board mandates in India open a window for silicone defoamer penetration in Tiruppur textile clusters previously served by organic alternatives. Target wastewater infrastructure upgrades in Maharashtra's industrial zones where technical buying committees are consolidating supply. Pursue toll-manufacturing partnerships with established emulsion blenders to bypass siloxane feedstock bottlenecks. For Investors and Strategic Acquirers: Asymmetric upside sits with regional blenders possessing formulation expertise but lacking captive monomer supply. Long-term viability centers on acquisition targets with validated EPA and REACH dossiers that reduce re-registration risk. Watch for ECHA classification decisions on cyclic siloxanes as inflection indicators for formulation chemistry redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer | Wacker Chemie AG's captive feedstock production insulates margin control from raw material volatility. |
| Green Manufacturing Transition | EU Green Deal carbon border adjustments favor bio-based silicone polyether copolymer development. |
| Long-term Supply Agreement | Dow Inc. anchors North American pulp mill demand through integrated siloxane-to-emulsion contracts. |
| Joint Venture | Shin-Etsu Chemical partnerships in China navigate MEE environmental audit requirements. |
| Capacity Expansion | Elkem Silicones targets India's Central Pollution Control Board-driven wastewater infrastructure build-out. |
Research Methodology
Bottom-up pulp mill and chemical plant modeling reconciled against top-down siloxane production tracking forms the analytical core. Primary interviews with formulation chemists, procurement leads at integrated paper mills, technical service directors, and wastewater plant operators combined with secondary validation from ECHA registration databases, EPA effluent guideline filings, and customs trade data. Triangulation across stakeholder inputs and regulatory disclosure documents ensures segmentation integrity.
Historical trendline analysis of silicone defoamer adoption rates across pulp processing, paints and coatings, and water treatment applications established baseline penetration curves. The projection framework segments by product architecture, end-use industry intensity, and regional regulatory cluster, with CAGRs derived from elasticity modeling against effluent standard tightening schedules. Siloxane feedstock capacity expansion timelines and environmental audit rollout pacing in China informed supply-side constraints.
Revisions become necessary when ECHA reclassifies additional siloxane chemistries or when China's MEE accelerates environmental audit schedules beyond modeled baselines. Forecasts reflect documented assumptions about regulatory enforcement intensity and substitution economics between silicone and mineral oil alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Demethylase Inhibitor Market
Specialty Chemicals
4-Propyl-1,3,2-Dioxathiolane 2,2-Dioxid Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Sandarac Market