
 Betanin Market | 2026-2036
Betanin Market Size, Share, and Industry Trends Forecast 2026-2036
Betanin Market Outlook
Clean-label food and beverage manufacturers are bifurcating away from synthetic dye buyers as the dominant procurement archetype in the betanin value chain. DDW The Color House leverages its vertical integration from beetroot sourcing to finished color systems to sustain margin control across multiple continents. Kalsec Inc. anchors its position through deep extraction technology leadership in natural colorants, while Sensient Technologies Corporation competes via broad formulation libraries that span liquid, powder, and encapsulated delivery formats.
Betanin is a water-soluble nitrogenous pigment extracted primarily from Beta vulgaris roots, with maximum absorbance near 535-540 nm and pH-dependent stability ranging from 4.0 to 7.0, functioning as a natural colorant and antioxidant in processed goods. Liquid betanin formulations dominate current volume owing to ease of incorporation into beverages and dairy, while powder and granule formats are capturing faster growth in dry-mix applications where shelf stability and freight economics matter. Pharmaceutical and nutraceutical applications concentrate margin pools due to stricter purity certifications and lower price elasticity compared to commodity food coloring.
FDA color additive regulations under 21 CFR 73 and EFSA food additive evaluations under Regulation (EC) No 1333/2008 govern betanin approval thresholds, labeling requirements, and maximum usage levels across jurisdictions. ISO 22000 and FSSC 22000 certification demands from downstream buyers are filtering out uncertified extractors and consolidating supply relationships with audited processors. Stakeholders must monitor evolving purity standards for pharmaceutical-grade betanin and assess backward integration into beetroot cultivar development to secure chromatographic consistency.
Market Dynamics
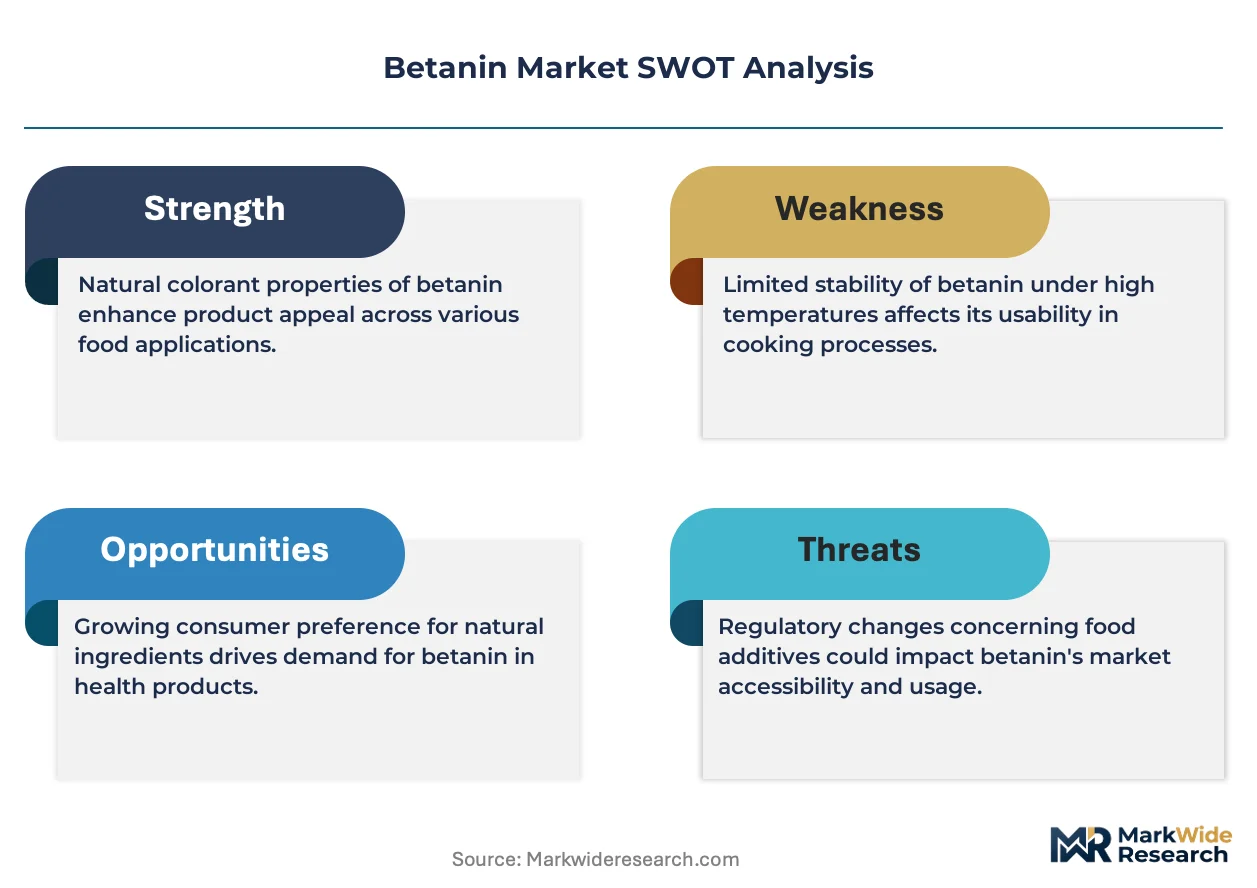
Synthetic dye replacement mandates are compressing formulation timelines for food and beverage manufacturers, forcing rapid qualification of betanin alternatives across multiple approval jurisdictions simultaneously.
Growth Catalysts
- REACH Annex XVII restrictions:ECHA's tightening thresholds on azo dyes and synthetic colorants redirect R&D budgets toward beetroot-derived substitutes in EU confectionery and dairy sectors.
- Encapsulation technology maturation:Microencapsulation processes now extend betanin thermal stability above 85°C, unlocking applications in UHT beverages and extruded snacks previously closed to natural pigments.
- German processing cluster dominance:Concentrated extraction capacity around Hamburg and Lower Saxony reduces logistics costs for pan-European bakery supply chains, accelerating adoption velocity.
Market Restraints
- Beetroot input volatility:Agricultural yields in Poland and Ukraine fluctuate 15-22% seasonally, creating raw material cost instability that squeezes processor margins.
- pH-dependent degradation:Betanin's chromatic stability collapses below pH 3.5 and above pH 7.0, structurally excluding applications in acidic soft drinks and alkaline noodle products.
- Anthocyanin substitution threat:Purple sweet potato and black carrot extracts offer superior light stability, capturing premium beverage applications where betanin falters.
Strategic Opportunities
- Pharmaceutical-grade certification gap:USP and EP monograph compliance for parenteral applications remains underdeveloped, creating first-mover advantage for GMP-certified extractors targeting oncology supportive care.
- India FSSAI natural colorant notification:Pending amendments to Food Safety Standards Regulations are expected to expand permitted betanin categories in processed foods, opening a 1.4 billion-consumer market.
- Cosmeceutical antioxidant positioning:Topical formulations leveraging betanin's ORAC values are penetrating Korean and Japanese skincare channels, diverting from commoditized food-grade pricing.
Industry Challenges
- Chromatographic consistency talent scarcity:Analytical chemists capable of HPLC method validation for betanin purity profiling command 40% salary premiums, constraining quality team scaling.
- FSSC 22000 audit backlog:Certification body capacity shortages extend implementation timelines 8-14 months, delaying supplier qualification for multinational food manufacturers.
- Legacy synthetic dye inventory absorption:Food manufacturers face stranded asset risk in existing Tartrazine and Allura Red AC stocks, slowing transition capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betanin Market |
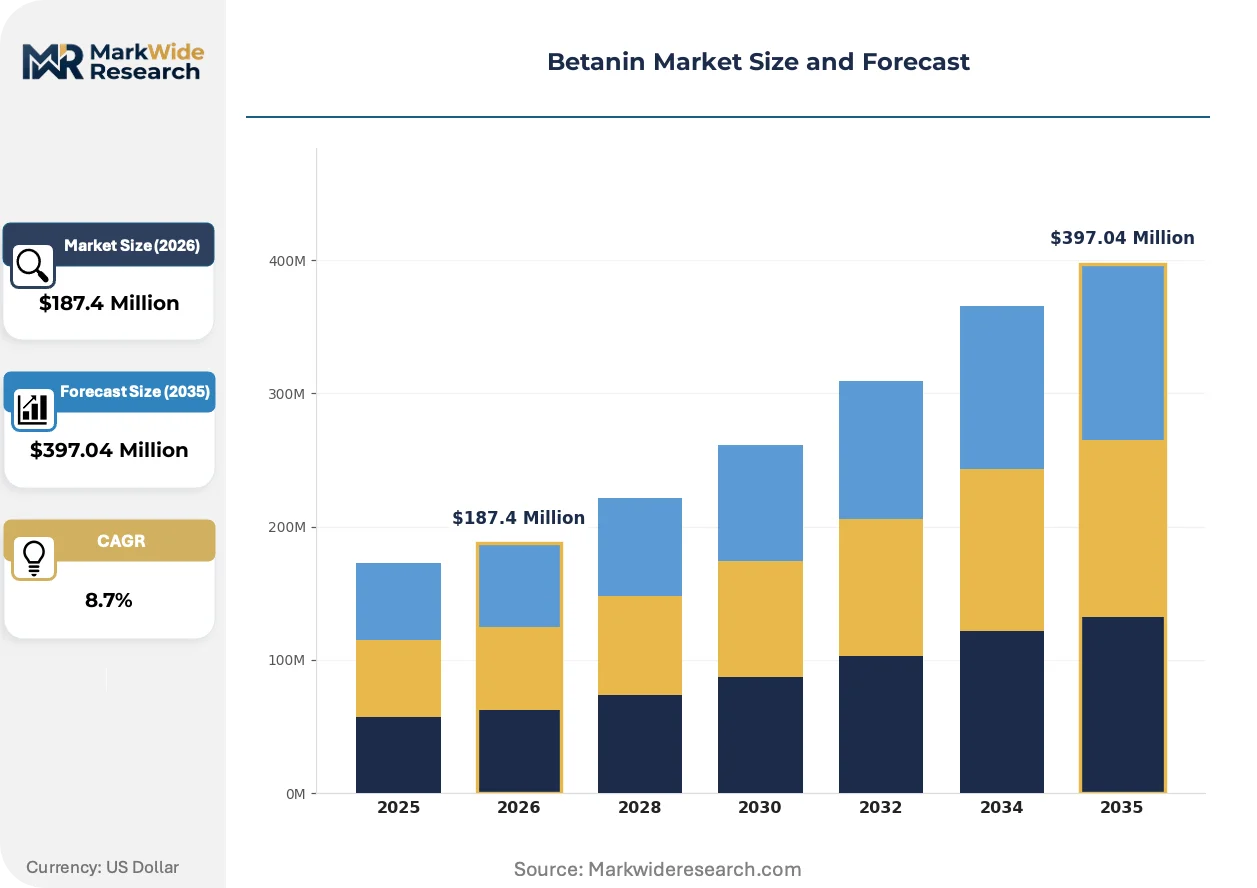
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Capsules Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Source: Beetroot, Other Vegetables, Fruit Extracts, Synthetic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | DDW The Color House, Kalsec Inc., Sensient Technologies Corporation, Synthite Industries Ltd., ROHA Group, GNT Group, Döhler GmbH, Plant Lipids, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betanin Market Strategic Shifts
Processing technology convergence and regulatory stringency are bifurcating the betanin value chain into commodity food-grade and premium pharmaceutical-grade tiers with diverging technical specifications.
Encapsulation via modified starch and gum arabic matrices is decomposing the traditional tradeoff between thermal stability and clean-label status. Beverage manufacturers in Germany and the Netherlands are adopting spray-dried betanin microcapsules at pilot scale for sports drink applications. This technology is compressing the shelf-life gap with synthetic alternatives from 18 months to 6 months, enabling broader retail distribution.
FDA's 21 CFR 73.260 color additive petition backlog is reshaping competitive entry sequencing for new betanin formulations. The industrial consequence is a 24-36 month qualification timeline that favors incumbent suppliers with existing approvals. Pet food and dietary supplement categories are most affected, with manufacturers accelerating GRAS self-affirmation pathways to circumvent delays.
Direct-procurement relationships between CPG manufacturers and beetroot cooperatives are displacing traditional distributor intermediaries in North American supply chains. Large bakery and confectionery buyers in California and Illinois are contracting directly with Red River Valley growers for identity-preserved cultivars. This pattern is most visible in organic and non-GMO verified product lines where traceability commands 12-18% price premiums.
Betanin Market Segmentation
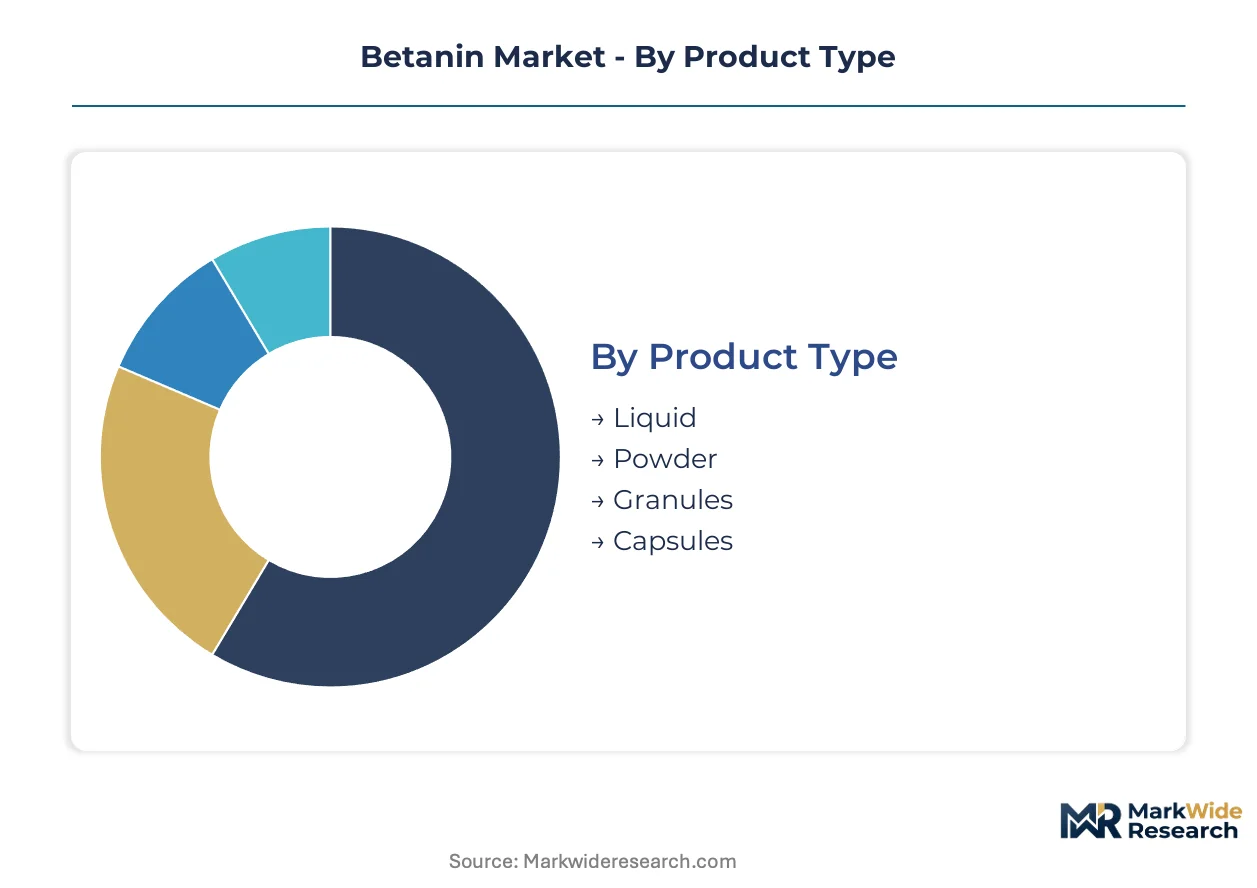
Betanin procurement patterns diverge sharply across product formats and end-use specifications, with pharmaceutical-grade certifications commanding 3-4x food-grade price multiples. Source traceability and delivery format stability now determine supplier selection more than unit cost alone.
Product Type:
Liquid formulations concentrate margin pools in high-volume beverage contracts, while encapsulation technologies are capturing premium positioning in thermal-stress applications.
- Liquid:Water-soluble betanin extracts with 0.5-2.0% standardized color value dominate beverage and dairy incorporation. German dairy processors in Bavaria and North Rhine-Westphalia are locking in annual supply contracts for UHT-stable liquid grades, prioritizing freight economics over powder conversion costs.
- Powder:Spray-dried formulations with maltodextrin carriers enable dry-mix bakery and confectionery applications where moisture control is critical. California-based clean-label CPG manufacturers are rotating procurement toward powder formats for organic cookie and granola lines, accepting 15-20% color potency tradeoffs for shelf stability.
- Granules:Agglomerated particles reduce dusting and improve flowability in industrial-scale dosing equipment. Nutraceutical tablet manufacturers in New Jersey and Utah specify granule grades for direct-compression formulations.
- Capsules:Pre-measured single-unit doses serve clinical trial supply and compounding pharmacy channels. USP-grade capsule demand is climbing fastest among oncology supportive care formulators seeking batch-to-batch chromatographic consistency.
Liquid holds installed capacity. Capsules is rotating up the share rankings.
Application:
Pharmaceutical and nutraceutical channels extract value through purity certification requirements that food-grade buyers cannot justify.
- Food & Beverages:Clean-label bakery, confectionery, and dairy applications drive volume procurement, with EFSA-compliant color additive petitions required for EU market access. Polish and Ukrainian beetroot supply chains feed pan-European bakery reformulation programs replacing Tartrazine and Allura Red AC.
- Pharmaceuticals:Parenteral and oral dosage forms demand USP and EP monograph compliance with HPLC-validated purity profiling. GMP-certified extractors in Germany and Switzerland are securing multi-year contracts for oncology and cardiovascular therapeutic categories.
- Cosmetics:Topical antioxidant formulations leverage betanin's ORAC values in Korean and Japanese skincare channels, diverting from commoditized food-grade pricing structures.
- Nutraceuticals:Dietary supplement applications in softgel and tablet formats require GRAS self-affirmation or FDA color additive petition clearance. Direct-to-consumer brands in California and Colorado are accelerating procurement for beetroot-based cardiovascular health positioning.
Food & Beverages anchors volume throughput. Pharmaceuticals is climbing the fastest.
Source:
Beetroot cultivar control determines chromatographic batch consistency, while alternative vegetable sources threaten betanin in pH-sensitive applications.
- Beetroot:Beta vulgaris L. cultivars with standardized betanin-to-vulgaxanthin ratios remain the dominant commercial source. Identity-preserved organic beetroot from Red River Valley cooperatives commands 12-18% price premiums in North American organic certification channels.
- Other Vegetables:Swiss chard and amaranth provide alternative betalain profiles with modified stability characteristics. Niche processors in Italy and France are piloting chard-derived extracts for regional specialty food applications.
- Fruit Extracts:Prickly pear and dragon fruit offer complementary betalain spectra but at substantially higher raw material costs. Cosmetic formulators in South Korea are evaluating prickly pear extracts for dual antioxidant-colorant positioning.
- Synthetic:Chemically synthesized betanin analogs remain commercially negligible due to clean-label rejection and regulatory complexity. No significant synthetic capacity is operational in FDA or EFSA jurisdictions.
Beetroot maintains captive supply relationships. Other Vegetables is gaining share fastest in premium positioning.
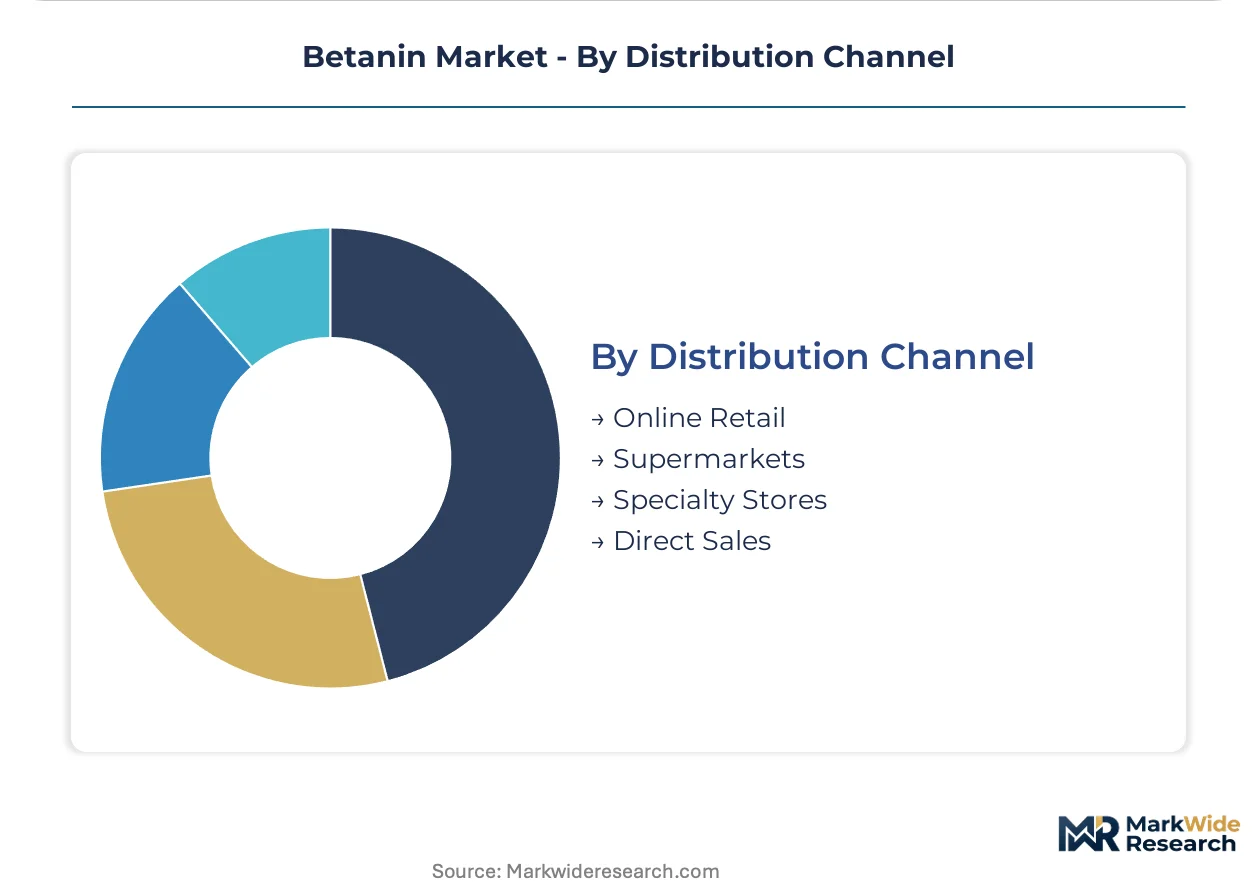
Distribution Channel:
Direct procurement relationships are displacing traditional distributor intermediaries in high-volume food manufacturing segments.
- Online Retail:E-commerce platforms serve small-scale nutraceutical and cosmetic formulators with MOQs below 25kg. Amazon Business and Alibaba channels are capturing artisanal food producer demand in secondary US and Chinese cities.
- Supermarkets:Mass-market retail carries finished consumer goods rather than industrial betanin, with private-label natural colorant lines in German and Dutch chains driving indirect ingredient demand.
- Specialty Stores:Natural products distributors and ingredient boutiques supply craft food manufacturers and independent cosmetic formulators. UNFI and KeHE in North America maintain betanin SKUs for regional bakery and confectionery accounts.
- Direct Sales:Long-term supply agreements between extractors and CPG manufacturers eliminate margin stacking. Illinois and California bakery conglomerates are contracting directly with Hamburg-area processors for identity-preserved beetroot supply chains.
Direct Sales holds contract value concentration. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals anchor European betanin distribution, while Union Pacific's rail corridors connect Red River Valley beetroot growers to Chicago-area processors. These infrastructure assets compress transit times for temperature-sensitive liquid extracts.
Germany
Clean-label dairy reformulation in Bavaria and North Rhine-Westphalia accelerates betanin procurement for UHT-stable applications. EFSA's Regulation (EC) No 1333/2008 governs maximum usage levels and labeling requirements for natural colorants. The Hamburg-Lower Saxony extraction cluster supplies pan-European bakery chains with identity-preserved organic grades.
United States
Illinois and California bakery conglomerates contract directly with Red River Valley beetroot cooperatives for non-GMO verified supply chains. FDA's 21 CFR 73.260 listing requirements create 24-36 month qualification timelines that favor incumbent suppliers. Chicago-area processors leverage Union Pacific rail access to minimize inbound agricultural logistics costs.
India
Processed food manufacturers in Maharashtra and Gujarat await FSSAI amendments to expand permitted natural colorant categories in confectionery. The country's food safety regulator evaluates betanin petitions under pending Food Safety Standards Regulations revisions. Mumbai-Pune industrial corridors position contract manufacturers to serve domestic and export markets simultaneously.
Switzerland
Pharmaceutical-grade betanin demand concentrates in Basel and Zurich for oncology supportive care applications. Swissmedic's GMP certification requirements filter supplier qualification to audited extractors with USP monograph compliance. The Basel-Lake Constance biotech corridor secures multi-year supply agreements for parenteral dosage forms.
Netherlands
Spray-dried betanin microcapsule adoption spreads among Rotterdam-area sports drink formulators seeking thermal stability above 85°C. REACH Annex XVII restrictions on azo dyes redirect R&D budgets toward beetroot-derived alternatives. The Rotterdam-Antwerp chemical processing hub enables encapsulation technology scale-up for beverage applications.
Betanin Market Competitive Environment
Listed leaders compete with private specialists across extraction technology and certification tiers. The vendor base clusters around three strategic positions: integrated processors controlling beetroot sourcing through finished color systems, technology-focused extractors with deep extraction capabilities, and formulation houses spanning multiple delivery formats. Archetypal differentiation separates commodity food-grade suppliers from pharmaceutical-grade certifiers. Competitive moves concentrate on backward integration into cultivar development and encapsulation technology licensing to extend thermal stability thresholds.
Within the integrated processing tier, DDW The Color House and Döhler GmbH exemplify archetypes spanning agricultural sourcing to formulation libraries. Kalsec Inc. occupies a specialist position in extraction technology leadership. Sensient Technologies Corporation anchors the formulation-diverse segment with broad delivery format coverage. These named entities represent competitive positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| DDW The Color House |
| Kalsec Inc. |
| Sensient Technologies Corporation |
| Synthite Industries Ltd. |
| ROHA Group |
| GNT Group |
| Döhler GmbH |
| Plant Lipids |
| Chr. Hansen Holding A/S |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month color stability guarantees now separate contract winners from spot-market suppliers, concentrating pricing power among German processors with captive beetroot sourcing and validated encapsulation capabilities. Food-grade liquid extracts trade at commodity spreads while pharmaceutical-grade capsules capture 3-4x multiples, with the Hamburg-Lower Saxony cluster dictating regional reference pricing through integrated production.
Pricing Analysis
Volume-discount tiering structures stratify procurement across annual contract, quarterly commitment, and spot-market bands. Pharmaceutical-grade USP and EP certification commands premium positioning over food-grade alternatives, with FSSC 22000 compliance adding further separation. Cost compression in commodity liquid grades intensifies as Polish and Ukrainian agricultural volatility feeds raw material instability. Bakery conglomerates in Illinois and California exhibit highest price sensitivity, while oncology formulators in Basel and Zurich absorb premiums for batch-to-batch chromatographic consistency.
Supply Chain Analysis
Beetroot sourcing from Poland, Ukraine, and the Red River Valley feeds extraction capacity concentrated in Germany and the United States. Processing draws from agricultural inputs, maltodextrin carriers, and modified starch encapsulation matrices. Single-source vulnerability in Eastern European beetroot supply chains exposes margin structures to climate-driven yield fluctuations. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries, with Illinois and California bakery buyers contracting identity-preserved cultivars from Hamburg-area processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPLC method validation expertise for betanin purity profiling commands 40% salary premiums, constraining quality team scaling and filtering competitive entry to audited extractors with analytical chemistry depth. This capability scarcity rewards first movers in pharmaceutical-grade certification and encapsulation technology licensing.
For Market Incumbents: Fortify backward integration into beetroot cultivar development to secure chromatographic batch consistency against anthocyanin substitution threats from purple sweet potato and black carrot extracts. Expand encapsulation licensing to beverage manufacturers seeking thermal stability above 85°C, while accelerating GMP certification for parenteral applications to capture oncology supportive care contracts. For New Entrants and Emerging Players: Anchor in India's pending FSSAI natural colorant notification expansion, where processed food manufacturers in Maharashtra and Gujarat await regulatory clarity to reformulate confectionery lines. Target cosmeceutical antioxidant positioning in Korean and Japanese skincare channels, where ORAC-value marketing diverges from commoditized food-grade pricing structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified natural ingredient processors with underutilized extraction capacity and dormant pharmaceutical-grade certification pathways. Long-term viability hinges on regulatory moat depth rather than commodity scale. Watch FDA 21 CFR 73.260 petition backlog resolution as inflection indicator for competitive entry sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivar Development | Secures chromatographic consistency for pharmaceutical-grade contracts requiring USP monograph compliance. |
| Encapsulation Technology Licensing | Extends thermal stability thresholds above 85°C for UHT beverage applications in Germany and the Netherlands. |
| GMP Certification Investment | Filters supplier qualification for parenteral dosage forms under Swissmedic and FDA oversight. |
| Direct Procurement Relationship Building | Eliminates margin stacking for Illinois and California bakery conglomerates seeking identity-preserved supply chains. |
| Pharmaceutical-Grade Purity Profiling | Captures 3-4x price multiples from oncology formulators demanding HPLC-validated batch consistency. |
Study Parameters
Initial hypotheses were tested against primary input from extraction technology directors, natural colorant procurement managers at bakery and confectionery manufacturers, pharmaceutical formulation scientists, and regulatory affairs specialists at EFSA and FDA, then refined against secondary validation from customs trade data, SEC filings of listed ingredient processors, EFSA food additive evaluation records, and ISO 22000 certification registries. Bottom-up demand modeling across application segments triangulated with top-down supply capacity assessments.
Variance-decomposition framing isolates volume, price, and mix effects across the projection horizon. Segmentation dimensions span product format, application grade, source cultivar, and distribution channel, with pharmaceutical certification tiers modeled separately from commodity food-grade throughput. CAGRs derive from elasticity-adjusted demand curves and capacity expansion schedules, incorporating beetroot yield volatility bands and encapsulation technology adoption S-curves.
Decision-makers should treat outputs as directional under stable regulatory approval timelines and unaltered REACH Annex XVII enforcement intensity; material deviation in FDA petition processing speed or Eastern European agricultural conditions would warrant model refresh. Practitioners should keep alternative scenarios live as FSSAI notification timelines and anthocyanin substitution cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Fatliquoring Agents Market