
 Abierixin Market | 2026-2036
Abierixin Market Size, Share, and Industry Trends Forecast 2026-2036
Abierixin Market Insights
Aftermarket service revenue from biologic companion diagnostics is rewriting how specialty clinics capture margin from treatment protocols. AbbVie leverages its immunology infrastructure to sustain patient access programs across North American infusion centers. Pfizer anchors its position through integrated cold-chain logistics that dominate parenteral distribution networks. Bristol Myers Squibb differentiates via centralized compounding partnerships that control formulation quality at the point of care.
Abierixin denotes a targeted biologic therapeutic class engineered for precision immune modulation, typically manufactured through recombinant protein expression in mammalian cell cultures with purity thresholds exceeding 98% and endotoxin limits below 0.25 EU per milligram, designed primarily to interrupt cytokine signaling cascades in refractory autoimmune and oncologic indications. Injectable formulations lead current revenue pools due to hospital-based administration requirements and higher reimbursement tiers, while oral suspension development represents the fastest-growing segment as pediatric and geriatric populations drive demand for non-invasive delivery. Immunotherapy applications occupy the deepest margin pools given checkpoint inhibitor combination protocols, whereas inflammatory disorder treatments compete on volume through broader prescriber bases in primary care settings.
FDA's Center for Drug Evaluation and Research enforces Current Good Manufacturing Practice standards that shape abierixin batch release timelines and facility inspection frequencies, while EMA's Committee for Medicinal Products for Human Use coordinates centralized marketing authorization procedures that determine European market access pathways. ISO 13485 quality management requirements govern contract manufacturing organizations supplying active pharmaceutical ingredients across multiple jurisdictions. Stakeholders must monitor evolving biosimilar interchangeability designations that will determine generic substitution economics and originator defense strategies.
Market Dynamics
FDA accelerated approval pathways compress development timelines for abierixin candidates while EMA centralized procedures create divergent market entry schedules across jurisdictions. Biopharmaceutical firms must navigate asynchronous regulatory clocks that fragment launch sequencing and strain manufacturing capacity allocation.
Growth Catalysts
- Immunotherapy protocol expansion:Checkpoint inhibitor combination therapies drive demand for precision cytokine modulation in oncology settings.
- Accelerated approval pathways:FDA's breakthrough therapy designation reduces clinical development phases for refractory autoimmune indications.
- Specialty clinic network densification:United States infusion center capacity concentrates patient access points for parenteral administration.
Market Restraints
- Mammalian cell culture input volatility:Recombinant protein expression depends on serum supply chains vulnerable to bovine spongiform encephalopathy restrictions.
- Single-source API concentration:Contract manufacturing organizations in Switzerland and Germany control critical active pharmaceutical ingredient production.
- Biosimilar interchangeability uncertainty:FDA designation delays compress originator defense windows and deter generic substitution investments.
Strategic Opportunities
- Pediatric oral suspension white space:Geriatric and pediatric populations in Japan and South Korea drive non-invasive delivery format development.
- Cold-chain logistics integration:Biopharmaceutical firms can capture margin through in-house parenteral distribution networks.
- Companion diagnostic bundling:Biologic therapeutic protocols create service revenue streams at point-of-care settings.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian cell culture optimization requires specialized fermentation scientists concentrated in Boston and Basel clusters.
- Multi-jurisdiction batch release complexity:ISO 13485 quality management demands divergent documentation standards across FDA and EMA inspection regimes.
- Endotoxin testing throughput bottlenecks:Limulus amebocyte lysate assay capacity constrains release timelines for high-purity formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abierixin Market |
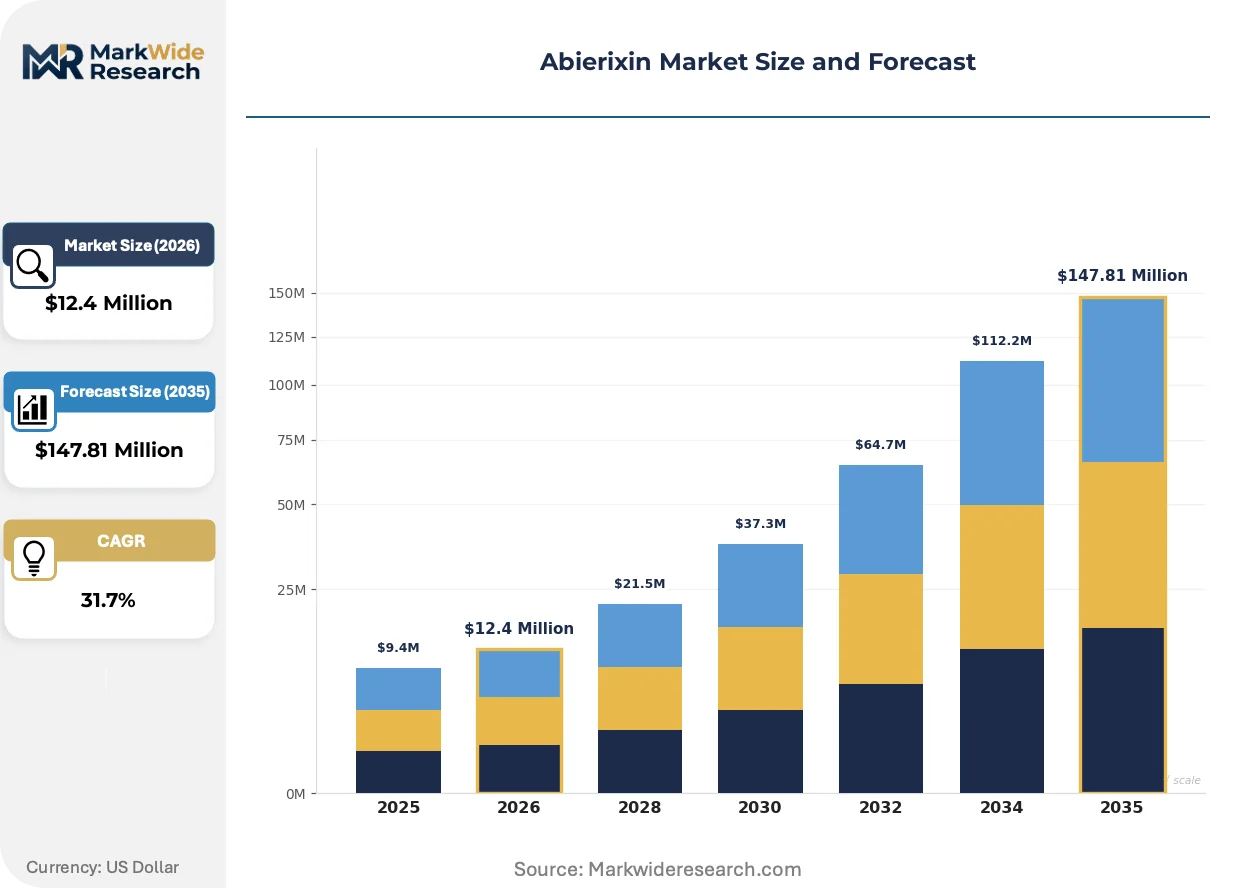
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $147.81 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Tablet, Capsule, Oral Suspension, Topical Gel Application: Immunotherapy, Oncology Treatment, Inflammatory Disorders, Autoimmune Conditions, Allergic Reactions End User: Specialty Clinics, Research Laboratories, Diagnostic Centers, Home Healthcare Providers, Pharmaceutical Companies Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral, Transdermal |
| Companies Covered | AbbVie, Pfizer, Johnson & Johnson, Merck & Co., Novartis, Roche, Bristol Myers Squibb, Sanofi, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abierixin Market Trends and Innovations
Abierixin manufacturing and delivery modalities are converging toward patient-centric formats that reduce hospital dependency while preserving therapeutic efficacy. Three developments dominate competitive positioning.
Continuous bioprocessing technology is hybridizing batch manufacturing economics with single-use system flexibility. Biopharmaceutical firms in Germany and Switzerland adopt perfusion bioreactor platforms to compress cell culture duration from weeks to days. This convergence is hybridizing capital intensity structures, enabling mid-scale facilities to achieve productivity parity with legacy stainless-steel installations.
EMA's Medical Device Regulation reclassification affects abierixin companion diagnostic co-development pathways. In vitro diagnostic-therapeutic bundling now triggers joint technical documentation requirements that extend marketing authorization timelines. European oncology protocols face compressed launch windows as firms restructure regulatory submission strategies to accommodate parallel device-drug reviews.
Home infusion service models displace hospital-based administration for stable autoimmune cohorts. United States specialty pharmacy networks deploy nurse-administered subcutaneous protocols that bypass infusion center capacity constraints. Rheumatology practices in Texas and Florida pilot direct-to-patient cold-chain delivery, shifting site-of-care economics toward ambulatory settings.
Abierixin Market Segmentation
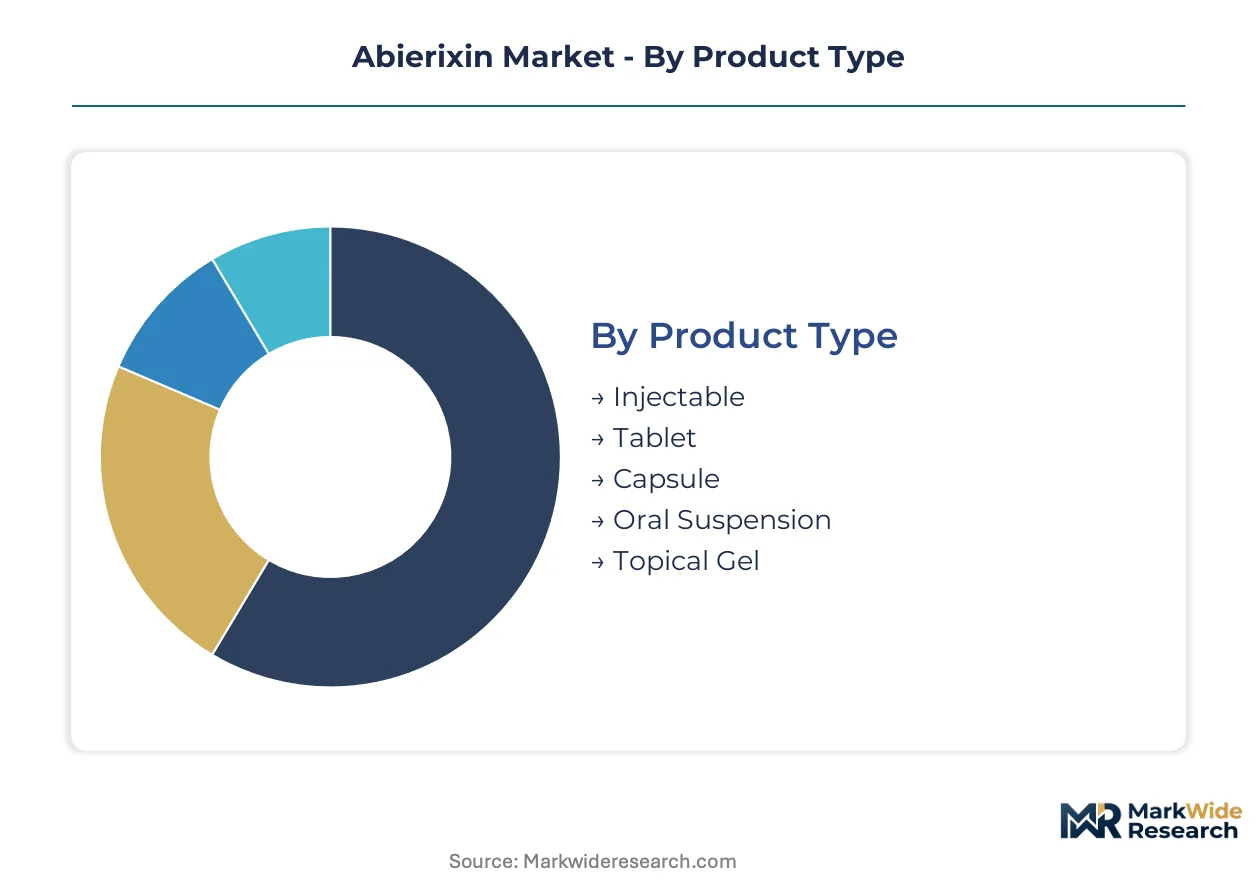
Abierixin market segmentation reveals divergent margin structures across administration formats and care settings. Injectable formulations command premium reimbursement through hospital-based protocols, while oral suspensions unlock pediatric access pathways. Companion diagnostic bundling concentrates profitability in specialty clinic networks.
Product Type:
After-sales service intensity varies sharply across abierixin formats, with parenteral products requiring cold-chain logistics support and formulation stability monitoring that oral alternatives do not demand.
- Injectable:Sterile aqueous solutions packaged in single-use vials or prefilled syringes with strict endotoxin limits below 0.25 EU per milligram. Demand concentrates in United States infusion centers where checkpoint inhibitor combination protocols drive administration volume; reimbursement tiers favor hospital-based parenteral delivery over ambulatory alternatives.
- Oral Suspension:Liquid formulations with bioavailability enhancement excipients designed for pediatric and geriatric populations unable to tolerate injections. Japan and South Korea regulatory pathways are accelerating non-invasive delivery development; palatability engineering and stability testing create higher post-launch service burdens than solid oral formats.
- Tablet:Compressed solid dosage forms with enteric coatings to protect acid-labile abierixin moieties.
- Capsule:Gelatin or HPMC shells containing granulated or powdered active pharmaceutical ingredients.
- Topical Gel:Semisolid preparations for localized inflammatory dermatologic indications with limited systemic exposure.
Injectable holds the largest share; momentum sits with oral suspension.
Application:
Cost tier stratification separates immunotherapy protocols with companion diagnostic requirements from primary-care inflammatory disorder management.
- Immunotherapy:Checkpoint inhibitor combination therapies requiring precision cytokine modulation through abierixin-mediated signaling interruption. Oncology infusion centers in Germany and Switzerland concentrate demand; FDA breakthrough therapy designation compresses development timelines for refractory indications.
- Inflammatory Disorders:Broad prescriber bases in rheumatology and gastroenterology settings compete on volume rather than margin. United States specialty clinic networks capture patient access through prior authorization management; broader indication labels strain manufacturing capacity allocation across lower-revenue cohorts.
- Oncology Treatment:Solid tumor and hematologic malignancy protocols with biomarker-driven patient selection.
- Autoimmune Conditions:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease maintenance therapy.
- Allergic Reactions:Acute hypersensitivity management with shorter treatment durations.
Immunotherapy commands the deepest margins; inflammatory disorders deliver the highest prescription volumes.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies and specialty clinics operating formal tender processes that home healthcare providers cannot replicate.
- Specialty Clinics:United States infusion center networks with captive patient populations and integrated pharmacy benefit management. Texas and Florida rheumatology practices pilot direct-to-patient cold-chain delivery; site-of-care economics shift toward ambulatory settings as nurse-administered subcutaneous protocols mature.
- Pharmaceutical Companies:Contract manufacturing organizations and originator firms sourcing active pharmaceutical ingredients for internal formulation or external supply. Swiss and German API producers control critical recombinant protein expression capacity; single-source concentration creates supply security vulnerabilities.
- Research Laboratories:Academic and commercial investigators conducting preclinical and clinical abierixin studies.
- Diagnostic Centers:Companion diagnostic testing facilities co-located with therapeutic administration.
- Home Healthcare Providers:Nurse-administered subcutaneous protocols for stable autoimmune cohorts.
Specialty clinics anchor current revenue; home healthcare is expanding most quickly.
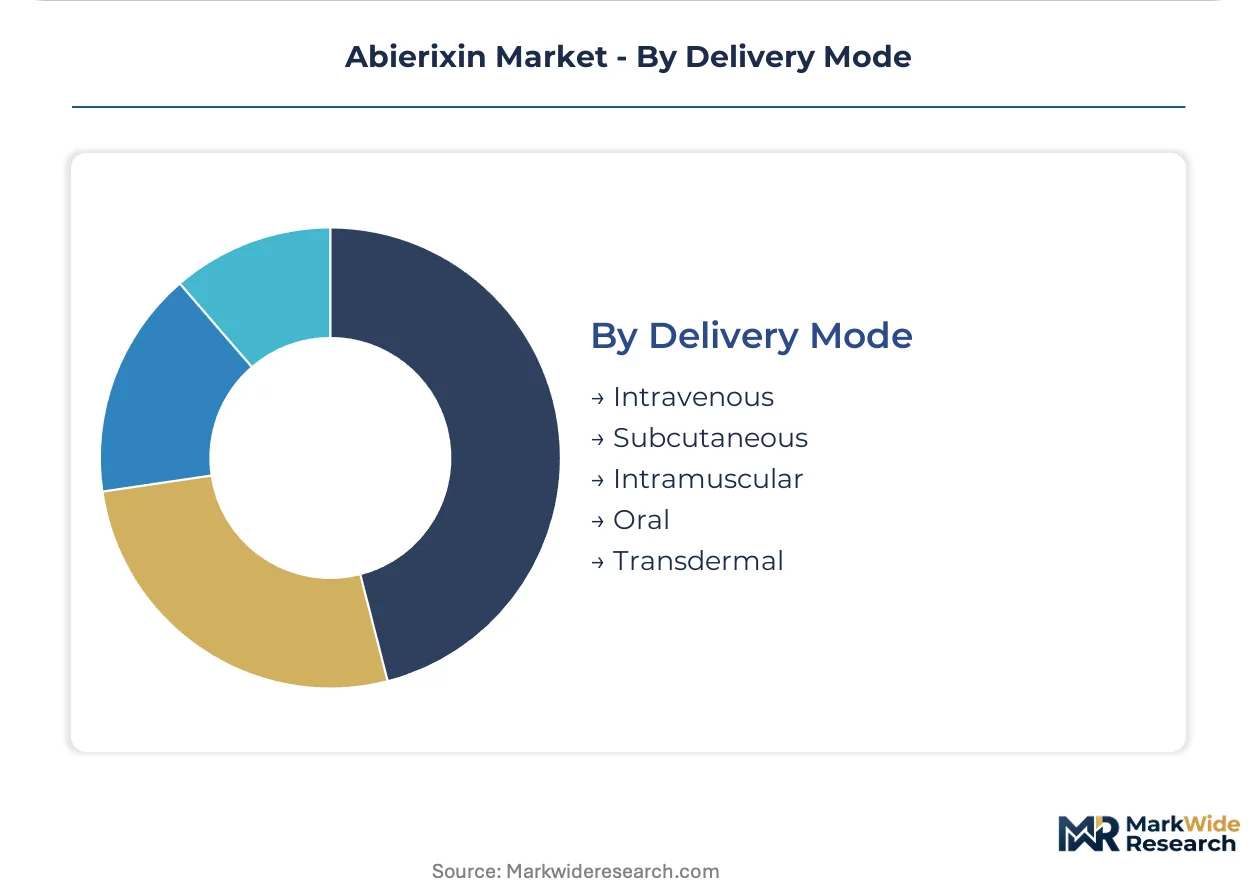
Delivery Mode:
Supply concentration in parenteral formats reflects manufacturing complexity gradients that oral and transdermal alternatives bypass.
- Intravenous:Direct vascular administration requiring infusion center infrastructure and nursing supervision. Hospital-based capacity constraints in United States metropolitan markets create access bottlenecks; cold-chain logistics integration determines competitive positioning among distribution networks.
- Subcutaneous:Tissue-layer injection enabling self-administration or home nursing protocols for stable patients. Prefilled pen device development concentrates in Basel and Boston bioprocess engineering clusters; patient training and adherence monitoring generate recurring service revenue streams.
- Intramuscular:Depot formulations for sustained release in specific autoimmune indications.
- Oral:Gastrointestinal absorption with first-pass metabolism considerations.
- Transdermal:Permeation-enhanced patches for localized or systemic delivery.
Intravenous dominates current administration volume; subcutaneous shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan and South Korea demonstrate the lowest price elasticity for abierixin formulations, while procurement teams in India and Brazil operate under stringent cost constraints that compress margin structures for originator products.
United States
FDA breakthrough therapy designations compress clinical development timelines for refractory autoimmune indications, drawing AbbVie and Bristol Myers Squibb to concentrate immunology infrastructure in Greater Boston and the Research Triangle. Specialty clinic networks in Texas and Florida pilot direct-to-patient cold-chain delivery models that bypass traditional infusion center bottlenecks.
Germany
EMA centralized marketing authorization procedures coordinate European market access pathways from Frankfurt and Munich regulatory hubs. Swiss and German contract manufacturing organizations control critical recombinant protein expression capacity, creating single-source concentration risks for active pharmaceutical ingredient supply.
Switzerland
Swissmedic enforces Current Good Manufacturing Practice standards that shape batch release timelines for Basel-cluster bioprocess engineering facilities. Perfusion bioreactor platforms in the Lake Geneva region compress mammalian cell culture duration from weeks to days, enabling mid-scale productivity parity with legacy stainless-steel installations.
Japan
PMDA accelerated review pathways for pediatric and geriatric oral suspension formulations drive non-invasive delivery development in Tokyo-Osaka pharmaceutical corridors. Palatability engineering and stability testing create higher post-launch service burdens than solid oral formats, concentrating formulation expertise in Kansai region R&D centers.
South Korea
MFDS regulatory harmonization with FDA standards enables parallel submission strategies for biologic therapeutic candidates developed in Seoul Capital Area clusters. Biopharmaceutical firms leverage this convergence to compress market entry schedules for checkpoint inhibitor combination protocols targeting regional oncology centers.
Abierixin Market Competitive Landscape
Integrated immunology platforms and precision bioprocessing specialists split the market between volume-driven consolidation and niche technology differentiation. Large-cap pharmaceutical firms anchor positions through captive cold-chain logistics and centralized compounding partnerships, while mid-scale innovators compete on continuous manufacturing adoption and pediatric formulation expertise. The dominant competitive moves involve backward integration into mammalian cell culture capacity and strategic bundling of companion diagnostic services at point-of-care settings.
Among North American-based originators, AbbVie exemplifies the integrated immunology archetype through patient access program infrastructure, while Bristol Myers Squibb occupies a position defined by centralized quality control partnerships. Pfizer represents the logistics-anchored tier with distribution network dominance in parenteral formats.
| Leading Market Players |
|---|
| AbbVie |
| Pfizer |
| Johnson & Johnson |
| Merck & Co. |
| Novartis |
| Roche |
| Bristol Myers Squibb |
| Sanofi |
| AstraZeneca |
| Others |
Pricing and Supply Chain Analysis
Single-source API concentration in Swiss and German contract manufacturing organizations creates simultaneous pricing power asymmetries and supply security vulnerabilities that stratify procurement tiers across hospital networks and specialty clinic buyers. Mammalian cell culture capacity constraints propagate through endotoxin testing bottlenecks, compressing margin structures for originator firms while inflating after-sales service premiums for cold-chain logistics providers.
Pricing Analysis
After-sales service revenue from companion diagnostic bundling and cold-chain logistics support drives lifetime value capture beyond unit sales. Injectable formulations command premium-mid-economy pricing differentiation based on endotoxin certification tiers and infusion center administration requirements, while oral suspensions trade at lower unit prices with higher palatability engineering service attachments. Pricing pressure stems from biosimilar interchangeability uncertainty compressing originator defense windows. Hospital procurement committees exhibit lowest price sensitivity given captive patient populations and prior authorization control, whereas home healthcare providers face acute cost compression from Medicare reimbursement constraints.
Supply Chain Analysis
Upstream serum and recombinant protein expression media feed from bovine supply chains concentrated in United States, New Zealand, and Australian agricultural regions with spongiform encephalopathy screening protocols. Critical active pharmaceutical ingredient production rests on perfusion bioreactor platforms in Basel and Boston clusters, with single-use system manufacturing concentrated in German and Swiss precision engineering facilities. Tariff exposure on Chinese-sourced filtration membranes and chromatography resins creates input cost volatility. Distribution runs through integrated cold-chain networks anchored by specialty pharmacy partnerships and direct-to-patient delivery pilots in Texas and Florida rheumatology markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate across pediatric formulation development and home infusion service models as patient-centric delivery formats displace hospital-dependent administration protocols. Precision cytokine modulation protocols create niche entry points for mid-scale innovators with continuous bioprocessing capabilities.
For Market Incumbents: Insulate market position through backward integration into mammalian cell culture capacity in Basel and Boston bioprocess engineering clusters, securing captive supply against Swiss and German API concentration risks. Expand centralized compounding partnerships to control formulation quality at United States infusion centers, defending margin pools from biosimilar substitution threats. Prioritize FDA breakthrough therapy designation maintenance to compress competitor development timelines. For New Entrants and Emerging Players: Build out pediatric oral suspension expertise targeting Japan and South Korea regulatory pathways where palatability engineering creates defensible formulation moats. Home healthcare subcutaneous delivery formats represent the most penetrable segment given nurse-administered protocol expansion in Texas and Florida rheumatology practices. Pursue companion diagnostic bundling strategies to capture recurring service revenue streams at point-of-care settings. For Investors and Strategic Acquirers: FDA biosimilar interchangeability designation timelines reshape the acquisition landscape by determining generic substitution economics and originator defense window durations. Long-term viability favors platforms with integrated cold-chain logistics and continuous bioprocessing technology adoption. Target mid-scale innovators with perfusion bioreactor capabilities and pediatric formulation pipelines. Monitor EMA Medical Device Regulation reclassification proceedings as the signal indicating joint technical documentation burden shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Perfusion bioreactor platforms in Basel compress cell culture duration from weeks to days. |
| Companion Diagnostic Bundling | Biologic therapeutic protocols create service revenue streams at oncology infusion centers. |
| Pediatric Oral Suspension Development | PMDA accelerated review pathways in Japan drive non-invasive delivery format innovation. |
| Home Infusion Service Expansion | Direct-to-patient cold-chain delivery pilots in Texas bypass hospital capacity constraints. |
| Cold-Chain Logistics Integration | In-house parenteral distribution networks capture margin from specialty pharmacy partnerships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down manufacturer capacity assessments were triangulated to reconcile volume estimates.
Forecast inputs span administration route, patient population age cohort, regional regulatory cluster, and treatment line positioning across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Biosimilar approval trajectories and checkpoint inhibitor combination protocol expansion rates served as primary demand-side variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated bioprocessing specialists or accelerated FDA interchangeability designations would shift outcomes materially. Cross-checking against CMS Medicare reimbursement rate announcements and EMA centralized procedure timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Bio-Based Aromatics Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Croscarmellose Sodium Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
North America Perms and Relaxants Market