
 Coconut Derived Surfactants Market | 2026-2036
Coconut Derived Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Derived Surfactants Market Outlook
Southeast Asian oleochemical producers is shifting capacity toward higher-value surfactant derivatives as crude coconut oil price volatility persists. BASF leverages its integrated feedstock partnerships across Malaysia and Indonesia to secure lauric acid supply. Croda International differentiates through specialty ester chemistry for premium personal care grades. Stepan Company anchors North American distribution with dedicated alkoxylation capacity for coconut-derived ethoxylates.
Coconut derived surfactants comprise surface-active agents synthesized from lauric-rich coconut oil fractions, typically containing C12-C14 alkyl chains that deliver foaming, wetting, and emulsifying functions across aqueous systems. These molecules undergo sulfonation, ethoxylation, or quaternization to yield anionic, non-ionic, or cationic variants with tailored hydrophilic-lipophilic balance values between 10 and 16. Non-ionic surfactants occupy the broadest application footprint due to their compatibility with hard water and mildness profiles in personal care. Liquid formulations dominate household cleaning channels, while powder and granule forms sustain industrial and textile processing volumes where dosing precision and storage stability matter.
REACH registration requirements in Europe and EPA Safer Choice criteria in the United States are elevating the cost of petrochemical surfactant alternatives while rewarding biobased feedstock documentation. BIS certification mandates in India for detergent-grade surfactants are tightening impurity thresholds for 1,4-dioxane and free oil content. Stakeholders must monitor how evolving ECHA restrictions on ethoxylated nonylphenols redirect formulation investment toward coconut-derived substitutes.
Market Dynamics
REACH compliance deadlines are forcing European formulators to abandon petrochemical surfactants, redirecting procurement toward lauric acid derivatives with verified biodegradability documentation. Southeast Asian oleochemical clusters now control the critical C12-C14 feedstock pipeline.
Growth Catalysts
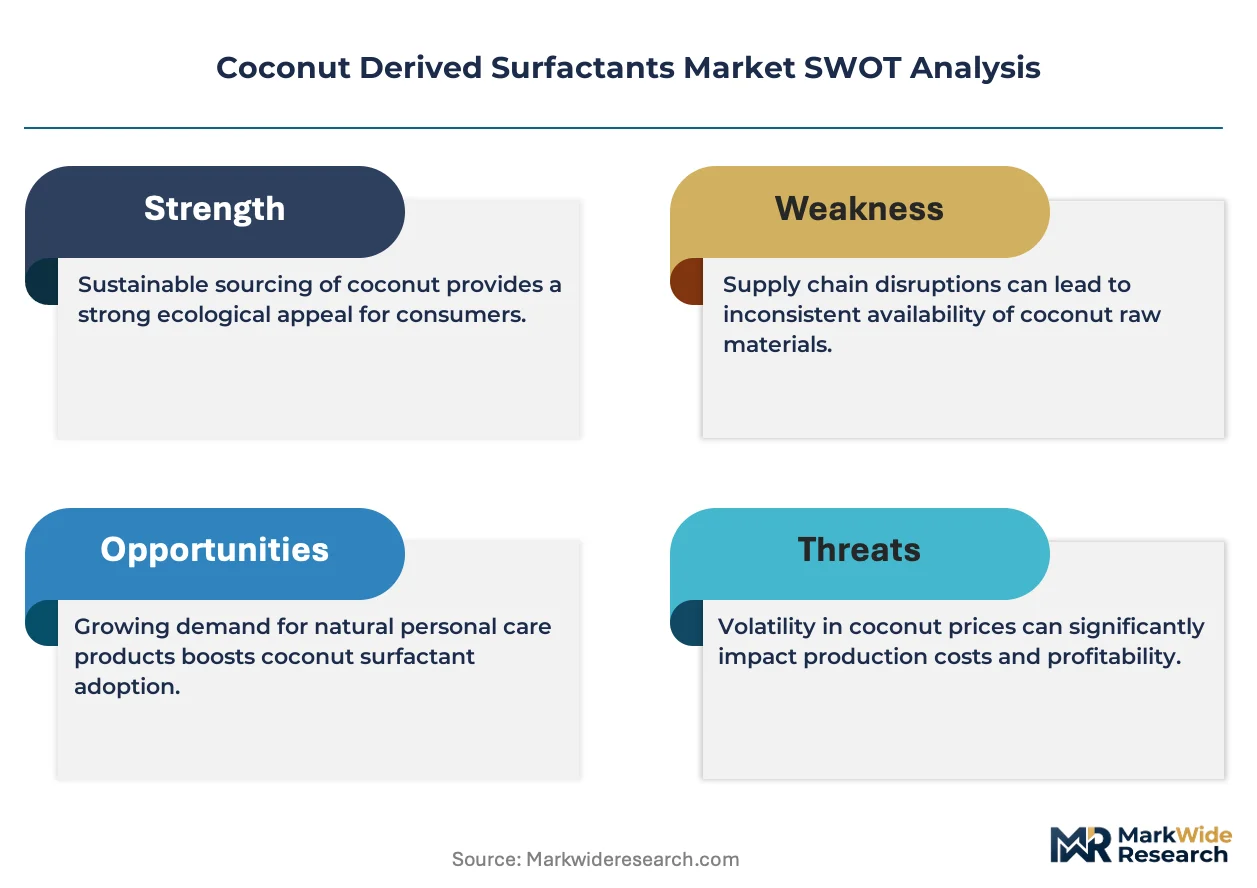
- REACH Registration Mandates:ECHA's tightened biodegradability thresholds disqualify synthetic alternatives in European personal care formulations.
- Hard Water Compatibility:Non-ionic coconut ethoxylates penetrate emerging markets with untreated municipal water supplies.
- Southeast Asian Processing Concentration:Indonesian and Philippine oleochemical infrastructure secures captive lauric acid supply for sulfonation and quaternization.
Market Restraints
- Crude Coconut Oil Volatility:Weather-driven harvest fluctuations in Mindanao and Sulawesi transmit directly to lauric acid contract pricing.
- Monoculture Feedstock Risk:Over 70 percent of global C12-C14 supply originates from two archipelagic nations with shared climate exposure.
- Ethoxylation Impurity Limits:BIS certification for Indian detergent grades enforces sub-10 ppm 1,4-dioxane thresholds that legacy equipment cannot meet.
Strategic Opportunities
- EPA Safer Choice Certification:Biobased surfactant documentation unlocks federal procurement preference in institutional cleaning contracts.
- Textile Wet Processing:Coconut-derived cationics penetrate technical fabric finishing where petrochemical quats face discharge scrutiny.
- Direct-to-Compounder Distribution:Bypassing traditional chemical distributor markups through dedicated ASEAN-to-EU logistics corridors.
Industry Challenges
- Sulfonation Engineering Shortage:Specialized reactor design expertise for continuous SO3 sulfonation concentrates among retired German and Japanese engineering consultancies.
- Multi-Jurisdiction Registration Burden:Parallel REACH, EPA, and BIS dossier preparation stretches regulatory affairs teams across incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Derived Surfactants Market |
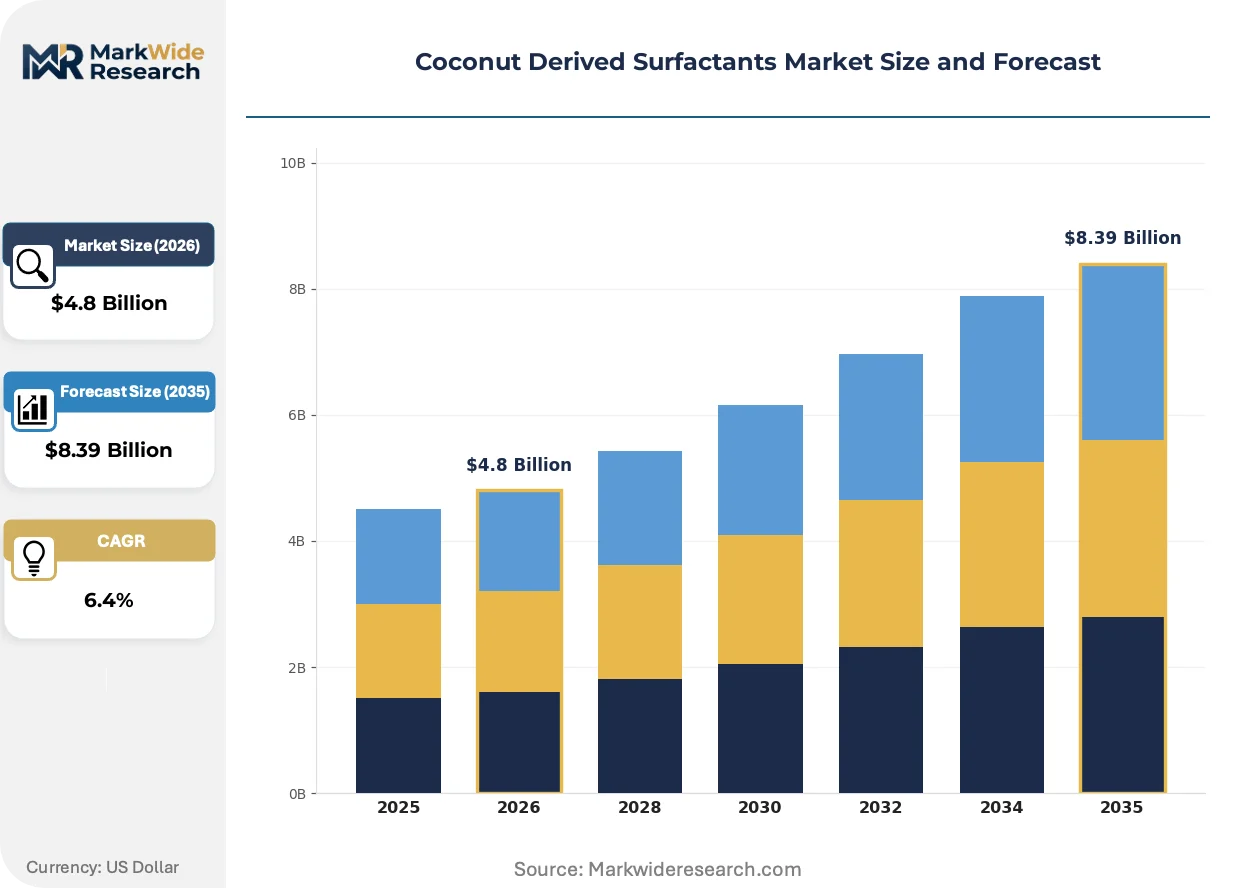
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Surfactants, Cationic Surfactants, Non-Ionic Surfactants, Amphoteric Surfactants Application: Personal Care, Household Cleaning, Industrial Cleaning, Textile Processing End User: Cosmetics Manufacturers, Detergent Producers, Cleaning Product Companies, Textile Manufacturers Form: Liquid, Powder, Paste, Granule |
| Companies Covered | BASF, Kao Corporation, Croda International, AkzoNobel, The Dow Chemical Company, Stepan Company, Evonik Industries, Clariant, Galaxy Surfactants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Derived Surfactants Market Strategic Shifts
Enzymatic interesterification is rewriting process economics for coconut-derived surfactant precursors. Formulators now demand chain-length specificity that chemical transesterification cannot deliver.
Enzymatic transesterification platforms is rewriting the cost structure for high-purity lauric-myristic fractions. Specialty personal care compounders in France and Germany are adopting these biocatalytic routes for premium emulsifier grades. The technology is rewriting margin allocation between feedstock processors and finished surfactant manufacturers by collapsing traditional fractionation steps.
EPA Safer Choice criteria now mandate full supply chain transparency for biobased content claims in institutional cleaning products. Formulators must submit carbon-14 testing documentation proving petrochemical contamination below 5 percent. North American household product manufacturers are responding by qualifying dedicated coconut-derived ethoxylate supply lines with segregated handling protocols.
Certification-driven specification is displacing price-first procurement in European personal care channels. Brand owners now require ECHA-compliant biodegradability dossiers before contract award, not after delivery. German and Dutch cosmetics manufacturers are consolidating supplier panels to those with in-house analytical capabilities for regulatory pre-certification.
Coconut Derived Surfactants Market Segmentation
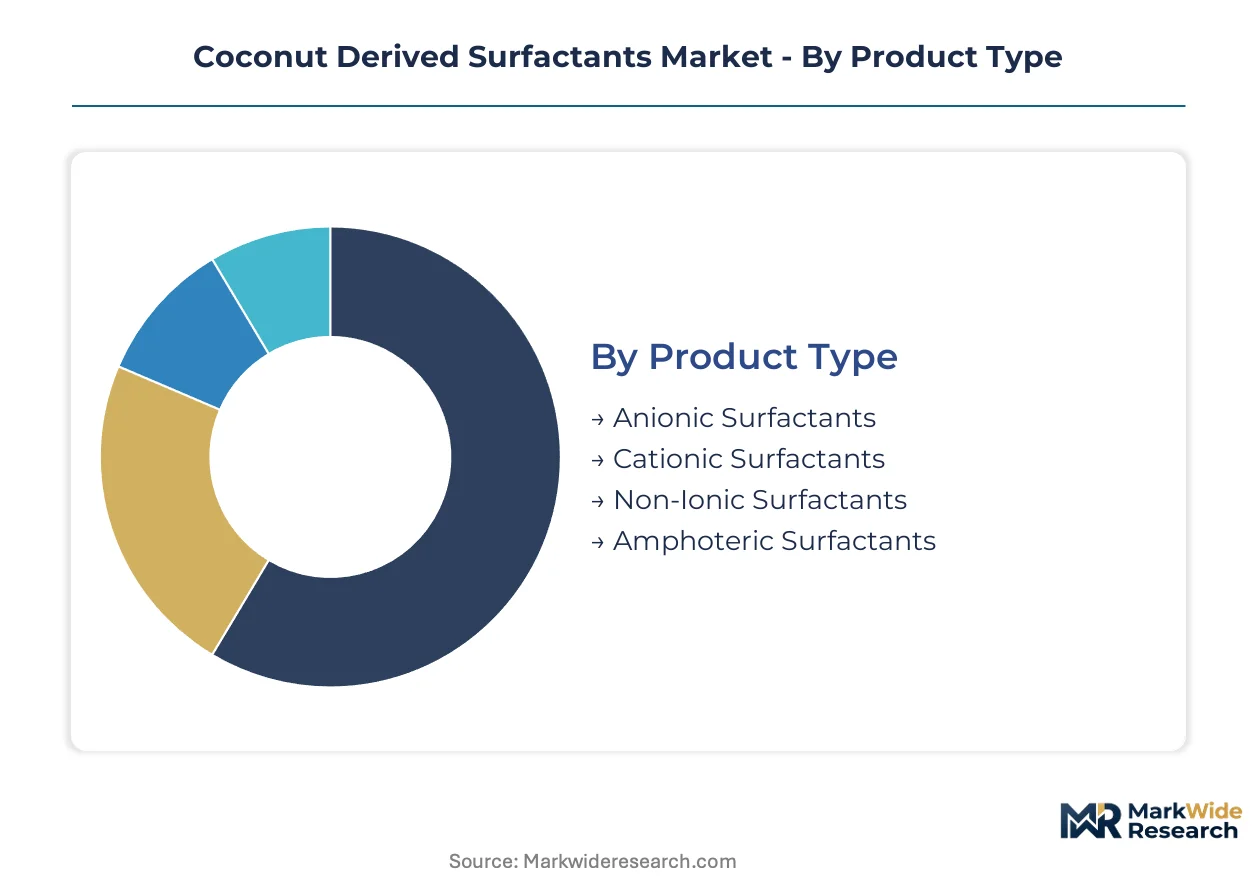
Surfactant selection in this market hinges on hydrophilic-lipophilic balance precision and downstream compatibility requirements. Formulators navigate trade-offs between foaming performance, biodegradability documentation, and regulatory pre-certification timelines across four critical dimensions.
Product Type:
Standalone surfactant systems dominate commodity applications, while embedded multi-functional blends penetrate premium personal care where formulation complexity rewards specificity.
- Anionic Surfactants:Sodium lauryl sulfate and sodium laureth sulfate derivatives deliver high-foaming profiles with C12-C14 alkyl chain specificity. Detergent producers in India and Southeast Asia anchor procurement volumes here, though BIS certification mandates for 1,4-dioxane content below 10 ppm strain legacy sulfonation infrastructure.
- Non-Ionic Surfactants:Coconut-derived ethoxylates with tailored ethylene oxide chain lengths provide hard water tolerance and mildness profiles unmatched by ionic alternatives. Cosmetics manufacturers in France and Germany concentrate demand for these grades, driven by REACH biodegradability thresholds that disqualify petrochemical alternatives.
- Cationic Surfactants:Quaternized lauric derivatives serve fabric softening and antimicrobial applications where cationic charge density matters.
- Amphoteric Surfactants:Betaine chemistry bridges anionic and cationic domains for mild personal care formulations.
Volume placements concentrate in Non-Ionic Surfactants; the faster expansion belongs to Amphoteric Surfactants.
Application:
Cost-tier stratification separates commodity cleaning applications from performance-critical personal care segments where specification premiums justify dedicated supply lines.
- Personal Care:Premium emulsifier and foaming agent grades demand enzymatic transesterification-derived lauric-myristic fractions with chain-length specificity. German and Dutch cosmetics manufacturers consolidate supplier panels to those with in-house ECHA-compliant biodegradability dossiers.
- Household Cleaning:Liquid dishwashing and laundry formulations absorb the largest absolute volumes of anionic and non-ionic grades. Indonesian and Philippine oleochemical clusters feed this channel through established sulfonation and ethoxylation infrastructure.
- Industrial Cleaning:Heavy-duty degreasers and metalworking fluids require higher active-matter concentrations.
- Textile Processing:Wetting agents and dye-leveling auxiliaries exploit coconut-derived compatibility with discharge scrutiny.
Household Cleaning commands the largest volume footprint; Personal Care generates the steepest margin expansion.
End User:
Customer-type fragmentation splits between brand-owning formulators with regulatory affairs depth and toll manufacturers dependent on pre-certified raw material supply.
- Cosmetics Manufacturers:Premium personal care compounders in France and Germany specify enzymatic-route esters with carbon-14 documentation proving biobased content above 95 percent.
- Detergent Producers:Mass-market formulators prioritize lauric acid supply security over specialty functionality, locking in long-term contracts with Malaysian and Indonesian oleochemical majors.
- Cleaning Product Companies:Institutional and industrial channels demand EPA Safer Choice certification for federal procurement eligibility.
- Textile Manufacturers:Technical fabric finishers seek cationic quats with verified biodegradability under OECD test protocols.
Detergent Producers anchor absolute volume; Cosmetics Manufacturers drive specification innovation fastest.
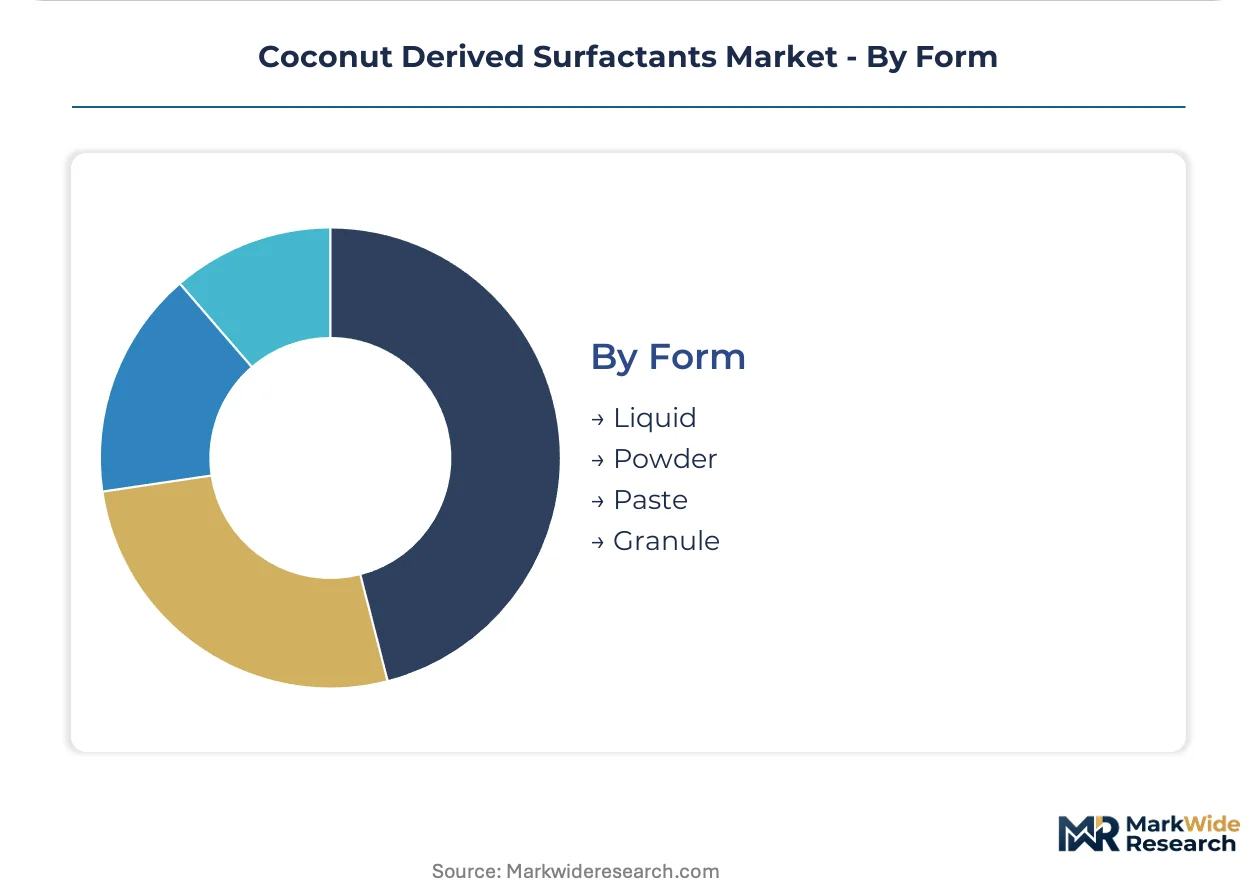
Form:
Supply-chain configuration separates liquid bulk deliveries for high-throughput channels from solid forms serving precision-dosing and storage-stability requirements.
- Liquid:Bulk tanker deliveries dominate household cleaning channels where dilution-to-ship economics favor aqueous concentrates. North American alkoxylation capacity supports regional ethoxylate supply.
- Powder:Spray-dried granules sustain detergent powder formulations across Indian and Southeast Asian markets.
- Paste:Semi-solid concentrates serve niche personal care compounding where viscosity control matters.
- Granule:Free-flowing solids enable precise dosing in industrial and textile processing where automated handling systems predominate.
Liquid forms capture the dominant volume share; Granule formats gain share fastest in automated industrial settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mindanao and Sulawesi plantations anchor raw material flows, while processing clusters in Southeast Asia, Europe, and North America convert lauric fractions into specification-grade surfactants. Regulatory divergence across jurisdictions is fragmenting formulation standards and procurement patterns.
Indonesia
North Sumatran oleochemical parks absorb the largest share of domestic crude coconut oil for sulfonation and ethoxylation. The country's national standards body enforces tightening purity thresholds for 1,4-dioxane in detergent-grade outputs. Medan-based processors are expanding dedicated alkoxylation lines to serve EU-bound personal care exports.
Philippines
Davao Region plantations supply high-lauric acid crude to integrated processors in Cebu and Manila. Biodiversity conservation mandates in coconut-growing provinces are constraining monoculture expansion. Quezon City formulators are qualifying enzymatic-route esters for premium cosmetics contracts bound for France and Germany.
Germany
REACH compliance deadlines are disqualifying petrochemical surfactants in personal care formulations. ECHA biodegradability documentation requirements are consolidating supplier panels to pre-certified vendors. Cologne and Hamburg cosmetics manufacturers are locking in long-term contracts with Southeast Asian oleochemical majors for lauric acid supply security.
United States
EPA Safer Choice criteria are elevating biobased surfactant preference in federal institutional cleaning procurement. Carbon-14 testing mandates for biobased content claims are forcing supply chain segregation protocols. Stepan Company's North American alkoxylation capacity anchors regional ethoxylate supply for household product manufacturers.
India
BIS certification mandates for detergent-grade surfactants are enforcing sub-10 ppm 1,4-dioxane thresholds. Gujarat and Maharashtra processing clusters are retrofitting sulfonation reactors to meet impurity limits. Mumbai-based detergent producers are prioritizing lauric acid supply security through long-term contracts with Indonesian suppliers.
Coconut Derived Surfactants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty ester chemistry and enzymatic processing routes. The vendor base stratifies between integrated oleochemical majors with captive feedstock and formulation specialists with regulatory pre-certification depth. Three archetypes dominate: Southeast Asian processors with upstream plantation control, European compounders with ECHA dossier expertise, and North American distributors with alkoxylation infrastructure. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure lauric acid supply lines and bypass traditional distributor markups.
Within the integrated processing tier, BASF and Croda International exemplify contrasting strategic positions. BASF leverages Malaysian and Indonesian feedstock partnerships for lauric acid supply security. Croda International occupies a specialty chemistry position through premium personal care grades. Stepan Company anchors North American distribution with dedicated alkoxylation capacity. These three entities represent the spectrum from commodity scale to specification-driven value capture.
| Leading Market Players |
|---|
| BASF |
| Kao Corporation |
| Croda International |
| AkzoNobel |
| The Dow Chemical Company |
| Stepan Company |
| Evonik Industries |
| Clariant |
| Galaxy Surfactants |
| Others |
Value Chain & Pricing Dynamics
Enzymatic transesterification platforms are collapsing traditional fractionation economics while concentrating margin capture among processors with biocatalytic capabilities. This production-method transition simultaneously elevates cost structures for legacy sulfonation equipment and rewards Southeast Asian oleochemical clusters with integrated enzymatic capacity.
Pricing Analysis
Service-bundling separates specification-grade suppliers from commodity traders, with REACH-compliant biodegradability dossiers and carbon-14 testing documentation now standard in premium personal care contracts. Pricing stratifies across enzymatic-route specialty esters, standard sulfonated anionics, and economy-grade ethoxylates with variable 1,4-dioxane profiles. Cost compression in standard anionic tiers is intensifying as Indian BIS certification mandates force reactor retrofits. Detergent producers in Southeast Asia exhibit highest price sensitivity; German cosmetics manufacturers accept specification premiums for pre-certified supply.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Philippine lauric acid supply, where over two-thirds of global C12-C14 feedstock originates from archipelagic plantations with shared climate exposure. The supply chain draws from crude coconut oil harvests in Mindanao and Sulawesi, sulfonation catalysts from German engineering consultancies, and ethoxylation capacity concentrated in Malaysia and Indonesia. Commodity price volatility in agricultural feedstocks represents the dominant structural risk. Distribution runs through ASEAN-to-EU logistics corridors for personal care grades and established chemical distributor networks for commodity detergent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration requirements function as a cost-of-compliance moat, elevating capital barriers for surfactant producers lacking in-house ECHA dossier capabilities and consolidated supplier relationships.
For Market Incumbents: Anticipate margin pressure from enzymatic-route specialty entrants by securing captive lauric acid supply through Malaysian and Indonesian feedstock partnerships. Invest in continuous SO3 sulfonation reactor upgrades to meet tightening 1,4-dioxane thresholds under Indian BIS and EU REACH standards. Prioritize regulatory pre-certification capabilities as the primary defensive lever against emerging biocatalytic competitors. For New Entrants and Emerging Players: Begin with enzymatic transesterification platforms targeting premium personal care compounders in France and Germany who demand chain-length specificity for emulsifier grades. Exploit the white-space opportunity in EPA Safer Choice-certified institutional cleaning supply lines where carbon-14 documentation requirements disadvantage legacy petrochemical suppliers. Pursue direct-to-compounder distribution through dedicated ASEAN logistics corridors to bypass established distributor markups. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty ester chemistry platforms with enzymatic processing capabilities and pre-certified ECHA dossier libraries. Five-to-ten year viability favors processors with backward integration into Southeast Asian lauric acid supply rather than toll manufacturers dependent on spot feedstock markets. Watch for EPA Safer Choice procurement mandate expansion as the signal indicating accelerated biobased surfactant substitution in North American institutional channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lauric Acid Supply | BASF's Malaysian and Indonesian feedstock partnerships secure captive C12-C14 pipeline against harvest volatility. |
| Enzymatic Transesterification Capacity Addition | Biocatalytic routes collapse fractionation steps and capture margin from premium personal care compounders. |
| REACH Pre-Certification Investment | ECHA-compliant biodegradability dossiers consolidate supplier panels and disqualify unprepared competitors. |
| Direct-to-Compounder Distribution | Dedicated ASEAN-to-EU logistics corridors bypass traditional chemical distributor markups in personal care channels. |
| EPA Safer Choice Qualification | Carbon-14 testing protocols unlock federal procurement preference in institutional cleaning contracts. |
Study Parameters
Document review covered customs and trade data from Indonesian and Philippine export authorities, ECHA registration dossiers, EPA Safer Choice certified product listings, and BIS certification records, complemented by interviews with oleochemical plant managers in Medan and Davao, procurement leads at European cosmetics manufacturers, and distribution channel partners in Hamburg and Rotterdam. Primary fieldwork with sulfonation engineering consultancies in Germany and Japan validated technical capacity assumptions. Secondary sources included SEC filings from listed surfactant producers, ACC and Cefic chemical industry reports, and OECD biodegradability test protocol documentation. Bottom-up capacity estimates triangulated against top-down demand modeling across personal care and household cleaning end-uses.
Segment-level outputs across the projection horizon reflect modeled interactions between product type tiers, application-grade specifications, end-user procurement sophistication, and physical form factors. The analytical framework incorporated enzymatic versus chemical processing route economics, regional regulatory cluster divergence under REACH and EPA frameworks, and lauric acid supply concentration patterns. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs included crude coconut oil harvest yield variability in Mindanao and Sulawesi, sulfonation reactor retrofit costs under tightening impurity standards, and carbon-14 testing adoption rates for biobased content verification.
Weather-driven harvest disruptions in Philippine and Indonesian coconut-growing regions, abrupt ECHA restrictions on ethoxylated alternatives, and enzymatic processing technology cost curves are the dominant revision risks that could shift trajectory materially. Forecasts reflect assumptions about regulatory enforcement continuity and biocatalytic platform scale-up economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Specialty Surfactants Market
Surfactants
Waxing Sponge Market
Surfactants
Cocamidopropyl Betaine Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Amino Silicone Oil Market
Surfactants
Cationic Surfactants Market
Surfactants
Dispersant Market
Surfactants
Disodium Laureth Sulfosuccinate Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Global Rhamnolipid Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Micellar Water Market
Surfactants
Secondary Alkane Sulfonate Market