
 Bitumen Emulsifier Market | 2026-2036
Bitumen Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen Emulsifier Market Analysis
A shortage of qualified asphalt chemists and emulsion formulation specialists is collapsing near-term production capacity at several regional blenders. Dow Chemical Company leverages its integrated ethylene oxide supply chain to control feedstock costs for cationic emulsifier grades. Nouryon anchors European supply through alkylamine derivative production at its Swedish and Dutch sites. Arkema Group competes on high-performance polyamide-based emulsifier architectures for polymer-modified binders.
Bitumen emulsifiers are surface-active agents, typically alkylamines or fatty acid derivatives, that reduce interfacial tension between bitumen and water to create stable colloidal suspensions with particle sizes below 10 microns; these emulsions enable cold-applied road binders, waterproofing membranes, and protective coatings without heating asphalt above 100°C. Cationic emulsifiers dominate volume because positively charged droplets adhere strongly to negatively charged aggregate surfaces, ensuring rapid break and early strength development in road bases. Anionic emulsifiers retain share in specific soil-stabilization and priming applications where slower setting tolerates extended workability windows.
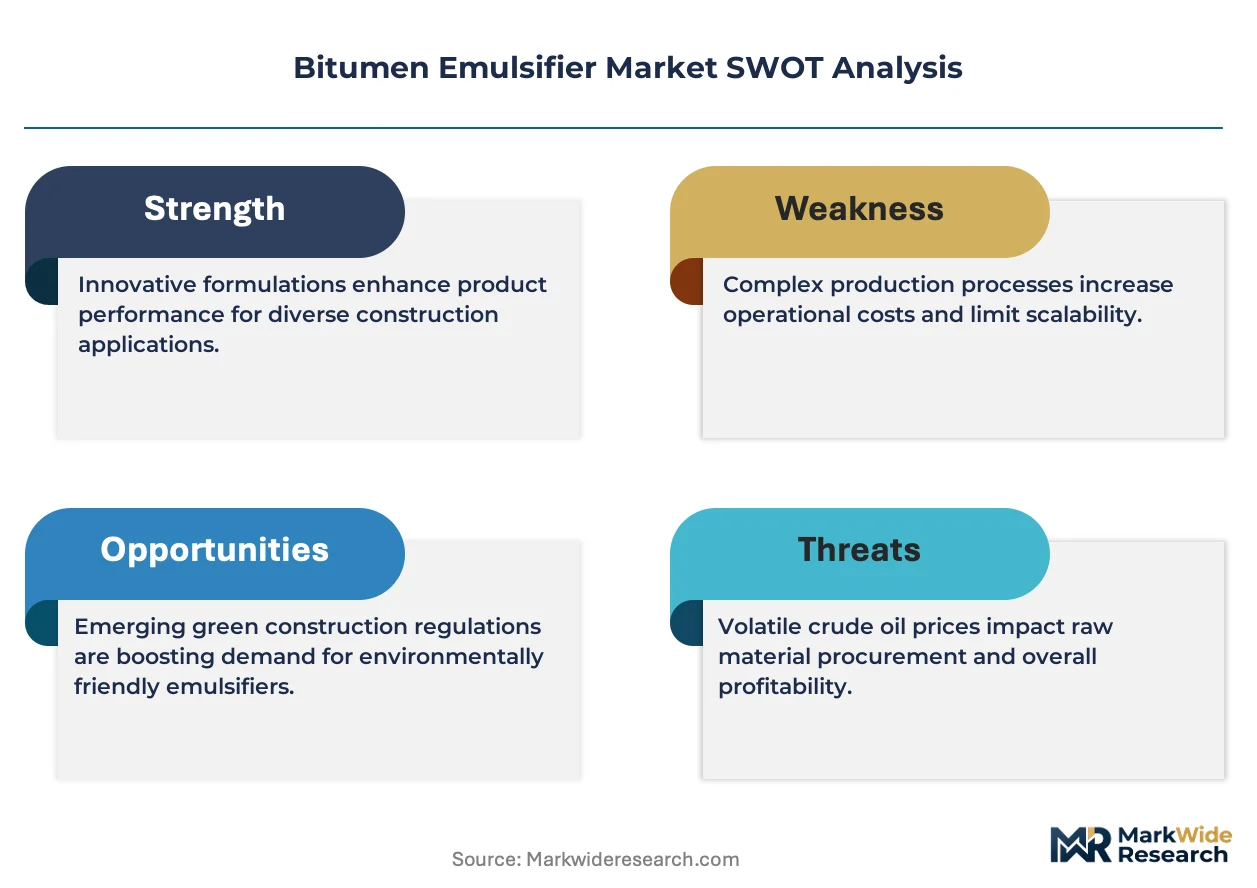
EPA stormwater regulations in the United States restrict volatile organic compound releases from hot-mix plants, indirectly expanding emulsion-based cold paving approvals. REACH registration requirements in Europe force emulsifier suppliers to document full toxicological profiles of amine-based surfactants, raising compliance barriers for import-dependent blenders. India's BIS certification for road emulsions mandates strict storage-stability testing that filters out low-grade formulations. Stakeholders must track bio-based emulsifier pilot programs and polymer-modified emulsion specifications to anticipate which chemistry platforms will capture the next wave of infrastructure specification changes.
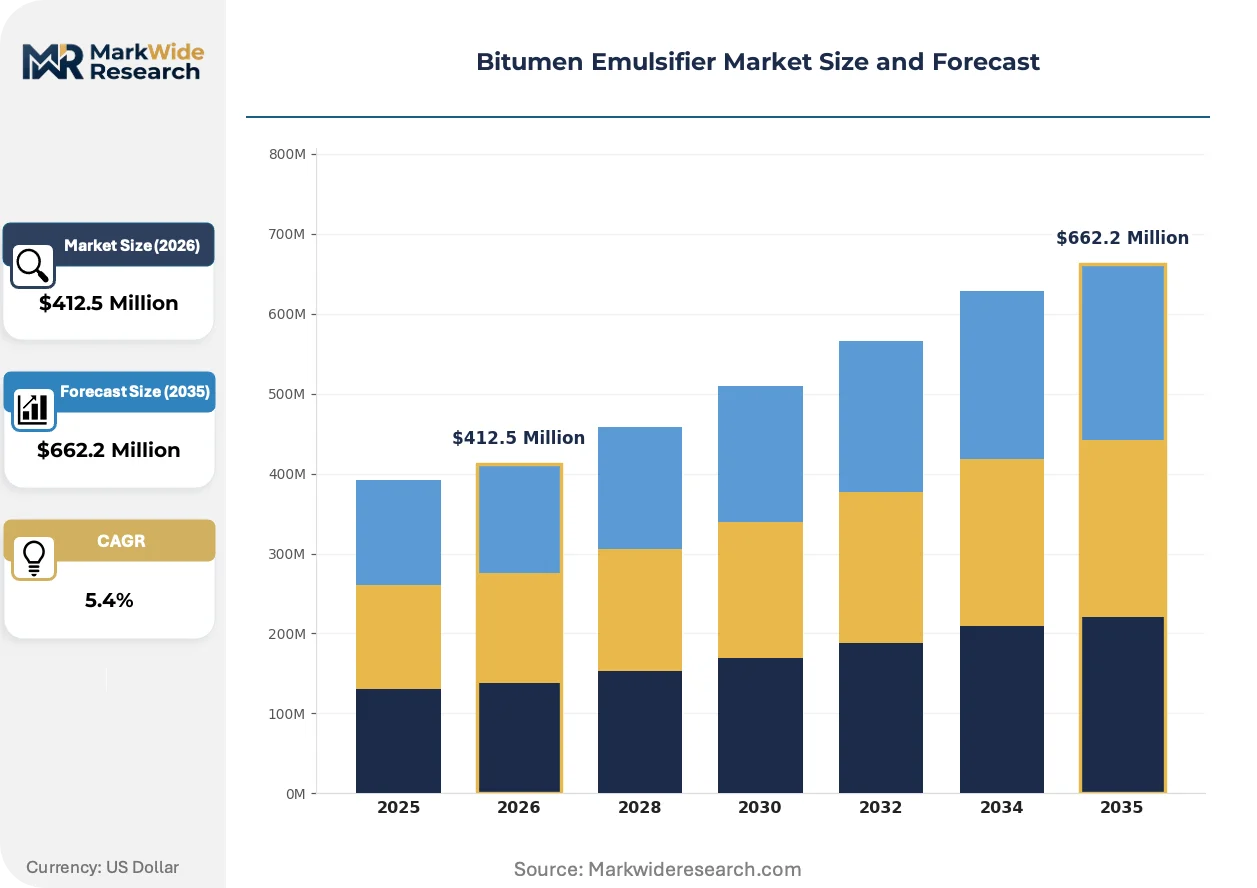
Market Dynamics
Formulation chemistry is pivoting toward bio-based surfactant architectures as REACH compliance costs and carbon-accounting pressures squeeze conventional alkylamine production economics across European supply chains.
Growth Catalysts
- EPA stormwater restrictions:Volatile organic compound limits at hot-mix asphalt plants in the United States are accelerating municipal approvals for cold-applied emulsion paving systems.
- Rural connectivity mandates:India's PMGSY rural road program and NHAI highway upgrades are concentrating bulk emulsifier procurement into standardized long-term supply contracts.
- Polymer-modified binder specifications:Polyamide-based emulsifier architectures are capturing specification share in high-performance waterproofing membranes and stress-absorbing pavement interlayers.
Market Restraints
- Ethylene oxide feedstock volatility:Integrated petrochemical producers control cationic emulsifier precursor costs, squeezing margin recovery at non-integrated regional blenders.
- REACH toxicological documentation:Full substance dossier requirements for amine-based surfactants are raising registration barriers for import-dependent European formulators.
- Hot-mix asphalt substitution resilience:Warm-mix additive technologies are preserving incumbent hot-lay installation economics in high-volume highway contracts.
Strategic Opportunities
- Bio-based surfactant pilots:Tall oil fatty acid derivatives and lignin-based emulsifiers are qualifying for EU Green Deal procurement preferences in Nordic infrastructure tenders.
- Soil stabilization vertical:Anionic emulsifier grades with extended workability windows are penetrating geotechnical ground improvement contracts in mining and airport runway expansion.
- Storage-stability certification arbitrage:India's BIS emulsion testing protocols are filtering out low-grade imports, creating captive demand for domestically certified production capacity.
Industry Challenges
- Asphalt chemist scarcity:Regional blending facilities face collapsed near-term production capacity as qualified emulsion formulation specialists retire without pipeline replacement.
- Multi-standard compliance complexity:Simultaneous adherence to EPA stormwater rules, REACH substance restrictions, and BIS stability mandates fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen Emulsifier Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic Emulsifiers, Anionic Emulsifiers, Non-Ionic Emulsifiers, Other Types Application: Road Construction, Waterproofing, Roof Coating, Oilfield Applications Technology: Mechanical Mixing, Chemical Emulsification, High-Pressure Homogenization, Other Methods End User: Construction Companies, Asphalt Producers, Municipalities, Contractors |
| Companies Covered | Dow Chemical Company, Nouryon, Arkema Group, Croda International Plc, Kao Corporation, BASF SE, Ingevity Corporation, AkzoNobel N.V., Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen Emulsifier Market Emerging Trajectories
Active reformulation of surfactant architectures around renewable feedstocks and performance-tailored polymer backbones is compressing legacy chemistry margins while opening specification pathways in premium application tiers.
Polyamide-modified bitumen emulsifiers are miniaturizing particle size distributions below five microns while maintaining storage stability. High-performance waterproofing contractors in Germany and Japan are specifying these grades for spray-applied membrane systems. The technology is miniaturizing application equipment requirements and enabling robotic deployment in confined infrastructure maintenance zones.
REACH registration deadlines for amine-based surfactants are forcing toxicological retesting of legacy emulsifier chemistries. European formulators are accelerating substitution timelines toward bio-based alternatives to avoid supply discontinuity. Polymer-modified binder specialists face compressed reformulation windows as downstream road authorities update national specification frameworks.
Specification-driven procurement is consolidating emulsifier supply relationships around certified domestic producers. Indian state public works departments are mandating BIS-certified storage stability as a contract precondition. Road construction contractors are shifting from spot-market sourcing to multi-year framework agreements with qualified blending facilities.
Bitumen Emulsifier Market Segmentation
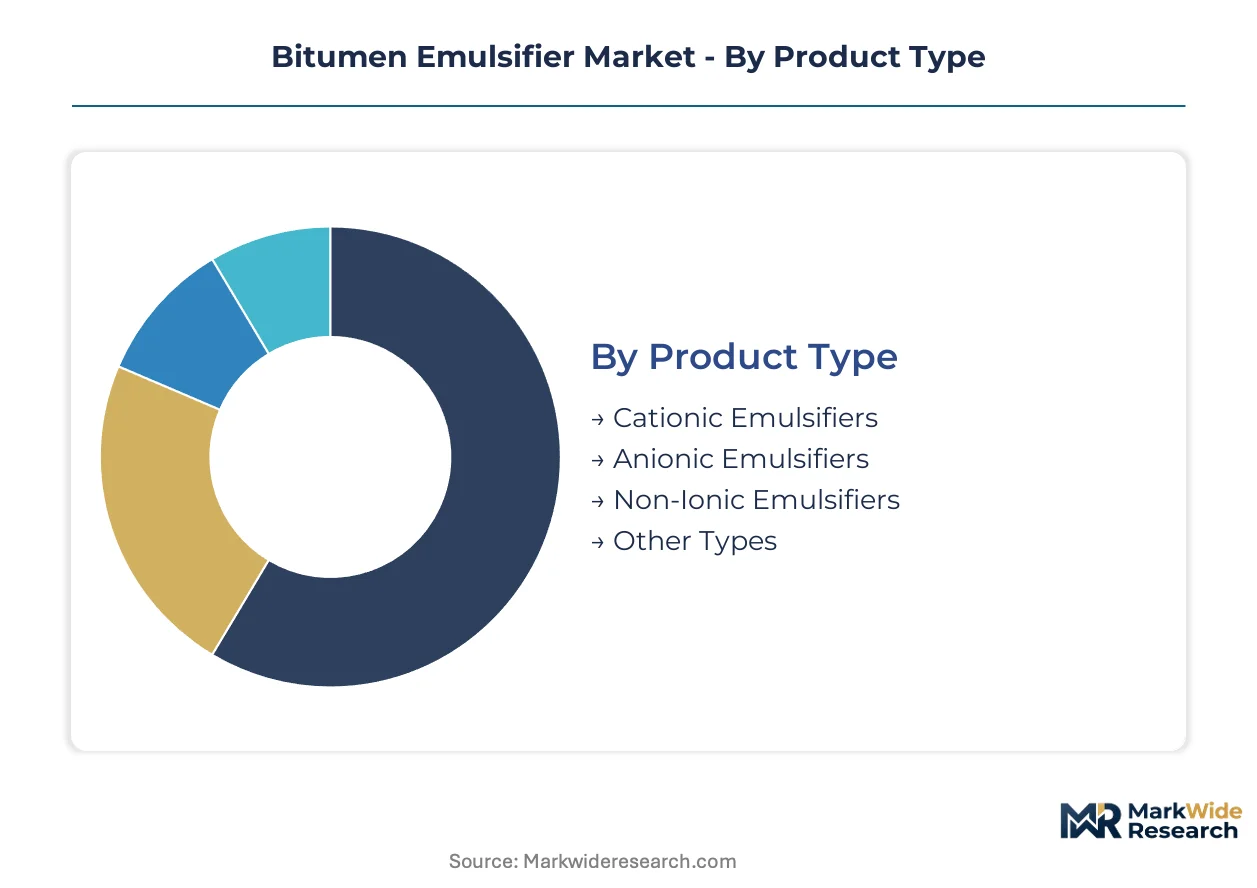
Segmentation in the bitumen emulsifier market reveals how specification requirements, formulation chemistry, and procurement channels fragment commercial opportunity. Understanding these divisions exposes where margin pools concentrate and which technology platforms face substitution pressure from bio-based alternatives.
Product Type:
Margin pools concentrate in cationic grades where aggregate adhesion performance commands specification premiums, while anionic formulations compete on cost in geotechnical niches.
- Cationic Emulsifiers:Positively charged alkylamine surfactants deliver rapid break characteristics and superior bonding to negatively charged aggregates. Demand concentrates in India's NHAI highway contracts and PMGSY rural road schemes where early traffic opening is mandatory. REACH compliance costs for amine-based chemistries are squeezing European formulator margins.
- Anionic Emulsifiers:Fatty acid derivatives carry negative surface charges suited to alkaline aggregates and extended workability applications. Soil stabilization contracts in mining and airport runway expansion are absorbing volumes in Australia and Canada. Slower setting kinetics limit penetration in time-critical road base construction.
- Non-Ionic Emulsifiers:Polyoxyethylene derivatives offer pH-independent stability for specialty waterproofing membranes.
- Other Types:Amphoteric and bio-based surfactant architectures piloting in Nordic EU Green Deal tenders.
The dominant share belongs to cationic emulsifiers, while bio-based alternatives in the "other" category are closing the gap fastest.
Application:
Application segmentation tracks how cold-lay technology penetrates construction verticals with differing performance specifications and regulatory exposure.
- Road Construction:Cold-mix and surface dressing applications consume bulk volumes through emulsion-based binders that eliminate heating above 100°C. India's BIS-certified storage stability mandates are filtering low-grade imports and consolidating procurement around domestic blenders. EPA stormwater restrictions in the United States are accelerating municipal cold paving approvals.
- Waterproofing:Spray-applied membrane systems specify polyamide-modified emulsifiers with particle sizes below five microns. German and Japanese contractors are driving adoption of robotic application equipment in confined maintenance zones.
- Roof Coating:Protective bituminous layers for commercial and industrial buildings.
- Oilfield Applications:Wellbore stabilization and pipeline coatings in hydrocarbon extraction.
Road construction commands the volume base, though waterproofing is expanding most quickly on premium pricing.
Technology:
Technology choice reflects capital intensity trade-offs between batch flexibility and continuous throughput economics.
- Mechanical Mixing:Rotor-stator systems dominate regional blending operations with lower capital barriers and formulation adaptability. Non-integrated producers in India and Brazil rely on this platform for multi-grade production runs. Particle size control limitations restrict penetration in polymer-modified specifications.
- Chemical Emulsification:In-situ surfactant generation enables precise droplet size distribution for high-performance grades.
- High-Pressure Homogenization:Intense shear forces achieve sub-five-micron distributions required for spray membrane and polymer-modified binders. Integrated petrochemical producers deploy this technology for captive emulsifier manufacturing.
- Other Methods:Ultrasonic and membrane emulsification piloting in specialty applications.
Mechanical mixing retains the installed base, while high-pressure homogenization is gaining share fastest in premium tiers.
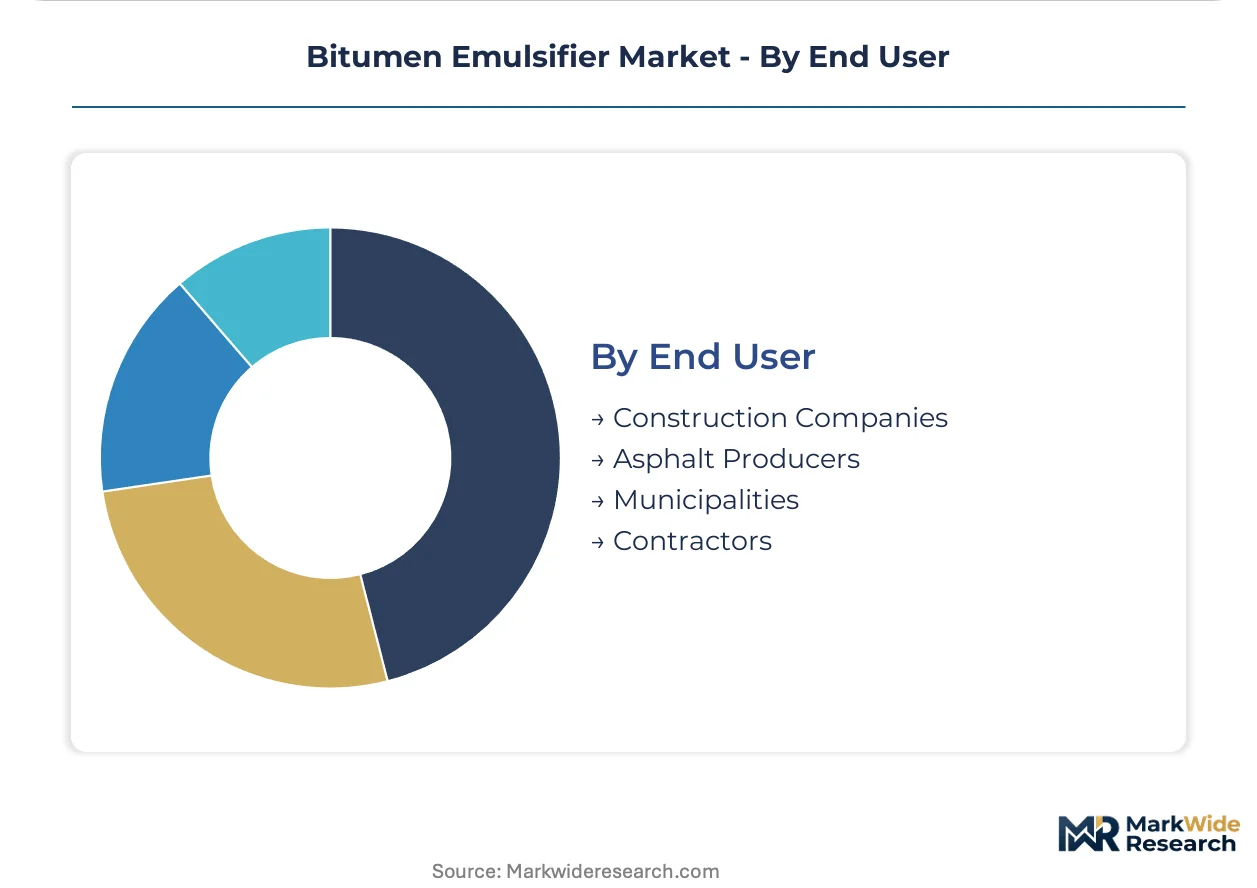
End User:
End user segmentation maps how procurement authority concentrates between integrated asphalt producers and fragmented construction contractors.
- Construction Companies:General contractors executing road and building projects source emulsifiers through project-specific supply agreements. India's state public works departments are mandating BIS certification as a contract precondition, shifting procurement from spot markets to multi-year frameworks.
- Asphalt Producers:Integrated bitumen refiners with captive emulsifier production control feedstock costs through ethylene oxide supply chain integration.
- Municipalities:City and county agencies with direct paving responsibility.
- Contractors:Specialized road maintenance and resurfacing operators.
Asphalt producers hold the volume anchor, while construction companies are consolidating procurement authority fastest through specification-driven tendering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates for road emulsions anchor the dominant geography, while REACH compliance in Europe and EPA stormwater rules in the United States reshape formulation economics across major demand centers.
India
NHAI highway upgrades and PMGSY rural road schemes concentrate bulk emulsifier procurement into standardized long-term supply contracts. BIS certification mandates strict storage-stability testing that filters out low-grade imports. State public works departments in Maharashtra and Gujarat are consolidating procurement around domestically certified blending facilities.
United States
EPA stormwater restrictions on volatile organic compound releases from hot-mix plants accelerate municipal approvals for cold-applied emulsion paving systems. State transportation departments in Texas and California are expanding cold-mix asphalt programs for maintenance overlays. Regional blending facilities in the Southeast face capacity constraints as qualified formulation specialists retire.
Germany
REACH registration requirements force suppliers to document full toxicological profiles of amine-based surfactants, raising compliance barriers for import-dependent blenders. The EU Green Deal pushes formulators toward bio-based surfactant chemistries in federal infrastructure tenders. Industrial clusters in North Rhine-Westphalia pilot tall oil fatty acid derivatives for Nordic road contracts.
China
Provincial transportation bureaus in Jiangsu and Guangdong are specifying polymer-modified emulsions for high-traffic expressway maintenance. National dual carbon goals pressure state-owned refiners to reduce energy-intensive hot-mix production. Yangtze River Delta chemical parks integrate ethylene oxide supply chains for captive cationic emulsifier manufacturing.
Brazil
Mining sector soil stabilization contracts in Minas Gerais absorb anionic emulsifier volumes with extended workability windows. Federal highway concession programs in São Paulo state require cold-lay surface dressing for traffic management efficiency. Regional blenders in the Southeast rely on mechanical mixing platforms for multi-grade production flexibility.
Bitumen Emulsifier Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the bitumen emulsifier supply base. Integrated petrochemical producers control feedstock economics through captive ethylene oxide supply chains, while specialized surfactant formulators compete on specification compliance and application engineering. The market structure fragments between global chemical conglomerates with backward integration advantages and regional blending specialists with formulation agility. Dominant competitive moves include strategic partnerships with road authorities for specification co-development and capacity expansion in BIS-certified production zones.
Among integrated chemical producers, Dow Chemical Company and BASF SE exemplify scale-driven archetypes with upstream control over cationic precursor supply chains. Nouryon anchors European supply through alkylamine derivative production at Swedish and Dutch sites, representing the regional-specialist archetype with deep REACH compliance expertise. These three companies occupy positions that span both feedstock security and formulation certification capabilities.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Nouryon |
| Arkema Group |
| Croda International Plc |
| Kao Corporation |
| BASF SE |
| Ingevity Corporation |
| AkzoNobel N.V. |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
India's BIS certification regime gates both supply qualification and price differentiation simultaneously, filtering low-grade imports while creating captive premiums for domestically certified production capacity. This regulatory architecture compresses margins at non-compliant blenders while concentrating pricing power with integrated producers who control ethylene oxide feedstock economics.
Pricing Analysis
Price spreads between European REACH-compliant grades and Indian BIS-certified formulations reflect compliance cost differentials rather than performance gaps. Three-tier pricing structure across premium polyamide-modified, standard cationic alkylamine, and economy mechanical-mix grades dominates procurement frameworks. Cost compression in standard cationic tiers is intensifying because integrated petrochemical producers leverage captive ethylene oxide supply. Municipal contractors in India's state public works departments exhibit highest price sensitivity, while German waterproofing specialists accept premium positioning for sub-five-micron specifications.
Supply Chain Analysis
China, India, and Germany anchor global emulsifier manufacturing through distinct competitive advantages. China draws from integrated Yangtze River Delta chemical parks for captive ethylene oxide and alkylamine derivative production. India sources tall oil fatty acid precursors from domestic pulp processing while importing specialty polyamide backbones. Germany relies on Nordic tall oil and lignin feedstocks for bio-based pilot programs. Single-source vulnerability concentrates in ethylene oxide supply, where non-integrated regional blenders lack feedstock security. Distribution runs through long-term framework agreements with state road authorities rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where REACH-compliant bio-based chemistries and BIS-certified storage stability are creating interoperable specification standards that favor integrated producers with dual-certification capabilities.
For Market Incumbents: Compound backward integration advantages by locking in ethylene oxide supply agreements before feedstock volatility escalates. Defend position by accelerating bio-based surfactant pilot programs to capture EU Green Deal procurement preferences. Prioritize capacity expansion in Maharashtra and Gujarat to secure BIS-certified production zones ahead of state consolidation mandates.
For New Entrants and Emerging Players: Differentiate on soil stabilization verticals where anionic grades with extended workability windows face limited incumbent concentration. Target Australia's mining sector and Canada's airport runway expansion programs as penetrable geographies. Deploy application-engineering partnerships with geotechnical contractors as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional blending specialists in India's Southeast and Brazil's Minas Gerais corridor. Long-term viability hinges on certification moats rather than scale economics. Monitor REACH registration deadline compliance as the critical inflection signal for European supply discontinuity and substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow Chemical's captive supply chain controls cationic precursor costs against import-dependent blenders. |
| Bio-Based Surfactant Pilot Expansion | Nordic tall oil derivatives qualify for EU Green Deal procurement preferences in German federal tenders. |
| BIS Certification Capacity Buildout | Maharashtra and Gujarat consolidation mandates filter low-grade imports toward domestic qualified producers. |
| Polyamide-Modified Emulsifier R&D | Arkema's sub-five-micron architectures penetrate German spray-applied waterproofing membrane specifications. |
| Soil Stabilization Vertical Partnership | Anionic grade specialists capture Australian mining and Canadian airport geotechnical improvement contracts. |
Methodological Framework
Desk research of customs trade data, SEC chemical sector filings, and BIS emulsion testing protocols preceded structured interviews with asphalt plant managers, road construction procurement leads, and surfactant R&D directors. Primary fieldwork with state public works department engineers and REACH compliance consultants validated formulation chemistry shifts. Secondary sources included ECHA substance dossiers, NHAI contract award databases, and EU Green Deal tender documentation. Bottom-up volume modeling triangulated against top-down petrochemical feedstock demand analysis.
Variance decomposition across product type, application vertical, technology platform, and end-user procurement authority anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled included cationic/anionic/non-ionic chemistry grades, road construction versus waterproofing application splits, mechanical mixing versus high-pressure homogenization technology tiers, and asphalt producer versus construction company end-user channels. CAGRs derived from elasticity-adjusted demand curves incorporating polymer-modified binder specification penetration rates and cold-mix asphalt program expansion trajectories.
Material uncertainties — ethylene oxide feedstock volatility, REACH registration deadline extensions, and BIS certification protocol revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure budget execution rates. Recalibration cycles align with material shifts in EU Green Deal procurement thresholds and Indian state-level tender consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Amino Silicone Oil Market
Surfactants
Wax Emulsion Market
Surfactants
Anionic Surfactants Market
Surfactants
MDEA Esterquats Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Specialty Surfactants Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
North America Surfactants Market
Surfactants
Dispersant Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Tetrabutylammonium Bromide Market