
 Emulsion Stabilizers Market | 2026-2036
Emulsion Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion Stabilizers Market Foresight
Pharmaceutical formulation is realigning emulsion stabilizer procurement toward high-purity grades and excipient-grade certifications. Cargill leverages its agricultural supply chain to anchor natural polymer production at scale. Palsgaard competes through specialized emulsifier blends tailored for dairy and confectionery applications. Royal DSM sustains technology leadership in enzymatically modified stabilizers for clean-label markets.
Emulsion stabilizers are amphiphilic compounds or polymeric systems that reduce interfacial tension between immiscible phases, typically achieving particle size distributions below 10 micrometers in food and pharmaceutical applications. Their primary industrial purpose is to prevent coalescence, creaming, and Ostwald ripening in oil-in-water or water-in-oil systems during processing, storage, and thermal cycling. Natural polymers occupy the premium tier in food and beverage applications, where clean-label positioning commands margin pools from cosmetic brands and food manufacturers. Synthetic polymers dominate volume in paints and coatings, where cost efficiency and batch consistency outweigh origin claims. Surfactants represent the fastest-growing chemistry class in pharmaceutical emulsions, driven by parenteral and topical formulation complexity.
EFSA maintains stringent safety evaluations for food additives under Regulation 1333/2008, directly influencing stabilizer approval timelines and reformulation costs for European suppliers. REACH mandates registration and hazard communication for synthetic polymer intermediates, shaping raw material sourcing decisions and substitution patterns across the value chain. FDA's Food Additive Regulations and GRAS notification pathway create parallel compliance obligations for exporters targeting United States pharmaceutical and food channels. Stakeholders must monitor divergence between EU and US purity standards for natural polymer derivatives, as regulatory misalignment threatens to fragment formulation strategies and duplicate qualification investments.
Market Dynamics
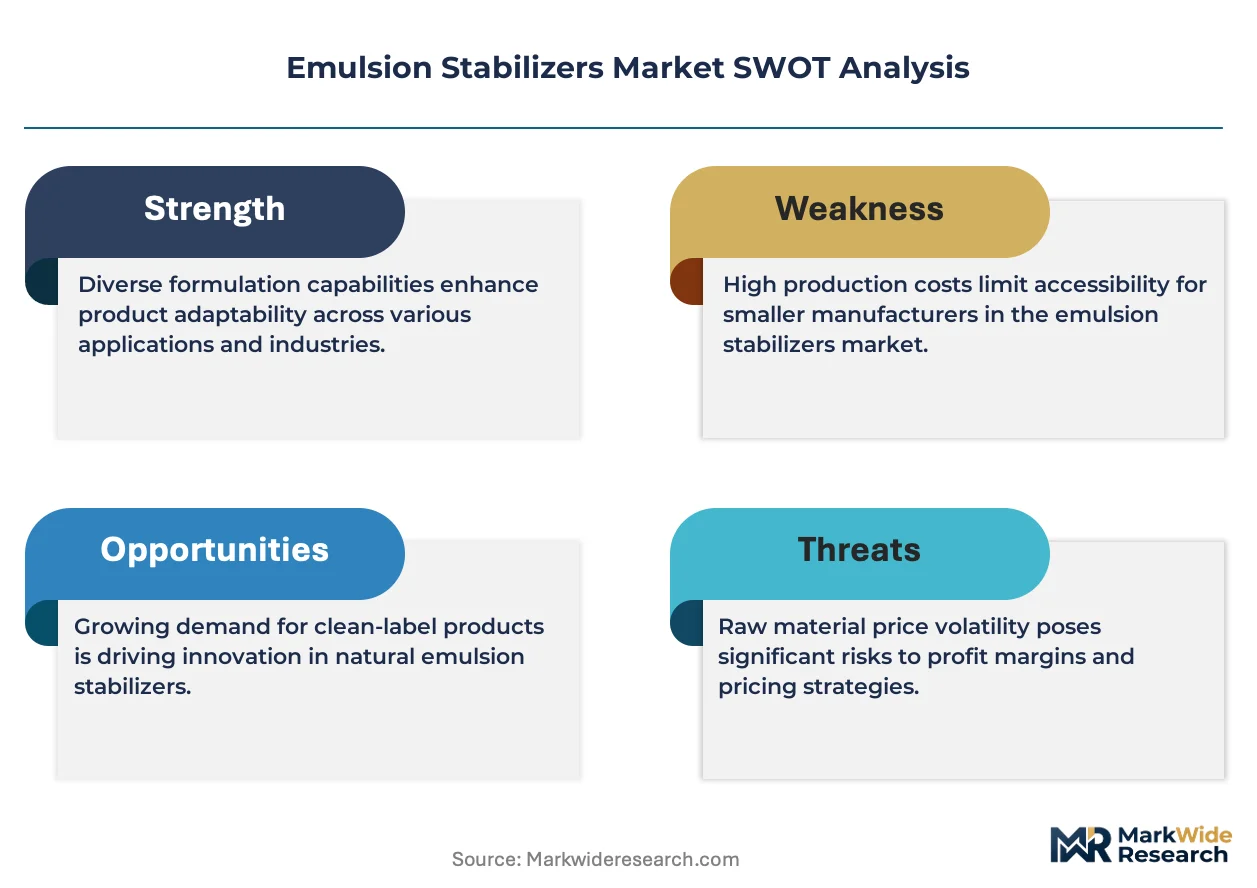
Clean-label mandates from EFSA and FDA are forcing reformulation cycles across food and pharmaceutical supply chains, compressing qualification timelines while elevating purity requirements for natural polymer derivatives.
Growth Catalysts
- EFSA Regulation 1333/2008:Stringent safety evaluations for food additives accelerate premium-grade stabilizer adoption as manufacturers preempt compliance-driven reformulation costs.
- Enzymatic modification:Biocatalytic processing of natural polymers enables cleaner-label positioning without sacrificing functional performance in dairy emulsions.
- Germany:Concentrated processed food manufacturing in Baden-Württemberg and Bavaria generates sustained procurement volume for high-performance stabilizer blends.
Market Restraints
- Gum arabic supply volatility:Sudan and Sahel region political instability creates raw material availability risk for acacia-derived stabilizers.
- REACH registration costs:Synthetic polymer intermediates face escalating compliance expenditure, disadvantaging smaller European compounders against integrated producers.
- Protein hydrolysate substitution:Dairy and plant-protein emulsifiers encroach on traditional stabilizer applications in beverage systems.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging regulatory alignment with Western standards creates first-mover advantage for excipient-grade certified suppliers.
- Cell-cultured meat:Novel fat-emulsion systems require specialized stabilizer architectures not served by incumbent food-grade portfolios.
- Direct-to-manufacturer platforms:Digital procurement channels bypass distributor markups for mid-volume pharmaceutical compounders.
Industry Challenges
- Excipient-grade certification timelines:USP-NF and EP qualification cycles extend 18-24 months, straining R&D-to-revenue conversion.
- Cross-functional formulation expertise:Scarce talent pools combining colloid chemistry with regulatory science constrain product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion Stabilizers Market |
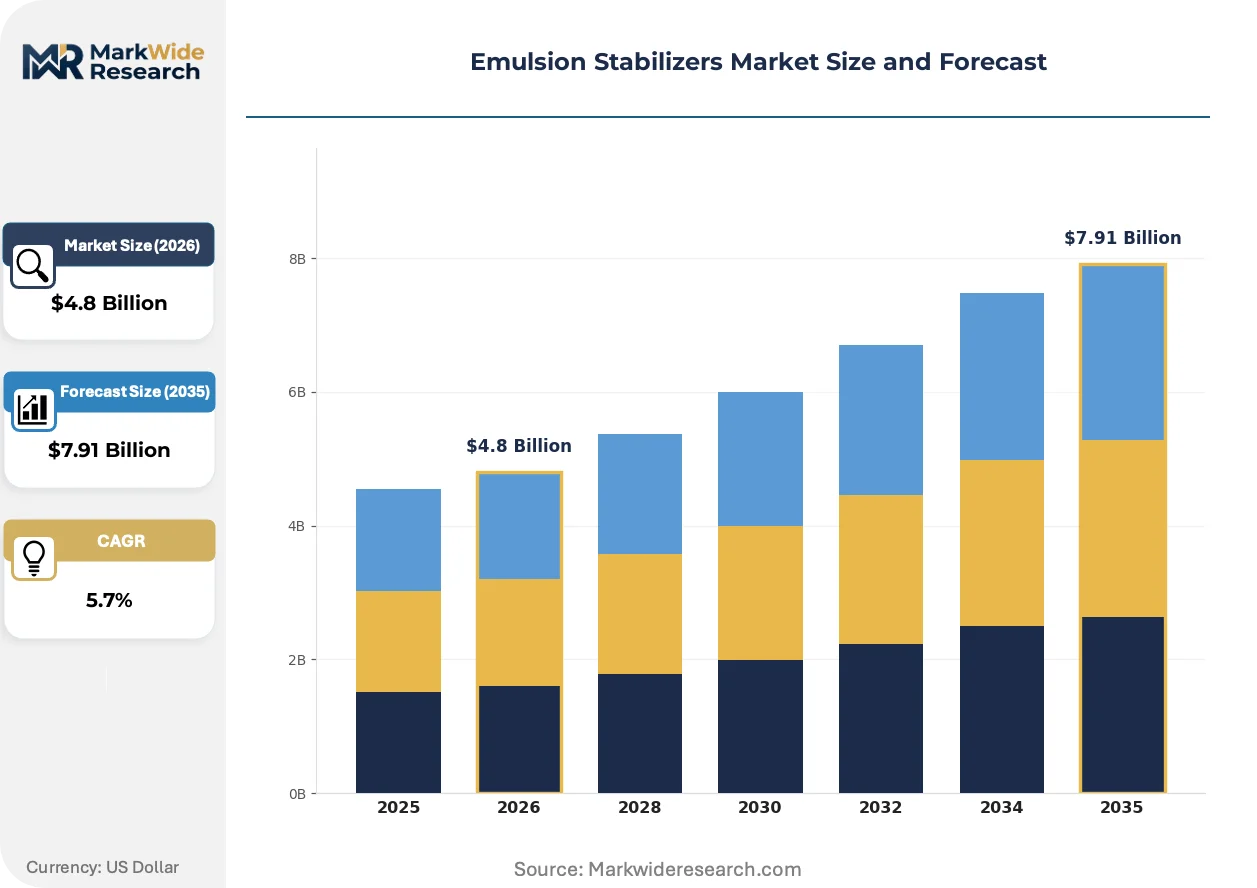
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polymers, Synthetic Polymers, Surfactants, Emulsifying Agents Application: Food & Beverage, Cosmetics, Pharmaceuticals, Paints & Coatings End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Chemical Producers Distribution Channel: Online Sales, Direct Sales, Wholesalers, Retailers |
| Companies Covered | Ashland Global Holdings, CP Kelco, Cargill, Tate & Lyle, Ingredion, Archer Daniels Midland, Royal DSM, Palsgaard, DowDuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion Stabilizers Market Shifts & Advancements
Microfluidic processing and enzymatic engineering are compressing development cycles for tailored stabilizer architectures, while regulatory divergence between jurisdictions fragments formulation standardization efforts.
Microfluidic emulsification is decentralizing scale-up pathways for pharmaceutical-grade emulsions. Parenteral formulation houses adopt continuous-flow processing to bypass batch-scale validation bottlenecks. This technology is decentralizing production economics toward distributed manufacturing nodes.
REACH authorization requirements for synthetic polymer intermediates tighten hazard communication obligations. European compounders face substitution pressure toward bio-based alternatives. Pharmaceutical excipient suppliers accelerate natural polymer qualification to preempt regulatory exclusion.
Long-term supply agreements now dominate stabilizer procurement for multinational food manufacturers. Spot-market purchasing retreats as EFSA-driven reformulation risks demand supply security. This contracting shift concentrates most visibly in French and UK dairy processing clusters.
Emulsion Stabilizers Market Segmentation
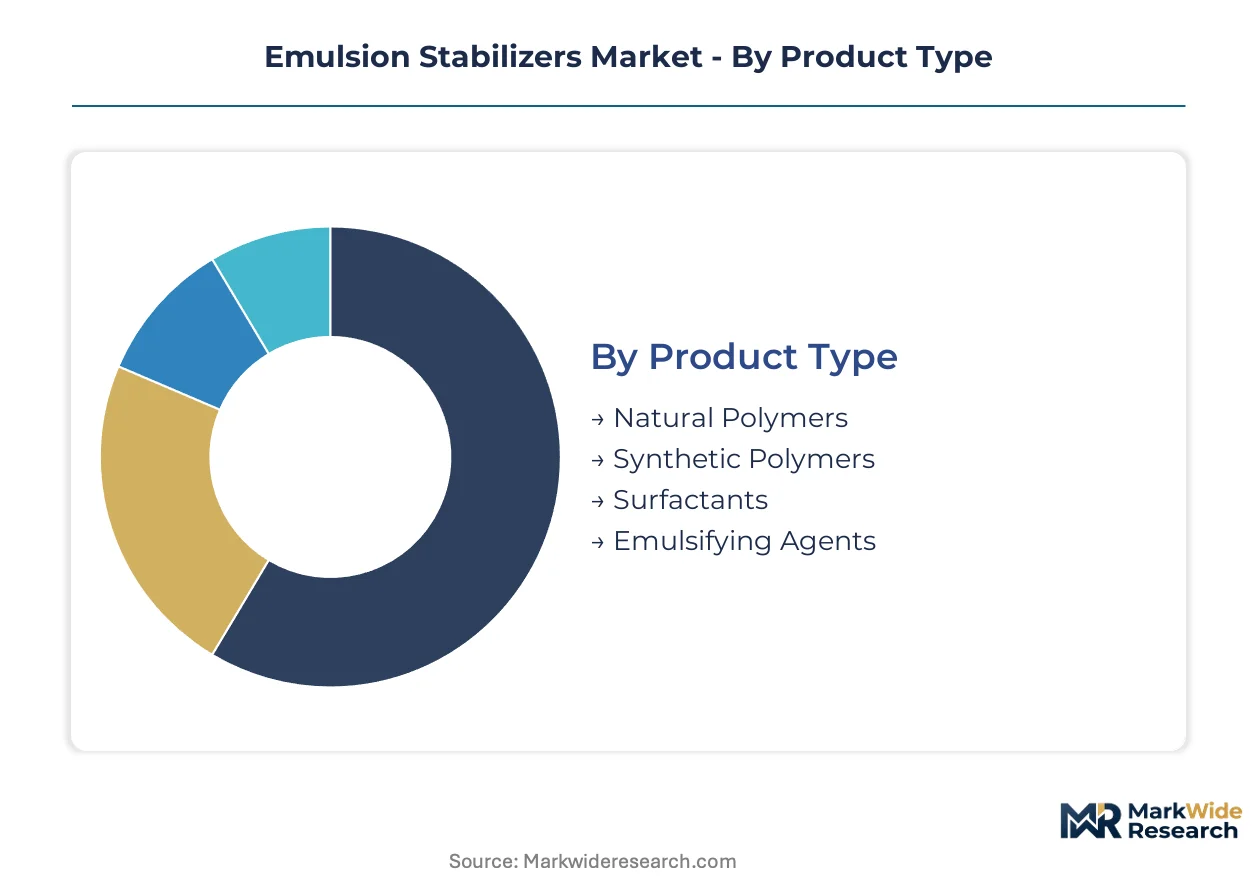
Emulsion stabilizer procurement splits sharply between premium-grade natural polymers for clean-label positioning and cost-optimized synthetics for industrial volume. Formulators select chemistry class based on regulatory jurisdiction, end-use certification requirements, and thermal stability demands.
Product Type:
Customization intensity spans from bespoke enzymatic modifications to commodity surfactant batches.
- Natural Polymers:Plant-derived hydrocolloids including acacia, guar, and pectin derivatives. Demand concentrates in German and French dairy processing where EFSA clean-label scrutiny drives premium positioning. Supply volatility from Sahel region gum arabic creates procurement hedging requirements.
- Synthetic Polymers:Petrochemical-based polyacrylates and cellulose ethers engineered for batch consistency. Paints and coatings manufacturers in the United States prioritize these for cost efficiency and REACH compliance simplification. Volume leadership reflects industrial scale economics over origin claims.
- Surfactants:Amphiphilic molecules for parenteral pharmaceutical emulsions.
- Emulsifying Agents:Lecithin and mono-diglyceride compounds for food systems.
Most installed capacity flows through Synthetic Polymers. Expansion is steepest in Surfactants.
Application:
Margin structure separates pharmaceutical excipient grades from commodity food additives.
- Food & Beverage:Stabilizers for dairy emulsions, salad dressings, and beverage clouding. UK and German processed food clusters sustain procurement volume for high-performance blends. EFSA reformulation mandates compress qualification timelines while elevating purity requirements.
- Pharmaceuticals:Parenteral and topical emulsions demanding USP-NF and EP certification. Complex formulation requirements in United States injectables drive surfactant chemistry adoption. Excipient-grade qualification cycles extend 18-24 months, straining supplier R&D conversion.
- Cosmetics:Skin and hair care emulsions with clean-label positioning.
- Paints & Coatings:Architectural and industrial finishes prioritizing cost efficiency.
Food & Beverage commands the largest volume base. Pharmaceuticals deliver the steepest margin expansion trajectory.
End User:
Procurement sophistication varies from multinational tender processes to mid-volume compounder spot buying.
- Food Manufacturers:Dairy, bakery, and beverage processors requiring supply security. French and UK dairy clusters now favor long-term agreements over spot purchasing to mitigate EFSA-driven reformulation risks. Technical service demands include application-specific blend customization.
- Pharmaceutical Companies:Formulation houses with excipient-grade certification requirements. United States parenteral developers compress development cycles through microfluidic processing partnerships. Regulatory documentation burdens exceed food-sector standards.
- Cosmetic Brands:Clean-label marketers sourcing plant-derived hydrocolloids.
- Chemical Producers:Industrial compounders integrating stabilizers into coating systems.
Food Manufacturers anchor installed demand. Pharmaceutical Companies are expanding procurement most quickly.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs.
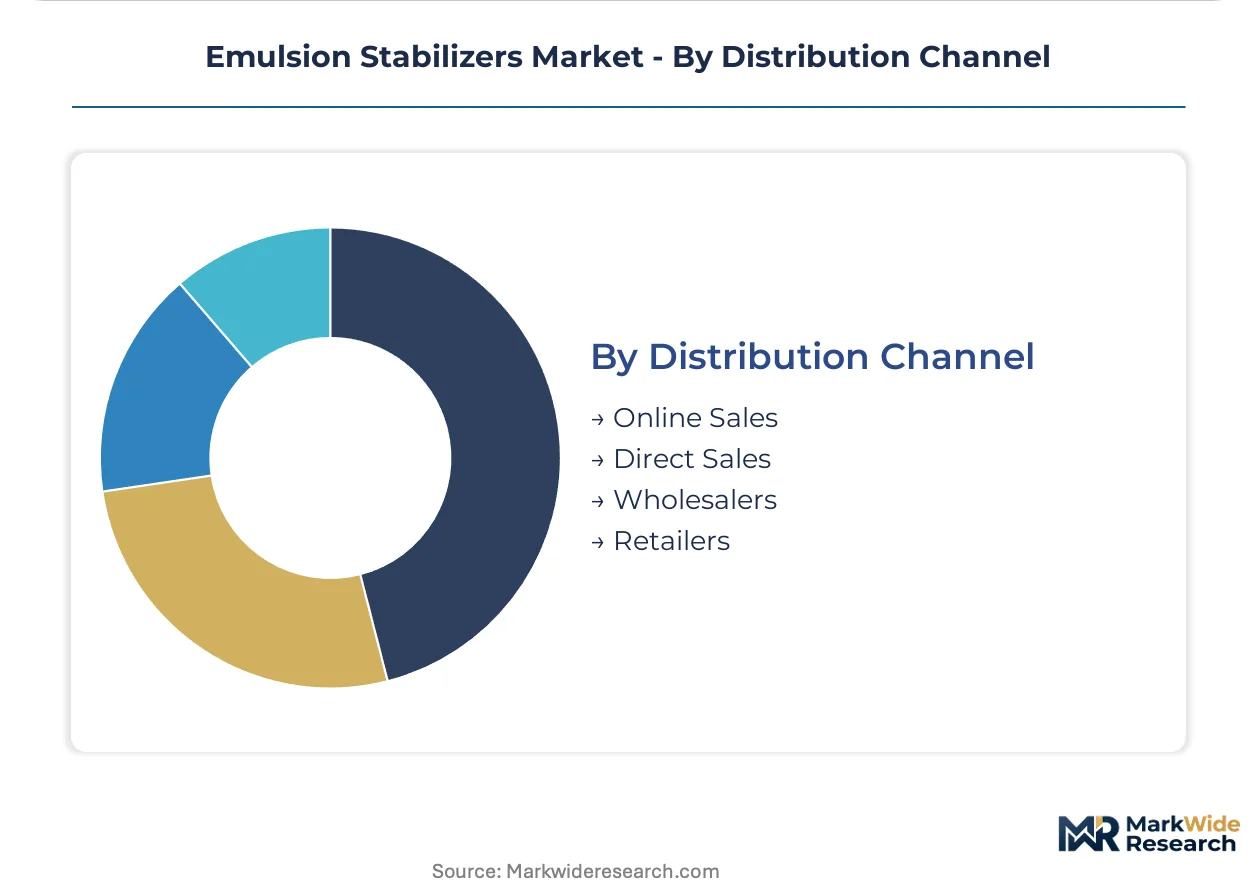
- Direct Sales:Manufacturer-to-compounder relationships for pharmaceutical and large food accounts. Technical collaboration on formulation development justifies relationship investment. United States and European multinationals consolidate procurement through direct channels.
- Online Sales:Digital platforms serving mid-volume pharmaceutical compounders and specialty food startups. Direct-to-manufacturer models bypass distributor markups while accelerating sample qualification. Adoption concentrates in North American and Western European markets.
- Wholesalers:Regional distributors for standard-grade industrial applications.
- Retailers:Small-package sales to artisanal food producers and cosmetic formulators.
Direct Sales carries the largest transaction value. Online Sales is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting stabilizer production toward jurisdictions with streamlined additive approval pathways. Manufacturers exploit compliance-cost gaps between REACH-heavy Europe and emerging markets adopting Western standards. This migration pattern concentrates investment in countries with dual-track regulatory credibility.
United States
Pharmaceutical parenteral formulation drives premium surfactant procurement from New Jersey and Massachusetts biotech clusters. FDA's GRAS notification pathway accelerates clean-label stabilizer market entry compared to EFSA timelines. Chicago and Minneapolis food processing hubs sustain bulk demand for lecithin and mono-diglyceride emulsifiers.
Germany
REACH authorization costs for synthetic polymer intermediates are compressing margins at mid-sized compounders in North Rhine-Westphalia. Baden-Württemberg dairy processors now mandate excipient-grade certifications for all hydrocolloid inputs. Munich formulation houses pioneer enzymatic modification partnerships with enzymatic engineering specialists.
India
FSSAI clean-label pathway alignment with Western standards attracts excipient-grade certification investments from Gujarat and Maharashtra chemical producers. CDSCO pharmaceutical regulations tighten impurity thresholds for parenteral-grade stabilizers. Hyderabad and Bangalore formulation clusters drive surfactant chemistry adoption in injectable generics.
China
NMPA harmonization with ICH guidelines accelerates pharmaceutical-grade stabilizer qualification for export-oriented producers in Jiangsu and Zhejiang. SAMR food additive standards tighten acacia-derived hydrocolloid specifications. Shanghai and Guangzhou cosmetic formulators source plant-derived stabilizers for clean-label skin care lines.
Brazil
ANVISA pharmaceutical excipient regulations drive USP-NF certification adoption among São Paulo chemical distributors. Processed dairy expansion in Minas Gerais sustains guar and pectin derivative procurement. Campinas and Porto Alegre food technology centers pilot cell-cultured meat fat-emulsion stabilizer applications.
Emulsion Stabilizers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade certification creating tiered entry barriers that commodity food-grade suppliers cannot easily cross. The market structure concentrates around three to five integrated agricultural processors controlling upstream hydrocolloid supply, while mid-tier compounders compete on blend customization for regional dairy clusters. Strategic archetypes include vertically integrated agricultural processors, enzymatic modification technology licensors, and excipient-grade certification specialists. Dominant competitive moves involve long-term supply agreements with multinational food manufacturers and microfluidic processing partnerships with parenteral formulation houses.
Within the agricultural-processor archetype, Cargill leverages its North American grain supply chain to anchor natural polymer production at scale. Royal DSM occupies a position in enzymatic modification technology for clean-label dairy applications. Palsgaard exemplifies the specialized blend formulator archetype, with Denmark-based operations serving European confectionery and dairy clusters. These three companies represent distinct competitive positioning vectors: upstream raw material control, biocatalytic processing capability, and application-specific formulation expertise.
| Leading Market Players |
|---|
| Ashland Global Holdings |
| CP Kelco |
| Cargill |
| Tate & Lyle |
| Ingredion |
| Archer Daniels Midland |
| Royal DSM |
| Palsgaard |
| DowDuPont |
| Others |
Supply & Pricing Matrix
EFSA-driven reformulation mandates in German and French dairy processing are forcing stabilizer suppliers to absorb elevated certification costs while maintaining price competitiveness against protein hydrolysate substitutes. This demand-side specification tightening compresses margin pools for mid-tier compounders and accelerates procurement consolidation toward integrated agricultural processors with captive raw material supply.
Pricing Analysis
Distributor markups in European food-grade channels range from 15 to 25 percent, while direct-to-manufacturer pharmaceutical contracts command 8 to 12 percent channel discounts reflecting volume commitments and technical service bundling. Three-tier pricing structure across excipient-grade, food-grade, and industrial-grade certifications anchors differentiation, with USP-NF qualification adding 30 to 40 percent premiums over standard food additive tiers. Cost compression in synthetic polymer segments is intensifying because REACH registration expenditures disadvantage smaller European compounders against integrated producers. Industrial coatings manufacturers exhibit highest price sensitivity, while parenteral pharmaceutical formulators prioritize supply security over unit cost.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Zhejiang chemical manufacturing zones are pushing pharmaceutical-grade stabilizer production toward Gujarat and Maharashtra, where technical labor pools support excipient-grade certification requirements. Supply concentration spans Sudan and Sahel region for gum arabic feedstock, India and China for acacia and guar derivatives, and North Rhine-Westphalia for synthetic polymer intermediates. Raw material sourcing draws from Sahel acacia plantations, Indian guar bean cultivation, and petrochemical crackers in Germany and the Netherlands. Single-source vulnerability in gum arabic procurement from politically unstable Sudan creates supply interruption exposure for clean-label hydrocolloid portfolios. Distribution runs through long-term supply agreements with multinational food manufacturers, bypassing spot-market volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with clean-label procurement mandates in European dairy and pharmaceutical parenteral formulation driving specification premiums toward enzymatically modified natural polymers and excipient-grade certified hydrocolloids.
For Market Incumbents: Hedge against gum arabic supply disruption by securing alternative acacia sourcing from Senegal and Mali while accelerating backward integration into guar bean cultivation in Rajasthan. Preempt protein hydrolysate substitution threats through enzymatic modification partnerships that preserve functional performance in beverage emulsion systems. Prioritize excipient-grade certification investments to defend margin position in pharmaceutical channels where qualification timelines create switching costs. For New Entrants and Emerging Players: Begin with cell-cultured meat fat-emulsion stabilizers, an application white space unserved by incumbent food-grade portfolios and requiring novel architecture development. Target mid-volume pharmaceutical compounders in Hyderabad and Bangalore through direct-to-manufacturer digital platforms that bypass established distributor relationships. Lead with microfluidic processing partnerships to compress development cycles for parenteral formulation houses seeking continuous-flow manufacturing alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with enzymatic modification technology licensors possessing clean-label dairy application expertise and established EFSA regulatory navigation capabilities. Five-to-ten year viability hinges on regulatory divergence between EU and US purity standards fragmenting formulation strategies and duplicating qualification investments. Monitor FSSAI clean-label pathway implementation in India as inflection signal for emerging market premium-grade stabilizer adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | French and UK dairy processors lock in hydrocolloid supply security against EFSA reformulation volatility. |
| Backward Integration | Cargill's North American grain supply chain anchors captive natural polymer production at scale. |
| Enzymatic Modification Partnership | Royal DSM's biocatalytic processing enables cleaner-label positioning without sacrificing dairy emulsion performance. |
| Excipient-grade Certification Investment | USP-NF and EP qualification cycles create 18-24 month barriers protecting pharmaceutical-grade margin pools. |
| Microfluidic Processing Collaboration | Parenteral formulation houses in New Jersey and Massachusetts adopt continuous-flow scale-up pathways. |
Research Methodology
Bottom-up pharmaceutical and food formulation modeling reconciled against top-down hydrocolloid and surfactant production tracking forms the analytical core of this study. Primary interviews with plant managers at European dairy processors, procurement leads at parenteral formulation houses, technical R&D directors at enzymatic engineering specialists, and distribution channel partners in specialty chemical distribution validated demand assumptions. Secondary sources include EFSA additive approval databases, REACH registration filings, USP-NF monograph updates, and customs trade data for acacia and guar derivatives. Triangulation across these sources reconciled volume estimates with value projections.
Historical trendline analysis of natural polymer and synthetic stabilizer demand patterns informed baseline trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type chemistry class, application grade tier, end-use industry vertical, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to validated base-year estimates, with pharmaceutical surfactant and enzymatically modified stabilizer categories receiving accelerated adoption assumptions reflecting clean-label formulation complexity trends.
Several conditions sit outside the modeled scope, including Sudanese political stability trajectories affecting gum arabic supply, divergence between EU and US purity standards for natural polymer derivatives, and breakthrough protein hydrolysate emulsifier technologies displacing traditional stabilizer architectures. Forecasts reflect documented assumptions regarding EFSA reformulation timeline adherence and FSSAI clean-label pathway implementation pace. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Global Detergent Polymers Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Global Methyl Soyate Market
Surfactants
Wetting Agents Market
Surfactants
North America Surfactants Market
Surfactants
Global Oilfield Surfactants Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Global Demulsifiers Market
Surfactants
Bitumen Emulsifier Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Micellar Water Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Natural Wax Emulsion Market