
 Natural Surfactants Market | 2026-2036
Natural Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Surfactants Market Analysis
Southeast Asia is reconfiguring its oleochemical processing base as Indonesia and Malaysia expand palm kernel and coconut oil derivative output. BASF SE leverages integrated oleochemical supply chains from European rapeseed and Asian palm sources to sustain cost-advantaged alkyl polyglucoside production. Stepan Company anchors North American natural surfactant supply through proprietary esterification technology and Midwestern soy-based feedstock partnerships.
Natural surfactants are surface-active compounds derived from renewable plant oils, animal fats, or microbial fermentation, typically featuring hydrophilic carbohydrate or amino acid head groups bonded to hydrophobic fatty acid chains, and function by reducing interfacial tension between immiscible phases. These compounds serve primarily as cleansing agents, emulsifiers, and dispersants in formulated products where petrochemical alternatives face regulatory or consumer scrutiny. Alkyl polyglucoside dominates product type value pools due to its broad pH stability and biodegradability profile, while saponins from quillaja and yucca extracts occupy premium niches in food-grade emulsification. Personal care applications lead end-use consumption, though agricultural chemicals represent the fastest-expanding segment as biopesticide formulations require compliant wetting agents.
EPA bio-based preferred purchasing programs and ECHA REACH substance evaluation protocols are tightening permissible thresholds for nonylphenol ethoxylates and other synthetic surfactant precursors, directly expanding qualified demand for certified natural alternatives. FDA food contact notification requirements and FSSAI clean-label directives further segment market access by purity grade and traceability documentation. Stakeholders must monitor evolving biobased certification standards and feedstock provenance regulations to secure formulation partnerships with multinational consumer goods manufacturers.
Market Dynamics
REACH substance evaluation protocols in Europe are systematically disqualifying petrochemical surfactant precursors, forcing formulation houses to redesign supply chains around certified natural alternatives with full feedstock traceability documentation.
Growth Catalysts
- EPA bio-based preferred purchasing:Federal procurement mandates in the United States are creating qualified demand pools for certified natural surfactants across institutional cleaning and agricultural chemical applications.
- Personal care clean-label pivot:FSSAI directives in India and FDA food contact notification requirements are segmenting market access by purity grade, accelerating alkyl polyglucoside uptake in premium cosmetics.
- Oleochemical processing expansion:Indonesia and Malaysia are scaling palm kernel and coconut oil derivative output, reducing feedstock cost volatility for carbohydrate-based surfactant producers.
Market Restraints
- Palm oil price volatility:Weather-driven supply disruptions in Southeast Asian plantation zones transmit directly to alkyl polyglucoside production economics.
- Technical performance gaps:Saponin-based emulsifiers exhibit narrower pH stability windows than synthetic alternatives, limiting deployment in industrial alkaline cleaners.
- Substitution pressure:Biosurfactants from microbial fermentation are capturing niche demand in pharmaceutical and specialty chemical applications.
Strategic Opportunities
- Agricultural wetting agent penetration:Biopesticide formulation growth in Brazil and India is creating compliant surfactant demand that natural alternatives uniquely satisfy.
- EU Green Deal chemical transition:Carbon border adjustment mechanisms and sustainable product mandates are expanding qualified demand for plant-derived surface-active compounds.
- Direct-to-manufacturer digital channels:Specialty chemical platforms are collapsing traditional distributor layers, enabling smaller natural surfactant producers to access multinational formulation houses.
Industry Challenges
- Biobased certification complexity:USDA BioPreferred, EU Ecolabel, and Roundtable on Sustainable Palm Oil standards impose overlapping documentation burdens that extend commercialization timelines.
- Specialized process engineering scarcity:Esterification and glycosidation expertise concentrates among veteran chemical engineers in Germany's Rhine-Ruhr cluster and select Midwestern US research universities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Surfactants Market |
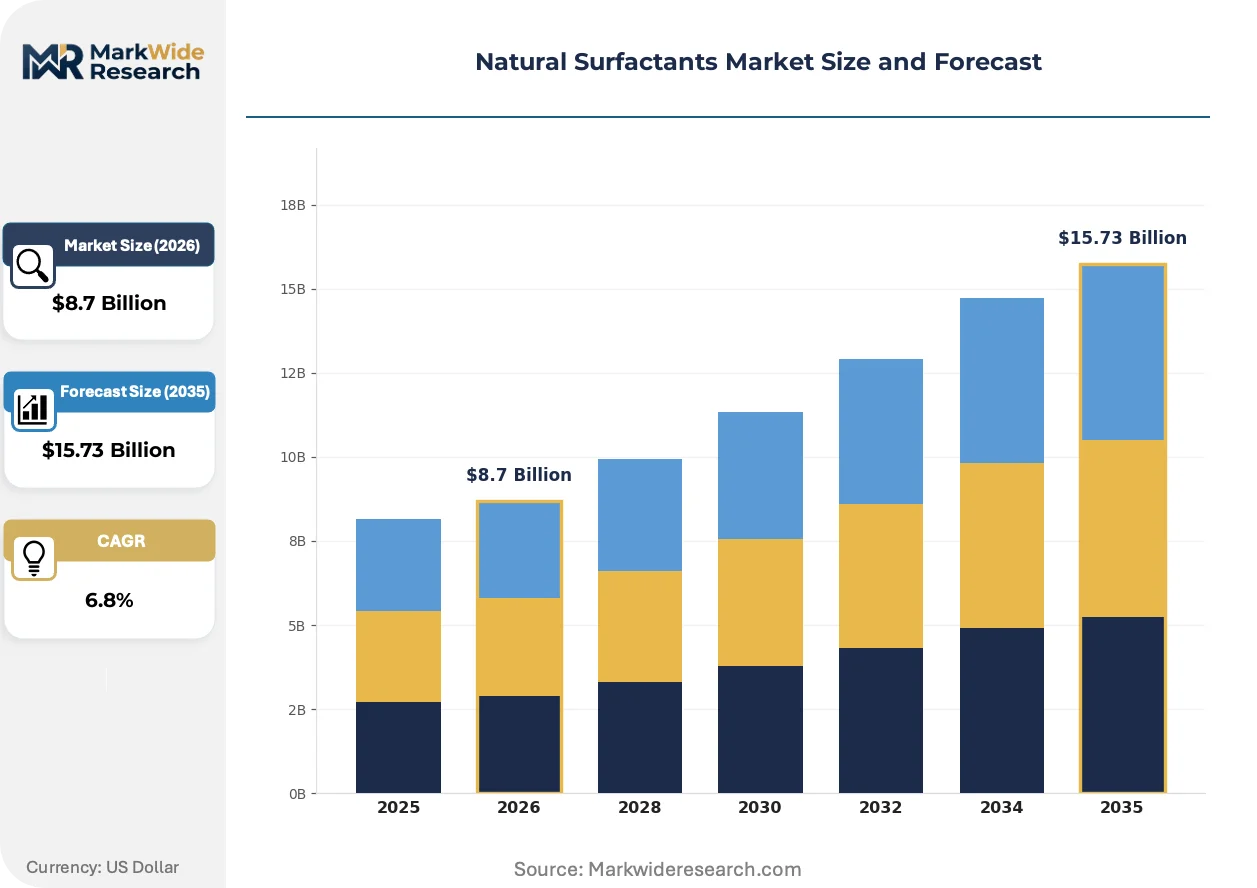
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soap, Alkyl Polyglucoside, Lecithin, Saponins End Use Industry: Personal Care, Household Detergents, Food Processing, Agricultural Chemicals Form: Liquid, Powder, Granular, Paste Application: Cleansing Agents, Emulsifiers, Foaming Agents, Dispersants |
| Companies Covered | Clariant, Stepan Company, BASF SE, WHEATOLEO, Kao Corporation, Croda International, Dow Inc., SEPPIC, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Surfactants Market Emerging Trajectories
Enzymatic synthesis routes and precision fermentation platforms are collapsing traditional thermochemical processing economics, while regulatory convergence around carbon intensity disclosure is reshaping competitive qualification requirements.
Enzymatic glycosidation using immobilized lipase catalysts is collapsing energy and solvent intensity in alkyl polyglucoside production. Specialty chemical producers in Germany and the Netherlands are retrofitting batch plants with continuous enzymatic reactors. This technology is collapsing the cost premium between natural and synthetic surfactants in mid-volume applications.
REACH authorization and restriction procedures are systematically removing nonylphenol ethoxylates from qualified chemical inventories. ECHA substance evaluation protocols now require extensive aquatic toxicity dossiers for petrochemical surfactant precursors. Agricultural chemical formulators across Poland, Spain, and Italy are accelerating natural surfactant qualification to preempt supply disruption.
Clean-label procurement mandates from multinational consumer goods manufacturers are compressing supplier qualification cycles. Tier-one personal care brands now require full feedstock provenance documentation and third-party sustainability certification before contract execution. This pattern concentrates most visibly in German and French cosmetics manufacturing clusters where regulatory anticipation runs highest.
Natural Surfactants Market Segmentation
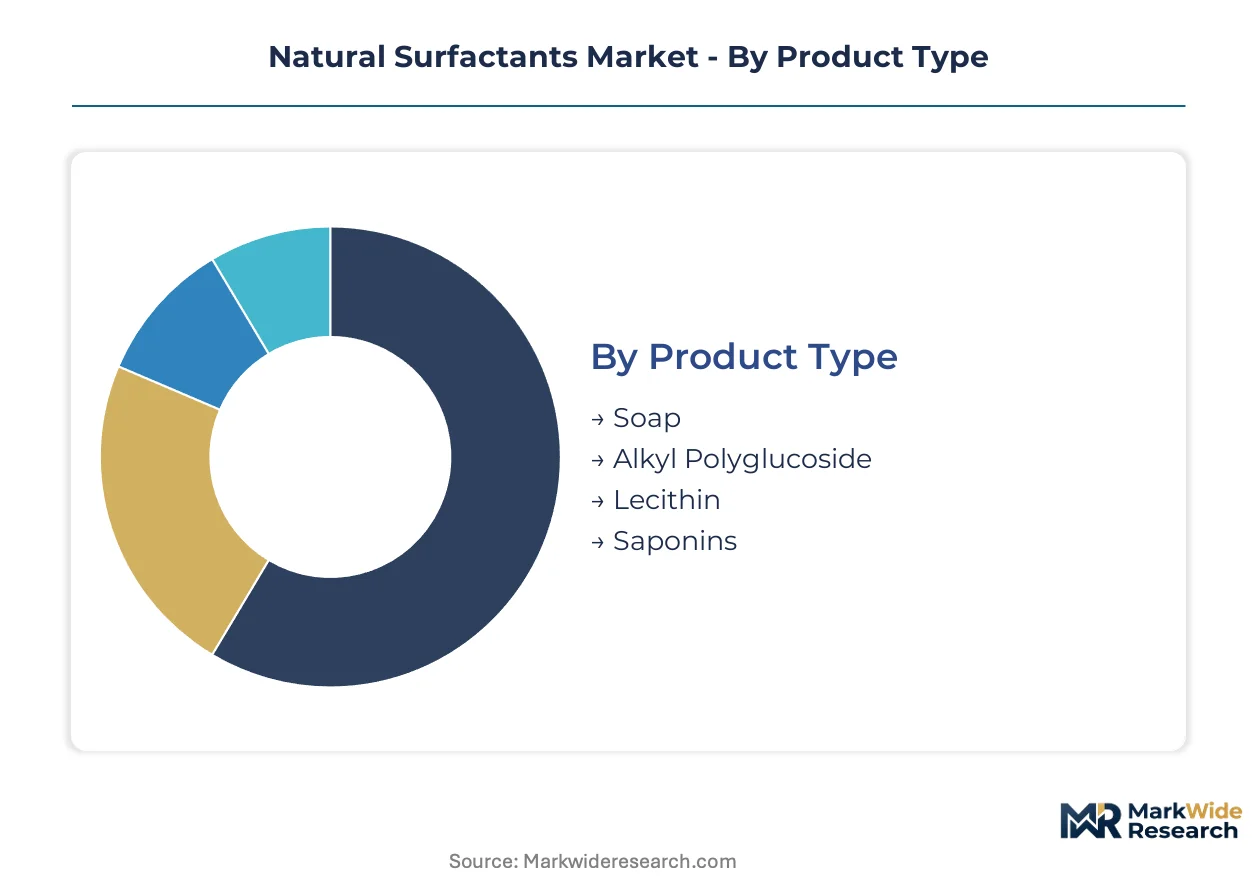
Natural surfactant procurement varies sharply by formulation requirement, with pH stability and biodegradability profiles determining product selection across regulated end-uses. Segmentation reveals how feedstock chemistry and physical form create distinct value pools that suppliers must navigate.
Product Type:
Use-case spectrum spans commodity cleansing to precision emulsification, with carbohydrate-based architectures commanding premium positioning in regulated applications.
- Alkyl Polyglucoside:Fatty alcohol-glucose condensation products deliver exceptional pH stability across 3-11 ranges with complete aquatic biodegradability. Personal care formulators in Germany's Rhine-Ruhr cluster specify this chemistry for sulfate-free shampoo and body wash lines under REACH-compliant procurement mandates.
- Saponins:Steroidal or triterpenoid glycosides extracted from quillaja bark and yucca root exhibit high surface activity with food-grade safety profiles. Food processing applications in Brazil and India concentrate demand for these emulsifiers where synthetic alternatives face FSSAI and FDA notification barriers.
- Soap:Traditional alkali-fatty acid salts remain cost-dominant in household cleaning formulations with minimal regulatory complexity.
- Lecithin:Phospholipid mixtures from soybean and sunflower sources serve niche pharmaceutical and nutraceutical emulsification with organic certification requirements.
The dominant share belongs to Alkyl Polyglucoside, while Saponins is closing the gap fastest.
End Use Industry:
Regulatory intensity creates tiered market access, with purity documentation requirements segmenting suppliers by certification depth.
- Personal Care:Cleansing and conditioning formulations demand non-irritant surfactants with full feedstock traceability. EU Ecolabel and USDA BioPreferred certification now gate contract access with multinational cosmetics manufacturers in France and Germany.
- Agricultural Chemicals:Biopesticide wetting agents require surfactants that satisfy EPA registration and EU sustainable use directive compliance. Formulators in Brazil and India source natural alternatives as synthetic precursors face aquatic toxicity restrictions.
- Household Detergents:Volume-driven applications prioritize cost-competitive biodegradability over premium certification tiers.
- Food Processing:Emulsifier applications concentrate in dairy alternatives and beverage systems where FDA GRAS and EFSA approvals determine supplier qualification.
Personal Care commands the largest revenue pool, though Agricultural Chemicals exhibits the steepest expansion trajectory.
Form:
Processing economics and formulation compatibility drive physical state selection across liquid-dominant and solid-specialized applications.
- Liquid:Ready-to-dose concentrates minimize handling energy in high-throughput personal care and detergent manufacturing. Continuous processing lines in the Netherlands and Germany favor pumpable alkyl polyglucoside solutions with standardized viscosity profiles.
- Powder:Spray-dried or agglomerated formats reduce transport costs for distant agricultural chemical formulators and enable precise dry-blending in powder detergents.
- Granular:Low-dust, free-flowing particles suit automated dispensing systems in institutional cleaning compound production.
- Paste:High-active concentrates serve specialty cosmetic formulations requiring controlled rheology without additional thickeners.
Liquid forms dominate volume throughput, while Powder formats gain share in export-oriented supply chains.
Application:
Functional performance requirements stratify product selection by interfacial tension reduction mechanism and foam stabilization needs.
- Cleansing Agents:Detergency applications require surfactants that emulsify oils and suspend particulates across variable water hardness. Hard surface and fabric cleaning formulations in institutional and household channels specify alkyl polyglucoside for residue-free performance.
- Emulsifiers:Stabilization of immiscible phases demands HLB-optimized surfactant blends with long-term shelf stability. Food-grade emulsification in plant-based dairy alternatives drives lecithin and saponin specification where label simplicity matters.
- Foaming Agents:Aesthetic and functional foam generation concentrates in personal care shampoos and fire-fighting formulations with protein-based or synthetic-natural hybrid systems.
- Dispersants:Particle suspension in agricultural chemical concentrates and pigment slurries requires surfactants with specific adsorption characteristics on solid surfaces.
Cleansing Agents retains the dominant position, while Emulsifiers is expanding most quickly in food-grade and pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European oleochemical import flows, while Singapore's Jurong Island petrochemical complex mediates Asian palm kernel oil derivative trade. These infrastructure nodes determine regional cost structures for natural surfactant production.
Germany
Rhine-Ruhr specialty chemical producers supply alkyl polyglucoside to domestic cosmetics manufacturers and export customers. ECHA REACH substance evaluation protocols systematically disqualify petrochemical surfactant precursors, redirecting formulation budgets toward plant-derived alternatives. Cologne and Düsseldorf host concentrated personal care R&D operations where clean-label procurement mandates compress supplier qualification cycles.
United States
Midwestern soy-based feedstock partnerships sustain North American natural surfactant supply through proprietary esterification technology. EPA bio-based preferred purchasing programs create qualified demand pools across institutional cleaning and agricultural chemical applications. Chicago and Minneapolis metropolitan areas concentrate formulation houses serving federal procurement contracts.
Indonesia
Palm kernel and coconut oil derivative output expansion reconfigures Southeast Asian oleochemical processing capacity. National biofuel policies and plantation zone development priorities shape export availability for carbohydrate-based surfactant producers. Medan and Surabaya industrial zones host integrated processing facilities serving both domestic and regional customers.
Brazil
Biopesticide formulation growth generates compliant surfactant demand that natural alternatives uniquely satisfy. ANVISA registration requirements and sustainable use directive alignment accelerate agricultural chemical formulator qualification of plant-derived wetting agents. São Paulo state concentrates both formulation R&D and distribution infrastructure for Latin American markets.
India
FSSAI clean-label directives segment market access by purity grade, accelerating alkyl polyglucoside uptake in premium cosmetics. Maharashtra and Gujarat host concentrated personal care manufacturing operations where traceability documentation gates contract execution with multinational brands. Mumbai-Pune industrial corridor suppliers increasingly specify third-party sustainability certification.
Natural Surfactants Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with proprietary glycosidation and esterification expertise. Market structure concentrates among integrated oleochemical producers and specialty chemical houses with captive feedstock arrangements. Three archetypes dominate: European rapeseed-palm supply chain integrators, North American soy-based technology licensors, and Asian plantation-linked derivative processors. Competitive moves center on enzymatic synthesis route licensing and backward integration into plantation or crushing assets.
Among integrated chemical producers, BASF SE and Stepan Company exemplify feedstock-technology coupling archetypes, while Clariant occupies a position within European specialty surfactant formulation. These entities represent contrasting geographic supply chain strategies—German rapeseed-Asian palm integration versus Midwestern soy anchoring—without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Clariant |
| Stepan Company |
| BASF SE |
| WHEATOLEO |
| Kao Corporation |
| Croda International |
| Dow Inc. |
| SEPPIC |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
Indonesia's palm kernel oil concentration ties directly to margin capture by European alkyl polyglucoside producers with integrated crushing assets. Weather volatility in Southeast Asian plantation zones transmits downstream as feedstock cost premiums that formulation houses either absorb or pass to personal care brands.
Pricing Analysis
REACH authorization protocols dictate the pricing tier structure across the European natural surfactant market. Three-tier pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade certification levels, with ECHA aquatic toxicity dossier requirements adding compliance premiums to higher tiers. Cost compression in industrial-grade alkyl polyglucoside is intensifying because Indonesian palm oil supply disruptions compress producer margins. Agricultural chemical formulators in Brazil exhibit highest price sensitivity, while German cosmetics manufacturers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Palm kernel and coconut oil feedstock availability centers on Indonesia, Malaysia, and the Philippines as the primary upstream concentration. Natural surfactant production draws from carbohydrate-based feedstocks, fatty alcohol precursors, and phospholipid mixtures as critical inputs. Single-source vulnerability runs through Rotterdam's liquid bulk terminals as the chokepoint for European oleochemical import flows. Distribution runs through specialty chemical platforms that collapse traditional distributor layers, enabling direct manufacturer access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: REACH-compliant feedstock traceability documentation creates switching costs that lock formulation houses into qualified supplier relationships.
For Market Incumbents: Entrench position through backward integration into plantation or crushing assets in Southeast Asia, securing captive supply against palm oil price volatility. Invest in enzymatic glycosidation reactor retrofitting to collapse energy intensity and defend margin position against microbial fermentation biosurfactant substitutes. Prioritize USDA BioPreferred and EU Ecolabel certification maintenance to sustain contract access with multinational personal care brands. For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial corridor presents underpenetrated white space where FSSAI clean-label directives segment procurement by purity grade. Target agricultural wetting agent applications in Brazil's biopesticide formulation growth as the most penetrable segment with lower certification barriers than personal care. Pursue direct-to-manufacturer digital channel strategies to bypass established distributor networks and access midsize formulation houses. For Investors and Strategic Acquirers: Capital is best deployed toward integrated oleochemical producers with captive European rapeseed-Asian palm supply chains and proprietary esterification technology. Long-term viability hinges on enzymatic synthesis route licensing portfolios that collapse thermochemical processing economics. Watch for carbon border adjustment mechanism implementation signals as the inflection indicator for accelerated plant-derived surfactant demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive palm kernel supply secures margin stability against Indonesian weather volatility. |
| Enzymatic Reactor Retrofitting | Continuous glycosidation collapse energy costs for mid-volume alkyl polyglucoside applications. |
| Biobased Certification Investment | USDA BioPreferred and EU Ecolabel documentation gates multinational cosmetics contract access. |
| Direct-to-Manufacturer Platform Launch | Digital channels bypass distributor layers to reach midsize formulation houses directly. |
| Joint Venture in Agricultural Wetting Agents | Brazil-India biopesticide growth creates compliant surfactant demand natural alternatives uniquely satisfy. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ECHA substance evaluation protocols, customs and trade data, and SEC filings from integrated chemical producers. Interviews with specialty chemical plant managers, personal care procurement leads at multinational brands, agricultural formulation R&D directors, and distribution channel partners inform demand-side validation. Bottom-up segment sizing triangulates against top-down trade flow analysis across the projection horizon.
Forecast inputs incorporate feedstock cost trajectories, regulatory authorization timelines, and end-use industry growth patterns. Segmentation dimensions span product type, end-use industry, physical form, and application function throughout the modeling period. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Palm oil supply volatility and REACH restriction list updates serve as industry-specific forecast sensitivity inputs.
Practitioners should monitor ECHA authorization procedure acceleration and Southeast Asian plantation weather patterns for early signals of forecast revision. Cross-checking against customs import data for oleochemical derivatives is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Benzyl Trimethyl Ammonium Chloride Market
Surfactants
Global Saponin Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Zeolite for Detergents Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Selenium Sulphide Market
Surfactants
Chlorooctane Market
Surfactants
Pharmaceutical Surfactants Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Global Rhamnolipid Market
Surfactants
Micellar Water Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Trisiloxane Market
Surfactants
Secondary Alkane Sulfonate Market