
 Cationic Surfactants Market | 2026-2036
Cationic Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Cationic Surfactants Market Analysis
REACH chemical registration is consolidating the cost-of-entry calculus for European cationic surfactant suppliers. BASF SE leverages its integrated amine chemistry platform to sustain feedstock cost advantages across quaternary ammonium production. Croda International plc anchors its position through specialty esterquat technology leadership in personal care applications. Kao Corporation dominates Asia-Pacific supply chains with captive fatty alcohol production and regional distribution density.
Cationic surfactants carry a positive surface charge at neutral pH, typically derived from quaternary ammonium nitrogen centers with alkyl chain lengths of C12–C18 that confer antimicrobial activity and substrate affinity through electrostatic binding. Manufacturers synthesize these compounds via reductive amination or direct quaternization of tertiary amines with alkyl halides, yielding products with critical micelle concentrations ranging from 0.1 to 1.0 mM for industrial formulation. Quaternary ammonium compounds command the largest volume share as established workhorses in disinfection and fabric softening, while amino acid-based surfactants represent the fastest-growing category as cosmetic manufacturers reformulate around biobased feedstocks and mildness claims. Fatty amines retain mature, cost-driven demand in textile processing and oilfield corrosion inhibition where performance specifications prioritize efficacy over sustainability positioning.
EPA antimicrobial pesticide registration governs quaternary ammonium compound claims in US disinfectant applications, while ECHA REACH compliance mandates full substance dossiers for European market access. China's MEE enforces GB standards for industrial chemical emissions that constrain manufacturing process choices for domestic producers. Stakeholders must monitor evolving biobased content mandates and perfluorinated substance restrictions that will reshape raw material sourcing decisions and product qualification pathways.
Market Dynamics
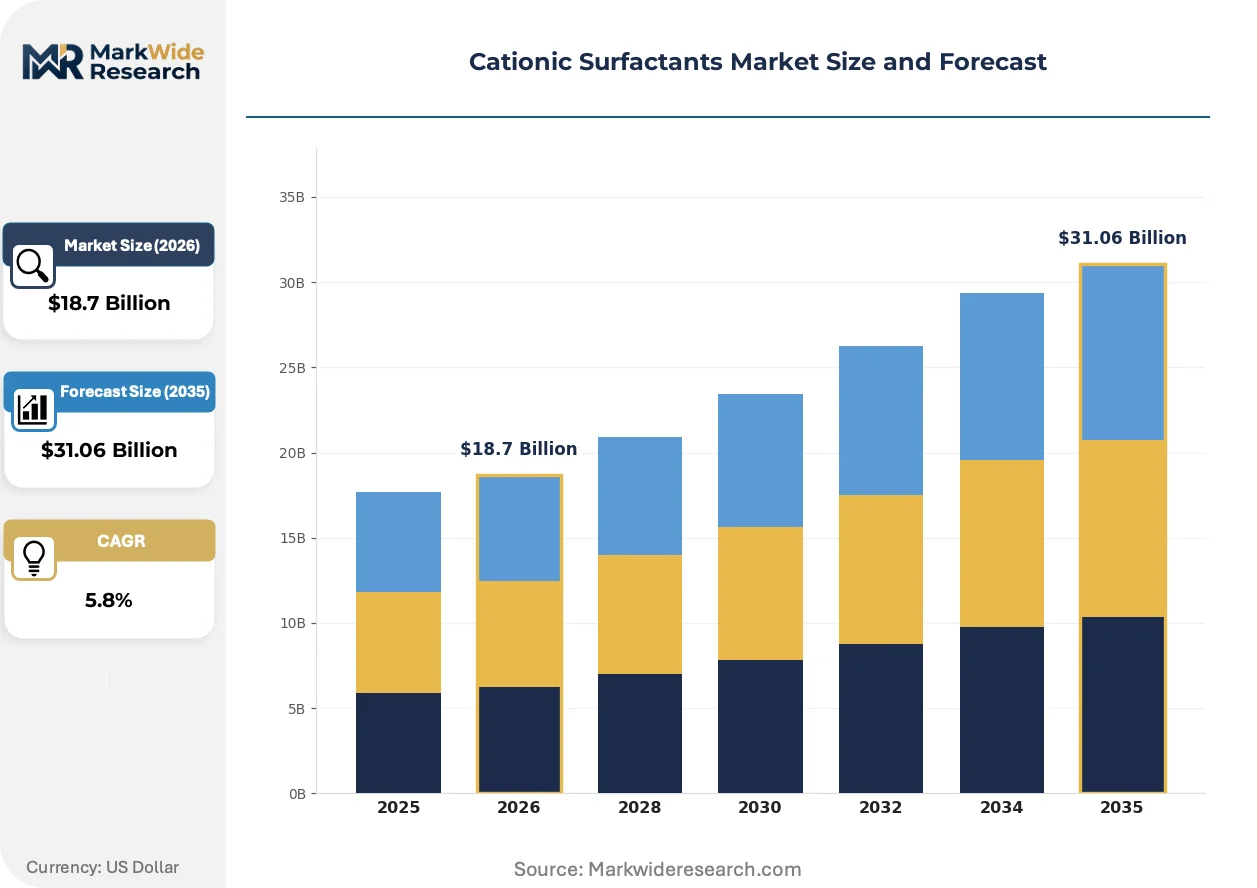
REACH chemical registration in Europe is consolidating supplier economics while Chinese textile processors and oilfield operators drive procurement volume concentration, reshaping competitive positioning around feedstock integration and regional distribution density.
Growth Catalysts
- Quaternary ammonium conditioning demand:Personal care formulators are expanding quaternary ammonium compound use in hair conditioning and skin feel applications, pulling volume through specialty esterquat channels.
- REACH compliance barriers:ECHA substance dossier requirements are filtering out marginal European suppliers, concentrating procurement among integrated amine chemistry platforms with established registration portfolios.
- Chinese industrial scaling:Domestic textile processing and oilfield chemical sectors in China are scaling surfactant procurement, anchoring Asia-Pacific demand concentration.
Market Restraints
- Fatty alcohol feedstock volatility:Palm kernel and coconut oil derivative pricing swings compress margin stability for producers lacking captive fatty alcohol supply.
- Quaternary ammonium substitution pressure:Amino acid-based surfactants are displacing conventional quaternary ammonium compounds in premium cosmetic formulations, threatening volume in high-margin personal care segments.
- EPA antimicrobial registration friction:Pesticide registration timelines for disinfectant claims extend commercialization cycles for new quaternary ammonium entrants in US markets.
Strategic Opportunities
- Biobased feedstock mandates:EU Green Deal biobased content requirements are creating qualification pathways for amino acid-based surfactant producers with certified renewable supply chains.
- India textile processing expansion:BIS standards adoption and domestic textile cluster growth are opening procurement channels for fatty amine suppliers in South Asian markets.
- Esterquat technology convergence:Combination of enzymatic esterification with quaternization chemistry is enabling next-generation conditioning actives with biodegradability credentials.
Industry Challenges
- Process chemistry talent scarcity:Reductive amination and quaternization expertise is concentrating among aging specialist workforces, constraining new facility commissioning.
- Multijurisdictional dossier management:Parallel EPA, ECHA, and MEE registration requirements are fragmenting compliance resources and extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cationic Surfactants Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quaternary Ammonium Compounds, Fatty Amines, Imidazolinium Compounds, Amino Acid-Based Surfactants Application: Personal Care, Household Cleaning, Textile Processing, Oilfield Chemicals End User: Cosmetic Manufacturers, Cleaning Product Companies, Textile Manufacturers, Oil & Gas Industry Packaging Type: Drums, IBC Totes, Bulk Containers, Pails |
| Companies Covered | Clariant AG, Croda International plc, BASF SE, Solvay SA, Nouryon, Stepan Company, Kao Corporation, AkzoNobel, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cationic Surfactants Market Emerging Trajectories
Formulation science is pivoting toward biobased nitrogen chemistry while regulatory frameworks harden around substance transparency, compressing traditional quaternary ammonium market share in premium segments.
Enzymatic esterquat synthesis is modularizing production economics for mid-chain conditioning actives. Specialty personal care manufacturers are adopting these biocatalytic routes at pilot scale. The technology is modularizing batch-size flexibility and enabling distributed manufacturing models that bypass centralized petrochemical infrastructure.
EU F-Gas Regulation and REACH restriction proposals are tightening scrutiny on fluorinated and persistent organic pollutants, extending to surfactant auxiliaries. Industrial formulators must now document substance fate across full lifecycle dossiers. Fabric softener and disinfectant applications face elevated compliance costs as ECHA evaluates quaternary ammonium environmental toxicity profiles.
Direct procurement relationships between personal care brands and biobased surfactant specialists are displacing traditional distributor intermediaries. Tier-one cosmetic houses are establishing preferred supplier programs with amino acid-based surfactant producers holding RSPO and COSMOS certifications. This channel restructuring is most visible in Western European markets where sustainability credentialing commands formulation priority.
Cationic Surfactants Market Segmentation
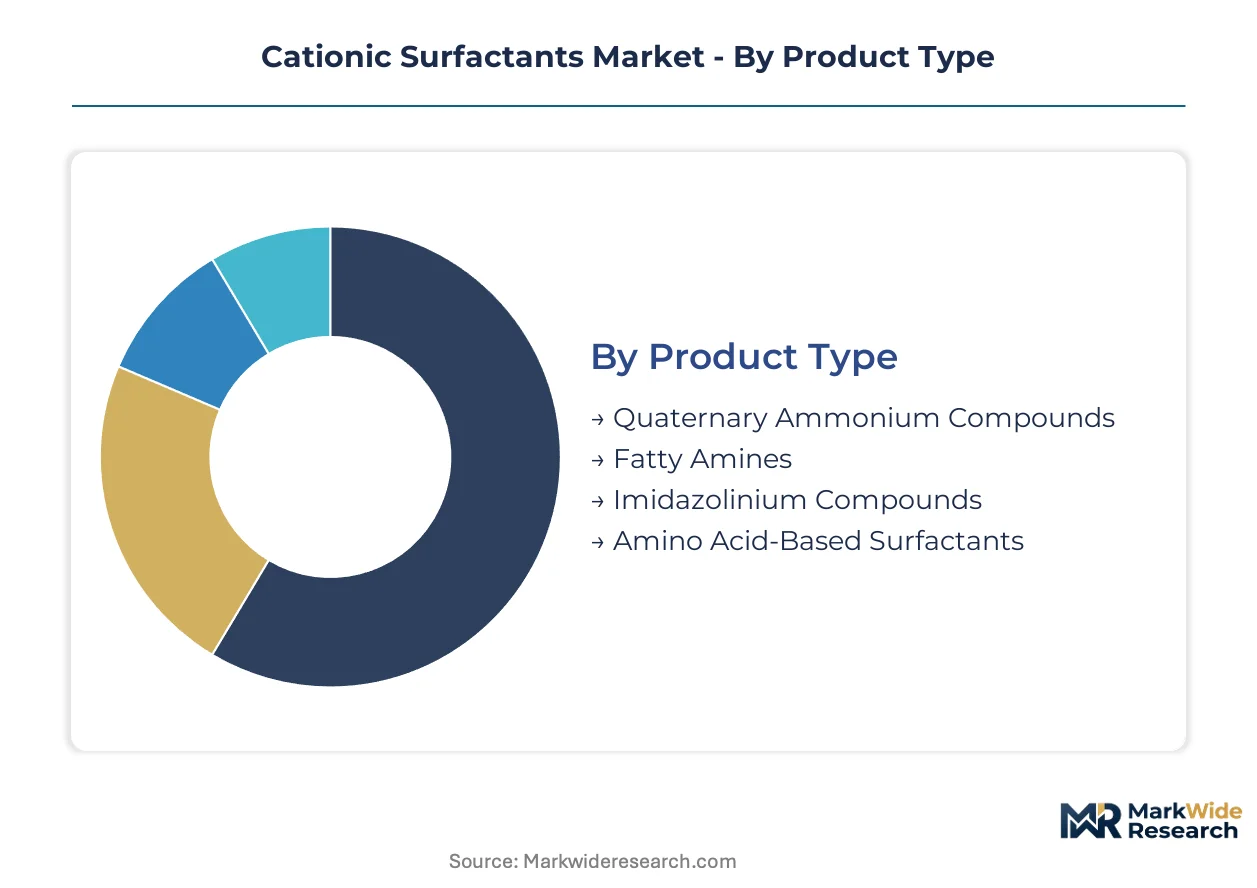
Cationic surfactant procurement patterns diverge sharply across technical specifications and volume tiers. Manufacturers configure production assets around either commodity-scale fatty amine output or specialized esterquat batches for conditioning applications.
Product Type:
Customization intensity varies from standardized quaternary ammonium bulk to precision-engineered amino acid derivatives requiring certified biobased feedstocks.
- Quaternary Ammonium Compounds:These nitrogen-centered surfactants with C12–C18 alkyl chains deliver antimicrobial efficacy through electrostatic substrate binding. Demand concentrates in US disinfectant formulations where EPA pesticide registration governs commercial claims, though registration timelines extend new entrant cycles.
- Amino Acid-Based Surfactants:Biobased nitrogen chemistry derived from renewable amino acid feedstocks enables mildness positioning in premium cosmetic formulations. Procurement from Western European cosmetic houses is climbing fastest as EU Green Deal biobased mandates reshape qualification pathways.
- Fatty Amines:Mature cost-driven chemistry for textile softening and oilfield corrosion inhibition where performance trumps sustainability credentials.
- Imidazolinium Compounds:Cyclic cationic structures serving niche fabric softener and asphalt emulsifier applications with limited volume scale.
Most installed capacity flows through Quaternary Ammonium Compounds. Expansion is steepest in Amino Acid-Based Surfactants.
Application:
Margin structures separate high-value personal care conditioning from commodity-scale industrial processing chemicals.
- Personal Care:Hair conditioning and skin-feel applications pull specialty esterquat volumes through reformulation cycles targeting mildness claims. Procurement from tier-one cosmetic houses in France and Germany is accelerating as RSPO and COSMOS certifications become formulation gatekeepers.
- Textile Processing:Fabric softening and dye-leveling applications in China's Zhejiang and Jiangsu provinces anchor regional demand concentration for fatty amine derivatives.
- Household Cleaning:Disinfectant and surface care formulations utilizing quaternary ammonium biocides face ECHA environmental toxicity scrutiny in European markets.
- Oilfield Chemicals:Corrosion inhibition and drilling fluid applications in Sichuan and Xinjiang basins drive procurement of cost-optimized fatty amine chemistry.
Volume concentrates in Textile Processing. Value capture is highest in Personal Care.
End User:
Customer scale fragments from multinational cosmetic houses to dispersed textile processing clusters.
- Cosmetic Manufacturers:Direct procurement relationships with biobased surfactant specialists are displacing traditional distributor channels. Esterquat producers with enzymatic synthesis capabilities command preferred supplier status.
- Textile Manufacturers:China's domestic processing sector scales surfactant procurement through consolidated purchasing cooperatives in Shaoxing and Huzhou clusters.
- Cleaning Product Companies:Formulators balance EPA registration requirements against amino acid-based substitution pressure in premium positioning tiers.
- Oil & Gas Industry:State-owned operators in China's Sichuan shale plays specify fatty amine chemistry for corrosion inhibition with limited sustainability compliance burden.
Contract structures are tightest with Cosmetic Manufacturers. Payment cycles are longest with Oil & Gas Industry.
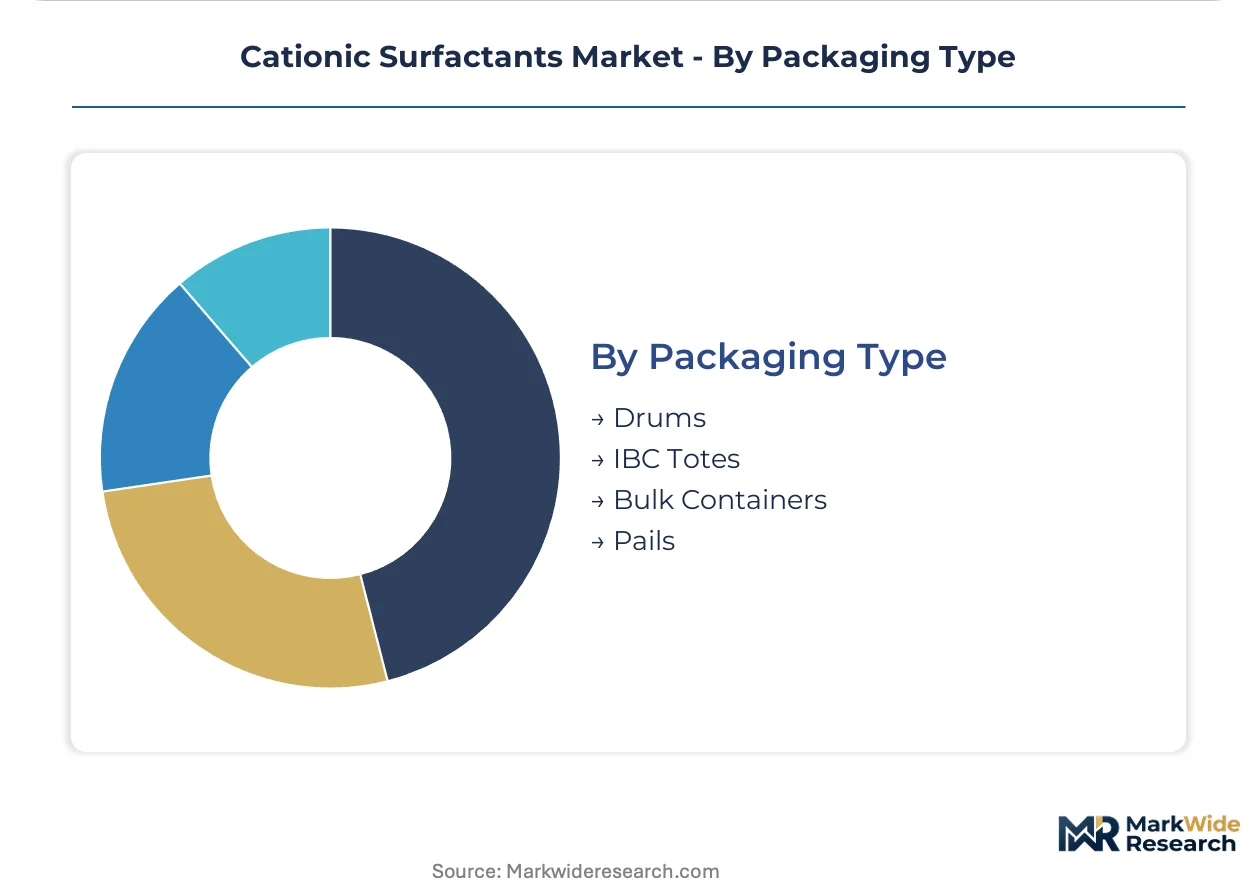
Packaging Type:
Logistics economics separate bulk tanker deliveries from drum-scale distributed manufacturing.
- Drums:Standard 200-liter steel packaging for mid-volume personal care and specialty chemical shipments requiring formulation flexibility.
- IBC Totes:Intermediate bulk containers serving textile processors and cleaning product manufacturers with moderate throughput and storage constraints.
- Bulk Containers:Tanker and ISO-tank configurations for oilfield chemical operators and large textile processors with dedicated unloading infrastructure.
- Pails:Small-volume packaging for pilot-scale cosmetic formulation and laboratory sampling requirements.
Shipment frequency is highest in Drums. Unit logistics cost is lowest in Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering established cationic surfactant synthesis protocols during the early twentieth century, with BASF SE's Ludwigshafen complex pioneering quaternary ammonium production at industrial scale. Contemporary demand geography reflects this technical heritage while shifting toward Asian manufacturing concentration.
United States
EPA antimicrobial pesticide registration governs quaternary ammonium compound claims in disinfectant formulations, extending commercialization timelines for new entrants. The agency's Office of Pesticide Programs maintains stringent efficacy and toxicity dossier requirements. Houston-Gulf Coast petrochemical corridors supply fatty alcohol feedstocks to domestic esterquat producers serving personal care formulators.
Germany
ECHA REACH compliance mandates full substance dossiers for European market access, consolidating procurement among integrated amine chemistry platforms with established registration portfolios. The EU Green Deal's biobased content requirements are reshaping qualification pathways for surfactant producers. Ludwigshafen and Marl chemical parks anchor quaternary ammonium manufacturing with backward integration into captive fatty amine supply.
China
MEE enforces GB standards for industrial chemical emissions that constrain manufacturing process choices for domestic producers. Dual carbon goals are accelerating process efficiency investments in Zhejiang and Jiangsu textile processing clusters. Shaoxing and Huzhou purchasing cooperatives consolidate fatty amine procurement for fabric softening applications.
India
BIS standards adoption and domestic textile cluster growth are opening procurement channels for fatty amine suppliers in South Asian markets. The PLI scheme for chemicals incentivizes capacity expansion in specialty surfactant manufacturing. Gujarat's chemical belt near Vadodara and Ankleshwar is attracting esterquat investment targeting cosmetic export qualification.
Japan
METI industrial chemical guidelines emphasize biodegradability credentials for surfactant applications in sensitive aquatic environments. JIS standards govern quality specifications for personal care and textile processing formulations. Osaka-Kansai chemical manufacturers maintain premium positioning in amino acid-based surfactant technology for cosmetic applications.
Cationic Surfactants Market Vendor Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive amine chemistry platforms. Tier-one suppliers with backward integration into fatty alcohol production command margin stability against feedstock volatility. Three archetypes dominate: European diversified chemical majors with REACH registration portfolios, Asia-Pacific regional champions with distribution density, and specialty esterquat innovators targeting premium personal care. Dominant competitive moves include enzymatic process licensing partnerships and direct procurement relationship establishment with tier-one cosmetic houses.
Among European diversified majors, BASF SE, Clariant AG, and Evonik Industries AG occupy positions anchored by Ludwigshafen and Marl production infrastructure with decades-long REACH dossier accumulation. Croda International plc exemplifies the specialty esterquat archetype through its documented technology leadership in personal care conditioning applications. Kao Corporation represents Asia-Pacific regional density with its established supply chain presence across Japanese and Chinese procurement channels.
| Leading Market Players |
|---|
| Clariant AG |
| Croda International plc |
| BASF SE |
| Solvay SA |
| Nouryon |
| Stepan Company |
| Kao Corporation |
| AkzoNobel |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
China's textile processing cooperatives in Shaoxing and Huzhou anchor procurement volume concentration, forcing three-tier pricing stratification across premium esterquat, standard quaternary ammonium, and economy fatty amine grades. Contract structures reward backward-integrated suppliers with captive fatty alcohol production while spot-market buyers absorb palm kernel oil volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RSPO-certified esterquat producers from commodity quaternary ammonium manufacturers and cost-optimized fatty amine suppliers. Price differentiation hinges on biobased certification tier and volume scale, with cosmetic houses paying premiums for enzymatic synthesis credentials. Cost compression in standard-grade quaternary ammonium is intensifying because Chinese textile processors are consolidating purchasing cooperatives. Oilfield chemical operators exhibit highest price sensitivity due to specification-driven procurement, while tier-one cosmetic manufacturers prioritize mildness claims over unit economics.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Singapore, and Shanghai coordinate hub-and-spoke patterns for drum-scale and bulk-tanker deliveries. Manufacturing concentrates in Germany, China, and Japan, with fatty alcohol feedstocks drawing from Malaysian and Indonesian palm kernel oil processing. Supply chain risk centers on single-source vulnerability for specialty amine intermediates used in esterquat production. Distribution runs through integrated chemical majors with captive logistics networks and established REACH dossier management capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cationic surfactants market represents a late-cycle quality story as personal care formulators pivot procurement toward amino acid-based surfactants with documented biodegradability credentials.
For Market Incumbents: Anchor market position through enzymatic esterquat technology licensing partnerships that preempt amino acid-based substitution in premium conditioning segments. Deepen backward integration into captive fatty alcohol supply to insulate margin stability against palm kernel oil price swings. Prioritize REACH dossier accumulation for next-generation quaternary ammonium variants before ECHA environmental toxicity restrictions harden. For New Entrants and Emerging Players: Direct-to-cosmetic-brand digital procurement platforms bypass traditional distributor intermediaries in Western European markets where RSPO and COSMOS certifications command formulation priority. Target India's Gujarat chemical belt expansion under PLI scheme incentives as the most penetrable geography for esterquat capacity qualification. Lead with certified biobased supply chain transparency as the primary go-to-market angle. For Investors and Strategic Acquirers: Specialty chemical conglomerates with personal care divisions are the most active acquirer in this space, seeking enzymatic synthesis capabilities and established cosmetic house relationships. The acquisition target archetype combines mid-scale esterquat production with RSPO-certified feedstock sourcing. Watch for ECHA restriction proposals on quaternary ammonium environmental toxicity as the inflection indicator for accelerated amino acid-based surfactant substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Alcohol Supply | BASF SE and Kao Corporation leverage captive palm kernel oil processing to stabilize margin structures against commodity volatility. |
| Enzymatic Esterquat Technology Licensing | Croda International plc partners with specialty manufacturers to modularize batch-size flexibility for distributed cosmetic production. |
| REACH Dossier Accumulation for Next-Generation Quaternary Ammonium | European suppliers preempt ECHA environmental toxicity scrutiny through early substance registration portfolios. |
| Direct Procurement Relationship Establishment with Tier-One Cosmetic Houses | Amino acid-based surfactant specialists displace traditional distributors by holding RSPO and COSMOS certifications. |
| India Capacity Expansion Under PLI Scheme Incentives | Gujarat chemical belt investments target cosmetic export qualification for South Asian market penetration. |
Methodological Framework
Bottom-up personal care and textile processing modeling reconciled against top-down fatty amine and quaternary ammonium production tracking forms the analytical core. Primary interviews with plant managers at integrated chemical complexes, procurement leads at Chinese textile cooperatives, technical R&D directors at esterquat innovators, and regulatory affairs specialists at ECHA-registered suppliers combined with secondary validation. Secondary sources include customs and trade data from German and Chinese export authorities, Cefic and ACC industry reports, SEC 10-K filings from listed chemical majors, and ECHA substance dossier databases.
Input-output matrices connect feedstock pricing indices for palm kernel and coconut oil derivatives against installed capacity utilization rates across Ludwigshafen, Marl, Zhejiang, and Jiangsu production hubs. Segmentation dimensions span product type tier, application intensity, end-user scale, and regional regulatory cluster. CAGRs derive from production volume trajectories mapped against formulation substitution elasticities in personal care and industrial end-uses. Forecast inputs incorporate enzymatic synthesis adoption curves and biobased content mandate compliance timelines across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for biocatalytic esterquat production would alter the outlook if enzymatic cost structures fail to achieve parity with conventional quaternary ammonium chemistry. Forecasts reflect documented assumptions around REACH registration timelines, ECHA restriction proposal implementation, and Chinese dual carbon policy enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Tetrabutylammonium Bromide Market
Surfactants
Dodecanol Market
Surfactants
Cetyl Chloride Market
Surfactants
Dioctyl Sulfosuccinates Components Market
Surfactants
Global Detergents Market
Surfactants
TEA Esterquats Market
Surfactants
Zeolite for Detergents Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Wax Emulsion Market
Surfactants
Global Barium Petroleum Sulfonate Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
Global Silicone Surfactants Market