
 Electric Vehicle High Voltage Connector System Market | 2026-2036
Electric Vehicle High Voltage Connector System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle High Voltage Connector System Market Insights
Skilled electromechanical engineering talent is collapsing across Central European manufacturing hubs, forcing connector suppliers to restructure hiring pipelines and automate assembly lines. TE Connectivity leverages its captive wire-harness operations to anchor vertical control over high-voltage subsystem integration. Yazaki Corporation competes through dedicated R&D centers in Japan that specialize in thermal-resistant polymer compounds for 800V applications. Sumitomo Electric Industries dominates submarine-cable-derived expertise, extending that knowledge into liquid-cooled EV interconnect architectures.
Electric Vehicle High Voltage Connector Systems comprise shielded conductive assemblies rated between 400V and 1000V DC, engineered from copper alloys with silver-plated contacts and high-grade thermoplastic housings to manage arcing resistance and electromagnetic interference during energy transfer between battery packs, inverters, and motors. DC Connector configurations lead volume deployment as OEMs standardize on direct-current fast-charging interfaces, while Liquid Cooling technology commands premium positioning due to thermal dissipation requirements at elevated amperage levels. Charging Infrastructure end users represent the fastest-growing demand pool as utility-backed station networks expand beyond metropolitan cores.
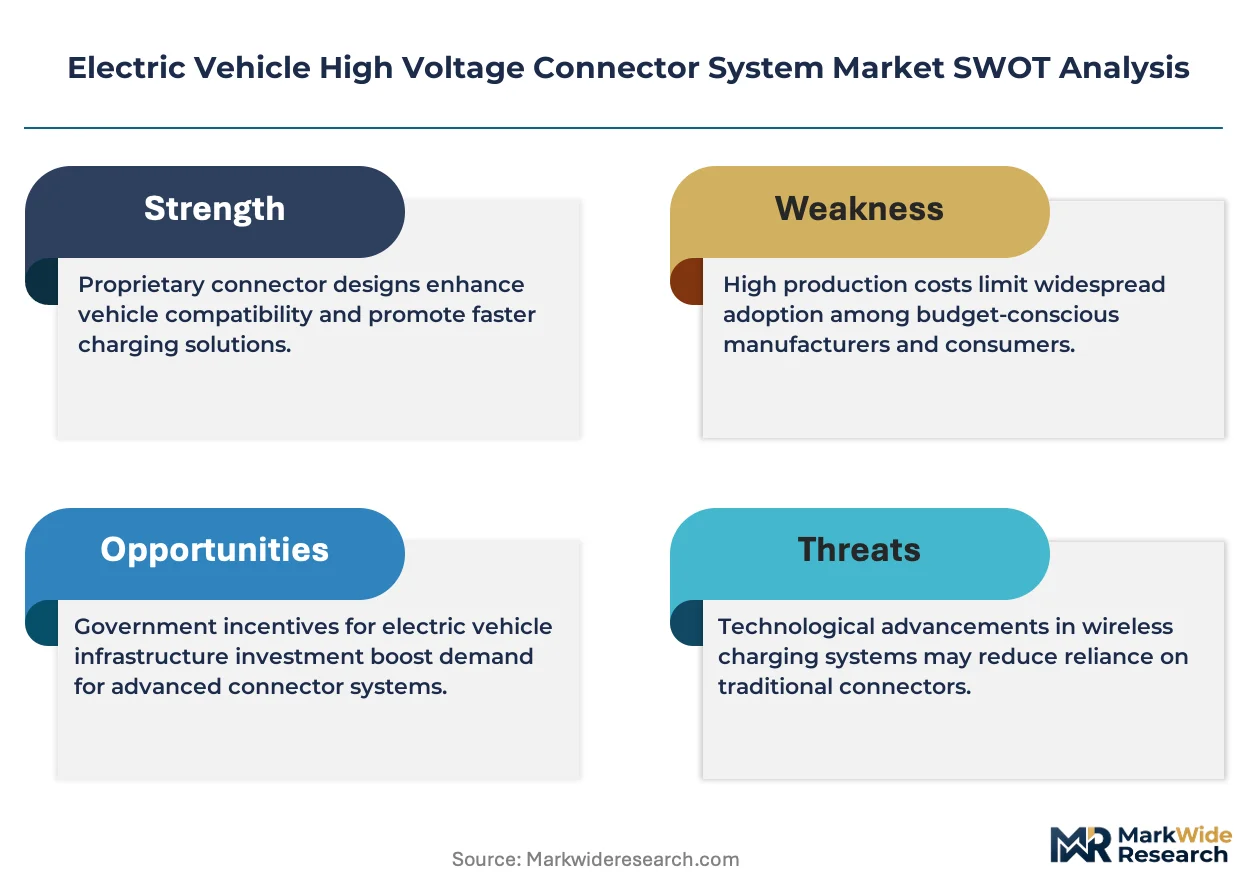
FDA oversight of electromagnetic compatibility in medical-adjacent mobility applications, EPA tailpipe-equivalent emissions frameworks for commercial EV fleets, and NHTSA Federal Motor Vehicle Safety Standards governing high-voltage isolation all shape product certification pathways and market access thresholds for connector manufacturers. China's SAMR enforces GB/T 20234 charging interface standards that dictate pin geometry and current ratings for vehicles sold domestically. Stakeholders must monitor evolving interoperability mandates across regulatory jurisdictions to anticipate redesign cycles and qualification timelines.
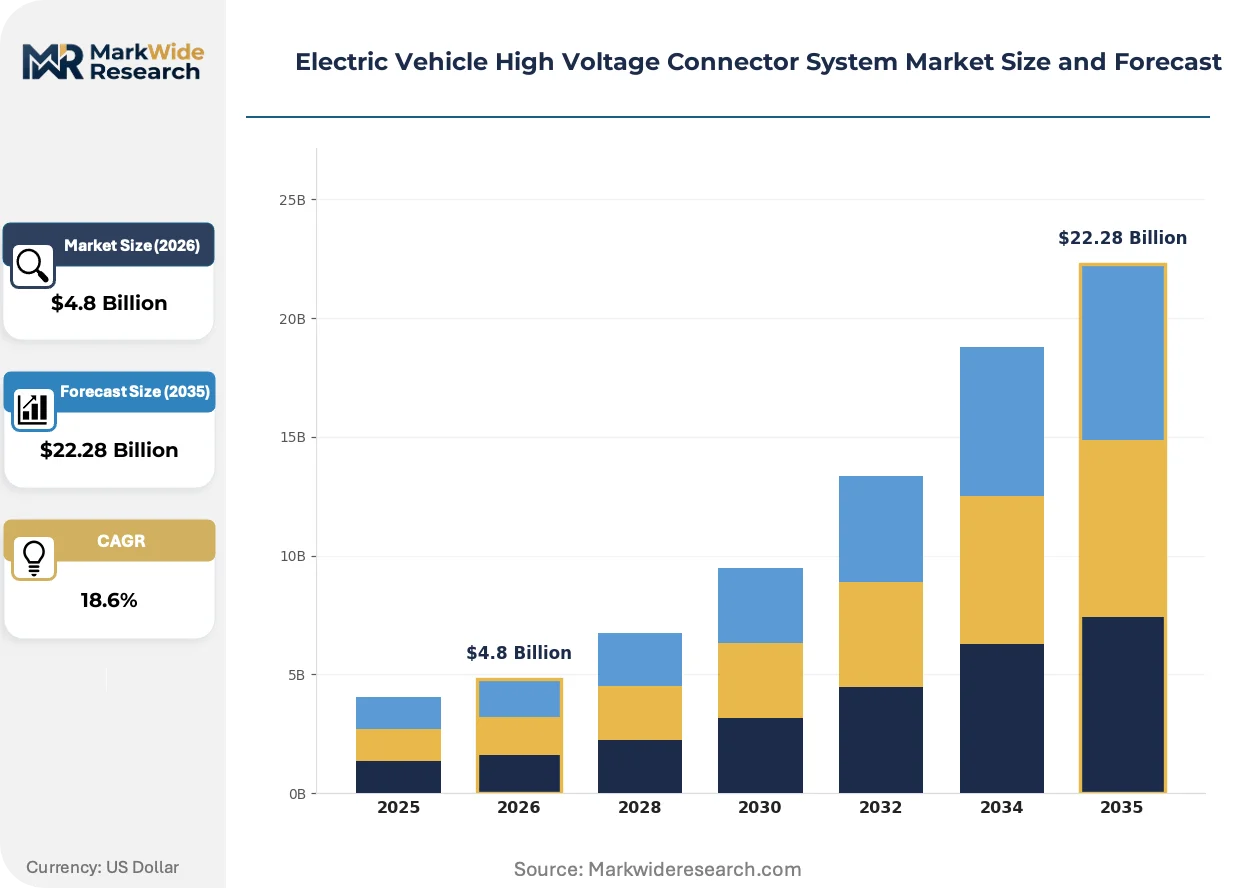
Market Dynamics
The transition to 800V architectures is compressing connector qualification timelines and forcing simultaneous redesigns across battery, inverter, and charging subsystems. Tier-1 suppliers must validate thermal cycling performance under GB/T 20234 pin geometries while scaling liquid-cooled production lines for premium passenger platforms.
Growth Catalysts
- GB/T 20234 mandates:China's SAMR enforces domestic charging interface standards that lock foreign suppliers into local certification partnerships, creating captive demand for qualified connector assemblies.
- Utility-backed station networks:Charging infrastructure operators in Germany, China, and the United States are procuring high-amperage DC connectors for corridor fast-charging deployments beyond metropolitan cores.
- Copper-silver plating:Contact metallurgy advances are extending cycle life under 800V arcing conditions, enabling OEMs to reduce warranty reserves on high-voltage interconnects.
Market Restraints
- Silver price volatility:Contact plating costs fluctuate with precious metals markets, compressing margins on high-current connector families where silver thickness specifications are non-negotiable.
- Central European talent scarcity:Electromechanical engineering graduates in Germany and Poland are declining, forcing suppliers to automate assembly or relocate technical centers.
- Silicon carbide inverter compatibility:Faster switching frequencies in SiC-based power electronics generate electromagnetic interference that legacy shielding designs cannot attenuate without complete connector redesign.
Strategic Opportunities
- Commercial fleet electrification:EPA tailpipe-equivalent frameworks for heavy-duty trucks are mandating high-voltage architectures that require ruggedized connector variants with enhanced vibration resistance.
- Second-life battery storage:Grid-scale stationary systems repurpose automotive connector platforms, opening aftermarket demand for refurbished high-voltage interconnects with modified current derating.
- ISO 6469-3 convergence:International safety standards for electric road vehicles are harmonizing isolation requirements across jurisdictions, enabling single-SKU strategies for export-oriented suppliers.
Industry Challenges
- 800V thermal management expertise:Liquid-cooled connector design requires computational fluid dynamics capabilities that reside in fewer than twelve specialized engineering groups worldwide.
- Cross-jurisdiction certification lag:Simultaneous NHTSA FMVSS 305, ECE R100, and GB/T qualification cycles extend product launch timelines by fourteen to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle High Voltage Connector System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Connector, AC Connector, Vehicle-to-Grid, Charging Adapter Application: Battery Charging, Energy Transfer, Data Communication, Thermal Management End User: OEMs, Aftermarket Providers, Fleet Operators, Charging Infrastructure Technology: Liquid Cooling, Mechanical Locking, Wireless Charging, Rapid Charging |
| Companies Covered | TE Connectivity, Yazaki Corporation, Aptiv PLC, Sumitomo Electric Industries, Amphenol Corporation, Molex LLC, Hirose Electric Co., Ltd., Rosenberger Group, Leoni AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle High Voltage Connector System Market Trends and Innovations
Connector architectures are fragmenting along voltage-tier lines as 400V mass-market platforms and 800V premium systems diverge in thermal and shielding requirements. Suppliers must maintain parallel development tracks without economies of scale crossover.
Polymer housings are bifurcating between cost-optimized PBT compounds for 400V applications and high-heat PPS formulations rated for continuous 180°C operation in 800V liquid-cooled assemblies. European OEMs are specifying the latter for next-generation performance sedans, compressing the addressable market for mid-tier thermal plastics and forcing compounders to license flame-retardant additive packages from aerospace suppliers.
NHTSA Federal Motor Vehicle Safety Standard 305 governs high-voltage isolation integrity during crash events, mandating connector position retention and automatic disconnection protocols. The regulation has triggered redesigns of underfloor battery pack interconnects, with suppliers relocating latching mechanisms to protected structural zones. Commercial vehicle platforms face the most severe compliance burden due to higher pack voltages and ground clearance constraints.
Fleet procurement offices are consolidating connector specifications across multiple vehicle programs to extract volume pricing from tier-1 suppliers. This concentration is displacing program-specific engineering relationships in favor of framework agreements covering five-to-seven year horizons. The shift is most pronounced in Germany's automotive manufacturing corridor, where OEM purchasing alliances are standardizing on two preferred connector families for 400V and 800V tiers respectively.
Electric Vehicle High Voltage Connector System Market Segmentation
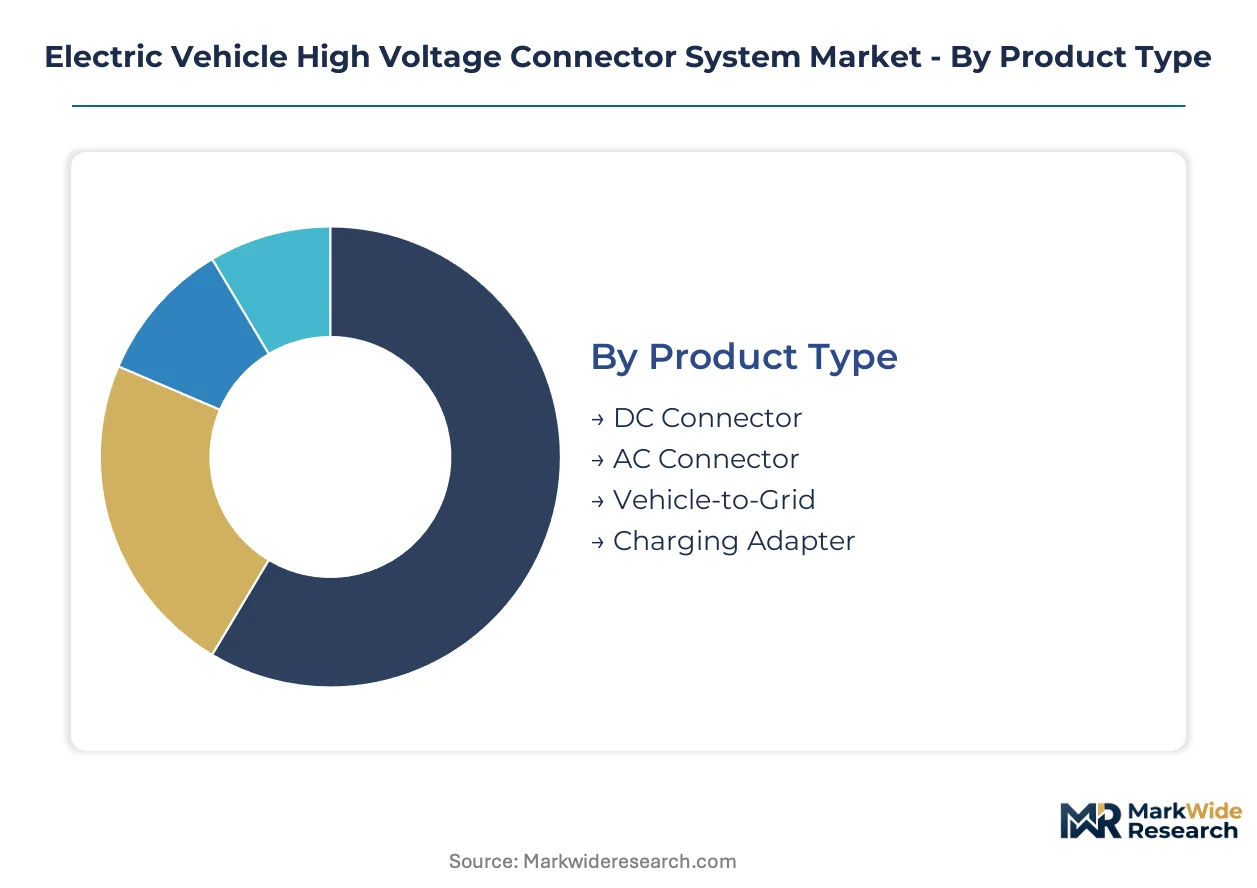
High-voltage connector procurement splits along voltage-tier lines, with 400V and 800V architectures demanding incompatible thermal and shielding specifications. Regulatory mandates from NHTSA, ECE R100, and China's SAMR enforce divergent certification pathways that segment supplier capabilities and lock in design choices.
Product Type:
NHTSA FMVSS 305 isolation requirements and ECE R100 pin-geometry standards create divergent compliance burdens across connector families, favoring suppliers with multi-jurisdiction qualification experience.
- DC Connector:Shielded conductive assemblies rated 400V-1000V DC with silver-plated copper contacts manage arcing resistance during fast-charging cycles. Procurement concentrates among German OEMs localizing 800V supply chains, driven by corridor charging network expansion beyond metropolitan cores.
- AC Connector:Lower-amperage interfaces for residential and workplace Level 2 charging employ simplified thermal management. Established volume favors this segment; emerging adoption favors DC Connector variants as utility-backed fast-charging networks proliferate.
- Vehicle-to-Grid:Bidirectional power flow interfaces enabling battery discharge into grid infrastructure.
- Charging Adapter:Interoperability bridges between regional connector standards.
Cost-tier differentiation separates premium liquid-cooled DC assemblies from commodity AC residential units.
Application:
Battery pack interconnects command the highest thermal cycling validation requirements, while data communication channels face electromagnetic compatibility thresholds from silicon carbide inverter switching frequencies.
- Battery Charging:Direct-current interfaces between external charging infrastructure and onboard battery management systems. German manufacturing corridors and China's NMPA-certified production zones concentrate procurement, constrained by GB/T 20234 pin-geometry mandates.
- Energy Transfer:High-voltage bus connections between battery packs, inverters, and traction motors. Volume clusters in 800V premium passenger platforms where OEMs specify PPS polymer housings rated for continuous 180°C operation.
- Data Communication:Low-voltage signal paths for battery state monitoring and fault diagnostics.
- Thermal Management:Integrated cooling channel architectures for elevated amperage handling.
Performance-tier procurement favors Battery Charging for warranty-critical applications; fleet standardization favors Energy Transfer for multi-vehicle platform consolidation.
End User:
Customer-type concentration determines volume pricing leverage, with framework agreements displacing program-specific engineering relationships across five-to-seven year horizons.
- OEMs:Original equipment manufacturers specifying connector families across vehicle platforms. Germany's automotive manufacturing corridor anchors procurement, with purchasing alliances consolidating specifications onto two preferred connector families for 400V and 800V tiers respectively.
- Charging Infrastructure:Utility-backed station network operators procuring high-amperage DC connectors for corridor deployments. This segment climbs the fastest as operators expand beyond metropolitan cores in the United States, Germany, and China.
- Aftermarket Providers:Replacement part distributors serving repair networks and second-life battery repurposing.
- Fleet Operators:Commercial vehicle procurement offices consolidating specifications across heavy-duty truck and bus programs.
Long-term contracting favors OEMs; spot procurement flexibility favors Aftermarket Providers.
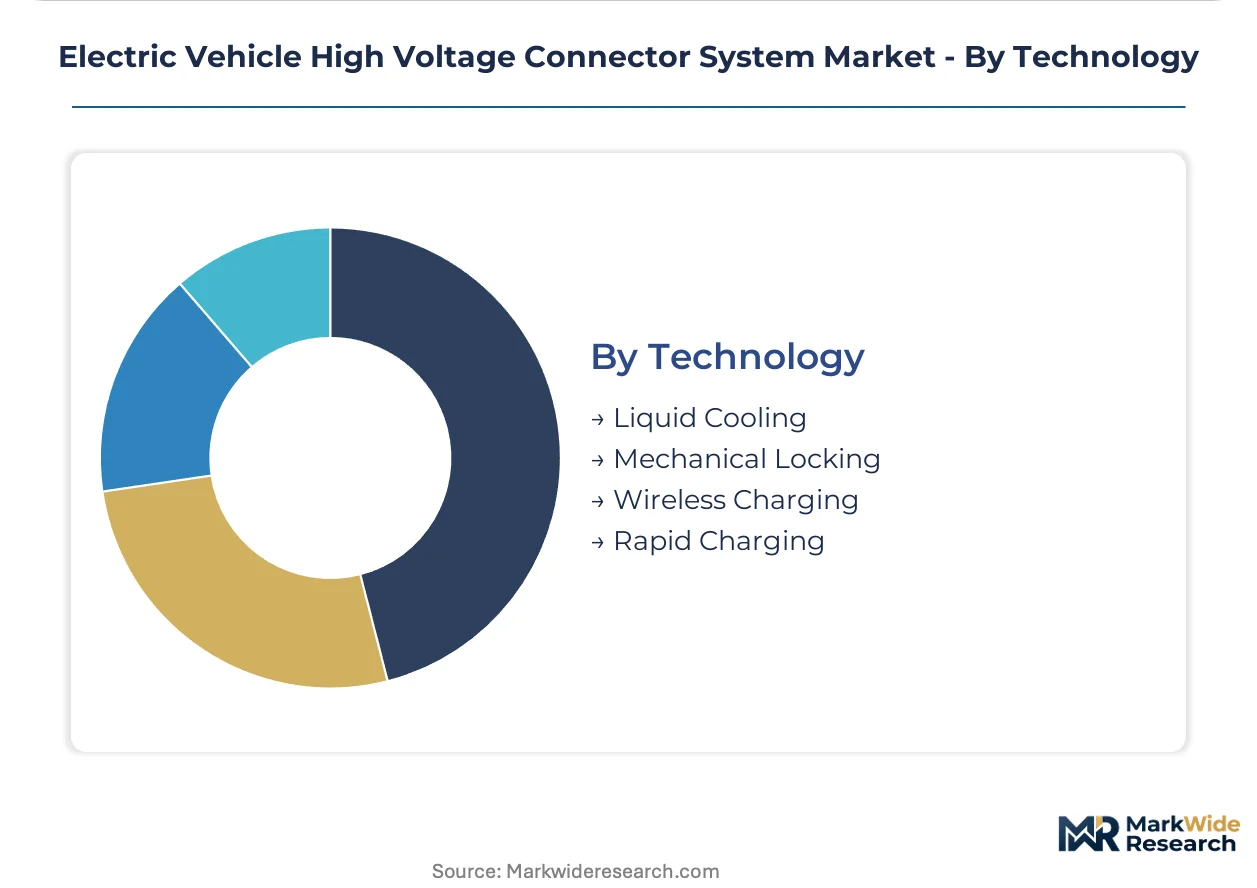
Technology:
Supply concentration for liquid-cooled expertise resides in fewer than twelve specialized engineering groups worldwide, creating capability scarcity for premium thermal management solutions.
- Liquid Cooling:Computational fluid dynamics-optimized channel architectures dissipating heat at elevated amperage levels. Premium passenger EV platforms in Germany specify these assemblies, constrained by scarce thermal engineering talent across Central European manufacturing hubs.
- Rapid Charging:High-current interfaces enabling sub-20-minute charge cycles. Demand concentrates among charging infrastructure operators deploying corridor fast-charging networks, driven by EPA tailpipe-equivalent frameworks for commercial fleet electrification.
- Mechanical Locking:Latching mechanisms ensuring position retention during crash events per NHTSA FMVSS 305.
- Wireless Charging:Inductive power transfer eliminating physical connector interfaces.
Maturity-stage deployment favors Mechanical Locking; technology-transition investment favors Liquid Cooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforces GB/T 20234 charging interface standards that dictate pin geometry and current ratings for vehicles sold domestically. Connector procurement concentrates in manufacturing corridors where OEMs localize supply chains for next-generation electric platforms. Regulatory mandates from NHTSA, ECE R100, and China's SAMR enforce divergent certification pathways that segment supplier capabilities.
China
Domestic EV production volumes drive connector demand across Yangtze River Delta manufacturing zones. SAMR certification requirements for GB/T 20234 pin geometries lock foreign suppliers into local partnership structures. Shenzhen and Shanghai anchor high-voltage subsystem assembly operations for premium passenger platforms.
Germany
OEM purchasing alliances consolidate specifications onto preferred connector families for 400V and 800V tiers respectively. KBA type-approval processes enforce ECE R100 compliance for high-voltage isolation integrity. Bavaria's automotive manufacturing corridor hosts localized supply chain operations for next-generation electric platforms.
United States
NHTSA Federal Motor Vehicle Safety Standard 305 mandates connector position retention and automatic disconnection protocols during crash events. EPA tailpipe-equivalent emissions frameworks for commercial fleets accelerate heavy-duty truck electrification programs. Michigan and California anchor battery pack interconnect procurement for domestic OEM platforms.
Japan
METI industrial policy supports domestic connector R&D for thermal-resistant polymer compounds in 800V applications. JIS standards govern electromagnetic compatibility thresholds for silicon carbide inverter integration. Nagoya and Tokyo metropolitan areas concentrate electromechanical engineering talent for liquid-cooled architecture development.
South Korea
MFDS-equivalent automotive safety mandates align with international isolation standards for export-oriented vehicle programs. Domestic battery manufacturers drive procurement of high-amperage DC connectors for integrated cell-to-pack architectures. Seoul Capital Area hosts tier-1 supplier technical centers serving Hyundai-Kia electric platform requirements.
Electric Vehicle High Voltage Connector System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the competitive landscape. The vendor base organizes around three strategic tiers: diversified electrical component conglomerates with captive wire-harness operations, specialized connector manufacturers with dedicated polymer R&D capabilities, and scale-driven automotive suppliers with integrated vehicle-electronics portfolios. Competitive dynamics center on backward integration into contact metallurgy and upstream control over thermal management engineering talent.
Among diversified electrical component conglomerates, TE Connectivity and Yazaki Corporation occupy positions exemplifying vertical integration strategies. Sumitomo Electric Industries represents the specialized engineering archetype with cable-derived expertise extending into liquid-cooled interconnect architectures. These three companies anchor the competitive structure by demonstrating distinct pathways to capability accumulation in high-voltage thermal management and multi-jurisdiction certification compliance.
| Leading Market Players |
|---|
| TE Connectivity |
| Yazaki Corporation |
| Aptiv PLC |
| Sumitomo Electric Industries |
| Amphenol Corporation |
| Molex LLC |
| Hirose Electric Co., Ltd. |
| Rosenberger Group |
| Leoni AG |
| Others |
Pricing and Supply Chain Analysis
Long-term framework agreements spanning five-to-seven years lock in both supply access and price visibility for German OEM purchasing alliances consolidating connector specifications across 400V and 800V tiers. These contracts insulate tier-1 suppliers from silver price volatility while committing volume to localized production corridors in Bavaria and the Yangtze River Delta.
Pricing Analysis
Price spreads between German-manufactured liquid-cooled assemblies and Chinese-produced AC connectors reflect certification-grade differentiation and thermal management complexity. Three-tier pricing structure across premium liquid-cooled, standard DC fast-charging, and economy AC residential levels stratifies by GB/T 20234 and ECE R100 qualification status. Pricing pressure stems from silver plating cost volatility and Central European electromechanical engineering wage inflation. Fleet procurement offices exhibit highest price sensitivity through consolidated multi-vehicle specifications, while premium passenger EV platforms prioritize thermal performance over unit cost.
Supply Chain Analysis
China and Germany anchor high-voltage connector assembly operations, with Japan and South Korea feeding specialized polymer compounds and precision contact metallurgy. Supply chains draw from copper alloy smelters in Chile, silver refineries in Mexico, and PPS resin producers in the United States. Single-source vulnerability concentrates in liquid-cooled thermal management engineering groups numbering fewer than twelve worldwide. Distribution runs through captive wire-harness operations at diversified electrical conglomerates and tier-1 automotive supplier technical centers serving OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 800V architecture transition constitutes a high-growth disruption reshaping competitive positioning, with silicon carbide inverter proliferation forcing complete connector redesign cycles and compressing qualification timelines by fourteen to eighteen months.
For Market Incumbents: Compound defensive moats through backward integration into silver-plated contact metallurgy and captive production of PPS polymer housings rated for continuous 180°C operation. Lock in scarce liquid-cooled thermal engineering talent through dedicated R&D center investments in Nagoya and Munich. Prioritize simultaneous NHTSA FMVSS 305, ECE R100, and GB/T qualification to maintain multi-jurisdiction certification leadership against emerging Asian challengers. For New Entrants and Emerging Players: GB/T 20234 fast-track certification partnerships with China's SAMR unlock access to Yangtze River Delta manufacturing zones where domestic EV production volumes concentrate. Target second-life battery storage interconnect refurbishment for grid-scale stationary systems, a white-space segment with modified current derating requirements and lower barrier to entry. Pursue charging infrastructure operator procurement offices expanding corridor fast-charging networks beyond metropolitan cores in the United States and Germany. For Investors and Strategic Acquirers: Capital is best deployed toward specialized connector manufacturers with dedicated polymer R&D capabilities and existing liquid-cooled architecture expertise. Long-term viability over the next decade hinges on positioning ahead of ISO 6469-3 harmonization enabling single-SKU export strategies. Monitor EPA tailpipe-equivalent framework enforcement for heavy-duty commercial fleets as the inflection signal for ruggedized connector variant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEM purchasing alliances consolidate specifications onto two preferred connector families reducing engineering overhead. |
| Battery Supply Agreement | Long-term offtake contracts with domestic cell manufacturers anchor localized high-voltage subsystem assembly operations. |
| Software-Defined Vehicle Investment | Integration of connector health monitoring into battery management systems enables predictive maintenance revenue streams. |
| Geographic Manufacturing Footprint | Technical center placement in Central European corridors addresses electromechanical engineering talent scarcity through proximity recruiting. |
| Charging Infrastructure Partnership | Utility-backed corridor network deployments in Germany and China secure high-amperage DC connector volume commitments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA FMVSS 305 regulatory filings, SAMR GB/T standard publications, and IHS Markit vehicle production databases. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement directors, charging infrastructure operators, and polymer compound R&D leads. Secondary validation incorporated SEC 10-K disclosures from electrical component conglomerates, customs trade data on copper alloy imports, and ECE R100 type-approval records. Bottom-up connector shipment estimates triangulated against top-down EV production forecasts across the analysis window.
Segmentation dimensions modeled include voltage tier architecture, cooling technology type, end-use application, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution across liquid-cooled premium, standard DC, and economy AC tiers. Industry-specific forecast inputs incorporated silicon carbide inverter adoption curves and GB/T 20234 mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained 800V platform proliferation and stable precious metals pricing; material deviation would warrant model refresh. Specific risk factors include silver price volatility compressing contact plating margins and Central European engineering talent scarcity accelerating automation capex requirements. Recalibration cycles align with material shifts in NHTSA regulatory interpretation and ECE R100 amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Europe Trailer Axle Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Snowplows Market
Vehicle Components
Car Modification Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Grille Guard Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
Wheel Loaders Market