
 Suction Pump Market | 2026-2036
Suction Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Suction Pump Market Analytics
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive advantage toward players with captive foundry and motor-winding operations. GRUNDFOS leverages its Danish vertical manufacturing base to control lead times on precision castings for high-specification diaphragm units. Xylem anchors its position through North American channel density in municipal water infrastructure. Kirloskar Brothers competes on cost-engineered centrifugal designs for India's agricultural and small-town water segments.
A suction pump is a fluid-handling device that creates partial vacuum to draw liquid or gas into a chamber, typically operating with suction lift capacities from 3 to 8 meters depending on impeller or diaphragm configuration, and serves to transfer, prime, or evacuate fluids across industrial, medical, and infrastructure applications. Centrifugal suction pumps occupy the largest installed base due to their flow-rate scalability in water treatment and oilfield surface operations. Peristaltic variants are gaining fastest in medical and laboratory end uses where contamination-free fluid path isolation matters. Diaphragm technologies concentrate margin pools in chemical processing and pharmaceutical transfer where material compatibility with aggressive media commands premium pricing.
The EPA's Clean Water Act effluent standards and the EU F-Gas Regulation on fluorinated greenhouse gases shape product design mandates for energy efficiency and seal integrity in municipal and HVAC-related pump deployments. China's MIIT efficiency labeling rules and India's BIS certification for electric motor-driven pumps create market-access thresholds that favor tested, certified product lines over unbranded imports. Stakeholders must monitor how tightening carbon-border adjustment mechanisms and local-content requirements in water infrastructure tenders reshape sourcing strategies for motor and casting components.
Market Dynamics
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is rotating competitive advantage toward players with captive foundry and motor-winding operations. This structural force is compressing margins for import-dependent assemblers while rewarding upstream control over precision castings and electric motor cores.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated greenhouse gas rules are mandating seal integrity upgrades in HVAC-related pump deployments, accelerating replacement cycles in municipal infrastructure across Germany, France, and Italy.
- Wastewater treatment expansion:Germany and Japan are expanding procurement of electric centrifugal suction pumps amid tightening effluent discharge rules under the EU Urban Wastewater Treatment Directive and Japan's Waterworks Law.
- Diaphragm pump technology:Material compatibility advances in PTFE and elastomer composites are opening premium margin pools in chemical processing and pharmaceutical fluid transfer applications.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric motor cores depend on neodymium-iron-boron magnets and copper windings, exposing manufacturers to Chinese export quota fluctuations and LME copper price swings.
- Foundry capacity concentration:Precision casting for high-specification pump housings concentrates in German, Italian, and Chinese supplier bases, creating single-source vulnerability for mid-tier assemblers.
- Physical suction lift ceiling:Atmospheric pressure limits practical suction lift to 8 meters for water at sea level, constraining deployment in high-altitude mining and remote agricultural applications without supplemental priming systems.
Strategic Opportunities
- India municipal water infrastructure:National Jal Jeevan Mission targets piped water connectivity to all rural households by 2024, concentrating demand for cost-engineered centrifugal and peristaltic pump technologies in high-growth metropolitan clusters.
- Medical-grade peristaltic convergence:Contamination-free fluid path isolation is accelerating adoption in biopharma manufacturing and laboratory automation, displacing piston and gear pump alternatives.
- China MIIT efficiency labeling:Mandatory energy-efficiency grades for electric motor-driven pumps are creating market-access thresholds that favor tested, certified product lines over unbranded imports.
Industry Challenges
- Multi-standard certification timelines:Simultaneous compliance with EPA Clean Water Act effluent standards, EU CE marking, and China's BIS certification creates 12-18 month product launch delays for cross-border suppliers.
- Legacy system integration friction:Smart pump connectivity protocols must interface with decades-old SCADA infrastructure in municipal water treatment plants, requiring custom middleware development.
- Precision casting skill scarcity:Captive foundry operations require metallurgical engineers capable of thin-wall stainless steel casting for diaphragm pump chambers, a talent pool concentrated in aging European and Japanese workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suction Pump Market |
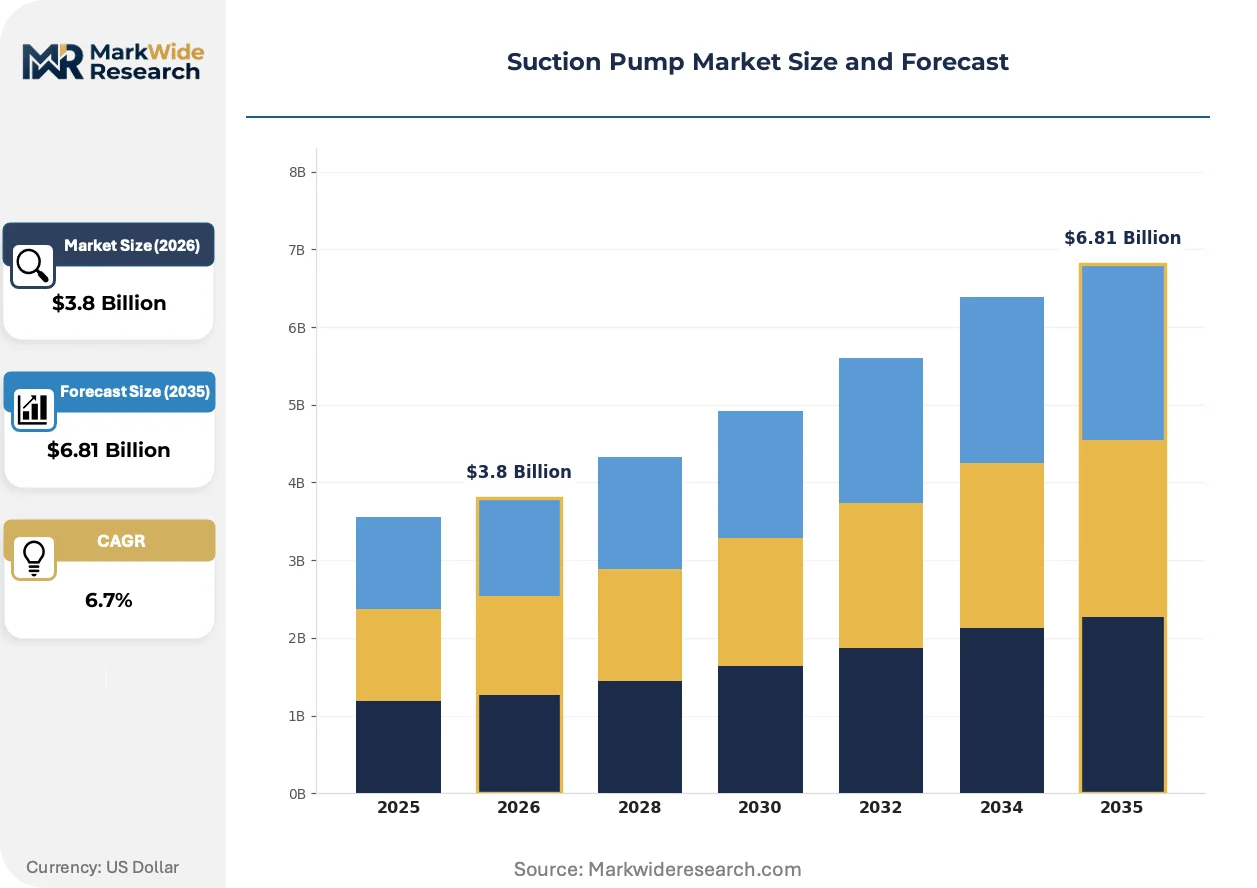
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm, Peristaltic, Centrifugal, Gear Application: Agriculture, Oil & Gas, Water Treatment, Medical End User: Hospitals, Laboratories, Industrial, Municipal Technology: Electric, Pneumatic, Manual, Hydraulic |
| Companies Covered | Xylem, GRUNDFOS, Flowserve Corporation, Sulzer AG, Kirloskar Brothers, Ebara Corporation, Gardner Denver, Shanghai Kai Quan Pump, Patterson Pump Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suction Pump Market Evolving Landscape
Digitalization of fluid-handling systems is compressing maintenance cycles and unbundling after-sales service from equipment sales. Three interconnected developments are reshaping how suction pump value is captured and delivered.
Smart pump monitoring is decomposing traditional preventive maintenance schedules. Embedded vibration and temperature sensors in centrifugal pump bearings transmit real-time performance data to cloud analytics platforms. Municipal water utilities in Germany and Japan are adopting these systems fastest, enabling condition-based replacement of seals and impellers before catastrophic failure.
REACH chemical substance restrictions are forcing material substitutions in elastomer seals and diaphragm components. The EU's rolling list of Substances of Very High Concern is phasing out certain phthalate plasticizers and perfluorinated compounds used in pump wet-ends. Pharmaceutical and food-processing pump manufacturers are responding fastest, qualifying hydrogenated nitrile and perfluoroelastomer alternatives ahead of sunset dates.
After-sales service unbundling is disrupting long-term maintenance contracting in oilfield surface operations. Operators are separating pump procurement from technical service agreements, sourcing spare parts through independent distributors and performing rebuilds in-house. This pattern is most visible in Permian Basin and North Sea deployments, where drilling contractors face capital discipline pressure from upstream operators.
Suction Pump Market Segmentation
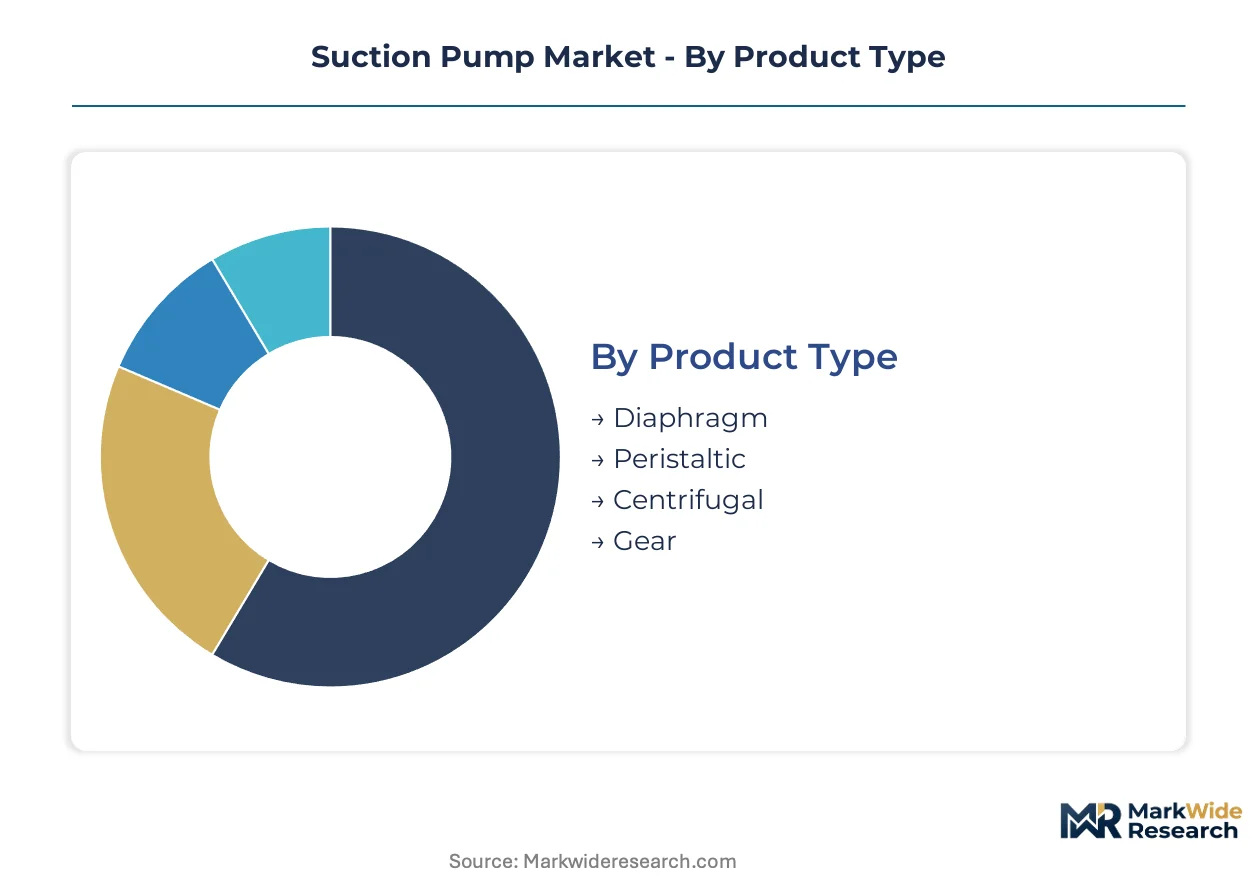
Suction pump procurement patterns diverge sharply across product architectures and power technologies, with substitution threats from competing fluid-handling technologies reshaping investment priorities in each category. Understanding where centrifugal designs face displacement from peristaltic alternatives, or where electric drives confront pneumatic competition, determines portfolio positioning for component suppliers and system integrators.
Product Type:
Peristaltic and diaphragm technologies face the strongest substitution pressure from progressing cavity pumps in high-viscosity chemical transfer, forcing manufacturers to defend margin through material differentiation and contamination-free certification.
- Centrifugal:Radial-flow impeller designs dominate water treatment infrastructure and oilfield surface operations where flow-rate scalability outweighs suction lift limitations. Demand concentrates in Germany and Japan as municipal utilities expand procurement under tightening EU Urban Wastewater Treatment Directive and Japan Waterworks Law effluent standards.
- Diaphragm:Reciprocating elastomer or PTFE membrane configurations isolate fluid paths completely, commanding premium positioning in pharmaceutical transfer and aggressive chemical processing where material compatibility determines equipment life. PTFE composite advances are opening margin pools in multi-stage chemical dosing systems.
- Peristaltic:Hose compression mechanisms eliminate seal wear and contamination risk in medical and laboratory automation.
- Gear:Positive displacement through meshing rotors serves viscous fluid handling in lubrication and fuel transfer applications.
Centrifugal designs anchor the volume base across municipal and industrial water infrastructure while peristaltic configurations gain share at the steepest rate in medical-grade and biopharma fluid handling.
Application:
Cost-tier segmentation separates specification-intensive medical and pharmaceutical deployments from price-sensitive agricultural and small-town water applications, with certification requirements creating divergent procurement pathways.
- Water Treatment:Municipal and industrial effluent handling drives the largest installed base, with electric centrifugal pumps serving primary clarification, filtration, and disinfection stages. Germany and Japan utilities are expanding procurement fastest amid regulatory tightening.
- Medical:Sterile fluid transfer, suction, and drainage applications demand contamination-free operation with single-use or sterilizable flow paths. Peristaltic and diaphragm technologies are displacing piston alternatives in biopharma manufacturing and laboratory automation.
- Agriculture:Irrigation and drainage applications prioritize first-cost economics and field-serviceability over efficiency ratings.
- Oil & Gas:Surface production and transfer operations require explosion-proof configurations and abrasion-resistant materials.
Water treatment anchors the volume base through municipal infrastructure renewal cycles while medical applications climb the fastest on biopharma manufacturing expansion and laboratory automation adoption.
End User:
Customer-type concentration shapes channel strategy, with municipal procurement favoring long-term service contracts and industrial buyers separating equipment purchase from technical support.
- Municipal:City and regional water authorities specify energy-efficient electric centrifugal pumps with 20-year service life expectations, bundling procurement with SCADA integration and preventive maintenance agreements. India's Jal Jeevan Mission is concentrating demand for cost-engineered centrifugal and peristaltic technologies in high-growth metropolitan clusters.
- Industrial:Chemical processing, food and beverage, and manufacturing facilities prioritize material compatibility and uptime reliability over capital cost, with REACH chemical restrictions forcing elastomer seal substitutions ahead of sunset dates.
- Hospitals:Surgical suction and wound drainage systems require portable, quiet operation with infection control certification.
- Laboratories:Research and analytical instrumentation demands precision flow control with minimal pulsation.
Municipal end users anchor the volume base through infrastructure program scale while industrial segments expand most quickly on chemical processing and food safety investment.
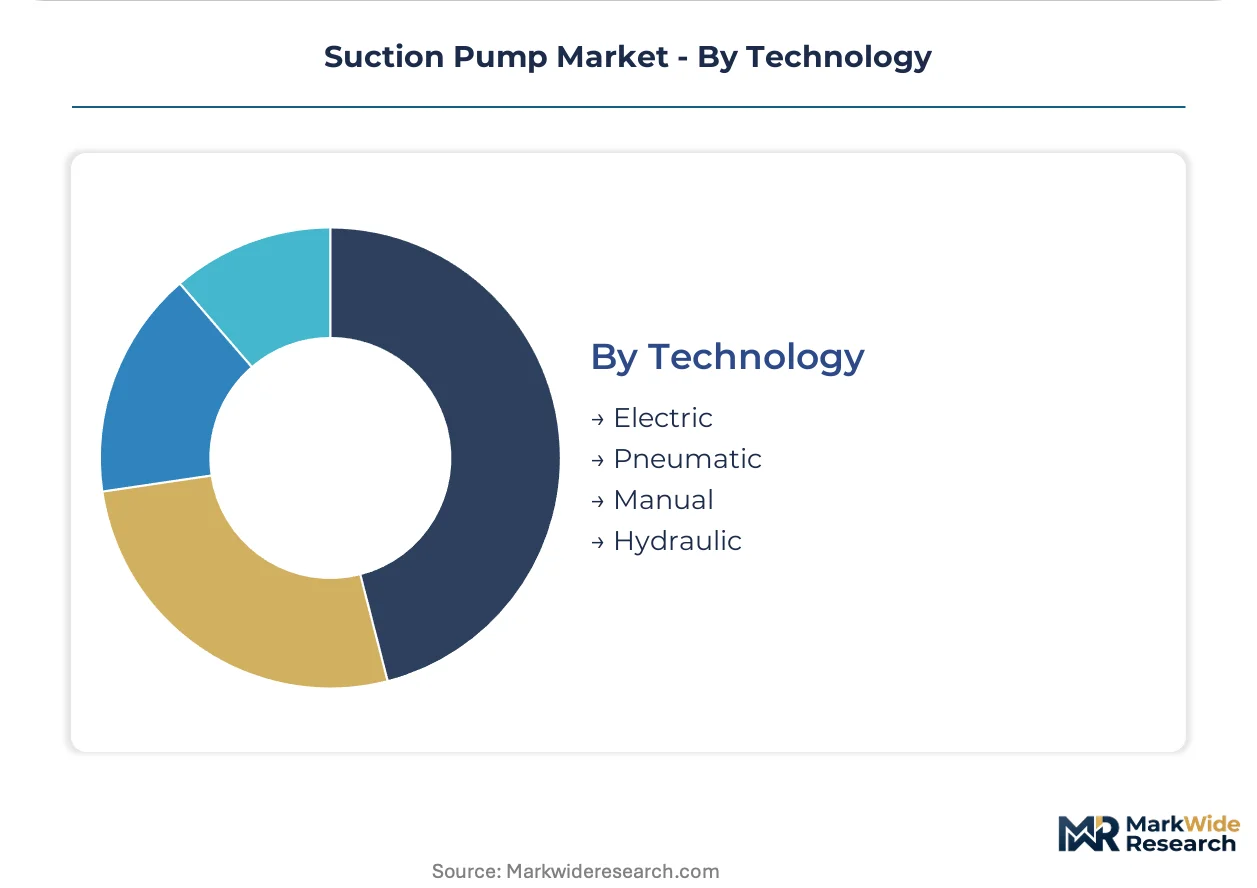
Technology:
Power-source selection determines regulatory exposure, with electric drives facing efficiency labeling mandates and pneumatic alternatives benefiting from explosion-proof intrinsic safety.
- Electric:AC induction and permanent magnet motor drives dominate flow-rate and pressure requirements above 1 kW, with China's MIIT efficiency labeling rules and India's BIS certification creating market-access thresholds that favor tested, certified product lines over unbranded imports.
- Pneumatic:Compressed-air-powered diaphragm and peristaltic configurations serve hazardous environments and mobile applications where electrical ignition risk prohibits standard motor drives.
- Manual:Hand-operated suction devices serve emergency medical and field applications without power infrastructure.
- Hydraulic:Fluid-power drives deliver high torque density in heavy-duty mining and construction dewatering.
Electric technology anchors the volume base through efficiency regulation and grid connectivity expansion while pneumatic alternatives gain share fastest in hazardous environment certification and mobile deployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Municipal buyers in Germany and Japan absorb premium pricing for efficiency-certified electric centrifugal units, while agricultural and small-town water authorities in India and rural China prioritize first-cost economics over lifecycle ratings.
Germany
Industrial wastewater treatment plants drive specification-grade procurement. The EU Urban Wastewater Treatment Directive mandates tertiary treatment upgrades, accelerating replacement cycles for high-efficiency centrifugal pumps. The Ruhr industrial cluster and Bavarian chemical corridor concentrate demand for PTFE-diaphragm technologies in aggressive media handling.
Japan
Aging water infrastructure and seismic resilience requirements shape municipal procurement. The Waterworks Law enforces strict leakage control standards, favoring precision-cast electric pumps with integrated monitoring. The Kanto region around Tokyo and Osaka's Kansai hub lead facility modernization programs.
China
Municipal water infrastructure programs concentrate demand in Yangtze River Delta metropolitan clusters. MIIT efficiency labeling rules for electric motor-driven pumps create market-access thresholds that favor tested, certified product lines over unbranded imports. Shanghai and Jiangsu province anchor procurement volume for diaphragm and peristaltic technologies.
India
The Jal Jeevan Mission targets universal rural piped water connectivity, concentrating demand for cost-engineered centrifugal designs. BIS certification for electric motor-driven pumps blocks unbranded Chinese imports. Maharashtra, Gujarat, and Karnataka's industrial belts drive agricultural and small-town water segment procurement.
United States
EPA Clean Water Act effluent standards enforce energy efficiency and seal integrity in municipal deployments. The Permian Basin oilfield surface operations and Texas Gulf Coast petrochemical corridor drive demand for explosion-proof and abrasion-resistant configurations. Midwest municipal utilities prioritize SCADA-integrated smart pump retrofits.
Suction Pump Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry and motor-winding operations conferring cost and lead-time advantages. The market structure rewards upstream control over precision castings and electric motor cores while compressing margins for import-dependent assemblers. Three archetypes dominate: vertically integrated European-Japanese industrial groups, cost-engineered Indian-Chinese fabricators, and medical-grade peristaltic specialists. Competitive moves center on foundry capacity expansion and efficiency certification pre-positioning ahead of regulatory deadlines.
Among the integrated leaders, GRUNDFOS anchors the premium-tier position through its Danish manufacturing base, while Xylem exemplifies North American channel density in municipal water infrastructure. Kirloskar Brothers occupies a position within the cost-engineered tier serving India's agricultural and small-town water segments. These three represent distinct strategic archetypes: captive vertical manufacturing, regional channel dominance, and emerging-market cost leadership.
| Leading Market Players |
|---|
| Xylem |
| GRUNDFOS |
| Flowserve Corporation |
| Sulzer AG |
| Kirloskar Brothers |
| Ebara Corporation |
| Gardner Denver |
| Shanghai Kai Quan Pump |
| Patterson Pump Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with German and Japanese municipal utilities lock in foundry capacity reservations and seal material supply, anchoring price visibility for precision-cast centrifugal pump components while exposing assemblers to copper and rare-earth magnet cost pass-through clauses.
Pricing Analysis
After-sales service revenue—spare parts, preventive maintenance contracts, and seal replacement programs—drives lifetime value capture across municipal and industrial deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and SCADA integration depth, with EU F-Gas Regulation compliance commanding margin premiums. Cost compression in economy-tier agricultural pumps intensifies due to unbranded Chinese import competition. Municipal buyers in Germany and Japan exhibit lowest price sensitivity, while India's Jal Jeevan Mission procurement prioritizes first-cost economics over lifecycle ratings.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Italian and German precision casting subcontractors serving mid-tier assemblers. Supply concentrates in China for electric motor cores, Germany for stainless steel pump housings, and India for cost-engineered cast iron components. Raw material dependencies center on neodymium-iron-boron magnets, copper windings, and PTFE-elastomer composites. Single-source vulnerability in German foundry capacity creates structural risk for high-specification diaphragm chamber production. Distribution runs through authorized dealer networks for municipal infrastructure and independent aftermarket channels for oilfield surface operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as REACH chemical restrictions and MIIT efficiency labeling bifurcate demand between certified premium tiers and unbranded economy alternatives, creating defendable niches for specialist manufacturers.
For Market Incumbents: Shield margin pools in pharmaceutical-grade diaphragm technologies by qualifying hydrogenated nitrile and perfluoroelastomer seal alternatives ahead of ECHA sunset dates. Accelerate captive foundry expansion in Denmark or Bavaria to compress lead times on thin-wall stainless steel castings, neutralizing the threat from import-dependent assemblers facing copper price volatility. For New Entrants and Emerging Players: Anchor in India's Jal Jeevan Mission procurement corridor, where BIS certification requirements block unbranded Chinese competition and concentrate demand for cost-engineered centrifugal designs. Target medical-grade peristaltic configurations for biopharma manufacturing automation, leveraging contamination-free fluid path isolation as the go-to-market wedge against piston pump incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated European-Japanese industrial groups with captive motor-winding operations and established EPA/CE/BIS certification portfolios, positioned for sustained viability across the analysis window. Monitor copper LME price trajectories and Chinese rare-earth export quota announcements as inflection indicators for margin compression in electric-drive segments.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Expansion | Secures thin-wall stainless steel casting capacity for diaphragm pump chambers under EU F-Gas seal integrity mandates. |
| Efficiency Certification Pre-Positioning | Locks MIIT Grade 1 and BIS certification ahead of China's carbon-border adjustment mechanism enforcement. |
| After-Sales Service Unbundling | Captures recurring revenue from Permian Basin operators separating pump procurement from technical support agreements. |
| Material Substitution R&D | Qualifies REACH-compliant elastomer alternatives before SVHC sunset dates force pharmaceutical pump redesigns. |
| Smart Pump Monitoring Integration | Enables condition-based maintenance contracts with German municipal utilities adopting SCADA-connected vibration sensors. |
Research Methodology
The analysis maps centrifugal, diaphragm, peristaltic, and gear pump sub-sectors, each validated through plant engineers at municipal water authorities, procurement leads at chemical processing facilities, aftermarket service heads at oilfield distributors, and regulatory affairs specialists at pump manufacturers. Primary interview findings triangulate against customs trade data for motor and casting components, SEC filings of listed pump manufacturers, EU ECHA substance restriction databases, and MIIT efficiency labeling registries. Bottom-up unit shipment estimates by product architecture reconcile with top-down infrastructure spending projections across Germany, Japan, China, India, and the United States.
Consistency checks validate volume and value outputs against external benchmarks including EIA industrial electricity consumption patterns, IEA water infrastructure investment trackers, and national procurement disclosures under India's Jal Jeevan Mission. The analytical framework models demand across product type, application, end user, and power technology dimensions over the projection horizon. CAGRs derive from regression analysis of historical replacement cycles, regulatory compliance deadlines, and infrastructure program scaling curves, with specific weighting applied to EU F-Gas Regulation phase-in timelines and China's dual carbon policy enforcement intensity.
Material uncertainties—copper and rare-earth magnet price volatility, foundry capacity constraints in aging European workforces, and carbon-border adjustment mechanism implementation timing—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure budget allocation stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Centrifugal Pumps Machines Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Reverse Osmosis Pump Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
Fluid Power Equipment Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Electric Submersible Pump (ESP) in Oil and Gas Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Circulators Market