
 Global Lobe Pumps Market | 2026-2036
Global Lobe Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lobe Pumps Market Foresight
Aftermarket service contracts and predictive maintenance subscriptions is restructuring how lobe pump vendors capture lifetime value from food and beverage clients. Netzsch Group leverages its global service footprint to lock in multi-year maintenance agreements across European dairy processors. Alfa Laval anchors its competitive position through hygienic design leadership and specialized clean-in-place protocols. Vogelsang GmbH & Co. KG differentiates with mobile service units that reduce downtime for municipal wastewater operators.
Lobe pumps are positive-displacement rotary pumps featuring two or more meshing lobes that transfer fluid without contact between the pumping elements, enabling shear-sensitive handling at capacities up to 1,000 m³/h with pulsation-free flow. They serve critical roles in hygienic processing, chemical transfer, and sludge handling where product integrity and containment take priority. Progressive cavity pumps and peristaltic pumps command attention in wastewater and chemical applications due to their compatibility with abrasive and viscous media. Magnetic drive technology is gaining structural importance as processors eliminate mechanical seal leakage paths to satisfy tightening environmental and safety protocols. Screw pumps occupy mature positions in oil and gas transfer, where established infrastructure and long replacement cycles limit margin expansion.
The US EPA enforces Clean Water Act discharge standards that compel wastewater utilities to upgrade pumping systems for improved reliability and reduced fugitive emissions. EMA and REACH in Europe impose material traceability and substance restriction requirements that filter through to seal compound selection and pump body metallurgy. China's MEE implements dual carbon goals that pressure chemical manufacturers toward energy-efficient fluid handling equipment. Stakeholders must weigh seal technology migration paths against retrofit economics while monitoring how regional decarbonization timelines reshape capital allocation for pump replacement cycles.
Market Dynamics
Magnetic drive technology is electrifying the competitive landscape by eliminating mechanical seal leakage paths, forcing incumbent vendors to reengineer product architectures and service revenue models simultaneously.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening controls on perfluorinated compounds are accelerating fluorocarbon-free seal material R&D across German and Italian pump manufacturers.
- Dairy processing automation:Food and beverage processors in Wisconsin and Bavaria are standardizing on clean-in-place compatible lobe pumps to reduce batch changeover downtime.
- China's chemical corridor expansion:Petrochemical capacity additions around Shanghai and Ningbo are generating concentrated demand for corrosion-resistant alloy pump configurations.
Market Restraints
- Specialty alloy input costs:Nickel and molybdenum price volatility is compressing margins for super-duplex stainless steel pump body production.
- Seal compound supply concentration:Advanced fluoroelastomer formulations rely on a limited supplier base concentrated in Germany and Japan.
- Progressive cavity pump substitution:Wastewater utilities facing abrasive sludge applications are specifying progressing cavity designs over lobe configurations for wear life.
Strategic Opportunities
- India's dairy modernization:FSSAI enforcement of hygienic processing standards is opening specification windows for stainless steel lobe pumps in cooperative dairy plants across Gujarat and Maharashtra.
- Predictive maintenance convergence:Vibration sensor integration with cloud analytics platforms is enabling subscription-based uptime guarantees for chemical processors.
- EU F-Gas phase-down:Refrigeration system rebuilds are creating aftermarket demand for hermetic lobe pump retrofits in cold chain logistics facilities.
Industry Challenges
- Clean-in-place validation timelines:FDA and EMA hygienic certification cycles for new pump geometries extend 18-24 months, delaying product launches.
- Legacy control system integration:Chemical plants with 1990s-era SCADA infrastructure face protocol incompatibility when installing digitally-enabled pump packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lobe Pumps Market |
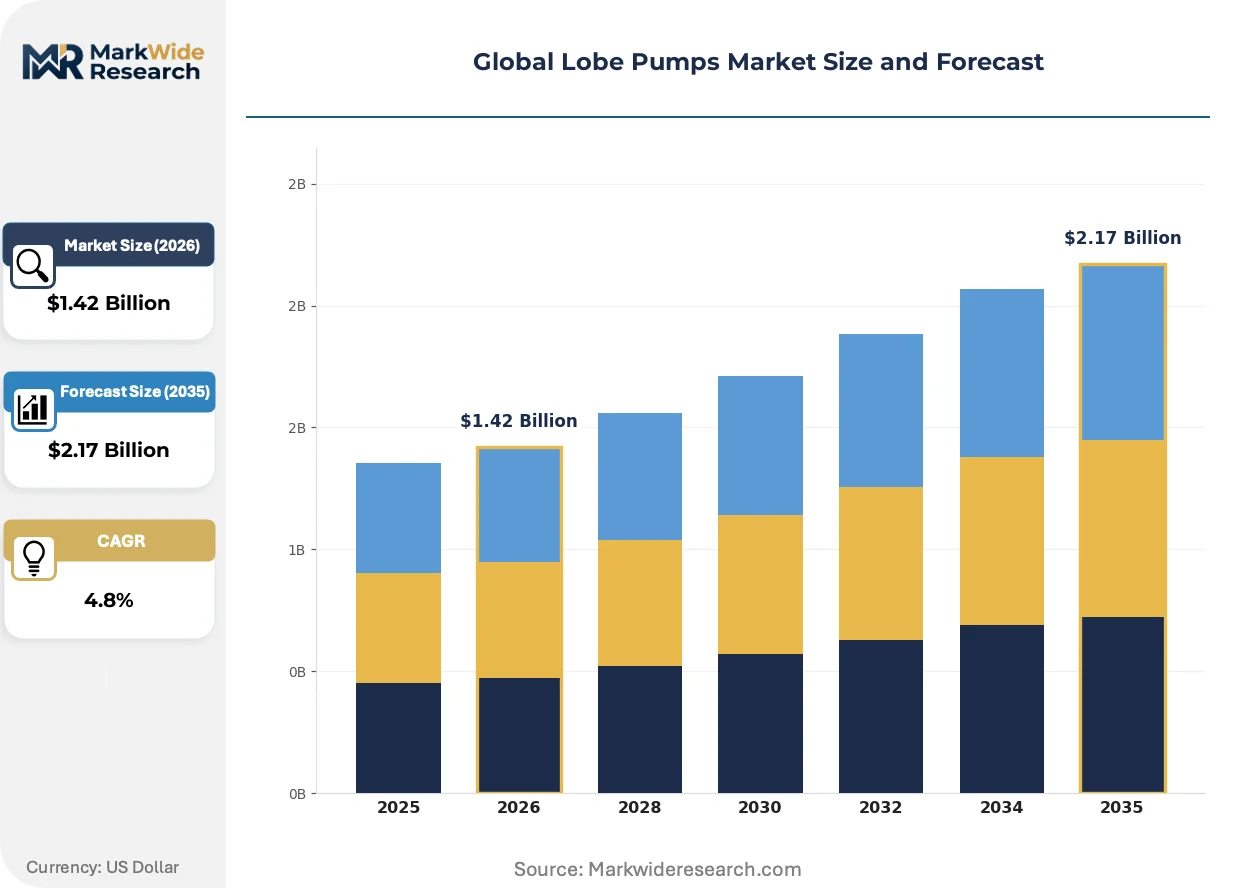
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Gear Pumps, Progressive Cavity Pumps, Diaphragm Pumps, Peristaltic Pumps, Screw Pumps Technology: Magnetic Drive, Mechanical Seal, Cartridge Seal, Peripheral Seal, Lip Seal Application: Wastewater Treatment, Chemical Processing, Food & Beverage, Pulp & Paper, Oil & Gas, Marine End User: Utility Providers, Chemical Manufacturers, Food Processors, Pulp Production Facilities, Petroleum Producers |
| Companies Covered | Netzsch Group, Börger GmbH, GEA Group, Alfa Laval, SPX Flow, Vogelsang GmbH & Co. KG, Fristam Pumpen GmbH, KSB SE & Co. KGaA, Wright Flow Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lobe Pumps Market Shifts & Advancements
Electrification of pump architectures, regulatory material bans, and servitization of vendor relationships are converging to restructure how value is captured across equipment lifecycles.
Magnetic drive lobe pump technology is electrifying the mid-duty chemical transfer segment by removing seal maintenance from operating cost structures. Specialty chemical manufacturers in Belgium and the Netherlands are specifying magnetically coupled configurations for solvent handling applications. This architecture is compressing the addressable market for conventional mechanical seal aftermarket services while expanding total pump lifecycle value capture.
REACH Annex XVII restrictions on microplastics and persistent organic pollutants are forcing reformulation of PTFE-based bearing and seal components. Compound suppliers must validate alternative filled polymer grades against 10-year wear specifications before OEM qualification. Food contact applications in France and Germany are experiencing the most acute certification bottlenecks as EFSA reviews new material safety dossiers.
Buyers are unbundling aftermarket service contracts from initial equipment purchases, forcing vendors to compete for multi-year maintenance agreements through predictive capability demonstrations. Municipal wastewater authorities in California and Texas are requesting guaranteed uptime clauses with financial penalties for unplanned downtime. This behavior is most visible in North American municipal procurement, where public sector budgeting constraints favor operational expenditure models over capital-intensive equipment ownership.
Global Lobe Pumps Market Segmentation
Lobe pump procurement patterns diverge sharply between high-volume commodity applications and precision-engineered hygienic installations. Technology selection and material specifications track directly against end-use contamination risk and regulatory exposure.
Product Type:
Volume concentration clusters in standardized rotary configurations for chemical transfer, while premium pricing attaches to specialized positive-displacement architectures for shear-sensitive media.
- Internal Gear Pumps:Compact intermeshing gear designs handle viscous fluids at moderate pressures with minimal pulsation. Demand concentrates in German automotive coating lines and Minnesota food oil processing facilities, where space-constrained installations prioritize footprint efficiency over absolute hygienic ratings.
- Progressive Cavity Pumps:Single-helix rotor turning within an elastomeric stator creates sealed cavities for abrasive sludge handling. Wastewater utilities in California and Texas specify these configurations for primary sludge transfer, accepting higher wear rates in exchange for lower capital outlay than lobe alternatives.
- Diaphragm Pumps:Reciprocating flexible diaphragms isolate fluid from mechanical components, enabling zero-leakage chemical transfer.
- Peristaltic Pumps:Hose compression mechanisms eliminate contamination paths for pharmaceutical and laboratory applications.
- Screw Pumps:Intermeshing helical screws provide continuous flow for high-viscosity crude oil and bitumen handling.
Mature deployment sits with Internal Gear Pumps. Newer deployment is concentrated in Progressive Cavity Pumps.
Technology:
Seal architecture selection determines lifecycle cost structures and regulatory compliance pathways across chemical and food processing installations.
- Magnetic Drive:Permanent magnet couplings transmit torque through containment shells, eliminating mechanical seal leakage paths entirely. Specialty chemical manufacturers in Belgium and the Netherlands specify magnetically coupled lobe pumps for solvent handling, satisfying EMA containment requirements while removing seal maintenance from operating budgets.
- Mechanical Seal:Spring-loaded faces maintain running clearances between rotating and stationary components, balancing capital cost against periodic replacement intervals. Legacy chemical plants in Louisiana and Texas retain mechanical seal configurations for non-hazardous fluid transfer where EPA risk management plan thresholds are not triggered.
- Cartridge Seal:Pre-assembled seal units reduce installation error and field assembly time for OEM aftermarket services.
- Peripheral Seal:Secondary containment designs provide backup leakage protection for critical environmental applications.
- Lip Seal:Elastomeric radial seals protect bearings from contamination in low-pressure auxiliary pump functions.
Mechanical Seal configurations retain installed base dominance. Magnetic Drive architectures are expanding most quickly in new chemical processing capacity.
Application:
Regulatory intensity and fluid characteristics fragment demand across contamination-sensitive food handling, abrasive wastewater streams, and hazardous chemical transfer.
- Food & Beverage:Hygienic lobe pump designs with 3-A Sanitary Standards certification enable clean-in-place protocols for dairy and beverage processing. Wisconsin cheese processors and Bavarian dairy cooperatives standardize on stainless steel configurations with electro-polished surfaces to minimize bacterial adhesion during extended production runs.
- Wastewater Treatment:Abrasion-resistant pump bodies handle primary sludge and thickened biosolids with minimal clogging. Municipal utilities in Shanghai and Ningbo specify hardened iron alloy rotors for combined sewer overflow pumping stations, where grit and debris accelerate wear in high-duty cycle operations.
- Chemical Processing:Corrosion-resistant alloys and specialized seal compounds manage aggressive solvents and reactive intermediates.
- Pulp & Paper:High-consistency stock pumps transfer fibrous slurries at elevated viscosities.
- Oil & Gas:API-compliant designs handle crude oil, refined products, and production chemicals.
- Marine:Compact footprints and vibration tolerance suit bilge and ballast applications.
Food & Beverage applications command premium pricing tiers. Wastewater Treatment represents the largest installed volume base.
End User:
Procurement sophistication varies between municipal utilities with extended capital cycles and private chemical manufacturers with shorter equipment replacement horizons.
- Chemical Manufacturers:Integrated petrochemical complexes and specialty chemical producers specify pumps against process hazard analyses and mechanical integrity programs. Operators in the Antwerp-Rotterdam chemical cluster prioritize magnetic drive configurations to eliminate seal failure scenarios in solvent service, aligning with Seveso III directive safety management requirements.
- Food Processors:Dairy cooperatives and beverage bottlers validate equipment against FDA and EMA hygienic design guidelines. French yogurt manufacturers and Dutch ingredient suppliers require 3-A symbol authorization and EHEDG certification for direct product contact surfaces, extending qualification timelines but locking in multi-year supply relationships.
- Utility Providers:Municipal wastewater authorities operate under public procurement constraints favoring lowest life-cycle cost evaluations.
- Pulp Production Facilities:Integrated paper mills specify pumps for black liquor and stock preparation stages.
- Petroleum Producers:Upstream and midstream operators prioritize mean-time-between-failure metrics for remote installations.
Petroleum Producers maintain the longest replacement cycles. Food Processors show the steepest expansion trajectory for hygienic specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Ningbo anchor chemical processing demand for corrosion-resistant lobe pump configurations. German dairy cooperatives in Bavaria drive hygienic specification upgrades. US wastewater utilities in California and Texas prioritize wear-resistant designs for abrasive sludge handling.
United States
Wisconsin cheese processors and Minnesota food oil facilities expand stainless steel lobe pump procurement for clean-in-place compatibility. EPA enforces Clean Water Act discharge standards that compel municipal utilities to upgrade pumping systems for improved reliability. California wastewater authorities specify hardened alloy rotors for combined sewer overflow stations.
Germany
Automotive coating lines in Stuttgart and Munich demand compact intermeshing gear pumps for space-constrained installations. ECHA's REACH Annex XVII restrictions on perfluorinated compounds accelerate fluorocarbon-free seal material R&D across German manufacturers. Bavarian dairy cooperatives standardize on electro-polished surfaces to minimize bacterial adhesion.
China
Petrochemical capacity additions around Shanghai and Ningbo generate concentrated demand for super-duplex stainless steel pump bodies. MEE implements dual carbon goals that pressure chemical manufacturers toward energy-efficient fluid handling equipment. Yangtze River Delta processing corridors specify magnetic drive configurations for solvent service.
Belgium
Specialty chemical manufacturers in the Antwerp-Rotterdam cluster prioritize magnetically coupled lobe pumps to eliminate seal failure scenarios. Seveso III directive safety management requirements align procurement with containment-focused architectures. Port of Antwerp chemical terminals specify corrosion-resistant alloys for aggressive solvent handling.
India
FSSAI enforcement of hygienic processing standards opens specification windows for stainless steel lobe pumps in cooperative dairy plants. Gujarat and Maharashtra dairy cooperatives modernize equipment to meet food contact compliance requirements. Mumbai-Pune industrial corridor processors validate pumps against clean-in-place protocols.
Global Lobe Pumps Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the lobe pump supply base. The vendor landscape organizes around three tiers: integrated multinational pump groups with full metallurgical capabilities, regional specialists focused on hygienic or chemical applications, and component suppliers feeding modular assembly networks. Dominant competitive moves include strategic partnerships for seal compound access and geographic expansion through local assembly licensing.
Among German-based pump fabricators, Netzsch Group, Börger GmbH, and Vogelsang GmbH & Co. KG occupy positions spanning industrial fluid handling archetypes. Netzsch represents the diversified multinational tier with integrated manufacturing depth. Börger exemplifies family-owned engineering focus on positive-displacement specialization. Vogelsang sits within the mobile service and aftermarket-centric segment. These anchors illustrate how European engineering heritage combines with distinct strategic postures toward equipment-versus-service revenue mix.
| Leading Market Players |
|---|
| Netzsch Group |
| Börger GmbH |
| GEA Group |
| Alfa Laval |
| SPX Flow |
| Vogelsang GmbH & Co. KG |
| Fristam Pumpen GmbH |
| KSB SE & Co. KGaA |
| Wright Flow Technologies |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates gate qualified supply for hermetic pump configurations and premium-tier pricing access for cold chain logistics retrofits. REACH Annex XVII substance restrictions on fluorinated compounds further bifurcate the supplier base between certified compound formulators and excluded competitors, compressing margin structures for non-compliant fabricators while elevating certified alternatives.
Pricing Analysis
Outcome-based pricing anchored to guaranteed uptime metrics dominates municipal wastewater procurement in California and Texas. Three-tier pricing structure across premium, standard, and economy levels separates magnetic drive hermetic configurations from mechanical seal variants and basic commodity pumps. Cost compression in standard-tier mechanical seal pumps is intensifying because nickel and molybdenum price volatility erodes super-duplex stainless steel margins. Chemical manufacturers in the Antwerp-Rotterdam cluster show least price sensitivity due to Seveso III containment requirements, while Indian dairy cooperatives face acute budget constraints under FSSAI modernization mandates.
Supply Chain Analysis
Dual-sourcing requirements for advanced fluoroelastomer compounds compel German and Japanese pump manufacturers to qualify secondary compound suppliers against 10-year wear specifications. Supply concentrates in Germany for precision-machined pump bodies, Japan for specialized seal formulations, and China for super-duplex stainless steel castings. Raw material dependencies draw from nickel, molybdenum, and cobalt-chrome alloys subject to commodity price volatility. Single-source vulnerability sits with PTFE-filled bearing formulations under REACH microplastic review. Distribution runs through OEM direct sales for large chemical processors and authorized service networks for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into seal compound formulation to escape supply concentration and capture margin erosion from fluorocarbon-free material transitions.
For Market Incumbents: Anticipate progressive cavity pump substitution threats in wastewater applications by hardening rotor alloys and extending wear warranties. Defend position through captive supply of REACH-compliant seal compounds, locking out competitors from qualified material access. Prioritize certification investment in 3-A Sanitary Standards and EHEDG protocols to extend qualification timelines for challengers.
For New Entrants and Emerging Players: Enter via India's dairy modernization wave, where FSSAI enforcement creates specification windows without entrenched incumbent relationships. Target Gujarat and Maharashtra cooperative plants with clean-in-place compatible stainless steel configurations priced below European alternatives. Pursue local assembly licensing to circumvent import cost structures and accelerate service response times.
For Investors and Strategic Acquirers: Magnetic drive technology penetration exceeding critical mass in Belgian and Dutch solvent handling is the leading indicator that seal-less architectures will displace mechanical seal aftermarket revenue pools. Position for 5-10 year consolidation around vertically integrated pump groups with in-house metallurgical capabilities and certified seal compound supply. Watch for ECHA acceleration of perfluorinated compound bans as the inflection signal for compound supplier acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Compounds | Captures margin from fluorocarbon-free formulations required by REACH Annex XVII restrictions. |
| Magnetic Drive Product Line Expansion | Eliminates mechanical seal maintenance revenue while satisfying EMA containment mandates in Antwerp-Rotterdam chemical cluster. |
| India Local Assembly Licensing | Reduces landed cost exposure for FSSAI-compliant dairy pump specifications in Gujarat and Maharashtra. |
| Predictive Maintenance Platform Launch | Enables subscription-based uptime guarantees for California and Texas municipal wastewater authorities. |
| Super-Duplex Stainless Steel Capacity Addition | Secures supply of corrosion-resistant pump bodies for Shanghai and Ningbo petrochemical expansions. |
Research Methodology
Multi-period observation of seal technology migration paths and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing facilities, aftermarket service heads at pump distributors, procurement leads at dairy cooperatives, and technical R&D directors at seal compound suppliers. Secondary validation drew from ECHA REACH substance restriction databases, EPA Clean Water Act enforcement records, FSSAI food contact compliance filings, and customs trade data for pump imports. Bottom-up equipment shipment tracking and top-down end-use demand estimation were triangulated against disclosed capacity expansions.
Segment-weighting across product type, seal architecture, application contamination risk, and end-user procurement sophistication structured the analytical framework. CAGRs were derived from installed base replacement cycle analysis and new capacity absorption rates across the projection horizon. Modeled dimensions included hygienic certification tier, corrosion resistance specification, and regional regulatory enforcement intensity. Forecast inputs incorporated MEE dual carbon goal implementation pace and EMA material traceability requirement expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH substance bans or nickel price spike scenarios. Deviation in ECHA perfluorinated compound restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Europe Subsea Pumps Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Centrifugal Pump Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
North America Axial Flow Pump Market
Pumps and Control Devices
North America Submersible Pumps Market