
 Skid Steer Loader Market | 2026-2036
Skid Steer Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Skid Steer Loader Market Intelligence
ISO 14397-1 certification for operating capacity and tipping load verification is redrawing competitive entry barriers for compact equipment manufacturers. Bobcat leverages its vertical integration into attachment ecosystems to sustain dealer loyalty across rental and contractor channels. Caterpillar anchors its position through proprietary telematics platforms that dominate fleet management purchasing criteria. Kubota competes by specializing in sub-75-horsepower segments where agricultural crossover demand remains strongest.
A skid steer loader is a compact, engine-powered machine with lift arms that pivot alongside the operator cabin, typically rated between 700 and 4,000 pounds of rated operating capacity and designed for tight-radius material handling in confined job sites. Track loader variants distribute ground pressure below 4 psi, enabling wetland and sensitive terrain access where wheeled units would compromise subgrade integrity. Construction end users command the largest equipment deployment base, though landscaping operators represent the fastest-growing rental segment as urban green infrastructure budgets expand. Diesel technology still occupies the dominant revenue share, yet electric powertrains are capturing disproportionate R&D allocation as municipalities impose noise and emissions restrictions on urban job sites.
EPA Tier 4 Final standards and OSHA silica exposure limits are forcing manufacturers to redesign engine compartments and operator enclosures, adding engineering cost but also creating product differentiation through certified compliance packages. The EU Machinery Directive and CE marking requirements impose additional testing protocols for any equipment sold into European rental fleets, effectively segmenting production lines by regulatory destination. Stakeholders must monitor battery-electric runtime benchmarks and fast-charging infrastructure buildouts, as these specifications will determine which powertrain architectures survive the next procurement cycle.
Market Dynamics
EPA Tier 4 Final emissions mandates and OSHA silica exposure rules are compressing product development cycles while forcing capital redeployment into compliant powertrain architectures and sealed cabin designs.
Growth Catalysts
- Municipal infrastructure mandates:Aging bridge and road repair obligations across the United States Midwest are expanding compact equipment fleet procurement. State transportation agencies specify ISO 14397-1 certified units for tipping load verification.
- Electric powertrain R&D allocation:Battery-electric architectures are capturing disproportionate engineering investment as urban noise ordinances and zero-emission zones proliferate. Fast-charging infrastructure buildouts in metropolitan construction corridors enable runtime benchmarks competitive with diesel.
- Track loader terrain access:Sub-4 psi ground pressure specifications are opening wetland and sensitive subgrade applications previously inaccessible to wheeled units. Landscaping contractors deploy these variants for urban green infrastructure projects.
Market Restraints
- Engine compartment redesign costs:EPA Tier 4 Final compliance requires thermal management and aftertreatment system integration that adds engineering expense and physical envelope constraints. Manufacturers absorb these costs or pass them through to price-sensitive rental fleets.
- Steel and hydraulic component volatility:Input cost fluctuations for high-strength steel and precision hydraulic valves compress margin predictability. Supply concentration for specialized castings in foundry clusters creates bottleneck exposure.
- Attachment ecosystem lock-in:Proprietary coupler designs and control interfaces create switching friction for end users invested in specific manufacturer attachment portfolios. This technical moat limits cross-platform interoperability.
Strategic Opportunities
- Sub-75-horsepower agricultural crossover:Farm operators seeking multi-purpose compact loaders represent an underpenetrated buyer segment. Equipment financing through agricultural credit channels differs from construction lending, requiring dedicated go-to-market restructuring.
- Telematics-platform unbundling:Fleet management purchasing criteria increasingly separate hardware from data services. Independent software vendors can integrate across OEM platforms, disintermediating proprietary systems.
- EU Green Deal machinery retrofit incentives:European rental fleets face accelerated replacement schedules under carbon intensity benchmarks. CE marking compliance for refurbished Tier 4 units creates secondary market arbitrage potential.
Industry Challenges
- Certification timeline compression:ISO 14397-1 operating capacity verification and EU Machinery Directive testing protocols must execute in parallel for multi-destination production lines. Regulatory divergence between EPA and ECHA emissions frameworks strains homologation resources.
- Electric powertrain integration complexity:Battery thermal management, motor control firmware, and legacy hydraulic system interfacing require cross-functional engineering coordination. Field service technician retraining for high-voltage systems extends rollout timelines.
- Silica exposure enclosure sealing:OSHA permissible exposure limits demand cabin pressurization and filtration system validation. Third-party certification for operator protection adds procurement cycle friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skid Steer Loader Market |
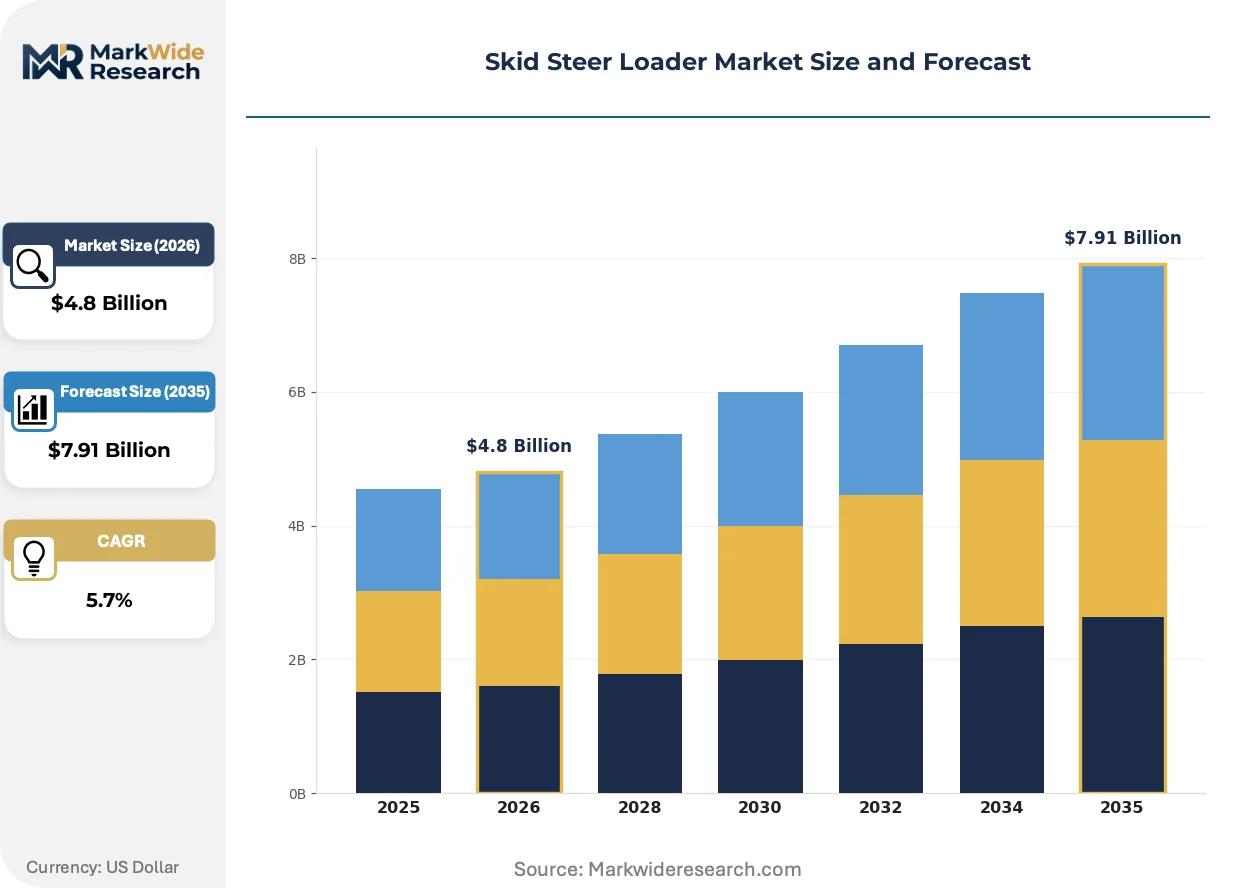
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Skid Steer, Track Loader, Wheeled Loader, Mini Loader End User: Construction, Agriculture, Landscaping, Waste Management Technology: Hydraulic, Electric, Diesel, Hybrid Size: Mini, Standard, Large, Extra Large |
| Companies Covered | GEHL, New Holland, Bobcat, Kubota, JCB, Caterpillar, Case, ASV, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skid Steer Loader Market Strategic Shifts & Innovations
Powertrain diversification and connected fleet architectures are redrawing competitive boundaries, with regulatory compliance and runtime economics now determining procurement outcomes more than lift capacity specifications.
Telematics integration is fragmenting fleet management purchasing criteria across construction and landscaping verticals. Contractors now expect real-time location tracking, utilization logging, and predictive maintenance alerts as standard features rather than premium upgrades. Equipment lessors differentiate through data service tiers, compressing hardware margin capture into recurring revenue models.
EPA Tier 4 Final standards are forcing engine compartment thermal redesigns that displace legacy packaging configurations. Aftertreatment systems for diesel particulate filtration and selective catalytic reduction consume additional envelope space, constraining operator visibility and service access. Compact equipment manufacturers serving California's CARB jurisdictions face the most stringent implementation timelines.
Rental channel preference for certified compliance packages is displacing bare-equipment procurement. Landscape contractors and municipal fleets now specify EPA Tier 4 Final and OSHA silica-certified units as baseline requirements, not optional upgrades. This behavioral shift concentrates volume with manufacturers offering bundled regulatory documentation and field validation support.
Skid Steer Loader Market Segmentation
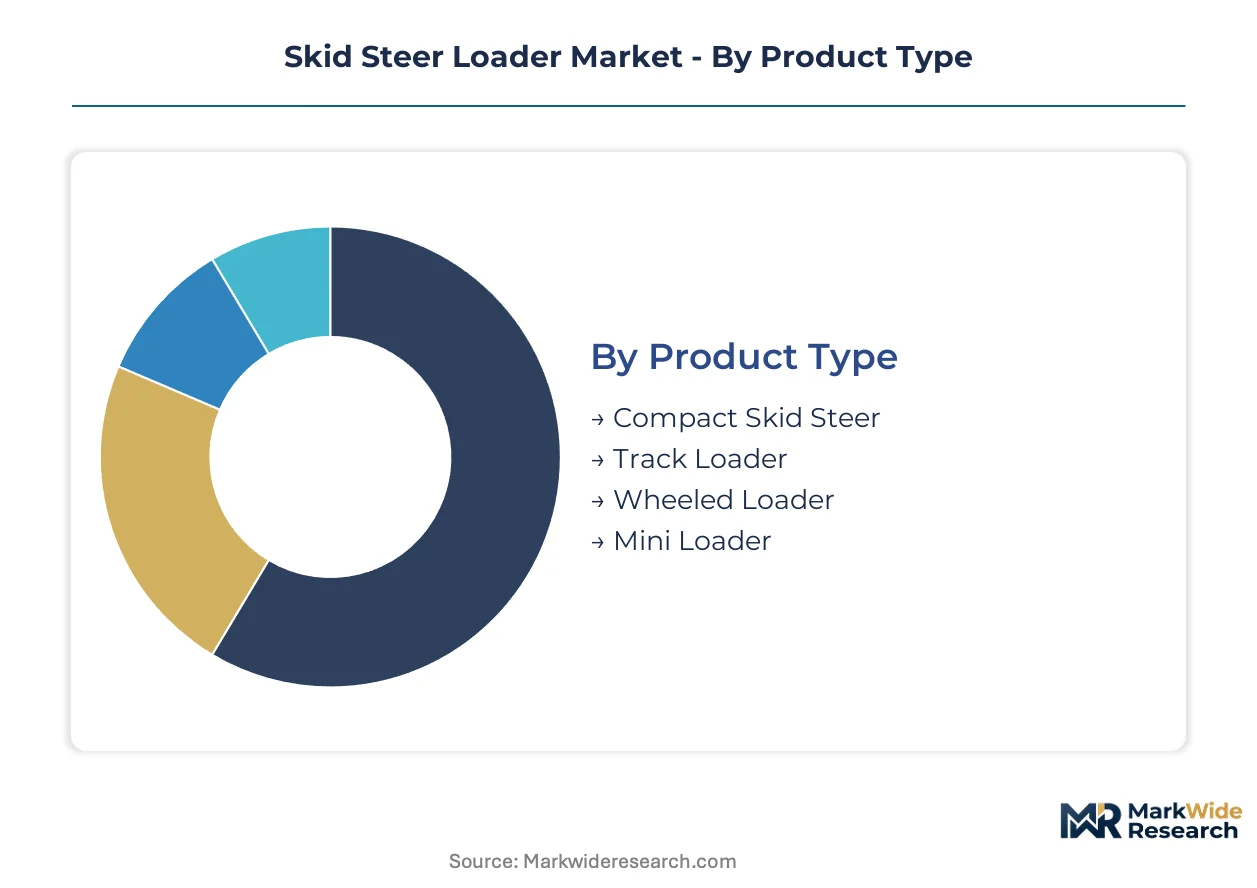
Segmentation in skid steer loaders determines equipment specification, procurement channel, and financing structure across divergent end-use economics. Product architecture and powertrain choices create distinct competitive arenas with different margin profiles and substitution vulnerabilities.
Product Type:
Track loaders face the most acute substitution pressure from compact excavators and mini dumpers in tight-access material handling, while wheeled variants compete with compact wheel loaders in open-yard applications.
- Compact Skid Steer:Units rated below 2,000 pounds operating capacity dominate residential construction and light commercial maintenance. Rental yards in the United States Midwest stock these configurations most densely for seasonal landscaping turnover.
- Track Loader:Sub-4 psi ground pressure specifications enable wetland access and sensitive terrain work. Landscaping contractors deploying these units for urban green infrastructure projects in Minnesota and Wisconsin drive replacement demand.
- Wheeled Loader:Higher travel speeds suit road maintenance and material yard shuttle applications.
- Mini Loader:Sub-1,000-pound capacity units access pedestrian pathways and interior demolition sites.
Compact skid steer retains volume leadership; track loader holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive fleet purchasers from seasonal rental-dependent operators, reshaping distribution and service bundling requirements.
- Construction:General contractors and specialty trades deploy skid steers for site prep, material handling, and attachment-driven tasks. Bridge and road repair obligations across Iowa, Illinois, and Ohio state transportation agencies sustain fleet renewal cycles.
- Agriculture:Farm operators seek multi-purpose compact loaders for feed handling, manure management, and light tillage. Agricultural credit channels finance these acquisitions differently than construction equipment lending.
- Landscaping:Urban green infrastructure budgets in Chicago, Detroit, and Indianapolis expand rental demand for certified low-emission units.
- Waste Management:Transfer stations and recycling facilities specify reinforced guarding and specialized attachment packages.
Construction commands absolute volume; landscaping gains share fastest.
Technology:
Application requirements dictate powertrain selection, with runtime demands and refueling infrastructure determining viable architectures for each deployment pattern.
- Diesel:EPA Tier 4 Final aftertreatment systems dominate current fleet composition. Thermal management redesigns constrain operator visibility and service access, particularly for California CARB jurisdictions.
- Electric:Battery architectures capture disproportionate R&D allocation as urban noise ordinances and zero-emission zones proliferate. Fast-charging infrastructure buildouts in metropolitan construction corridors enable competitive runtime benchmarks.
- Hydraulic:Legacy drive systems persist in price-sensitive rental segments.
- Hybrid:Dual powertrain configurations target intermittent-duty applications with variable load profiles.
Diesel retains installed base dominance; electric climbs the fastest.
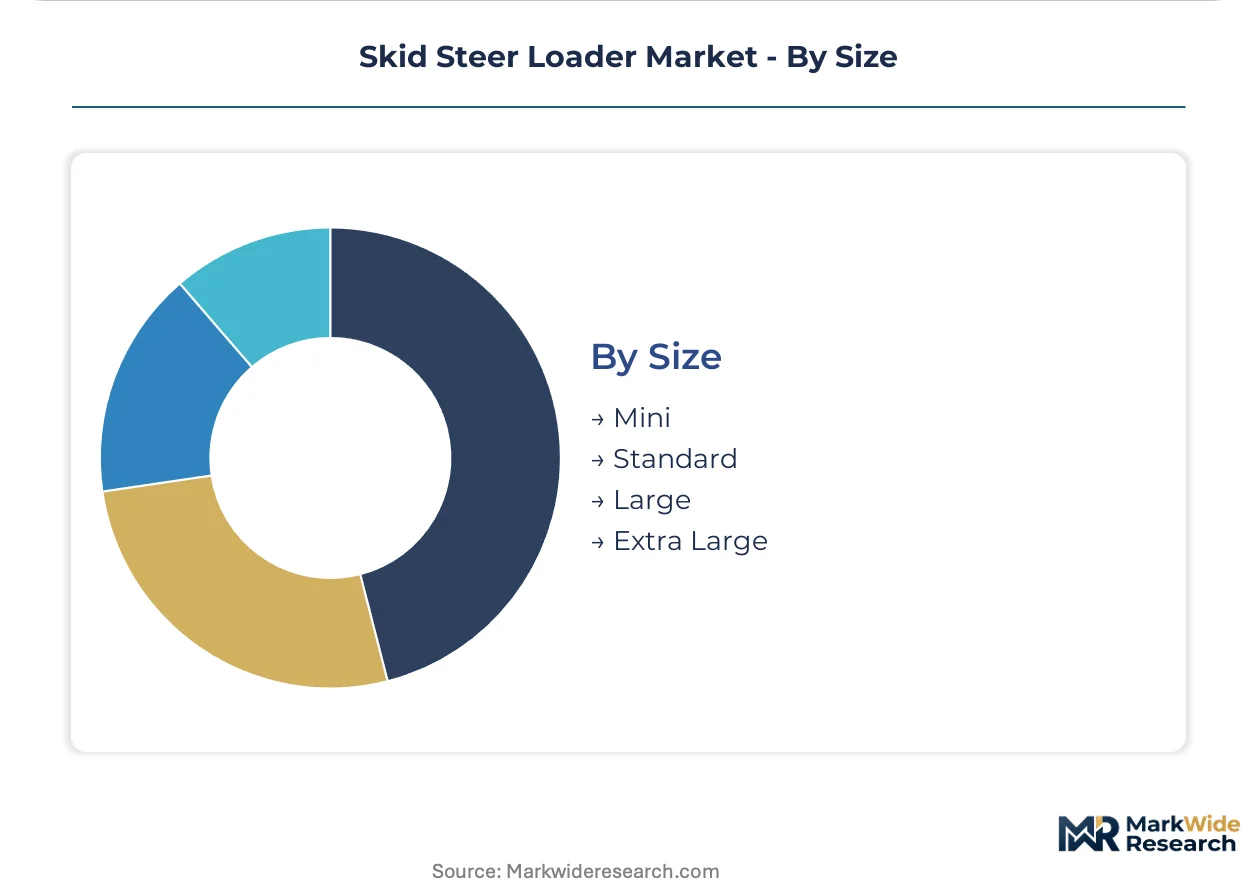
Size:
Customer type fragmentation separates owner-operators from fleet managers, with procurement authority and specification influence varying sharply by organization scale.
- Standard:Mid-range units between 1,500 and 2,500 pounds rated operating capacity balance versatility and transportability. Municipal infrastructure agencies specify ISO 14397-1 certified units in this range for tipping load verification.
- Mini:Sub-1,000-pound capacity machines access confined job sites and interior work zones. Landscaping contractors in dense urban cores deploy these for sidewalk repair and tree planting operations.
- Large:2,500-3,500 pound capacity units serve heavy material handling and attachment-intensive applications.
- Extra Large:Maximum capacity configurations above 3,500 pounds address specialized industrial and demolition tasks.
Standard size retains procurement volume leadership; mini holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal fleet managers and agricultural cooperatives dominate procurement across concentrated manufacturing corridors. State transportation agencies in the United States Midwest specify certified compact equipment for infrastructure rehabilitation. European rental fleets face accelerated replacement schedules under carbon intensity benchmarks.
United States
Bridge repair obligations across Iowa, Illinois, and Ohio sustain fleet renewal cycles for state transportation agencies. EPA Tier 4 Final mandates compress procurement timelines for compliant diesel architectures. Minneapolis-St. Paul and Milwaukee metropolitan construction corridors drive track loader deployment for urban green infrastructure projects.
Germany
Precision agriculture operators in Lower Saxony and Bavaria seek multi-purpose compact loaders for feed handling operations. EU Machinery Directive testing protocols and CE marking requirements segment production lines for European rental fleets. Stuttgart industrial cluster hosts engineering centers developing battery-electric powertrain integration for municipal applications.
China
Urban demolition contractors in the Yangtze River Delta deploy mini loaders for interior site access. MIIT emission standards and GB certification protocols govern domestic equipment registration. Shanghai metropolitan construction zones impose noise ordinances accelerating electric powertrain trials.
Japan
Landscaping contractors in Tokyo and Osaka prefectures rent compact equipment for seasonal urban maintenance. METI energy efficiency guidelines influence municipal procurement specifications. Nagoya industrial corridor concentrates hydraulic component manufacturing for regional OEM supply.
Canada
Wetland remediation contractors in Alberta and British Columbia specify sub-4 psi ground pressure track loaders for sensitive terrain access. Health Canada and provincial environmental regulators enforce emission standards aligned with EPA Tier 4 Final. Edmonton and Calgary municipal fleets expand compact equipment procurement for road maintenance obligations.
Skid Steer Loader Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with captive engine and hydraulic component capabilities. Market structure consolidates around three to four integrated manufacturers controlling attachment ecosystem architectures and dealer network density. Strategic archetypes include full-line construction equipment houses, agricultural machinery crossovers, and compact equipment specialists. Competitive moves concentrate on telematics platform unbundling and electric powertrain R&D partnerships with battery cell suppliers.
Within the full-line construction tier, Caterpillar and John Deere occupy positions defined by proprietary fleet management systems and vertical control over component supply. Bobcat exemplifies the compact equipment specialist archetype with concentrated attachment portfolio development. Kubota represents the agricultural machinery crossover segment leveraging sub-75-horsepower engineering heritage for farm operator penetration.
| Leading Market Players |
|---|
| GEHL |
| New Holland |
| Bobcat |
| Kubota |
| JCB |
| Caterpillar |
| Case |
| ASV |
| John Deere |
| Others |
Cost & Logistics Intelligence
Foundry capacity utilization above 85 percent in specialized casting clusters concentrates component supply for high-strength steel housings and precision hydraulic valves, establishing cost floors that OEMs either absorb or pass through to rental fleets. This scale concentration compresses margin flexibility for mid-tier manufacturers while reinforcing pricing power among vertically integrated producers with captive foundry operations.
Pricing Analysis
Cost-plus contracts indexed to steel commodity benchmarks dominate procurement between OEMs and rental fleet operators, with EPA Tier 4 Final certification packages commanding premium positioning over bare-equipment baselines. Price differentiation separates ISO 14397-1 certified units with tipping load verification from uncertified alternatives, while brand premiums attach to proprietary telematics integration. Pricing pressure stems from input cost volatility in hydraulic component supply, with municipal fleet purchasers exhibiting highest price sensitivity due to constrained capital budgets and construction contractors showing greater willingness to pay for compliance bundling.
Supply Chain Analysis
Just-in-time inventory strategies prevail among compact equipment assemblers for standardized hydraulic components, while strategic stockpiling of specialized castings insulates against foundry bottleneck exposure in the United States, Germany, and Japan. Raw material dependencies center on high-strength steel plate, precision hydraulic valves, and battery cell supply for electric architectures. Single-source vulnerability concentrates in German-engineered hydraulic systems and Chinese-processed rare earth elements for electric motor magnets. Distribution runs through captive dealer networks and independent rental yards with regional service coverage obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Attachment ecosystem services and predictive maintenance subscriptions expand faster than hardware unit sales, converting capital expenditure relationships into recurring revenue streams that improve customer lifetime value metrics across rental and contractor channels.
For Market Incumbents: Fortify proprietary telematics platform control by unbundling hardware from data services before independent software vendors achieve cross-OEM integration. Deepen backward integration into hydraulic component production to offset foundry concentration risk in German and Japanese supply clusters. Prioritize electric powertrain R&D partnerships with battery cell suppliers to defend against agricultural machinery crossovers entering sub-75-horsepower segments. For New Entrants and Emerging Players: Lead with electric powertrain architectures targeting urban landscaping contractors facing noise ordinance enforcement in Minneapolis-St. Paul and Milwaukee metropolitan corridors. Exploit underpenetrated agricultural credit channel financing for farm operator segments seeking multi-purpose compact loaders. Establish go-to-market presence through attachment interoperability certification rather than competing head-to-head on dealer network density. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compact equipment specialists with concentrated attachment portfolio development over diversified industrial conglomerates facing powertrain transition complexity. Five-to-ten year viability hinges on successful electric runtime benchmark achievement and fast-charging infrastructure capture in metropolitan construction zones. Monitor battery-electric fleet penetration rates in municipal procurement specifications as the critical inflection signal for powertrain architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Attachment Ecosystem Expansion | Bobcat's vertical control over quick-coupler standards locks rental yards into recurring attachment purchases. |
| Electric Powertrain Partnership | Battery cell supply agreements with Korean manufacturers secure runtime benchmarks competitive with diesel architectures. |
| Telematics Platform Unbundling | Caterpillar's proprietary fleet management data services displace hardware margin capture with subscription revenue. |
| Foundry Backward Integration | Captive casting production insulates Kubota from supply concentration exposure in Japanese precision component clusters. |
| Agricultural Credit Channel Restructuring | Equipment financing through Farm Credit System lending expands addressable market for sub-75-horsepower crossover units. |
Research Approach
A standing panel of fleet maintenance directors, rental yard operations managers, OEM procurement executives, and agricultural cooperative equipment specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA engine certification filings, OSHA silica exposure compliance databases, Association of Equipment Manufacturers shipment reports, and state transportation agency procurement records. Bottom-up unit demand modeling triangulated against top-down equipment stock replacement analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, powertrain technology, and rated operating capacity tier. CAGRs derived from equipment stock aging analysis and replacement cycle timing, with municipal infrastructure obligation schedules and electric charging infrastructure buildout trajectories serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Tier 4 Final enforcement and EU Machinery Directive CE marking protocols; material policy shifts in California CARB jurisdictions or EU Green Deal machinery retrofit incentives would require re-modeling. Practitioners should keep alternative scenarios live as battery-electric runtime benchmarks and fast-charging network density evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Dryers Market
Construction Equipment
Sandblast Nozzle Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Bale Openers Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
(AWP) Aerial Work Platform Rental Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Mobile Asphalt Plant Market