
 Global Desmopressin Market | 2026-2036
Global Desmopressin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desmopressin Market Foresight
Aftermarket service revenue from patient monitoring and adherence programs is tilting toward integrated care models that lock in prescriber loyalty. Ferring Pharmaceuticals leverages its urology specialty infrastructure to sustain direct-to-clinic relationships across European markets. Teva Pharmaceutical Industries anchors its position through broad generic desmopressin portfolios that compete aggressively on hospital tender pricing. Pfizer Inc. differentiates via hemophilia center partnerships that extend its reach into coagulation therapy protocols.
Desmopressin is a synthetic analog of vasopressin, structurally modified by deamination at the first amino acid and substitution of L-arginine with D-arginine at the eighth position, yielding enhanced antidiuretic potency with minimal vasoconstrictive activity. The peptide acts primarily on V2 receptors in renal collecting ducts to promote water reabsorption, and on endothelial V2 receptors to release von Willebrand factor for hemostatic applications. Tablets dominate volume due to chronic nocturia and diabetes insipidus maintenance therapy, while lyophilized powder commands premium positioning in surgical and hemophilia settings where rapid intravenous reconstitution is critical. Nasal spray formulations face structural decline amid FDA warnings regarding hyponatremia risk and unpredictable bioavailability, redirecting development toward oral liquid alternatives for pediatric populations.
FDA oversight of peptide manufacturing through Current Good Manufacturing Practice requirements shapes facility investment and batch release timelines for desmopressin producers. EMA's F-Gas Regulation and REACH chemical safety protocols influence excipient selection and packaging material compliance across European supply chains. India's CDSCO accelerates market entry for domestic manufacturers such as Sun Pharmaceutical Industries and Cadila Healthcare through streamlined abbreviated new drug application pathways. Stakeholders must monitor evolving pharmacovigilance requirements for hyponatremia labeling and pediatric dosing guidance as regulatory scrutiny intensifies across major prescribing markets.
Market Dynamics
Hospital procurement consolidation across Germany, the United States, and Japan is concentrating purchasing power and compressing tender margins for desmopressin suppliers. Formulation manufacturers now compete on integrated care protocols rather than molecule price alone.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate pediatric formulation development for diabetes insipidus and hemophilia indications.
- Perioperative Coagulation Management:North American health systems expand desmopressin stocking for surgical bleeding protocols, creating institutional demand anchors.
- Aging Demographics:Germany, Japan, and the United States report rising nocturia diagnoses among patients over sixty-five, sustaining chronic prescription volumes.
Market Restraints
- Hyponatremia Safety Labeling:FDA warnings on nasal spray formulations restrict prescribing freedom and trigger formulary exclusions in risk-averse institutions.
- Peptide Manufacturing Concentration:Current Good Manufacturing Practice compliance costs limit viable production to a handful of specialized facilities in Switzerland and Germany.
- Oral Solid Dosage Substitution:Tablet and liquid alternatives displace intravenous demand in maintenance therapy settings, compressing premium pricing power.
Strategic Opportunities
- Pediatric Oral Liquids:Unmet need in children under twelve with diabetes insipidus creates white space for palatable, dose-flexible formulations.
- EMA Pediatric Investigation Plans:Structured development pathways reduce regulatory uncertainty for sponsors targeting juvenile indications.
- Integrated Adherence Monitoring:Digital pill dispensers linked to urology clinics lock in prescriber loyalty through outcome tracking.
Industry Challenges
- Peptide Synthesis Expertise Scarcity:Solid-phase manufacturing requires chemists trained in GMP peptide chemistry, a talent pool concentrated in Basel and Boston.
- Batch Release Timeline Compression:FDA and EMA pharmacovigilance updates demand rapid label revisions, straining regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desmopressin Market |
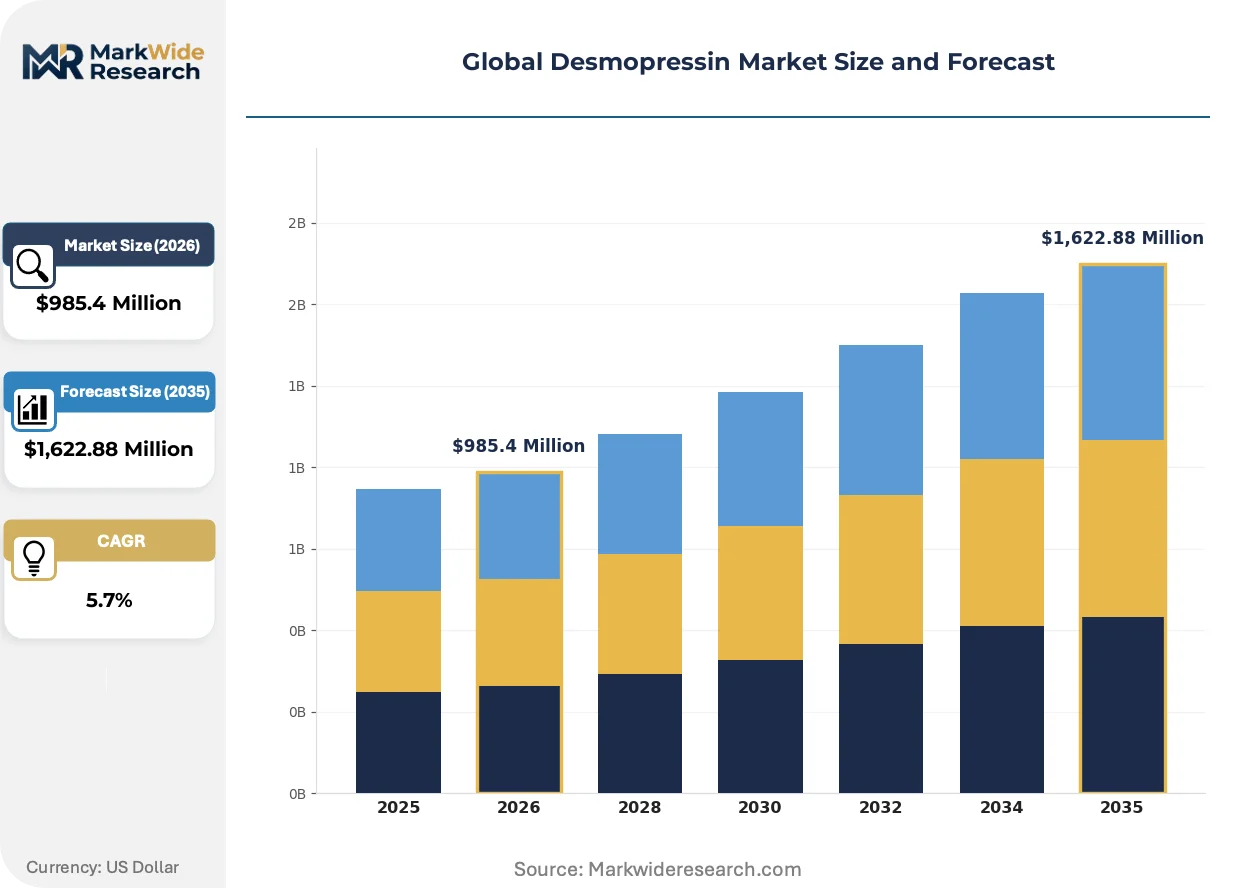
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $1,622.88 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Nasal Spray, Injection, Oral Liquid, Lyophilized Powder Therapy Area: Nocturia, Diabetes Insipidus, Hemophilia A, Von Willebrand Disease, Postoperative Bleeding End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Wholesale Distributors |
| Companies Covered | Ferring Pharmaceuticals, Teva Pharmaceutical Industries, Pfizer Inc., Sun Pharmaceutical Industries, Cadila Healthcare, Shanghai Soho-Yiming Pharmaceuticals, Sanofi, Mylan N.V., NorthStar Rx LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desmopressin Market Shifts & Advancements
Formulation technology and procurement digitization are restructuring how desmopressin reaches end-users. Three developments dominate competitive differentiation.
Orally disintegrating tablet technology eliminates water requirements for diabetes insipidus patients with swallowing difficulties. Geriatric wards in Japanese hospitals adopt these formulations rapidly for nocturia management. Conventional immediate-release tablets are rendering obsolete in institutional settings where patient compliance determines reimbursement.
EMA's F-Gas Regulation restricts hydrofluorocarbon propellants in nasal spray devices, forcing excipient reformulation across European supply chains. Manufacturers substitute nitrogen-powered systems or abandon inhalation routes entirely. German and French tenders now specify propellant-free delivery as a technical requirement.
Hospital buying groups in the United States consolidate desmopressin procurement under centralized pharmacy and therapeutics committees. Independent physician prescribing loses ground to protocol-driven automated dispensing. This concentration is most visible in hemophilia treatment centers where standardized coagulation algorithms override individual brand preference.
Global Desmopressin Market Segmentation
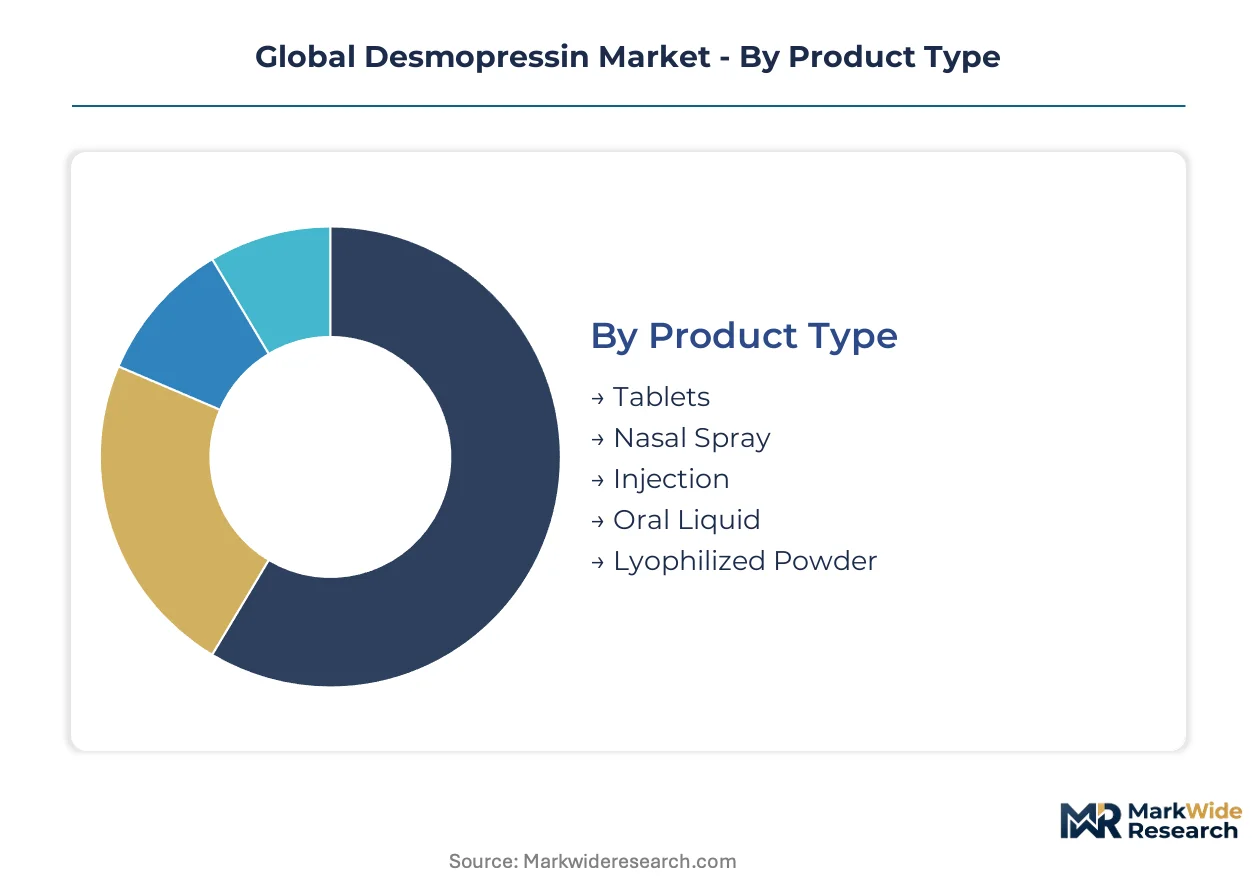
Desmopressin procurement patterns diverge sharply across formulation types and clinical settings, with after-sales monitoring intensity varying from intensive hemophilia center partnerships to routine retail pharmacy fulfillment. Understanding these segment boundaries clarifies where manufacturers must invest in adherence infrastructure versus price-competitive supply.
Product Type:
After-sales service intensity escalates with formulation complexity, from automated refill programs for chronic oral therapies to on-call clinical support for perioperative injectables.
- Tablets:Immediate-release and extended-release oral solids dominate chronic maintenance prescriptions for nocturia and diabetes insipidus. German and Japanese urology clinics drive volume through automated 90-day refill programs that lock in patient retention. By volume, tablets lead. By growth pace, lyophilized powder is ahead.
- Lyophilized Powder:Sterile vials requiring reconstitution command premium positioning in surgical suites and hemophilia treatment centers where rapid intravenous administration is critical. United States hospital systems stock these formulations for perioperative coagulation protocols, with manufacturers providing 24-hour clinical pharmacist hotlines.
- Nasal Spray:Metered-dose devices face structural decline amid FDA hyponatremia warnings and EMA F-Gas Regulation compliance costs.
- Injection:Pre-filled syringes and ampoules serve acute bleeding episodes in emergency departments.
- Oral Liquid:Pediatric-focused solutions address dose-flexibility needs for children under twelve with diabetes insipidus.
Formulation selection tracks clinical acuity, with higher-touch service models attaching to acute-care presentations.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention settings, with reimbursement intensity determining prescriber access.
- Nocturia:Chronic nighttime voiding disorders in patients over sixty-five sustain the largest prescription base across Germany, Japan, and the United States. Primary care urologists in Japan's geriatric wards prescribe oral disintegrating tablets for swallowing difficulties, with outcomes tracked through digital adherence platforms.
- Hemophilia A:Desmopressin-induced von Willebrand factor release provides non-transfusion hemostatic support for mild to moderate cases. United States hemophilia treatment centers incorporate the peptide into standardized coagulation algorithms, generating institutional demand anchors.
- Diabetes Insipidus:Central and nephrogenic forms require lifelong antidiuretic therapy, with pediatric patients driving formulation innovation.
- Von Willebrand Disease:Type 1 patients respond to V2 receptor-mediated factor release, particularly in perioperative settings.
- Postoperative Bleeding:Surgical protocols in North American health systems increasingly stock desmopressin for coagulation management.
By prescription volume, nocturia leads. By protocol-driven institutional penetration, hemophilia A is expanding most quickly.
End User:
Customer type determines procurement sophistication, from centralized hospital tenders to fragmented retail pharmacy fulfillment.
- Hospitals:Integrated health systems in Germany and the United States consolidate desmopressin purchasing under pharmacy and therapeutics committees, with automated dispensing cabinets driving protocol compliance. Perioperative coagulation management and emergency bleeding control generate the highest per-patient utilization.
- Specialty Clinics:Urology and hematology centers maintain direct manufacturer relationships for chronic therapy management, with Ferring Pharmaceuticals leveraging specialty infrastructure across European markets.
- Ambulatory Surgical Centers:Freestanding facilities stock limited formulations for same-day procedures.
- Diagnostic Laboratories:Reference labs utilize desmopressin challenge testing for diabetes insipidus confirmation.
By procurement scale, hospitals dominate. By prescriber loyalty intensity, specialty clinics are climbing the fastest.
Distribution Channel:
Supply concentration varies from captive hospital pharmacy networks to fragmented online fulfillment.
- Hospital Pharmacy:Centralized purchasing within integrated delivery networks captures the majority of perioperative and inpatient desmopressin volume in the United States and Germany.
- Retail Pharmacy:Community outlets fulfill chronic maintenance prescriptions for nocturia and diabetes insipidus, with 90-day supply programs common.
- Online Pharmacy:Digital channels gain traction for refill convenience among stable chronic patients.
- Wholesale Distributors:McKesson and AmerisourceBergen handle bulk procurement for hospital systems and retail chains.
By transaction volume, hospital pharmacy leads. By channel shift momentum, online pharmacy is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys desmopressin primarily for perioperative coagulation protocols, while Japan channels volume toward geriatric nocturia management. The United States splits demand across hemophilia treatment centers and hospital surgical suites.
Germany
Hospital procurement consolidation drives tender-based purchasing for intravenous formulations. EMA's F-Gas Regulation forces propellant-free nasal spray alternatives. The Rhine-Ruhr hospital network standardizes desmopressin stocking for bleeding disorder protocols.
United States
Hemophilia treatment centers embed desmopressin into standardized coagulation algorithms. FDA orphan drug incentives accelerate pediatric formulation development. Boston's specialty pharmacy cluster supports 24-hour clinical pharmacist hotlines for perioperative dosing.
Japan
Geriatric wards prescribe oral disintegrating tablets for nocturia patients with swallowing difficulties. PMDA pharmacovigilance updates tighten hyponatremia labeling requirements. Tokyo's integrated health systems deploy digital adherence platforms for chronic therapy tracking.
India
Domestic manufacturers supply affordable oral solids for diabetes insipidus maintenance therapy. CDSCO streamlined abbreviated new drug application pathways accelerate market entry. Gujarat's pharmaceutical manufacturing belt expands peptide synthesis capacity for export markets.
Switzerland
Specialized peptide manufacturing facilities serve European hospital tender demand. Swissmedic enforces Current Good Manufacturing Practice standards for batch release timelines. Basel's contract manufacturing organizations concentrate solid-phase synthesis expertise for lyophilized powder production.
Global Desmopressin Market Competitive Landscape
Capability concentration sits with specialty peptide manufacturers; scale advantage sits with broad generic portfolios. The market structures around three tiers: integrated multinational pharmaceutical companies with hemophilia center partnerships, regional urology-focused specialists with direct-to-clinic relationships, and domestic generic manufacturers competing on hospital tender pricing. Dominant competitive moves include specialty clinic loyalty programs and backward integration into peptide synthesis capacity.
Among integrated multinationals, Ferring Pharmaceuticals and Pfizer Inc. exemplify contrasting archetypes. Ferring anchors European market presence through urology specialty infrastructure and direct prescriber relationships. Pfizer occupies a position tied to hemophilia treatment center networks and institutional protocol penetration. Teva Pharmaceutical Industries represents the scale-driven tier with broad generic portfolios competing aggressively on hospital procurement pricing.
| Leading Market Players |
|---|
| Ferring Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Pfizer Inc. |
| Sun Pharmaceutical Industries |
| Cadila Healthcare |
| Shanghai Soho-Yiming Pharmaceuticals |
| Sanofi |
| Mylan N.V. |
| NorthStar Rx LLC |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor links Swiss peptide synthesis facilities to German hospital networks, with transport cost volatility amplifying price spreads between lyophilized powder and oral solid formulations while compressing margins for nasal spray variants facing EMA F-Gas compliance burdens.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement in Germany and the United States, locking in volume commitments for perioperative coagulation protocols. Three-tier pricing structure across premium intravenous formulations, standard oral tablets, and economy generic solids separates hemophilia treatment centers from retail urology clinics. Cost compression in the nasal spray segment is intensifying because FDA hyponatremia warnings trigger formulary exclusions. Retail pharmacy fulfillment for chronic nocturia maintenance shows highest price sensitivity; hemophilia center partnerships demonstrate lowest sensitivity due to protocol-driven standardization.
Supply Chain Analysis
Swissmedic export controls on solid-phase peptide synthesis equipment limit technology transfer to Indian and Chinese manufacturing aspirants, constraining capacity expansion outside Basel and Boston talent clusters. Active pharmaceutical ingredient production centers on Switzerland, Germany, and India, with formulation finishing distributed across regional hubs. Boc-protected amino acids and specialized resins for solid-phase synthesis draw from limited qualified suppliers. Single-source vulnerability concentrates in lyophilized powder sterile filling capacity. Distribution runs through captive hospital pharmacy networks in integrated US health systems and wholesale distributors McKesson and AmerisourceBergen for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
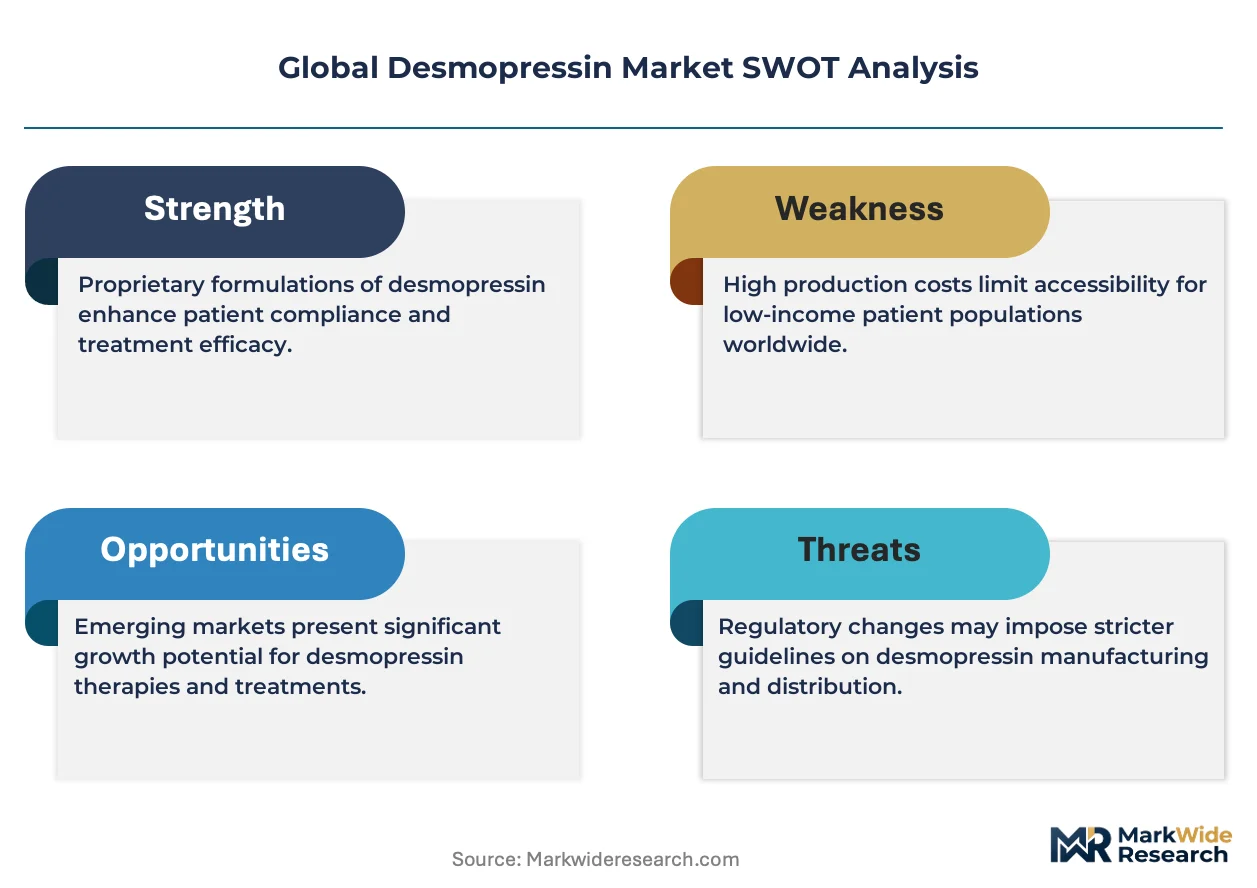
FDA orphan drug incentives and EMA pediatric investigation plans are reshaping competitive positioning, creating first-mover advantages for sponsors that secure pediatric formulation exclusivity ahead of indication expansion.
For Market Incumbents: Pre-empt generic erosion in oral solid dosage by securing pediatric liquid formulation approvals through FDA orphan pathways before patent cliffs accelerate. Backward integration into peptide synthesis capacity in Basel or Boston talent clusters defends against API supply bottlenecks. Lock in hemophilia treatment center partnerships through 24-hour clinical pharmacist support programs that embed desmopressin into standardized coagulation algorithms. For New Entrants and Emerging Players: Pediatric oral liquids for diabetes insipidus in children under twelve represent the most penetrable entry point, with dose-flexibility requirements creating formulation barriers for generic tablet manufacturers. CDSCO streamlined abbreviated new drug application pathways in India offer accelerated market entry for domestic manufacturers targeting export markets. Partner with Tokyo's integrated health systems on digital adherence platform integration to secure prescriber loyalty without direct hospital tender competition. For Investors and Strategic Acquirers: Specialized peptide contract manufacturing organizations with Swissmedic GMP certification and solid-phase synthesis expertise in the Basel region offer the strongest acquisition profile for long-term viability. Monitor EMA pediatric investigation plan submission rates as the inflection indicator for formulation innovation pipelines. CDSCO approval timelines for abbreviated new drug applications signal competitive pressure intensity from Indian generic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | FDA orphan drug exclusivity locks in seven-year market protection for diabetes insipidus indications. |
| Peptide Synthesis Capacity Expansion | Swiss and German GMP facilities command premium positioning amid manufacturing concentration constraints. |
| Hemophilia Center Partnership Programs | Protocol-driven institutional penetration embeds desmopressin into standardized coagulation algorithms. |
| Digital Adherence Platform Integration | Tokyo's geriatric wards deploy outcome tracking to sustain prescriber loyalty for chronic nocturia therapy. |
| Propellant-Free Delivery System Reformulation | EMA F-Gas Regulation compliance opens technical differentiation for nitrogen-powered nasal alternatives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads at EMA and FDA, formulary directors at German hospital networks, peptide manufacturing executives in Basel, and urology clinic prescribing heads in Japan; and secondary validation through FDA orphan drug designations, EMA pediatric investigation plan submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up prescription volume modeling triangulated against top-down market sizing from customs trade data and pharmaceutical distribution records.
Forecast inputs across the analysis window incorporate formulation type segmentation by route of administration, therapy area stratification across nocturia and hemophilia indications, end-user procurement sophistication tiers, and regional regulatory cluster differentiation. CAGRs derive from patient population epidemiology, protocol adoption curves in hemophilia treatment centers, and tender pricing trajectory analysis. Peptide manufacturing capacity constraints and CDSCO approval velocity feed directly into supply-side elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement intensity or hospital capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding FDA labeling stability and EMA F-Gas implementation timelines. Material shifts in pediatric investigation plan completion rates or Swiss peptide synthesis capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Japan Generic Drug Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Global Exocrine Pancreatic Insufficiency (EPI) Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
BRAF-MEK Inhibitors Market