
 Traumatic Brain Injury Drugs Market | 2026-2036
Traumatic Brain Injury Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Traumatic Brain Injury Drugs Market Analytics
Multi-source API procurement for neuroprotective compounds is consolidating around a smaller set of GMP-certified suppliers. Pfizer leverages its global manufacturing footprint to secure raw material continuity for analgesic and anticonvulsant portfolios. Teva Pharmaceutical Industries anchors its position through specialized generic formulations targeting post-TBI seizure management. BrainStorm Cell Therapeutics differentiates via autologous mesenchymal stem cell platforms directed at neurodegenerative sequelae.
Traumatic brain injury drugs comprise pharmaceutical agents designed to attenuate secondary neurological damage, manage intracranial pressure, and modulate neuroinflammatory cascades following blunt or penetrating head trauma. These therapies typically target glutamate excitotoxicity, oxidative stress pathways, or blood-brain barrier integrity, with formulation stability often requiring controlled-release matrices or parenteral delivery systems to achieve therapeutic concentrations in cerebrospinal fluid. Neuroprotective agents command premium pricing due to complex peptide stabilization requirements and limited manufacturing capacity, while intravenous delivery modes dominate acute-stage settings where rapid bioavailability determines clinical outcomes. Oral formulations sustain growth in subacute and chronic treatment stages as patients transition from hospital to rehabilitation center or home care environments.
FDA breakthrough therapy designation and EMA's PRIME scheme for neurological orphan indications compress development timelines and reshape competitive entry dynamics. The FDA's stringent Phase III endpoint requirements for cognitive recovery metrics influence trial design investments across the development pipeline. Stakeholders must monitor evolving reimbursement policies for cell-based therapies and position manufacturing assets to serve both institutional purchasers and emerging home infusion channels.
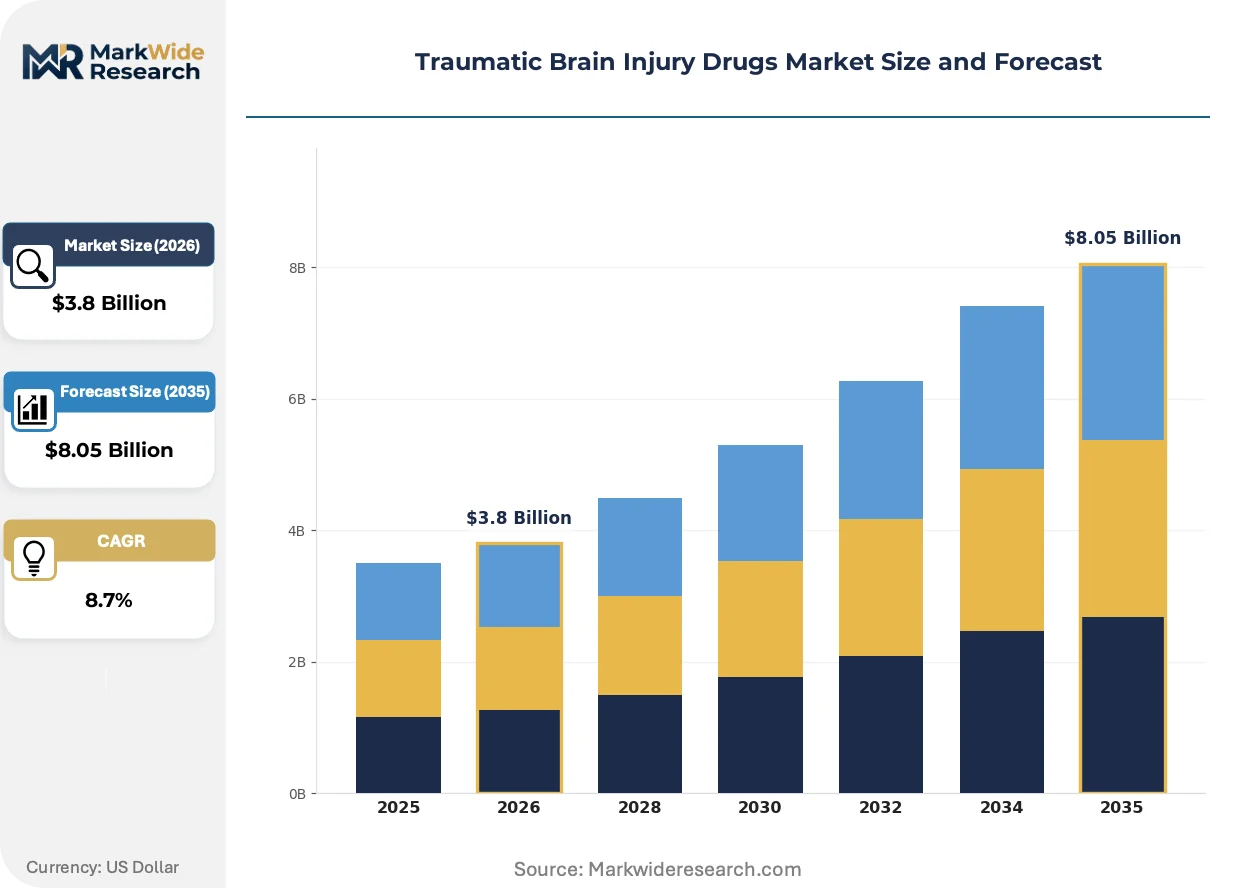
Market Dynamics
FDA breakthrough therapy designations for neurological indications are compressing clinical trial timelines and redistributing R&D capital toward neuroprotective candidates with biomarker-validated endpoints.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's breakthrough therapy designation shortens development cycles for neuroprotective agents targeting secondary brain injury cascades. Sponsors gain rolling review privileges and intensive agency guidance.
- Level I Trauma Network Expansion:United States trauma center certification standards now mandate protocolized neurocritical care, institutionalizing early pharmacologic intervention. This infrastructure locks in demand for acute-stage formulations.
- Biomarker-Guided Patient Stratification:Glial fibrillary acidic protein and ubiquitin C-terminal hydrolase L1 assays enable enrichment strategies in Phase III trials. Regulators accept these surrogate endpoints for accelerated approval.
Market Restraints
- Peptide Stabilization Costs:Neuroprotective biologics require lyophilization and cold-chain distribution. Manufacturing yield losses exceed small-molecule benchmarks by significant margins.
- Single-Source API Concentration:GMP-certified suppliers for specialized excipients cluster in Switzerland and Germany. Geopolitical friction threatens continuity for parenteral formulation components.
- Cognitive Endpoint Variability:FDA mandates standardized neuropsychological batteries for functional recovery claims. Inter-rater reliability issues inflate trial sample size requirements and extend enrollment periods.
Strategic Opportunities
- Home Infusion Channel Development:Subacute TBI patients transition to outpatient settings faster than reimbursement infrastructure permits. Specialty pharmacy networks capture margin from extended anticonvulsant tapering protocols.
- EMA PRIME Alignment:European regulators prioritize neurological orphan indications through accelerated assessment. Sponsors with FDA breakthrough status gain parallel procedural advantages for EU market entry.
- Autologous Cell Therapy Integration:Mesenchymal stem cell platforms address neurodegenerative sequelae outside acute pharmaceutical windows. Manufacturing partnerships with hospital-based cell processing facilities reduce logistics complexity.
Industry Challenges
- Neurocritical Care Specialist Scarcity:Board-certified intensivists with TBI protocol expertise concentrate in academic medical centers. Community hospital adoption lags despite standardized guidelines.
- Cell Therapy Manufacturing Scale-Up:Autologous platforms require patient-specific batch processing. Current cleanroom capacity constraints limit commercial expansion beyond Phase III cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traumatic Brain Injury Drugs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Anticonvulsants, Neuroprotective Agents, Anti-inflammatory Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Treatment Stage: Acute, Subacute, Chronic, Palliative |
| Companies Covered | Pfizer, Teva Pharmaceutical Industries, Fresenius, Oragenics, SHINKEI Therapeutics, Hope Biosciences, BrainStorm Cell Therapeutics, Neuren Pharmaceuticals, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traumatic Brain Injury Drugs Market Evolving Landscape
Neuropharmacology is pivoting from empirical symptom management toward mechanism-based interventions validated by circulating biomarker panels. This shift reconfigures trial design, reimbursement negotiation, and prescriber education investments across the development pipeline.
Controlled-release intrathecal delivery systems are integrating into acute care protocols to maintain therapeutic cerebrospinal fluid concentrations without repeated lumbar puncture. Neurosurgical services at Johns Hopkins and Mayo Clinic pilot these platforms for refractory intracranial hypertension. The technology is integrating continuous pressure monitoring with automated dosing algorithms, compressing nursing labor intensity in intensive care units.
EMA's PRIME scheme for neurological orphan indications now mandates pediatric investigation plans earlier in development. Sponsors must submit extrapolation strategies for adolescent TBI populations before Phase II completion. This regulatory tightening most affects neuroprotective peptides with narrow therapeutic indices, forcing reformulation investments for weight-based dosing flexibility.
Hospital procurement committees now unbundle neurocritical care pharmaceuticals from bundled payment contracts. Stand-alone value assessments for neuroprotective agents require pharmacoeconomic models demonstrating reduced ventilator days. This behavioral shift concentrates purchasing authority within pharmacy and therapeutics committees at United States academic medical centers, displacing individual prescriber discretion in protocol selection.
Traumatic Brain Injury Drugs Market Segmentation
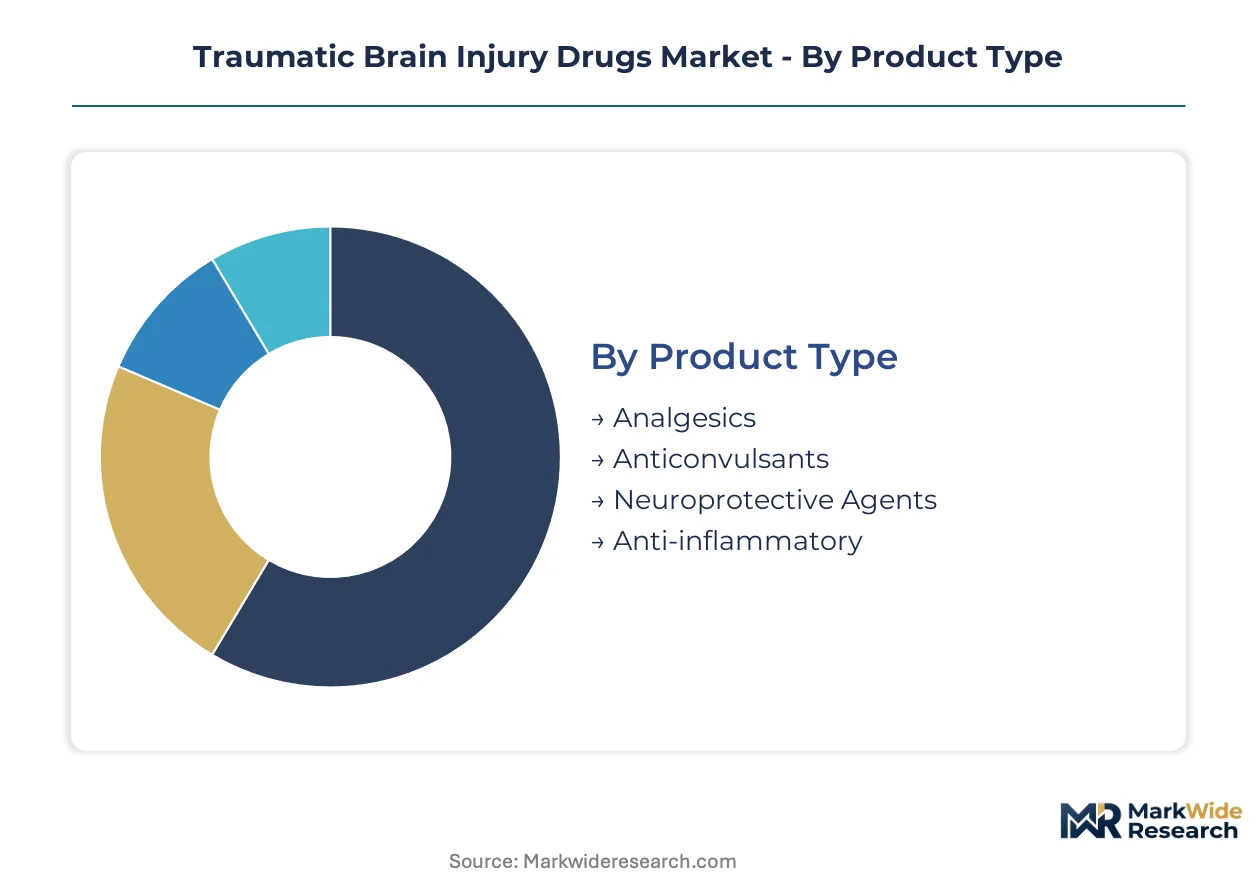
Segmentation in the traumatic brain injury drugs market reveals distinct clinical utility patterns across pharmacological classes and care settings. Treatment protocols vary sharply between emergency neurocritical care and long-term rehabilitation, driving divergent formulation requirements and procurement behaviors.
Product Type:
Formulation chemistry determines therapeutic windows, manufacturing complexity, and reimbursement positioning across the four pharmacological categories.
- Neuroprotective Agents:Peptide-based biologics targeting glutamate excitotoxicity and oxidative stress cascades require lyophilization and cold-chain integrity. Demand concentrates in United States Level I trauma centers where FDA breakthrough-designated candidates command premium positioning through protocol standardization.
- Anticonvulsants:Small-molecule therapies modulate post-traumatic seizure prophylaxis through sodium channel blockade and GABA potentiation. Rehabilitation centers in Germany and Japan drive volume for extended-release oral formulations supporting outpatient tapering protocols.
- Analgesics:Opioid and non-opioid pain management compounds address acute headache and cranial trauma discomfort through intravenous and oral routes.
- Anti-inflammatory:Corticosteroid and NSAID formulations target neuroinflammatory modulation with narrower therapeutic indices requiring biomarker-guided dosing.
Neuroprotective agents lead on scale through acute-care premium capture; anticonvulsants lead on momentum via rehabilitation channel expansion.
Delivery Mode:
Route of administration directly shapes bioavailability profiles, nursing labor intensity, and patient transition feasibility across care settings.
- Intravenous:Parenteral delivery achieves rapid cerebrospinal fluid penetration for neurocritical care protocols. United States hospital systems mandate IV-first approaches for Glasgow Coma Scale scores below 13, locking in demand for infusion-compatible formulations.
- Oral:Tablet and capsule formulations sustain therapeutic concentrations during subacute and chronic recovery phases. Home care environments in the United Kingdom and Australia prioritize oral routes reducing skilled nursing dependency.
- Subcutaneous:Depot injections and continuous infusion pumps bridge acute-to-chronic transitions with intermediate pharmacokinetic profiles.
- Topical:Transdermal patches and localized applications address adjunctive symptom management with limited CNS penetration.
Intravenous formulations dominate acute-stage value capture; oral routes gain share fastest through early discharge incentives.
End User:
Institutional capabilities and reimbursement structures create distinct purchasing authority patterns across the care continuum.
- Hospitals:Academic medical centers and trauma-designated facilities concentrate neurocritical care expertise and pharmacy and therapeutics committee authority. United States Medicare severity-adjusted diagnosis-related group payments institutionalize bundled neuropharmaceutical procurement.
- Rehabilitation Centers:Post-acute facilities manage anticonvulsant tapering and neuroplasticity-focused pharmacotherapy. German neurological rehabilitation clinics (Neuro-Reha) set European standards for interdisciplinary medication management protocols.
- Home Care:Outpatient settings require patient-administered formulations with simplified dosing regimens and caregiver training support.
- Clinics:Ambulatory neurology practices handle chronic TBI follow-up with emphasis on cognitive side effect monitoring.
Hospitals anchor revenue concentration through acute-stage premium pricing; rehabilitation centers show steepest expansion trajectory via protocolized post-acute pharmacotherapy.
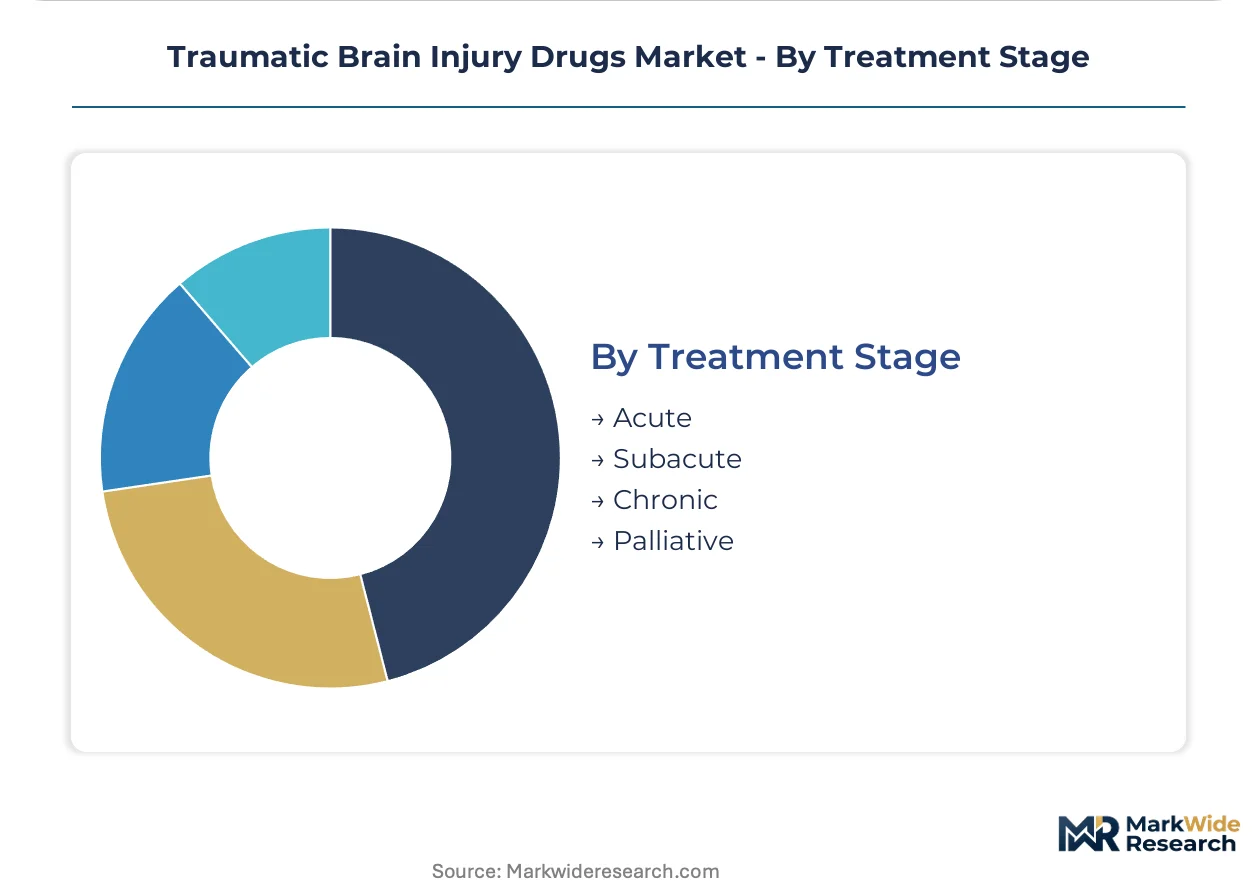
Treatment Stage:
Temporal positioning relative to injury onset determines therapeutic objectives, biomarker integration, and regulatory pathway eligibility.
- Acute:Emergency interventions within 72 hours target intracranial pressure management and secondary injury prevention. FDA breakthrough therapy designations concentrate in this window with biomarker-enriched trial endpoints.
- Subacute:Interventions from 72 hours to 6 months address neuroinflammatory resolution and early neuroplasticity support. Japanese stroke and TBI rehabilitation networks prioritize this phase for pharmacological neurorecovery trials.
- Chronic:Long-term management of post-concussion syndrome and neurodegenerative sequelae requires sustained-release formulations and cognitive monitoring.
- Palliative:End-of-life symptom control for severe TBI outcomes emphasizes comfort-focused medication regimens.
Acute-stage therapies command highest per-patient revenue; subacute interventions are climbing the fastest through rehabilitation network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Level I trauma center networks institutionalize protocolized neurocritical care and drive acute-stage pharmaceutical demand. Regulatory pathways and reimbursement structures in specific countries reshape competitive entry dynamics and manufacturing investment patterns.
United States
FDA breakthrough therapy designations compress clinical trial timelines for neuroprotective candidates targeting secondary brain injury cascades. Medicare severity-adjusted diagnosis-related group payments institutionalize bundled neuropharmaceutical procurement at academic medical centers. Johns Hopkins and Mayo Clinic pilot intrathecal delivery systems with automated dosing algorithms in Baltimore and Rochester.
Germany
EMA PRIME scheme alignment accelerates assessment for neurological orphan indications, creating parallel procedural advantages for sponsors with FDA breakthrough status. German neurological rehabilitation clinics set European standards for interdisciplinary medication management protocols. GMP-certified suppliers for specialized excipients cluster in Swiss and German manufacturing corridors.
Japan
PMDA regulatory frameworks prioritize pharmacological neurorecovery trials in stroke and TBI rehabilitation networks during the subacute treatment window. METI industrial policy supports domestic manufacturing capacity for parenteral formulation components. Tokyo and Osaka metropolitan areas concentrate neurocritical care specialist training programs.
United Kingdom
Home care environments prioritize oral formulations reducing skilled nursing dependency as patients transition from hospital to rehabilitation settings. NHS England reimbursement policies for cell-based therapies remain under active negotiation. London and Southeast England anchor pharmaceutical distribution infrastructure serving subacute and chronic treatment stages.
Australia
TGA regulatory pathways influence biomarker-guided patient stratification strategies for glial fibrillary acidic protein assays in Phase III trials. National trauma registry data informs protocol standardization across state-based health systems. Sydney and Melbourne concentrate neuropharmacology research institutions collaborating with Asia-Pacific clinical trial networks.
Traumatic Brain Injury Drugs Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and specialized formulation capabilities. Market structure consolidates around large-cap pharmaceutical conglomerates with neuroprotective and anticonvulsant portfolios, mid-tier generic specialists, and emerging cell therapy platforms. Three archetypes dominate: diversified pharmaceutical conglomerates leveraging global manufacturing footprints, specialized generic formulators targeting post-TBI seizure management, and autologous cell therapy developers addressing neurodegenerative sequelae. Competitive moves concentrate on strategic partnerships with hospital-based cell processing facilities and capacity expansion for GMP-certified peptide stabilization.
Among diversified pharmaceutical conglomerates, Pfizer anchors scale-driven manufacturing for analgesic and anticonvulsant portfolios. Teva Pharmaceutical Industries exemplifies specialized generic formulation capabilities in post-TBI seizure management. BrainStorm Cell Therapeutics occupies a position within the autologous mesenchymal stem cell platform segment directed at neurodegenerative sequelae.
| Leading Market Players |
|---|
| Pfizer |
| Teva Pharmaceutical Industries |
| Fresenius |
| Oragenics |
| SHINKEI Therapeutics |
| Hope Biosciences |
| BrainStorm Cell Therapeutics |
| Neuren Pharmaceuticals |
| Integra LifeSciences |
| Others |
Value Network & Pricing Analysis
Cold-chain sustainability mandates from the European Union's F-Gas Regulation and analogous EPA guidelines in the United States now gate qualified supply access for neuroprotective peptide manufacturers, with compliant logistics infrastructure becoming the threshold for premium-tier pricing authority in acute-care contracts.
Pricing Analysis
Input-cost pass-through from specialized excipients and lyophilization energy requirements dominates neuroprotective agent pricing, with peptide stabilization failures inflating per-batch manufacturing overhead by multiples versus small-molecule benchmarks. Three-tier pricing structure across breakthrough-designated biologics, standard neuroprotectives, and generic anticonvulsants reflects FDA certification status and GMP-audit tier. Pricing pressure stems from Medicare bundled payment compression at United States academic medical centers, forcing volume commitments for formulary access. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity; Level I trauma networks with protocol standardization mandates show lowest.
Supply Chain Analysis
GMP certification for parenteral peptide excipients gates supplier participation, with qualified manufacturing clustering in Switzerland, Germany, and select United States facilities. Cold-chain logistics draws from specialized refrigerant suppliers and validated container providers, with cleanroom capacity for autologous cell therapy processing resting on hospital-based partnerships. Single-source API concentration in Swiss-German manufacturing corridors creates tariff exposure vulnerability under evolving transatlantic trade frameworks. Distribution runs through institutional purchasing consortia and specialty pharmacy networks serving subacute transition protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where rehabilitation network expansion and biomarker-validated endpoints shift procurement authority toward manufacturers with demonstrated neurorecovery outcomes.
For Market Incumbents: Extend manufacturing footprints into hospital-adjacent cell processing partnerships to capture autologous therapy logistics before cleanroom capacity constraints harden. Deepen backward integration into peptide excipient supply through captive relationships with Swiss and German GMP-certified suppliers, insulating against single-source concentration risk as geopolitical friction intensifies. For New Entrants and Emerging Players: Launch via home infusion channel partnerships targeting subacute anticonvulsant tapering protocols, where reimbursement infrastructure lags behind patient discharge velocity. White-space concentrates in Japanese rehabilitation networks pursuing pharmacological neurorecovery trials and Australian state-based trauma registry integration for biomarker-guided patient stratification. For Investors and Strategic Acquirers: Roll-up economics work for specialized generic formulators with post-TBI seizure management portfolios because Medicare bundled payment standardization concentrates purchasing authority within pharmacy and therapeutics committees. Target mid-tier manufacturers with GMP-certified peptide stabilization capabilities and established Level I trauma center relationships. Signal to monitor: FDA breakthrough therapy designation velocity for neuroprotective candidates with GFAP-validated endpoints.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP-certified cleanroom expansion addresses autologous cell therapy capacity constraints at hospital-based processing facilities. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for biomarker-enriched neuroprotective candidates. |
| Licensing Agreement | Specialized excipient partnerships secure raw material continuity for lyophilized peptide formulations. |
| Pipeline Diversification | Intrathecal delivery platform development targets refractory intracranial hypertension protocols at Johns Hopkins and Mayo Clinic. |
| Hospital System Partnership | Academic medical center alliances embed automated dosing algorithms within neurocritical care protocols. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Australia, with primary inputs from each market informing demand calibration and regulatory pathway assessment. The study combines structured interviews with neurocritical care specialists, hospital pharmacy and therapeutics committee chairs, regulatory affairs leads at neurological drug sponsors, and formulary directors at United States academic medical centers with secondary validation from FDA breakthrough therapy designation announcements, EMA PRIME scheme assessments, ClinicalTrials.gov neuroprotective agent registrations, and Medicare severity-adjusted diagnosis-related group payment schedules. Bottom-up patient flow modeling and top-down pharmaceutical procurement value triangulation anchor volume and value estimates.
Granularity extends to pharmacological class, delivery mode, end-user institution type, and treatment stage relative to injury onset, with regional regulatory clusters modeled separately for pathway velocity assessment. CAGRs derive from patient incidence projections, protocol penetration assumptions, and pricing trajectory analysis across the projection horizon. Forecast inputs incorporate Level I trauma center network expansion rates, biomarker assay adoption curves, and rehabilitation channel reimbursement evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA cognitive endpoint requirement changes or EMA pediatric investigation plan tightening. Model outputs reflect assumptions regarding biomarker surrogate endpoint acceptance and cell therapy manufacturing scale feasibility. A model refresh is warranted upon material change in Medicare bundled payment neuropharmaceutical unbundling policies or Swiss-German excipient supply continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Global Inhaled Antibiotics Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Carbapenem Antibiotics Market