
 Germany Industrial Wood Coatings Market | 2026-2036
Germany Industrial Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Industrial Wood Coatings Market Foresight
The direct-to-miller distribution channel is reconfiguring as national coating distributors consolidate regional warehousing across Bavaria and Saxony. Meffert AG Farbwerke leverages its Black Forest production base to sustain same-day delivery commitments for midsize carpentry workshops. Hesse-Lignal anchors southern German market share through specialized hardwood finishing systems. Teknos Deutschland GmbH competes on industrial roller-coating lines for high-volume flooring producers.
Germany industrial wood coatings comprise resin-based protective and decorative films applied to timber substrates, typically ranging from 40 to 120 microns dry-film thickness, designed to enhance abrasion resistance, moisture protection, and aesthetic uniformity in factory settings. Spray coating technology dominates furniture manufacturing lines for complex geometries, while roller coating captures margin pools in continuous flooring production due to near-zero overspray and material efficiency. Waterborne polyurethane leads product-type growth as VOC thresholds tighten, whereas nitrocellulose maintains entrenched position in artisan musical instrument finishing where rapid solvent evaporation enables hand-rubbed luster.
REACH registration requirements and the EU Green Deal's carbon-border adjustments compel reformulation of solvent-borne systems, while Germany's Federal Emission Control Act (BImSchV) mandates real-time VOC monitoring at industrial coating facilities. ECHA substance evaluations further restrict isocyanate exposure limits, accelerating investment in blocked-catalyst waterborne hardeners. Stakeholders must monitor pending amendments to the EU Industrial Emissions Directive that could mandate closed-loop solvent recovery for facilities above threshold coating volumes.
Market Dynamics
REACH registration requirements and BImSchV emission controls are forcing wholesale reformulation of solvent-borne coating systems across German industrial wood finishing operations.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Manufacturers accelerating waterborne polyurethane R&D to avoid import penalties on carbon-intensive formulations.
- Furniture OEMs in Baden-Württemberg:Carpentry clusters demanding low-VOC systems to maintain export eligibility into Nordic markets with stricter environmental standards.
- Blocked-catalyst waterborne hardeners:New chemistry eliminating isocyanate exposure risks while matching solvent-borne durability in continuous roller-coating lines.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compressing margins for white and pastel decorative finishes in mid-tier flooring segments.
- Specialty resin supply concentration:Bio-based polyol production clustering in Benelux creates single-source vulnerability for German formulators.
- Isocyanate exposure thresholds:ECHA substance evaluations tightening workplace limits faster than blocked-catalyst alternatives can achieve commercial scale.
Strategic Opportunities
- North Rhine-Westphalia industrial furniture belt:Untapped demand for UV-curable waterborne hybrids in high-volume panel processing.
- Closed-loop solvent recovery:Pending EU Industrial Emissions Directive amendments creating first-mover advantage for facilities investing in recovery infrastructure.
- Digital color-matching platforms:Direct-to-miller distributors integrating spectrophotometry tools to reduce reformulation cycles for custom hardwood finishes.
Industry Challenges
- Formulation chemist scarcity:Shortage of specialists capable of balancing bio-based content with BImSchV compliance timelines.
- Legacy spray-line retrofit costs:Capital intensity of converting conventional booths to waterborne-compatible humidity and temperature controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Industrial Wood Coatings Market |
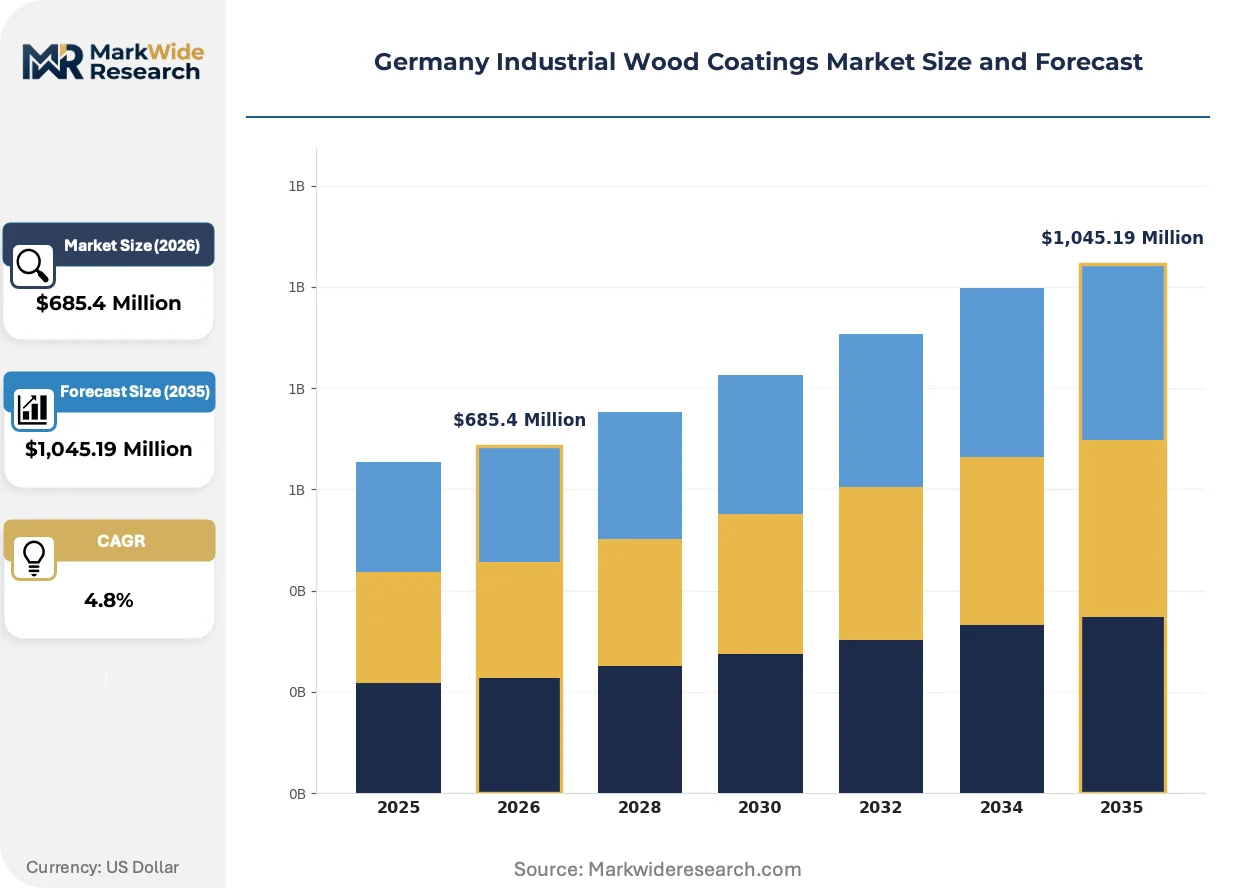
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Epoxy, Waterborne, Nitrocellulose Technology: Spray Coating, Dip Coating, Roller Coating, Brush Application, Flow Coating Application: Furniture Manufacturing, Flooring, Cabinet, Musical Instruments, Decorative Panels End User Industry: Carpentry Workshops, Interior Designers, OEM Manufacturers, Custom Woodworking, Artisan Producers |
| Companies Covered | Meffert AG Farbwerke, Hesse-Lignal, Henkel AG & Co KGaA, IVM Chemicals GmbH, Teknos Deutschland GmbH, HUELSEMANN Coatings GmbH, Weilburger Coatings GmbH, AkzoNobel NV, DAW SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Industrial Wood Coatings Market Shifts & Advancements
Digital integration across coating specification and application is compressing development cycles while regulatory chemistry mandates drive material science investment.
UV-LED curable waterborne systems are virtualizing the traditional thermal curing bottleneck in continuous flooring production. High-volume manufacturers in North Rhine-Westphalia adopting hybrid UV-LED lines achieve instant through-cure without heat-sensitive substrate damage. This technology is virtualizing the capital-intensive infrared tunnel ovens that previously dominated roller-coating installations.
BImSchV real-time VOC monitoring mandates are compelling industrial facilities to install continuous emission measurement systems. German coating operations above threshold volumes now face immediate production halts for exceedance events rather than periodic inspection penalties. Flooring producers with continuous lines are most exposed, driving investment in predictive maintenance algorithms for spray booth capture efficiency.
Specification workflows are migrating to cloud-based substrate-coating matching platforms. Bavarian and Saxony distributors consolidating regional warehousing now offer digital color libraries reducing physical sample shipment requirements. Carpentry workshops in the Black Forest cluster leverage these tools to accelerate custom hardwood finish approvals, compressing the traditional weeks-long matching process to same-day confirmation.
Germany Industrial Wood Coatings Market Segmentation
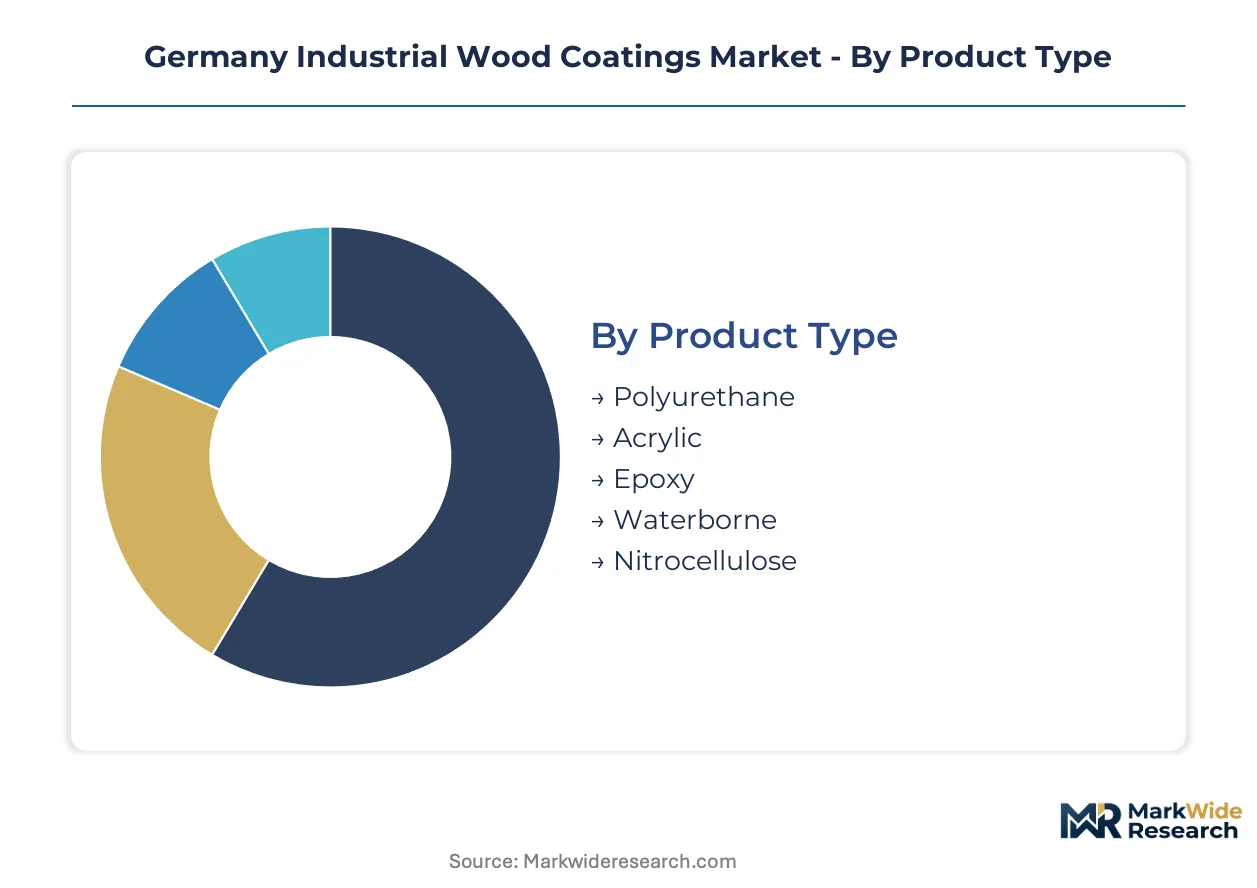
Segmentation in Germany's industrial wood coatings market reveals distinct performance profiles across formulation chemistry, application method, and customer scale. Cycle times vary dramatically — continuous flooring lines turn inventory weekly while artisan musical instrument finishing operates on quarterly batches. Understanding these velocity differentials shapes inventory positioning and technical service resource allocation.
Product Type:
Reformulation cycles separate fast-adapting waterborne systems from legacy solvent platforms with decade-long qualification timelines.
- Polyurethane:Two-component aliphatic systems deliver abrasion resistance exceeding 1000 Taber cycles for high-traffic flooring applications. Baden-Württemberg carpentry clusters specify polyurethane for kitchen cabinetry facing moisture exposure and thermal cycling.
- Waterborne:Blocked-isocyanate hardeners now achieve solvent-borne durability in continuous roller-coating lines without workplace exposure risks. North Rhine-Westphalia flooring producers are converting spray booths to accommodate waterborne humidity and temperature requirements.
- Acrylic:UV-stable formulations for exterior joinery applications with limited penetration in interior industrial segments.
- Epoxy:High-build systems reserved for specialty industrial substrates requiring chemical resistance beyond standard wood finishing.
- Nitrocellulose:Rapid solvent evaporation enables hand-rubbed finishes in Black Forest musical instrument workshops where traditional luster remains non-negotiable.
Waterborne polyurethane anchors the volume base while nitrocellulose gains share at the steepest rate among legacy holdouts in premium artisan segments.
Technology:
Capital intensity and material efficiency create divergent margin structures across application methods.
- Roller Coating:Near-zero overspray and 95% transfer efficiency capture margin pools in continuous flooring production. North Rhine-Westphalia panel processors operate multi-head roller lines achieving 40-120 micron films in single passes.
- Spray Coating:Dominates furniture manufacturing for complex geometries where three-dimensional coverage remains essential. Bavarian distributors stock specialized low-pressure spray equipment for midsize carpentry workshops.
- Dip Coating:Uniform film deposition for turned components and small furniture parts with limited German industrial presence.
- Brush Application:Confined to touch-up operations and prototype finishing outside continuous production environments.
- Flow Coating:Specialized vertical surface treatment for cabinet doors and panel edges in custom woodworking operations.
Roller coating anchors the volume base while UV-LED curable spray systems gain share at the steepest rate among technology conversions.
Application:
Production scale and specification complexity segment demand across end-use categories.
- Furniture Manufacturing:OEM producers in Baden-Württemberg and North Rhine-Westphalia drive specification authority for waterborne systems. Kitchen and office furniture lines require coordinated color matching across batch cycles.
- Flooring:Continuous production lines demand real-time viscosity control and instant cure compatibility. Hesse-Lignal maintains specialized hardwood finishing systems for engineered plank producers.
- Cabinet:Frame-and-panel construction requires edge-sealing compatibility with face-film systems.
- Musical Instruments:Hand-rubbed nitrocellulose traditions in artisan violin and guitar finishing resist waterborne conversion despite regulatory pressure.
- Decorative Panels:High-volume melamine-competing segments where coating cost per square meter dominates procurement decisions.
Furniture manufacturing anchors the volume base while flooring gains share at the steepest rate among waterborne conversion investments.
End User Industry:
Customer scale determines technical service intensity and distribution channel economics.
- OEM Manufacturers:High-volume furniture and flooring producers with in-house color laboratories and direct formulation relationships. REACH compliance documentation requirements favor integrated supply agreements.
- Carpentry Workshops:Midsize Baden-Württemberg clusters demanding same-day delivery and digital color matching through consolidated Bavarian and Saxony distribution.
- Custom Woodworking:Project-based operations with specification volatility and limited inventory carrying capacity.
- Artisan Producers:Musical instrument and specialty furniture makers prioritizing traditional finish aesthetics over regulatory compliance speed.
- Interior Designers:Specification influence without direct procurement authority in most German industrial segments.
OEM manufacturers anchor the volume base while carpentry workshops gain share at the steepest rate among digital distribution investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg commands premium pricing leverage over North Rhine-Westphalia due to specialized artisan demand density, while standardized flooring production in the latter compresses margin structures through volume procurement.
Baden-Württemberg
Carpentry clusters in Freiburg and Stuttgart drive specification authority for low-VOC waterborne systems in kitchen cabinetry. BImSchV emission thresholds force continuous booth monitoring investments across midsize workshops. The Black Forest musical instrument corridor sustains nitrocellulose demand despite REACH pressure, with violin makers prioritizing hand-rubbed finish traditions over compliance speed.
North Rhine-Westphalia
Industrial furniture OEMs in Bielefeld and Detmold anchor high-volume roller-coating consumption for engineered flooring panels. EU Green Deal carbon-border adjustments accelerate waterborne polyurethane conversion to avoid import penalties. The region's continuous production lines demand real-time viscosity control systems and instant-cure compatibility.
Bavaria
Furniture manufacturing around Nuremberg and Munich concentrates procurement through consolidated distribution networks. REACH registration documentation requirements favor integrated supply agreements with coating formulators. Bavarian distributors deploying digital color-matching platforms reduce physical sample shipment requirements for custom hardwood finishes.
Hesse
Engineered plank producers in the Frankfurt-Rhine-Main metropolitan area source specialized hardwood finishing systems for export-oriented flooring operations. ECHA isocyanate exposure limit evaluations drive blocked-catalyst waterborne hardener trials. Hesse-based formulators maintain technical service proximity to high-specification flooring customers.
Lower Saxony
Panel processing facilities near Hanover supply decorative surfaces for residential construction with cost-per-square-meter procurement discipline. Pending EU Industrial Emissions Directive amendments create uncertainty around closed-loop solvent recovery mandates. Lower Saxony operations below threshold coating volumes face delayed compliance timelines relative to larger facilities.
Germany Industrial Wood Coatings Market Competitive Landscape
Specialized regional formulators and diversified multinational chemical groups split the market along customization-versus-scale lines. The vendor structure concentrates technical service resources in southern German carpentry clusters while standardizing formulations for northern industrial volume. Three archetypes dominate: Black Forest-based specialists serving artisan musical instrument makers, North Rhine-Westphalia-anchored industrial coating suppliers, and Benelux-dependent bio-based resin distributors. Competitive moves center on distributor warehousing consolidation and blocked-catalyst chemistry licensing.
Among Germany-based specialists, Meffert AG Farbwerke and Hesse-Lignal occupy positions anchored in regional production geography, while Teknos Deutschland GmbH represents the Nordic-origin industrial coating archetype with German subsidiary operations. These three exemplify the segmentation between artisan-serving formulators with same-day delivery commitments and industrial-scale suppliers optimizing continuous line compatibility.
| Leading Market Players |
|---|
| Meffert AG Farbwerke |
| Hesse-Lignal |
| Henkel AG & Co KGaA |
| IVM Chemicals GmbH |
| Teknos Deutschland GmbH |
| HUELSEMANN Coatings GmbH |
| Weilburger Coatings GmbH |
| AkzoNobel NV |
| DAW SE |
| Others |
Supply & Pricing Matrix
Rhine-Alpine freight corridors linking Benelux resin plants to Baden-Württemberg carpentry clusters transmit feedstock cost volatility directly into formulation pricing, while distribution consolidation across Bavaria and Saxony compresses margin capture for mid-tier waterborne systems.
Pricing Analysis
The customization-premium spread between artisan-configured nitrocellulose finishes and standard waterborne flooring systems runs three to four levels deep. Pricing stratifies across premium hand-rubbed musical instrument coatings, specification-grade kitchen cabinetry systems, and economy panel finishes competing with melamine alternatives. Cost compression in white and pastel decorative tiers stems from titanium dioxide feedstock swings. OEM flooring manufacturers in North Rhine-Westphalia exhibit highest price sensitivity due to continuous-line volume procurement, while Black Forest violin makers accept premium positioning for traditional luster chemistry.
Supply Chain Analysis
Contract manufacturing concentration for bio-based polyol intermediates rests with Benelux specialty chemical producers serving German formulators. Geographic supply concentration clusters in Belgium, the Netherlands, and eastern German resin synthesis corridors. Raw material dependencies center on isocyanate precursors, blocked-catalyst hardeners, and UV-curable oligomer feedstocks. Single-source vulnerability in bio-based polyol production creates exposure to ECHA substance evaluation disruptions. Distribution runs through consolidated Bavarian and Saxony warehousing networks with same-day delivery commitments to midsize carpentry workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German industrial wood coatings incumbents face substitution defense imperatives as powder coating and thermal transfer film technologies encroach on decorative panel segments.
For Market Incumbents: Pre-empt blocked-catalyst waterborne hardener licensing agreements to secure formulation differentiation before ECHA isocyanate limits tighten further. Backward integration into captive bio-based polyol production mitigates Benelux supply concentration risk. Secure exclusive distributor relationships in consolidating Bavarian and Saxony warehousing networks to defend channel control against Nordic-origin competitors.
For New Entrants and Emerging Players: Untapped demand for UV-curable waterborne hybrids in North Rhine-Westphalia's high-volume panel processing lines represents the most penetrable entry point. Digital color-matching platform integration with regional distributors offers a technology-led go-to-market angle bypassing legacy formulation relationships. Artisan musical instrument finishing in the Black Forest corridor provides niche premium positioning with limited incumbent specialization.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming industrial coatings divisions lacking waterborne conversion focus. Long-term viability hinges on bio-based chemistry R&D depth and regulatory compliance documentation infrastructure. Monitor ECHA substance evaluation timelines for isocyanate exposure limits as inflection indicators for blocked-catalyst technology adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Polyol Production | Captive supply of renewable feedstocks reduces Benelux single-source vulnerability for German formulators. |
| Blocked-Catalyst Waterborne Hardener Licensing | Technology partnerships accelerate compliance with ECHA isocyanate exposure threshold reductions. |
| Regional Warehousing Consolidation | Bavarian and Saxony distribution hubs enable same-day delivery commitments to midsize carpentry clusters. |
| UV-LED Curable System Development | Instant through-cure compatibility addresses North Rhine-Westphalia continuous flooring line requirements. |
| Digital Color-Matching Platform Deployment | Spectrophotometry integration compresses custom hardwood finish approval cycles for Black Forest workshops. |
Research Methodology
Cross-validation between primary interviews with coating formulators, procurement leads at furniture OEMs, and distribution channel partners anchors the qualitative findings against secondary validation from REACH registration databases, BImSchV emission compliance records, and customs trade data for resin imports. Plant managers at Baden-Württemberg carpentry clusters and technical R&D directors at regional formulators provided operational perspective. Bottom-up segmentation modeling triangulates with top-down macroeconomic calibration across the German manufacturing sector.
Calibration against historical formulation conversion cycles and regulatory compliance cost trajectories shapes the projection framework. Segmentation dimensions include resin chemistry type, application technology, end-use industry vertical, and regional production cluster density. CAGRs derive from elasticity-adjusted demand modeling incorporating VOC threshold tightening schedules and carbon-border adjustment implementation. Industry-specific forecast inputs capture blocked-catalyst hardener adoption curves and UV-LED curing infrastructure deployment rates.
Practitioners should monitor ECHA substance evaluation timelines, titanium dioxide feedstock contract renegotiations, and EU Industrial Emissions Directive amendment progress for early signals of forecast revision. Quarterly review of BImSchV compliance exceedance reports and distributor warehousing consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Paints and Coatings Additives Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
India Industrial Coatings Market
Paints & Coatings
South America Paints and Coatings Market
Paints & Coatings
Global Exterior Architectural Coatings Market