
 Structured Data Management Software Market | 2026-2036
Structured Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Structured Data Management Software Market Analytics
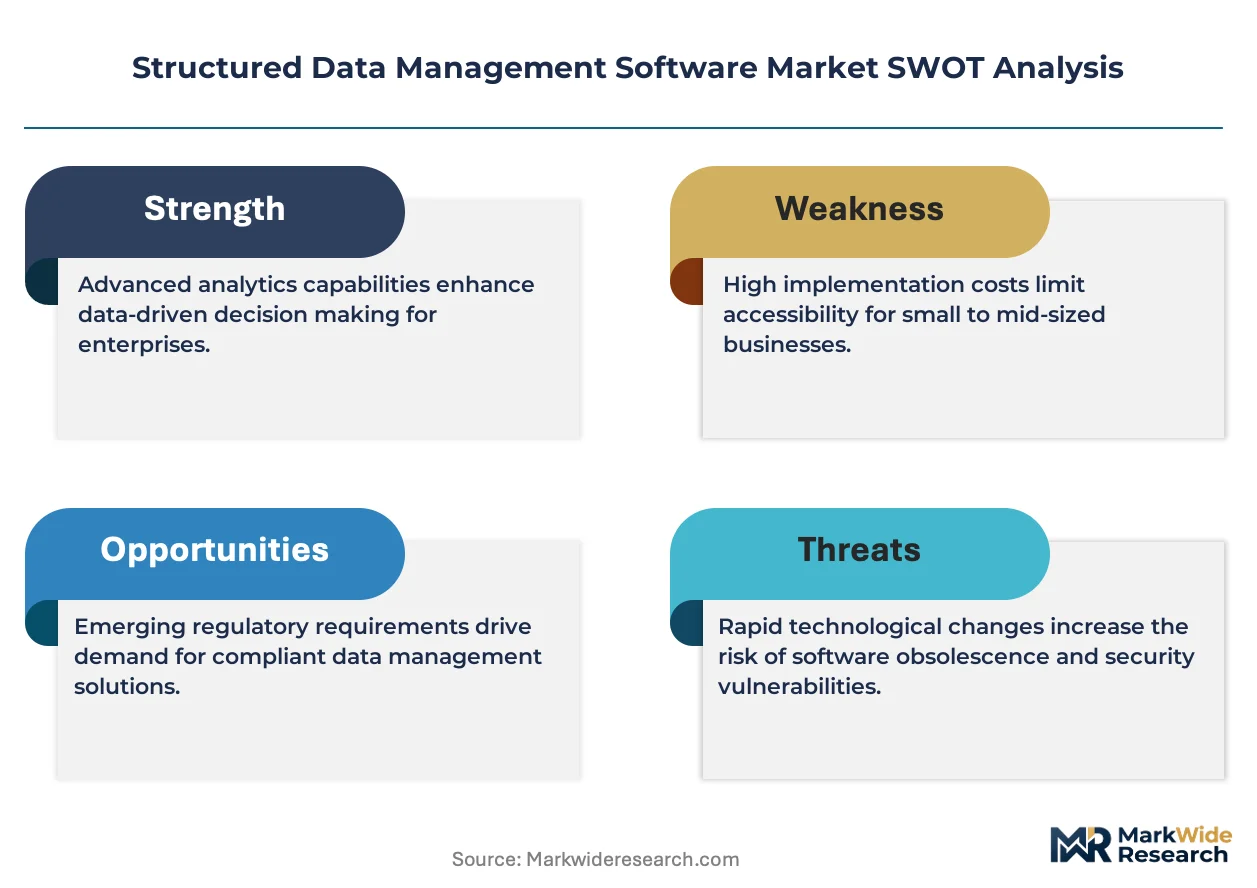
Aftermarket service revenue from legacy on-premises maintenance is narrowing as enterprises accelerate SaaS and cloud-native transitions. Informatica leverages its dual-deployment architecture to sustain enterprise relationships across hybrid environments. Oracle anchors its position through deep database integration, while Ataccama competes aggressively on AI-augmented data quality automation.
Structured Data Management Software encompasses platforms that enforce schema consistency, lineage tracking, and policy-driven governance across relational and transactional data stores, typically operating through metadata repositories, business rule engines, and automated profiling pipelines to ensure interoperable, auditable datasets for operational and analytical workloads. Cloud-based deployment represents the fastest-expanding segment as organizations retire capital-intensive data center commitments, while data governance solutions command premium pricing due to escalating regulatory exposure and the complexity of cross-border data residency requirements. Metadata management retains steady uptake among enterprises consolidating fragmented analytics estates.
The EU AI Act and GDPR impose strict provenance and bias-auditing obligations that directly expand demand for governance and lineage tools across European operations. In the United States, SEC climate disclosure rules and HIPAA data integrity standards are pushing BFSI and healthcare buyers toward certified quality management frameworks. Stakeholders must weigh interoperability commitments against vendor lock-in risks as platform consolidation accelerates.
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR are forcing enterprises to retire legacy on-premises data architectures, compressing procurement cycles for governance and quality tools as compliance deadlines harden.
Growth Catalysts
- EU AI Act Provenance Mandates:European financial services firms must deploy automated lineage tracking to satisfy bias-auditing obligations, expanding demand for metadata management platforms.
- India's PLI Scheme for Data Centers:Domestic hyperscale construction is accelerating structured data volume growth, pulling governance software procurement into Mumbai and Hyderabad clusters.
- Real-Time Streaming Integration:Apache Kafka and Flink pipelines now require schema registry enforcement, embedding data quality automation directly into operational workflows.
Market Restraints
- Specialized Talent Scarcity:Shortages of data stewards and metadata architects in Germany and the United States are extending implementation timelines and inflating service costs.
- Cloud Concentration Risk:AWS, Azure, and GCP control over 70% of enterprise data storage, creating dependency exposure as these platforms bundle competing governance tools.
- Cross-Border Data Friction:GDPR data residency requirements conflict with India's data localization mandates, complicating multi-national deployment architectures.
Strategic Opportunities
- Underpenetrated Manufacturing Vertical:German automotive and industrial equipment producers lag financial services in governance maturity, representing untapped seats for quality automation platforms.
- Federated Learning Convergence:Combining differential privacy with structured data governance enables privacy-preserving analytics across healthcare networks without raw data movement.
- SEC Climate Disclosure Rules:US-listed enterprises must establish auditable emissions data pipelines, creating certified framework demand that vendors can capture through sustainability module expansion.
Industry Challenges
- Mainframe Integration Complexity:COBOL-era systems at US banks and insurers resist API-based lineage extraction, requiring costly custom connector development.
- Certification Timeline Compression:ISO 27001 and SOC 2 audit cycles for cloud-native deployments now overlap with product release schedules, straining DevOps resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structured Data Management Software Market |
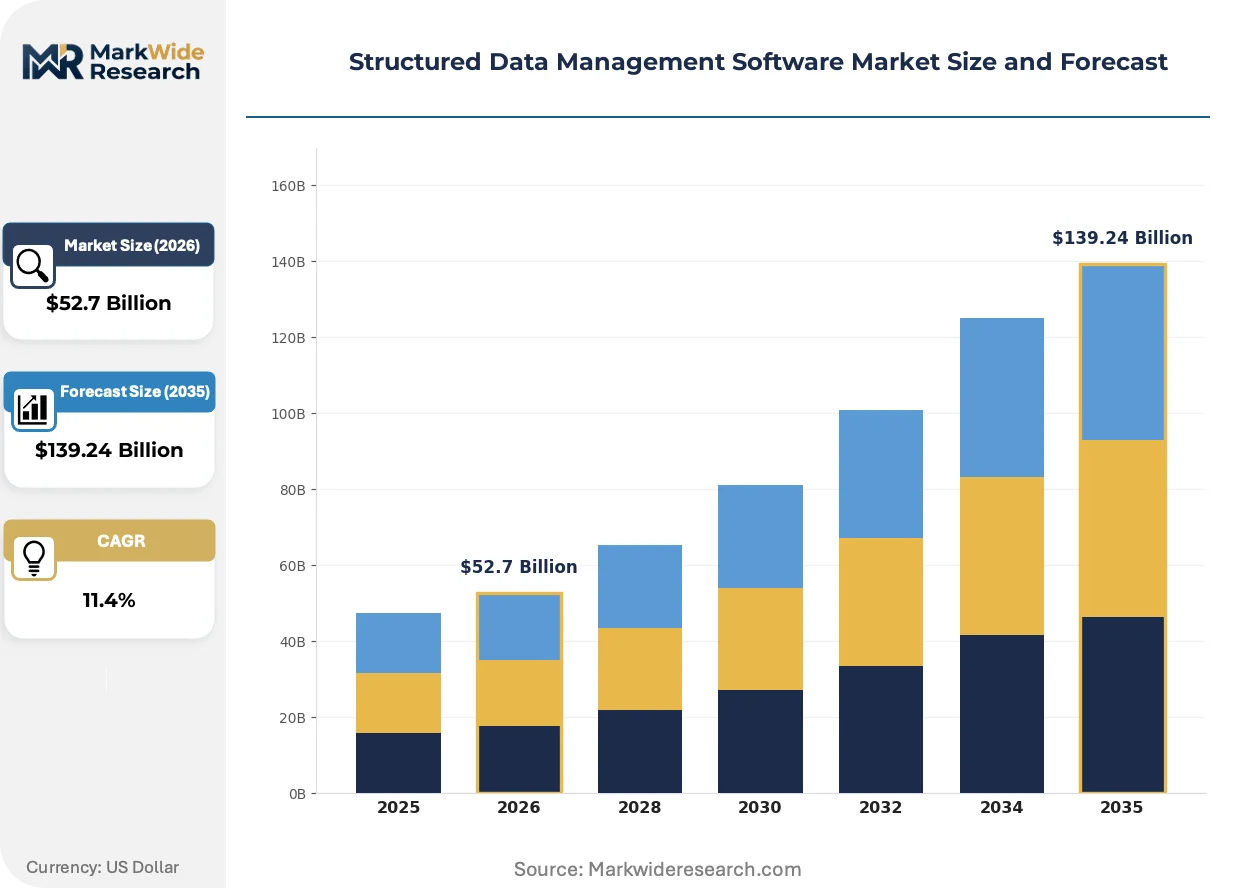
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Healthcare, BFSI, Retail, Education Solution: Data Integration, Data Governance, Data Quality, Metadata Management Application: Data Warehousing, Business Intelligence, Analytics, Machine Learning |
| Companies Covered | Semarchy, Profisee, Informatica, Syniti, Precisely, IBM, Ataccama, TIBCO EBX, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structured Data Management Software Market Evolving Landscape
Active metadata systems are displacing static repositories as the operational brain of enterprise data stacks, embedding policy enforcement directly into query engines and transformation pipelines rather than treating governance as a post-hoc audit layer.
AI-augmented data quality automation is digitizing anomaly detection and remediation workflows that previously required manual SQL profiling. Pharmaceutical manufacturers in Basel and Boston are deploying these systems to satisfy FDA data integrity standards, compressing validation cycles from quarterly to continuous monitoring. The structural consequence is a shift from human-in-the-loop quality assurance toward autonomous data reliability engineering.
The EU AI Act's risk-based classification system is forcing European enterprises to reconstruct training data provenance for high-risk AI applications. Financial institutions in Frankfurt and Paris are prioritizing lineage tools that map structured data flows into model development environments, with compliance officers now embedded in procurement decisions previously owned by IT. This regulatory pressure is accelerating consolidation around platforms that unify governance, quality, and observability functions.
Consumption-based pricing for data governance platforms is displacing perpetual license models among mid-market buyers. US healthcare systems and regional banks are adopting seat-flexible subscriptions that scale with active data asset counts rather than total employee bases. This shift is most visible in Texas and Florida, where private equity-backed provider networks prioritize opex predictability over capital efficiency.
Structured Data Management Software Market Segmentation
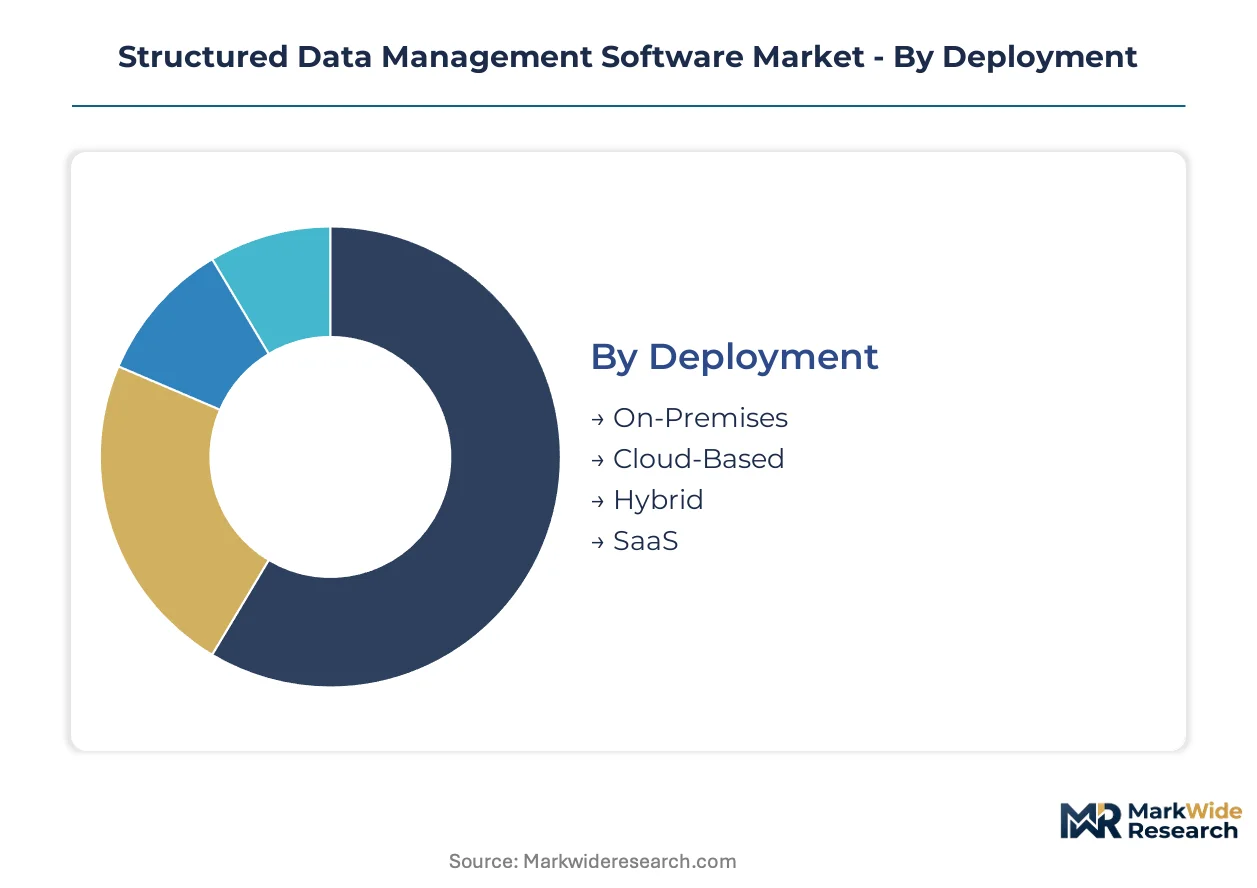
Deployment architecture determines capital structure and compliance posture for structured data management procurement. End-user verticals impose divergent schema requirements and audit frequencies. Solution specialization and application context further differentiate vendor positioning across enterprise data estates.
Deployment:
Cost tier separates procurement approaches from perpetual capital commitments through consumption-scaled subscriptions.
- Cloud-Based:Multi-tenant architectures eliminate data center overhead while embedding automated scaling and disaster recovery. US healthcare systems in Texas and Florida prioritize opex predictability through seat-flexible subscriptions tied to active data asset counts rather than total employee bases.
- SaaS:Browser-delivered governance layers accelerate time-to-value for mid-market buyers lacking dedicated infrastructure teams. India's PLI scheme for data centers is pulling governance software procurement into Mumbai and Hyderabad hyperscale clusters as domestic structured data volumes expand.
- On-Premises:Perpetual licenses persist in German automotive and US defense contexts where air-gapped environments satisfy national security requirements.
- Hybrid:Dual-deployment architectures sustain enterprise relationships across environments where regulatory data residency conflicts with cloud cost advantages.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
End User:
Application context drives schema complexity, lineage depth requirements, and audit frequency across vertical procurement.
- BFSI:Transactional data stores demand real-time consistency enforcement and fraud-pattern detection across millions of daily records. Frankfurt and Paris financial institutions prioritize lineage tools mapping structured flows into model development environments to satisfy EU AI Act risk-classification mandates.
- Healthcare:Patient records require HIPAA-compliant integrity standards with immutable audit trails for clinical decision support. FDA data integrity standards in Basel and Boston pharmaceutical manufacturing are compressing validation cycles from quarterly reviews toward continuous monitoring.
- Retail:Omnichannel transaction streams necessitate schema registry enforcement across Apache Kafka and Flink pipelines.
- Education:Research data management platforms face lighter governance maturity requirements but escalating funder-mandated provenance documentation.
BFSI captures premium pricing through compliance-driven procurement. Healthcare is climbing the fastest as FDA and HIPAA enforcement tightens.
Solution:
Functional maturity determines margin structure from commodity integration through premium governance automation.
- Data Governance:Policy engines and lineage repositories enforce regulatory provenance across distributed data estates. EU AI Act and GDPR mandates are expanding demand for automated bias-auditing and cross-border residency management tools among European operations.
- Data Quality:Profiling pipelines and anomaly detection digitize remediation workflows previously requiring manual SQL intervention. AI-augmented automation is shifting pharmaceutical manufacturers from human-in-the-loop assurance toward autonomous reliability engineering.
- Data Integration:ETL and ELT orchestration layers consolidate fragmented analytics estates through standardized transformation pipelines.
- Metadata Management:Active metadata systems displace static repositories by embedding policy enforcement directly into query engines rather than treating governance as post-hoc audit layers.
Data Integration holds installed capacity. Data Governance is rotating up the share rankings.
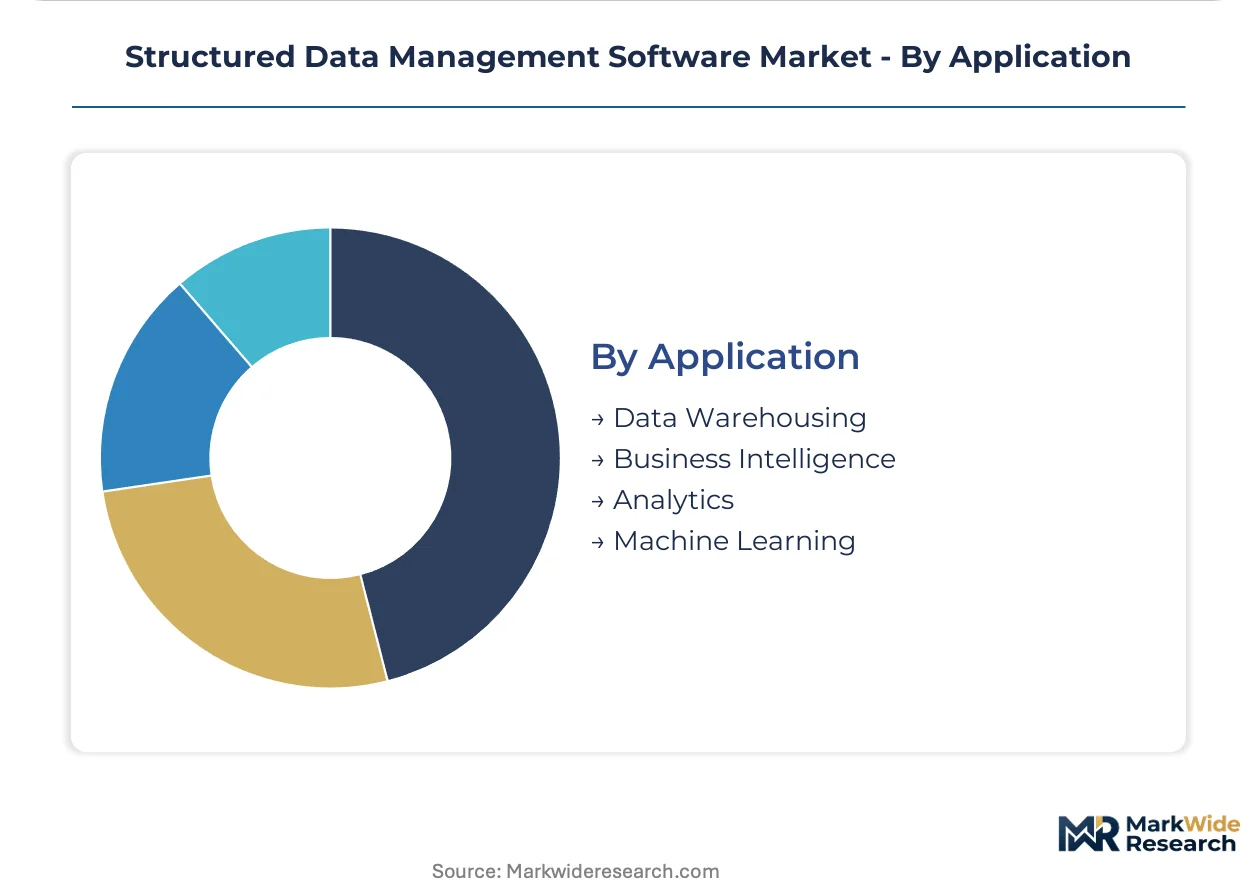
Application:
Customer type stratifies from operational reporting through predictive model development environments.
- Machine Learning:Training data provenance and feature store governance require lineage tracking into model development pipelines. SEC climate disclosure rules are pushing US-listed enterprises toward auditable emissions data pipelines with certified framework demand.
- Business Intelligence:Self-service analytics platforms consolidate fragmented reporting estates through governed semantic layers and certified metric definitions.
- Data Warehousing:Centralized analytical stores enforce schema consistency across historical and real-time ingestion patterns.
- Analytics:Operational and exploratory workloads demand interoperable, auditable datasets with automated profiling for schema drift detection.
Data Warehousing holds installed capacity. Machine Learning is gaining share fastest as model governance matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters in three distinct geographies where regulatory pressure and enterprise modernization intersect. Germany, the United States, and India generate disproportionate procurement velocity as cloud migration mandates harden compliance deadlines.
United States
SEC climate disclosure rules and HIPAA data integrity standards are pushing BFSI and healthcare buyers toward certified quality management frameworks. Texas and Florida healthcare systems prioritize opex predictability through seat-flexible subscriptions tied to active data asset counts. Private equity-backed provider networks in these states are accelerating SaaS transitions.
Germany
Automotive and industrial equipment producers in Baden-Württemberg and Bavaria lag financial services in governance maturity, representing untapped seats for quality automation platforms. The EU AI Act's risk-based classification system forces Frankfurt financial institutions to reconstruct training data provenance for high-risk applications. Stuttgart and Munich manufacturing clusters face compressed certification timelines.
India
Domestic hyperscale construction under the PLI scheme for data centers is accelerating structured data volume growth. Mumbai and Hyderabad clusters are pulling governance software procurement as enterprises modernize legacy architectures. SEBI and RBI guidelines on data localization are reshaping deployment preferences toward hybrid architectures.
United Kingdom
London financial services firms must deploy automated lineage tracking to satisfy EU AI Act bias-auditing obligations despite post-Brexit regulatory divergence. The Information Commissioner's Office enforcement of GDPR provenance requirements is expanding demand for metadata management platforms. Edinburgh and Manchester enterprise hubs are consolidating fragmented analytics estates.
France
Paris-based institutions prioritize lineage tools mapping structured data flows into model development environments, with compliance officers now embedded in procurement decisions. CNIL guidance on automated decision-making is tightening schema consistency requirements. Lyon pharmaceutical manufacturers are deploying AI-augmented quality systems to satisfy EMA data integrity standards.
Structured Data Management Software Market Competitive Landscape
Database-anchored incumbents and cloud-native specialists split the market between deep integration and deployment flexibility. Consolidation pressure is intensifying as platform bundling from hyperscalers compresses standalone vendor margins. Two archetypes dominate: legacy infrastructure extenders leveraging installed database relationships, and AI-augmented quality automation specialists competing on autonomous remediation. M&A activity targets metadata management capabilities, while strategic partnerships with cloud providers secure distribution access.
Among database-anchored incumbents, Oracle and IBM occupy positions leveraging deep enterprise integration, while Informatica exemplifies the hybrid-deployment extender archetype sustaining relationships across on-premises and cloud environments. Ataccama represents the AI-augmented specialist tier competing aggressively on autonomous data quality automation. These three anchors illustrate the strategic divergence between infrastructure leverage and algorithmic differentiation reshaping procurement decisions.
| Leading Market Players |
|---|
| Semarchy |
| Profisee |
| Informatica |
| Syniti |
| Precisely |
| IBM |
| Ataccama |
| TIBCO EBX |
| Oracle |
| Others |
Value Network & Pricing Analysis
Trans-Atlantic fiber corridors connecting Frankfurt cloud regions to US East Coast data centers impose bandwidth cost premiums that compress margins for European SaaS deployments while enabling tiered pricing stratification between latency-sensitive financial services buyers and cost-optimized mid-market adopters.
Pricing Analysis
GDPR and EU AI Act compliance mandates dictate the pricing tier structure across deployment architectures, with certified governance modules commanding premium positioning against standard quality automation seats. Three-tier pricing structure across enterprise, professional, and essential levels reflects certification depth, active metadata volume, and cross-border residency management complexity. Cost compression in essential tiers is intensifying because hyperscaler bundled offerings commoditize baseline integration functions. Mid-market healthcare systems in Texas and Florida exhibit highest price sensitivity through seat-flexible subscription demands, while Frankfurt BFSI institutions accept premium positioning for bias-auditing lineage tools.
Supply Chain Analysis
Systems integrators and boutique consultancies in India, Poland, and the Czech Republic hold implementation capacity for metadata migration and legacy connector development. Software licensing draws from US West Coast engineering clusters, Irish European headquarters structures, and Bangalore development centers. Single-source vulnerability concentrates in Apache Kafka schema registry dependencies and cloud-native Kubernetes orchestration layers. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and regional systems integrators with vertical specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement of structured data management platforms is bottlenecked by acute scarcity of metadata architects and certified data stewards capable of deploying lineage tracking across hybrid cloud estates.
For Market Incumbents: Build switching-cost moats through deep ERP and database integration that embed governance policies into operational transaction flows. Incumbents should anchor renewal rates by expanding professional services footprints in Germany and India where talent scarcity extends implementation timelines. Hyperscaler bundling of competing quality tools threatens standalone pricing power, requiring incumbents to differentiate through vertical-specific compliance accelerators for FDA and EMA regulated environments. For New Entrants and Emerging Players: German automotive manufacturing clusters in Baden-Württemberg and Bavaria present underpenetrated governance maturity gaps against saturated financial services verticals. New entrants should target tier-two industrial equipment producers with lightweight SaaS quality automation that bypasses heavy IT involvement. A channel-first go-to-market through regional manufacturing technology distributors accelerates seat acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-augmented quality automation specialists with autonomous remediation capabilities over legacy integration incumbents. Long-term viability hinges on platform consolidation around unified governance-quality-observability stacks rather than point solutions. Acquisition target archetype: metadata management platforms with active policy embedding technology. The signal to watch is hyperscaler marketplace revenue share shifts indicating bundling pressure intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying governance, quality, and observability functions captures EU AI Act procurement consolidation. |
| Acquisition of Specialist Firm | Metadata management capabilities fill active policy embedding gaps in legacy vendor portfolios. |
| Strategic Partnership | Hyperscaler marketplace distribution secures access to AWS, Azure, and GCP bundled procurement flows. |
| Geographic Expansion | Mumbai and Hyderabad hyperscale clusters under India's PLI scheme accelerate structured data volume capture. |
| Product Launch | Sustainability modules addressing SEC climate disclosure rules create certified framework differentiation. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, IT procurement officers, data platform engineers, and channel integration specialists. Primary fieldwork captured deployment architecture preferences, compliance-driven procurement timelines, and vendor evaluation criteria across BFSI, healthcare, and manufacturing verticals. Secondary validation drew from customs records of software licensing flows, Gartner and Forrester vendor assessments, and trade data on data center construction. Bottom-up sizing of seat counts and top-down revenue triangulation anchored market estimates.
Forecast assumptions held cloud migration velocity and regulatory enforcement timelines fixed while varying enterprise modernization budget cycles and hyperscaler bundling intensity across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern. CAGRs were derived from slope analysis of seat expansion curves and pricing trajectory assumptions. Industry-specific inputs encompassed EU AI Act implementation phase deadlines and FDA data integrity standard revision schedules.
Practitioners should monitor hyperscaler governance tool bundling announcements and EU AI Act supervisory authority enforcement actions for early signals of competitive intensity shifts. Forecasts reflect assumptions on regulatory timeline adherence and cloud cost optimization priorities that may revise with macroeconomic stress or geopolitical fragmentation. Quarterly review of vendor marketplace revenue disclosures and data center construction permit filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Web Framework Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Recruitment Software Market
Software & Services
IT Services Market
Software & Services
Storyboarding Software Market
Software & Services
PLM Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Global AR Game Engine Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
HR Tech Market
Software & Services
Bankruptcy Software Market
Software & Services
Course Authoring Software Market
Software & Services
Staffing Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Saas Based HRM Market