
 Saas Based HRM Market | 2026-2036
Saas Based HRM Market Size, Share, and Industry Trends Forecast 2026-2036
Saas Based HRM Market Outlook
Mid-market employer consolidation is expanding the addressable base for unified platforms. Oracle Corporation leverages its database heritage to anchor enterprise accounts with embedded analytics. SAP SE competes through deep ERP integration that sustains renewal rates among European manufacturers. Workday Inc. specializes in financial-HRM convergence for healthcare and education buyers.
SaaS-based human resource management delivers workforce administration through multi-tenant cloud architectures with API-first connectivity to payroll, benefits, and time-tracking systems. The primary commercial purpose centers on replacing fragmented on-premises installations with configurable, mobile-accessible employee lifecycle management. Public cloud deployment leads volume due to lower capital barriers for SMEs transitioning from spreadsheet-based processes. Subscription-based pricing captures the dominant margin pool by locking in predictable recurring revenue, while pay-per-use models attract seasonal employers with variable headcount. Feature demand concentrates in payroll processing and employee self-service portals where compliance automation reduces administrative overhead.
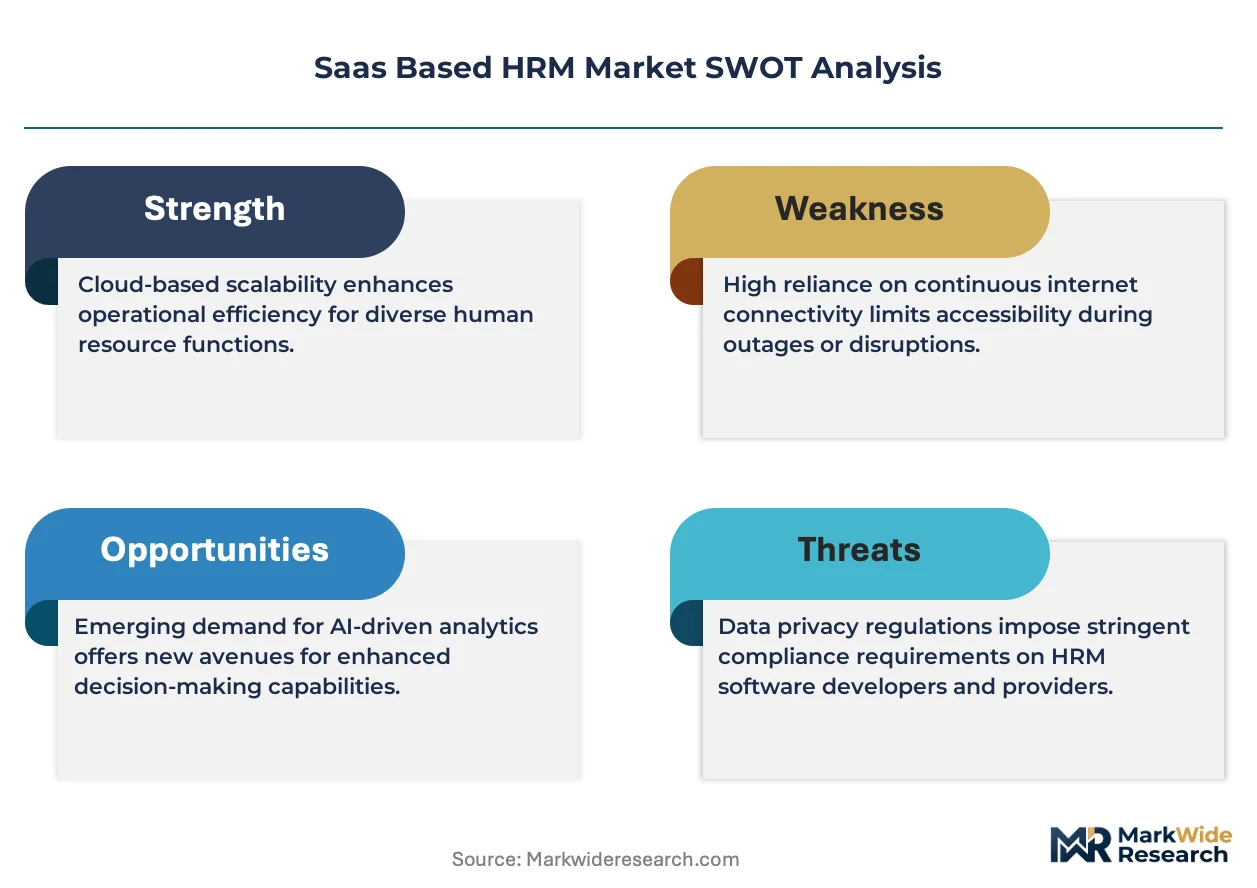
GDPR and the EU AI Act constrain automated candidate screening algorithms, forcing vendors to document decision logic and human oversight protocols. The US Department of Labor and EEOC scrutiny of AI-driven hiring outcomes shapes product roadmaps toward explainable recommendation engines. Stakeholders must monitor evolving state-level biometric and wage-transparency laws that fragment compliance requirements across multi-jurisdictional deployments.
Market Dynamics
Healthcare systems across North America are replacing legacy on-premises systems with cloud-native workforce platforms, compressing procurement cycles and forcing incumbent vendors to re-architect around API-first connectivity.
Growth Catalysts
- EU AI Act:The regulation's documentation requirements for automated screening tools are accelerating vendor investment in explainable AI modules, creating competitive differentiation for compliant platforms.
- Mid-market manufacturers in Germany:These employers are consolidating fragmented HR vendor relationships around unified payroll-talent suites, expanding the addressable base for integrated platform providers.
- Mobile-first employee self-service:Frontline workers in retail and logistics now expect consumer-grade mobile interfaces, pulling platform roadmaps toward native app development and real-time notification architectures.
Market Restraints
- GDPR Article 22 constraints:The prohibition on solely automated decisions with legal effects creates algorithmic auditing burdens that inflate implementation costs for European deployments.
- Public cloud concentration risk:Multi-tenant architectures create single points of failure where AWS, Azure, or Google Cloud outages cascade across thousands of employer instances simultaneously.
- Biometric data fragmentation:US state-level laws in Illinois, Texas, and Washington create conflicting consent and retention requirements that complicate time-clock and access-control feature standardization.
Strategic Opportunities
- Seasonal employer pay-per-use models:Agricultural and hospitality sectors with variable headcount represent underserved demand for consumption-based pricing rather than fixed per-employee subscriptions.
- API marketplace ecosystems:Open banking-style connectivity between HRM platforms and niche benefits administrators, learning management systems, and productivity tools creates platform stickiness through network effects.
- CSRD workforce disclosure mandates:The EU Corporate Sustainability Reporting Directive's human capital metrics requirements position integrated analytics suites as compliance infrastructure for large employers.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle on-premises installations require costly middleware development to synchronize data with cloud-native HRM platforms, extending implementation timelines.
- AI/ML talent scarcity:Explainable recommendation engine development demands specialized machine learning engineers and labor economists that vendor engineering organizations struggle to recruit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saas Based HRM Market |
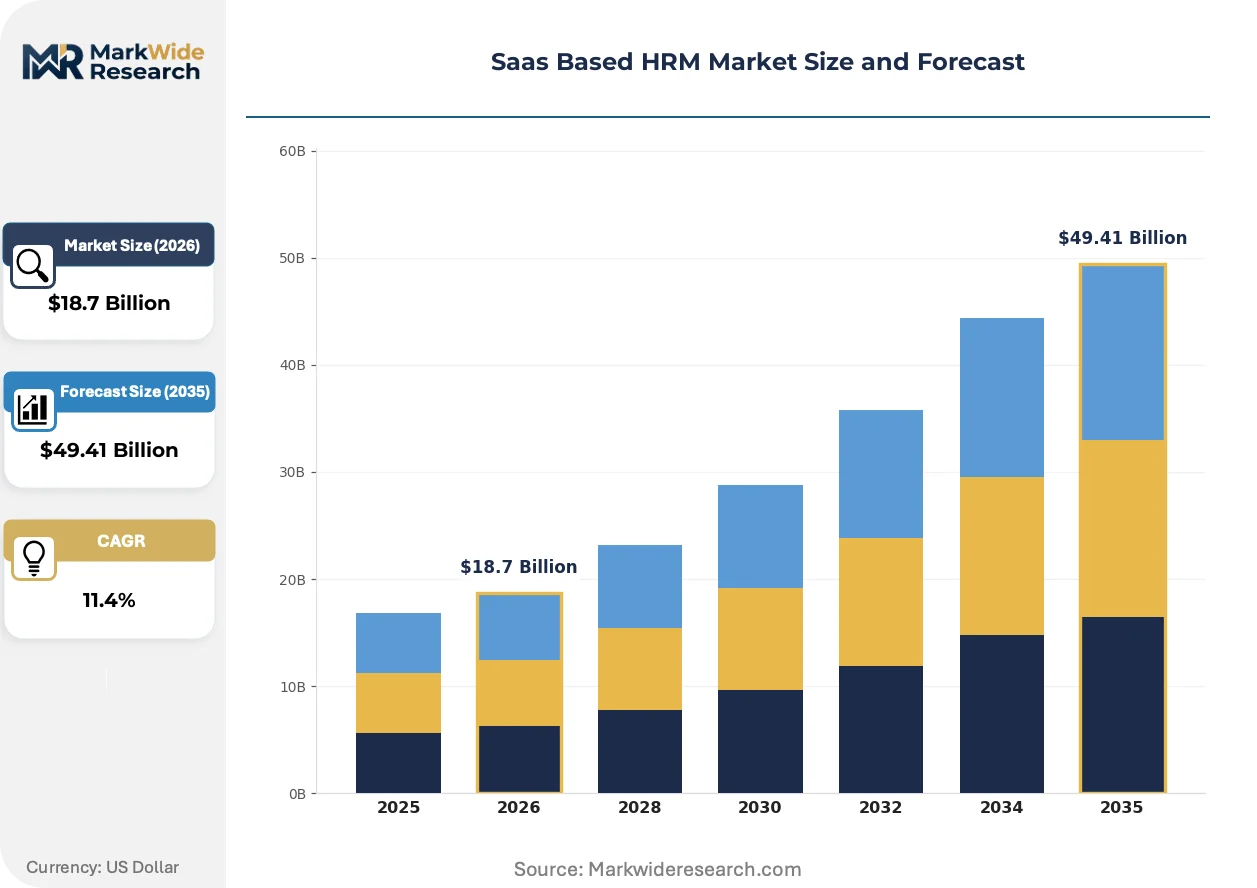
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Startups, Consulting Firms Feature: Recruitment Management, Performance Tracking, Payroll Processing, Employee Self-Service Pricing Model: Subscription-Based, One-Time License, Pay-Per-Use, Freemium |
| Companies Covered | Workday Inc., Oracle Corporation, SAP SE, UKG Inc., Ceridian HCM Holding Inc., Automatic Data Processing, BambooHR, Rippling, Paycom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saas Based HRM Market Strategic Shifts
Embedded analytics and machine learning inference are migrating from bolt-on dashboards into core transaction processing, reshaping how workforce data generates operational intelligence.
Natural language processing for candidate screening and sentiment analysis is electrifying recruitment workflows by automating resume parsing and interview transcription. Large healthcare systems and university systems are deploying these tools at enterprise scale, compressing time-to-fill metrics while forcing vendors to document decision logic for EEOC scrutiny. The technology is electrifying competitive positioning around compliance automation rather than pure matching accuracy.
The EU AI Act's risk-based classification system for employment-related algorithms is mandating human-in-the-loop protocols and bias testing documentation. Vendors must now maintain technical files and conformity assessments for automated screening tools, inflating product development overhead. German and French mid-market employers are delaying procurement decisions until vendor compliance certifications mature, creating a temporary demand pause in continental Europe.
Consolidation of point solutions into unified suites is displacing best-of-breed procurement strategies among employers with 500-5,000 employees. These buyers are prioritizing single-vendor accountability over specialized functionality, compressing margins for standalone time-tracking or benefits administration vendors. The shift is most visible in US manufacturing and distribution verticals where IT headcount constraints favor simplified vendor management.
Saas Based HRM Market Segmentation
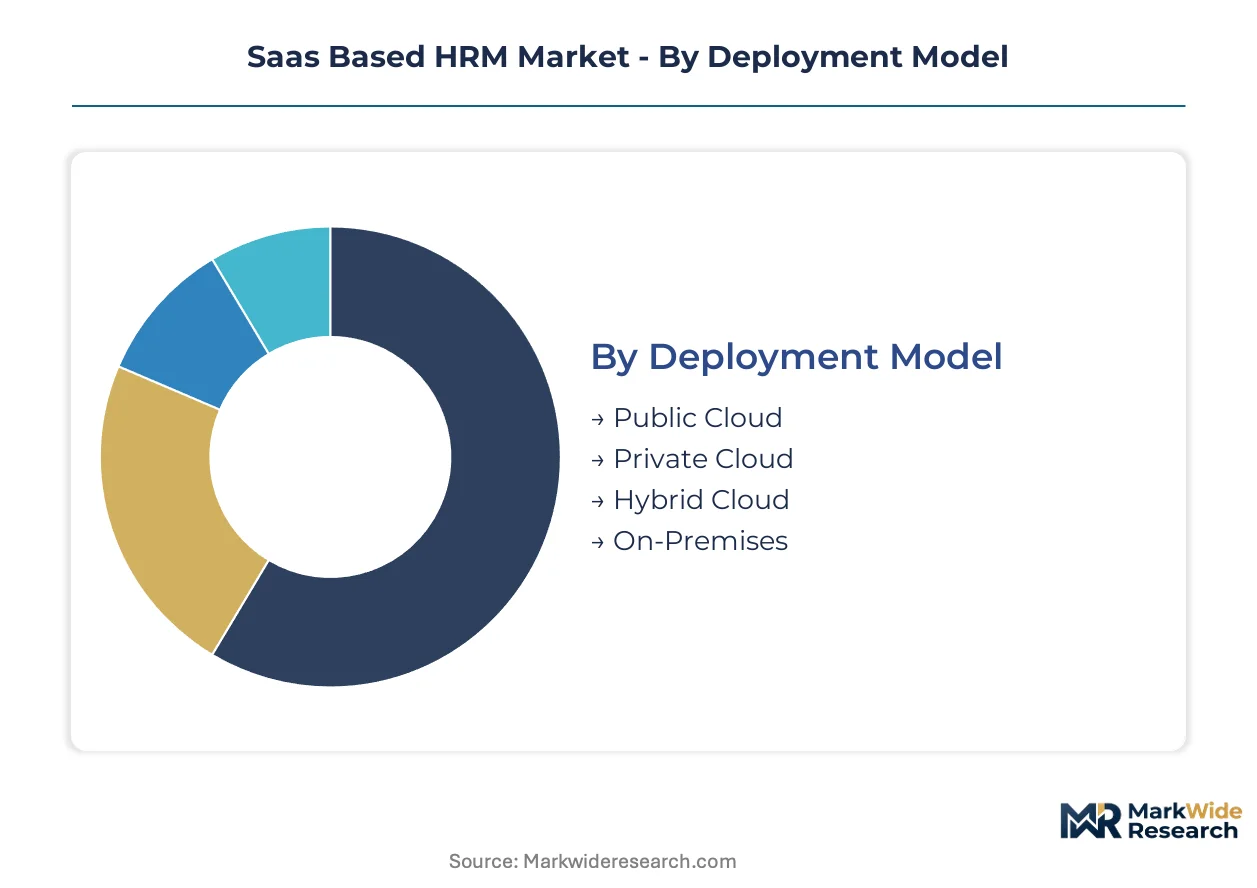
SaaS HRM platforms fragment across deployment architectures, buyer scale, functional modules, and commercial terms. Each segmentation axis reveals distinct procurement patterns and margin structures that reshape vendor go-to-market priorities.
Deployment Model:
Multi-tenant architectures define the technology spectrum, with isolation levels and infrastructure control separating the four deployment modes.
- Public Cloud:Shared infrastructure with automatic scaling and zero capital expenditure. Demand concentrates among SMEs in the United States transitioning from spreadsheet-based workforce management, driven by subscription affordability and rapid implementation timelines.
- Private Cloud:Dedicated single-tenant environments with customizable security postures. German automotive suppliers and French pharmaceutical manufacturers favor this model to satisfy works council data residency requirements while retaining cloud agility.
- Hybrid Cloud:Split architectures keeping sensitive payroll data on-premises while routing self-service functions through public endpoints. Canadian provincial healthcare authorities deploy hybrid configurations to reconcile HIPAA-equivalent privacy mandates with mobile accessibility demands.
- On-Premises:Legacy installations with full hardware ownership and manual upgrade cycles. Japanese industrial conglomerates maintain on-premises systems due to METI cybersecurity guidelines and internal IT labor retention.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Public Cloud.
End User:
Organizational scale dictates feature complexity, integration requirements, and sales cycle duration across buyer categories.
- SMEs:Employers with 50-500 employees seeking out-of-box functionality with minimal IT overhead. United Kingdom professional services firms represent accelerating demand, pulled by auto-enrollment pension compliance and real-time reporting to HMRC.
- Large Enterprises:Complex multi-entity organizations requiring global payroll consolidation and advanced analytics. Australian mining operators and Brazilian energy majors drive expansion here, prioritizing CSRD-aligned workforce disclosure capabilities.
- Startups:High-growth companies with volatile headcount needing rapid provisioning and de-provisioning. Singapore fintech ventures and Netherlands scale-ups favor API-first platforms that sync with cap table management tools.
- Consulting Firms:Project-based employers with rotating contractor populations and time-billing requirements. Indian IT services exporters and Polish business process outsourcing providers dominate procurement, seeking granular cost allocation by client engagement.
Revenue concentration weights toward Large Enterprises. Volume expansion is climbing the fastest among Startups.
Feature:
Functional modules align with workforce lifecycle stages, from attraction through separation, each carrying distinct compliance burdens.
- Recruitment Management:Candidate sourcing, applicant tracking, and interview scheduling with embedded AI screening. United States healthcare systems are deploying these tools at enterprise scale, compressing time-to-fill metrics while forcing vendors to document decision logic for EEOC scrutiny.
- Performance Tracking:Goal-setting frameworks, continuous feedback mechanisms, and calibration analytics. South Korean chaebols and Swiss banking groups drive demand, integrating performance data with succession planning for leadership pipelines.
- Payroll Processing:Gross-to-net calculation, tax withholding, and regulatory filing across jurisdictions. Mexican manufacturers expanding nearshoring operations prioritize this module to navigate SAT electronic invoicing integration and social security contributions.
- Employee Self-Service:Mobile-accessible profile management, benefits enrollment, and time-off requests. Italian retail chains and Spanish hospitality operators deploy native apps for frontline workers with limited desktop access.
Procurement frequency peaks with Payroll Processing. Innovation investment is gaining share fastest in Recruitment Management.
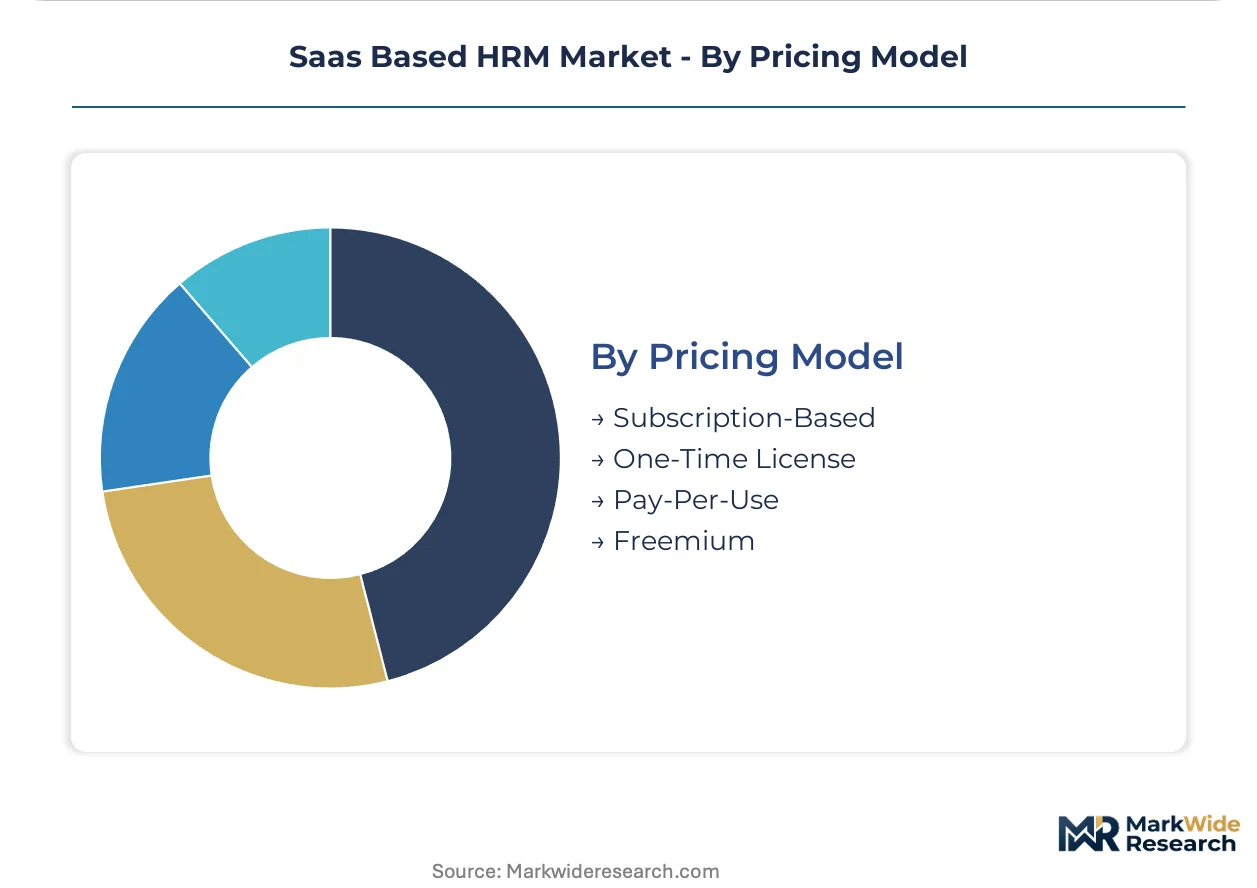
Pricing Model:
Commercial structures segment buyers by predictability preference, cash flow profile, and usage volatility.
- Subscription-Based:Fixed per-employee-per-month fees with tiered feature access. This structure captures the dominant margin pool through predictable recurring revenue and annual commitment discounts.
- One-Time License:Perpetual software ownership with separate maintenance contracts. Turkish government agencies and Indonesian state-owned enterprises favor this model to satisfy public procurement regulations requiring asset capitalization.
- Pay-Per-Use:Consumption-based billing tied to active employees or processed transactions. Agricultural cooperatives in Argentina and seasonal tourism operators in Greece represent underserved demand for variable cost alignment with headcount fluctuations.
- Freemium:Core functionality at no cost with premium feature upsells. Early-stage ventures in Israel and venture-backed startups in Vietnam adopt freemium tiers for initial HR infrastructure before scaling to paid plans.
Revenue stability sits with Subscription-Based. Commercial experimentation is expanding most quickly in Pay-Per-Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems in the United States and mid-market manufacturers in Germany concentrate procurement volume for cloud-native workforce platforms, while regulatory divergence across jurisdictions fragments vendor compliance roadmaps.
United States
Large healthcare networks and university systems drive enterprise-scale deployments of AI-enabled recruitment tools. EEOC scrutiny of automated hiring outcomes forces vendors to document decision logic and maintain human oversight protocols. The Boston-Cambridge corridor anchors healthcare HRM adoption, with Massachusetts General Brigham and Partners HealthCare consolidating fragmented systems onto unified cloud platforms.
Germany
Mid-market automotive suppliers and pharmaceutical manufacturers consolidate vendor relationships around integrated payroll-talent suites. The EU AI Act mandates technical files and conformity assessments for automated screening algorithms, inflating implementation timelines. Stuttgart and Munich manufacturing clusters delay procurement until vendor compliance certifications mature, creating temporary demand concentration in Bavaria and Baden-Württemberg.
United Kingdom
Professional services firms with 50-500 employees accelerate migration from spreadsheet-based processes to public cloud HRM. Auto-enrollment pension compliance and real-time HMRC reporting requirements pull demand toward subscription-based platforms. London's financial services corridor and Manchester's professional services cluster represent the fastest-growing sub-regional concentrations.
Canada
Provincial healthcare authorities deploy hybrid cloud configurations to reconcile HIPAA-equivalent privacy mandates with mobile accessibility demands. Ontario and British Columbia health systems lead procurement, splitting sensitive payroll data on-premises while routing employee self-service through public endpoints. Federal procurement guidelines favor vendors with domestic data residency certifications.
Australia
Mining operators and energy majors prioritize CSRD-aligned workforce disclosure capabilities as integrated analytics infrastructure. New South Wales and Western Australia resource extraction hubs drive large-enterprise segment growth, consolidating multi-entity payroll across remote operations. The country's national privacy regulator enforces strict biometric data consent requirements for time-clock deployments.
Saas Based HRM Market Competitive Environment
United States vendors anchor the enterprise tier with database heritage and financial system convergence; European specialists hold manufacturing-centric positions through deep ERP integration. The vendor base stratifies across three tiers: cloud-native challengers with API-first architectures, legacy ERP extenders with renewal-dependent installed bases, and vertical specialists serving seasonal or project-based employers. Strategic moves concentrate on M&A consolidation of point solutions and geographic expansion through compliance localization.
Within the legacy ERP extender tier, Oracle Corporation and SAP SE occupy positions defined by database and manufacturing system heritage respectively. Workday Inc. anchors the cloud-native tier with financial-HRM convergence specialization. These three entities exemplify how vendor origin and core technology stack determine competitive positioning across buyer segments.
| Leading Market Players |
|---|
| Workday Inc. |
| Oracle Corporation |
| SAP SE |
| UKG Inc. |
| Ceridian HCM Holding Inc. |
| Automatic Data Processing |
| BambooHR |
| Rippling |
| Paycom |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure spot pricing indexes cascade through SaaS HRM vendor cost structures, compressing margins for multi-tenant providers while amplifying pricing power for single-tenant private cloud specialists serving German automotive suppliers and French pharmaceutical manufacturers.
Pricing Analysis
Volume concentrates in subscription-based per-employee-per-month tiers while margin pools accrue to consumption-based pay-per-use models for seasonal employers. Price differentiation hinges on compliance certification level—EU AI Act conformity assessments command premiums—and integration depth with legacy ERP systems. Cost compression in public cloud tiers is intensifying because hyperscaler concentration creates vendor lock-in leverage. SMEs exhibit highest price sensitivity, prioritizing rapid implementation over advanced analytics; large enterprises tolerate premium pricing for global payroll consolidation and CSRD-aligned workforce disclosure capabilities.
Supply Chain Analysis
Freight costs for edge computing hardware and biometric time-clock devices exert downstream pressure on hybrid deployment pricing, particularly for Canadian provincial healthcare authorities reconciling data residency with mobile accessibility. Supply concentrates in the United States for cloud-native platform development, India for implementation services and API integration labor, and Ireland for EU data hosting. Component dependencies span AWS/Azure/Google Cloud compute instances, identity verification APIs, and payroll tax calculation engines. Single-source vulnerability concentrates in hyperscaler outages that cascade across thousands of employer instances simultaneously. Distribution runs through direct enterprise sales teams for large accounts and self-service digital channels for SME acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native workforce platforms are displacing fragmented on-premises installations across healthcare and manufacturing verticals, with API-first architectures replacing legacy ERP extenders as the dominant technology stack.
For Market Incumbents: Extend embedded analytics capabilities into core transaction processing to deepen platform stickiness against best-of-breed point solutions. Acquire compliance automation specialists to satisfy EU AI Act technical documentation requirements before German mid-market procurement decisions accelerate. Prioritize backward integration into payroll tax calculation engines to reduce third-party API dependency and defend margin position.
For New Entrants and Emerging Players: API marketplace ecosystems offer the lowest customer acquisition cost route into underserved seasonal employer segments in agricultural and hospitality verticals. Target pay-per-use pricing models for Argentine agricultural cooperatives and Greek tourism operators where variable headcount alignment creates immediate value demonstration. Pursue vertical specialization in CSRD workforce disclosure analytics for Australian mining operators and Brazilian energy majors before integrated suites absorb this functionality.
For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first challengers with explainable AI modules in the United States healthcare corridor, where EEOC scrutiny is forcing vendor consolidation around compliant platforms. Long-term viability rests on regulatory adaptation speed rather than matching engine accuracy alone. Monitor EU AI Act conformity assessment completion rates as the inflection signal for continental European demand reactivation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented payroll and talent suites for German mid-market manufacturers. |
| Acquisition of Specialist Firm | Absorbs explainable AI compliance capabilities ahead of EU AI Act enforcement. |
| Geographic Expansion | Localizes data residency for Canadian provincial healthcare hybrid cloud mandates. |
| Product Launch | Introduces consumption-based pricing for seasonal agricultural and hospitality employers. |
| Strategic Partnership | Connects HRM platforms to open banking-style benefits administrator ecosystems. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with CTOs, HR technology procurement officers, platform engineers, and integration specialists at healthcare systems and manufacturing enterprises. Secondary validation drew from SEC 10-K disclosures, EU AI Act implementation guidance, and hyperscaler infrastructure capex reports. Bottom-up modeling of deployment mode and organization size segments triangulated against top-down macroeconomic indicators.
Granularity-level modeling distinguished public cloud, private cloud, hybrid, and on-premises architectures across SME, large enterprise, startup, and consulting firm buyer categories. Functional module segmentation captured recruitment management, performance tracking, payroll processing, and employee self-service adoption patterns. CAGRs were derived from regression analysis of historical subscription revenue and projected procurement cycle compression. Industry-specific inputs included EEOC enforcement patterns, works council negotiation timelines, and biometric consent law proliferation.
Inputs from healthcare system procurement databases and German automotive supplier ERP migration records were available through the study window; gaps in EU AI Act third-party audit completion rates introduce uncertainty bands around continental European demand timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hyperscaler pricing trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Lease Accounting Software Market
Software & Services
Labeling Software Market
Software & Services
Automotive Operating Systems Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Enterprise Search Software Market
Software & Services
Attendance Tracking Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
G Suite Technology Services Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Global Virtual Desktop Market
Software & Services
Spend Analysis Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Saas-Based SCM Market
Software & Services
Sales Training Software Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Supply Chain Management (SCM) Software Market