
 Global AR Game Engine Software Market | 2026-2036
Global AR Game Engine Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global AR Game Engine Software Market Foresight
Platform licensing revenue is tilting from perpetual sales toward subscription and revenue-share models as cloud rendering pipelines mature. Epic Games leverages its Unreal Engine ecosystem to anchor high-fidelity industrial visualization contracts. Unity Technologies sustains broad platform reach across mobile AR and wearable form factors. Qualcomm Inc. competes through Snapdragon Spaces, an SDK layer that extends silicon-level optimization into engine middleware.
AR game engine software comprises development frameworks that integrate real-time rendering, spatial mapping, and sensor fusion algorithms to synchronize digital content with physical environments, typically operating at 60 frames per second with sub-50-millisecond motion-to-photon latency to prevent user disorientation. The primary commercial purpose is reducing the technical barrier for creators building location-based entertainment, workforce training simulations, and retail try-on experiences. SLAM and visual-inertial odometry within the Core Technology dimension dominate R&D allocation because these modalities determine tracking stability under variable lighting. The Application Type category shows Entertainment retaining the largest installed base while Industrial Training generates the highest per-seat pricing. Platform Compatibility spans six operating systems, though iOS and Android together absorb the majority of mobile-first development hours.
The EU AI Act and GDPR constrain how engines process facial geometry and gaze vectors, forcing vendors to embed on-device inference and explicit consent flows. The FDA in the United States evaluates AR training modules for surgical credentialing, creating a compliance threshold that segments professional-grade engines from consumer tools. China's NMPA and MIIT coordinate personal information protection standards for camera-access applications, affecting localization requirements for foreign engine providers. Stakeholders must monitor which regulatory frameworks achieve cross-border recognition, as divergence in biometric data rules will fragment engine certification paths and reshape geographic deployment priorities.
Market Dynamics
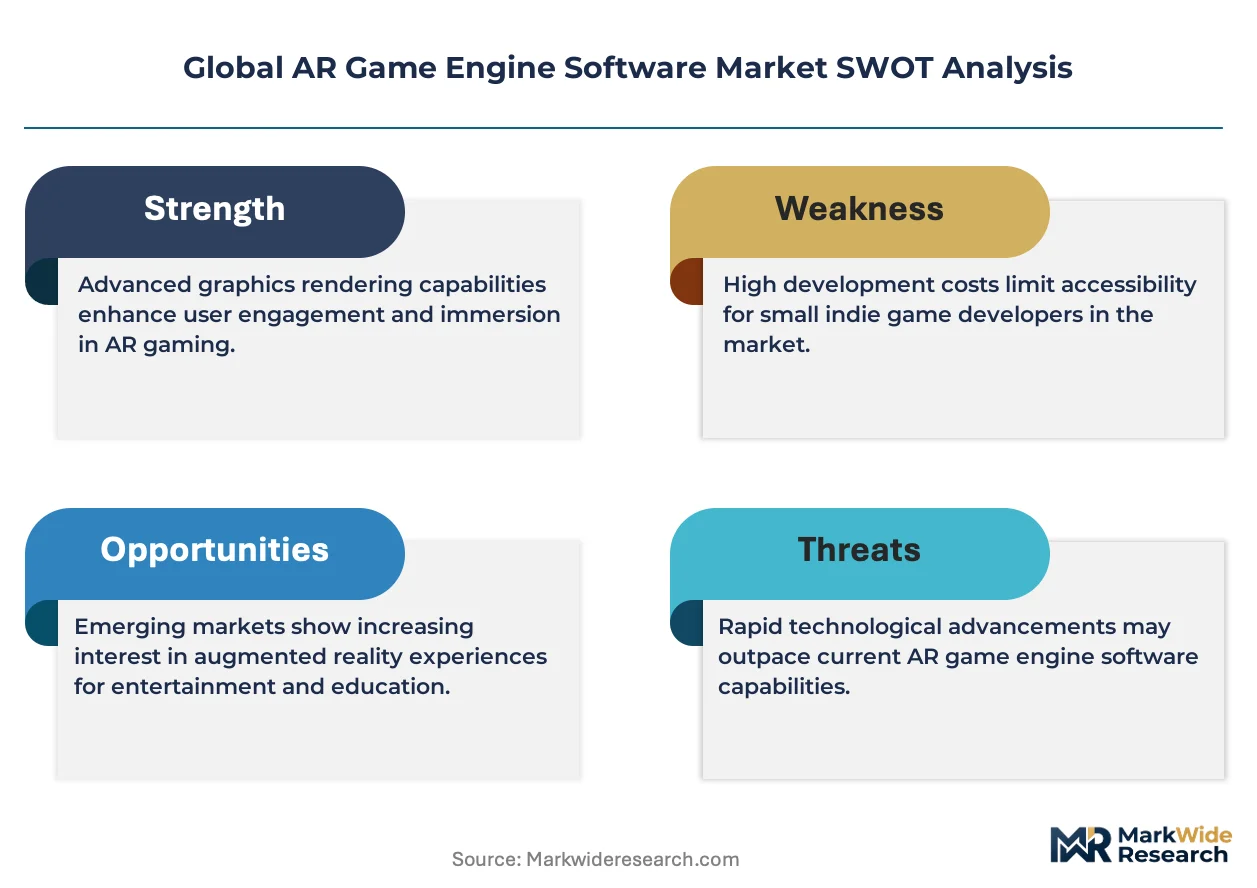
Cloud rendering pipelines are collapsing the traditional perpetual-license model, forcing engine vendors to rebuild revenue architectures around consumption-based metering and revenue-share partnerships with hardware OEMs.
Growth Catalysts
- EU AI Act compliance mandates:Biometric data processing restrictions accelerate on-device inference adoption, creating upgrade cycles for privacy-compliant engine architectures across European enterprise deployments.
- Industrial training simulators:Manufacturing and logistics departments replace physical equipment with spatial computing modules, driving per-seat pricing premiums for professional-grade engine licenses.
- SLAM algorithm advances:Visual-inertial odometry improvements under variable lighting conditions expand addressable use cases into warehouse and field service environments previously excluded by tracking instability.
Market Restraints
- Silicon supply concentration:Snapdragon Spaces optimization dependencies create middleware vulnerability to Qualcomm's roadmap decisions and foundry allocation priorities.
- GDPR biometric friction:Explicit consent flow requirements add deployment complexity and user abandonment risk for consumer-facing AR applications in European markets.
- Motion-to-photon latency floors:Sub-50-millisecond thresholds demand specialized rendering pipelines that inflate development costs for cross-platform engine compatibility.
Strategic Opportunities
- German automotive certification pathways:KBA safety standards for AR-enabled driver assistance create regulatory moats for engine vendors achieving type-approval integration.
- Surgical credentialing modules:FDA evaluation frameworks for AR training in medical education open professional services revenue streams distinct from entertainment licensing.
- Edge-cloud hybrid rendering:5G network slicing enables split-computation architectures that reduce device-side thermal constraints while maintaining latency budgets.
Industry Challenges
- Spatial mapping talent scarcity:Computer vision engineers with SLAM and sensor fusion expertise command compensation premiums that strain mid-tier engine vendor R&D budgets.
- Cross-platform shader fragmentation:Six operating system targets force maintenance of divergent rendering backends, multiplying QA cycles and technical debt accumulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AR Game Engine Software Market |
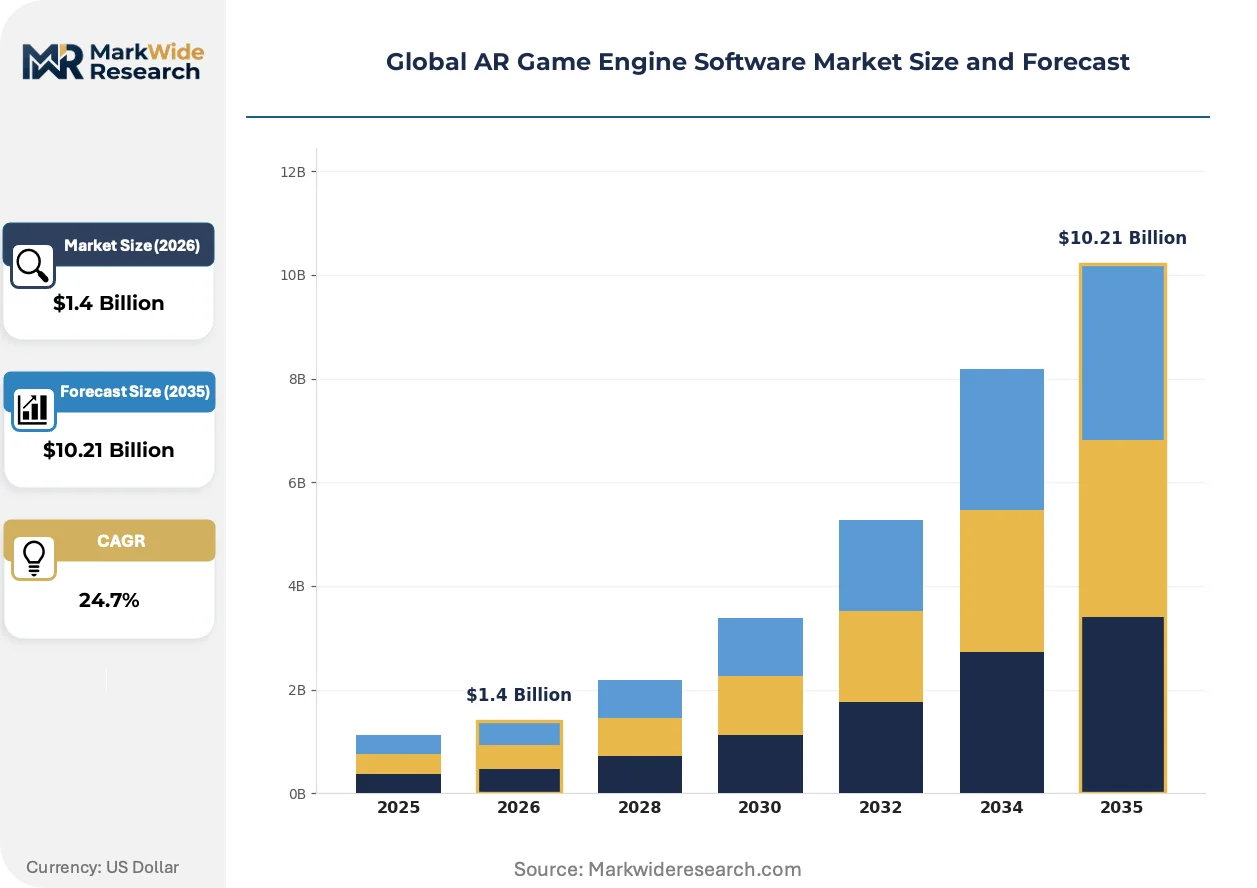
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $10.21 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Compatibility: iOS, Android, Windows, macOS, Linux, WebGL Core Technology: SLAM, Marker-Based Tracking, GPS-Based Tracking, Depth Sensing, Visual-Inertial Odometry, Sensor Fusion Application Type: Education, Retail Engagement, Tourism, Entertainment, Marketing, Industrial Training End User: Developers, Game Studios, Educational Institutions, Event Organizers, Advertising Agencies, Simulation Providers |
| Companies Covered | Unity Technologies, Epic Games, Niantic, Crytek GmbH, Cocos, Godot, Qualcomm Inc., Mozilla, YoYo Games Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AR Game Engine Software Market Shifts & Advancements
Neural compression and real-time neural radiance fields are rewriting fidelity-per-watt benchmarks, compressing the hardware performance gap between mobile and tethered AR experiences.
Neural radiance field (NeRF) rendering is collapsing the asset pipeline for photorealistic environmental mapping. Automotive design studios in Germany and Japan now deploy real-time NeRF capture for virtual showrooms, eliminating traditional photogrammetry bottlenecks. The technology is collapsing weeks of manual mesh optimization into hours of automated inference, redistributing competitive advantage toward compute infrastructure ownership.
China's NMPA and MIIT coordination on personal information protection standards for camera-access applications forces foreign engine providers to localize data residency architectures. The framework segments professional-grade engines from consumer tools through certification tiering. Surgical training module vendors targeting Chinese hospitals must demonstrate on-device facial geometry processing with zero cloud transmission.
Enterprise procurement committees now mandate outcome-based validation metrics for training simulator deployments, displacing seat-count licensing in favor of competency-attainment guarantees. German automotive OEMs and US logistics operators lead this contractual evolution. The shift compresses vendor cash conversion cycles while raising performance liability exposure.
Global AR Game Engine Software Market Segmentation
Segmentation in the AR game engine software market reveals how technical specifications, deployment environments, and buyer economics fragment demand. Each category exposes distinct purchasing logics that vendors must address through specialized licensing architectures and support tiers.
Platform Compatibility:
Mature mobile platforms anchor volume while emerging wearable and desktop targets command premium engineering investment.
- iOS:Apple's tight hardware-software integration enables sub-50-millisecond motion-to-photon latency benchmarks. Enterprise training contracts in the United States and Germany concentrate here due to fleet standardization and MDM compliance tooling.
- Android:Fragmented device matrices force engine vendors to maintain extensive shader variant libraries. Chinese logistics operators and Indian retail chains drive volume through white-label hardware procurement.
- Windows:Tethered industrial headsets rely on DirectX rendering pipelines for warehouse simulation fidelity.
- macOS:Creative professional workflows in Japanese automotive studios favor Metal-optimized engines for design visualization.
- Linux:Embedded robotics and drone swarms deploy headless AR guidance modules requiring stripped runtime footprints.
- WebGL:Browser-based retail try-on experiences bypass app store friction but sacrifice sensor fusion depth.
iOS and Android together handle the majority of throughput; WebGL is gaining share fastest as cloud rendering matures.
Core Technology:
Cost tier stratification separates foundational tracking modalities from premium sensor fusion stacks requiring specialized compute.
- SLAM:Simultaneous localization and mapping algorithms consume the largest R&D allocation across engine vendors. German manufacturing floors and US surgical training centers demand millimeter-scale spatial consistency under variable lighting.
- Visual-Inertial Odometry:Fusing camera feeds with IMU data reduces drift in GPS-denied environments. Field service deployments in Japan and warehouse robotics in China prioritize this modality for extended tracking sessions.
- Marker-Based Tracking:Legacy museum installations and budget education deployments still specify fiducial-dependent pipelines.
- GPS-Based Tracking:Location-based entertainment in urban cores relies on coarse outdoor positioning for geofenced content triggers.
- Depth Sensing:Time-of-flight and structured light modules enable occlusion handling for furniture placement applications.
- Sensor Fusion:Multi-modal integration layers command the highest per-seat pricing in professional-grade engine tiers.
SLAM handles the majority of throughput; Visual-Inertial Odometry is expanding most quickly as mobile IMU precision improves.
Application Type:
Customer type dictates margin structure, with entertainment buyers optimizing for reach and industrial buyers prioritizing outcome guarantees.
- Entertainment:Location-based experiences and mobile games drive the largest installed base through freemium content models. South Korean gaming conglomerates and US theme park operators anchor demand for high-fidelity character rendering.
- Industrial Training:Manufacturing and logistics departments replace physical simulators with spatial computing modules. German automotive OEMs and US warehouse operators generate the highest per-seat pricing through competency-attainment contracting.
- Education:K-12 and university procurement cycles favor perpetual licenses over subscription models.
- Retail Engagement:Virtual try-on and spatial commerce applications prioritize WebGL deployment for frictionless customer onboarding.
- Tourism:Heritage site AR overlays in Italy and Japan rely on GPS-Based Tracking for outdoor historical reconstruction.
- Marketing:Campaign-specific activations demand rapid deployment tooling and ephemeral content management.
Entertainment handles the majority of throughput; Industrial Training is climbing the fastest on share as enterprise procurement matures.
End User:
Volume concentration sits with production-scale buyers while margin capture favors specialized service integrators.
- Developers:Individual creators and small teams populate the long tail through revenue-share and indie licensing tiers. India's mobile-first developer ecosystem and Brazil's emerging AR startup scene concentrate growth here.
- Game Studios:Mid-size and AAA publishers negotiate enterprise support SLAs and source code access. Japanese and Polish studios drive console-adjacent AR pre-production pipelines.
- Educational Institutions:University research labs and vocational programs procure through academic pricing frameworks.
- Event Organizers:Temporary installation demands favor rental licensing and on-site technical support packages.
- Advertising Agencies:Campaign-centric buyers prioritize rapid iteration tooling and brand-safe content moderation.
- Simulation Providers:Defense and healthcare credentialing vendors require FDA and military certification alignment.
Developers handle the majority of throughput; Simulation Providers are gaining share fastest as professional certification standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise training deployments in Germany favor surgical-grade latency benchmarks while Chinese logistics operators prioritize volume scalability over fidelity. Developer ecosystems in the United States concentrate around San Francisco and Seattle, where hardware OEM partnerships anchor platform standardization.
United States
FDA evaluation frameworks for AR surgical training modules create compliance thresholds that segment professional-grade engines from consumer tools. The agency's medical device oversight extends to spatial computing credentialing systems, forcing vendors to maintain separate certification tracks. Boston's medical technology corridor hosts multiple simulation providers targeting hospital procurement committees with competency-attainment guarantees.
China
NMPA and MIIT coordination on personal information protection standards forces foreign engine providers to localize data residency architectures. The framework mandates on-device facial geometry processing with zero cloud transmission for camera-access applications. Shenzhen's hardware manufacturing cluster drives white-label AR device production for logistics operators demanding cost-optimized runtime footprints.
Germany
KBA safety standards for AR-enabled driver assistance systems create regulatory moats for engine vendors achieving type-approval integration. The EU AI Act's biometric data processing restrictions accelerate on-device inference adoption across European enterprise deployments. Stuttgart's automotive design studios deploy real-time neural radiance field capture for virtual showrooms, eliminating traditional photogrammetry bottlenecks.
Japan
METI industrial policy prioritizes spatial computing modules for manufacturing workforce training, with specific allocation for SME technology adoption subsidies. PMDA oversight of medical device software extends to AR surgical planning tools, creating parallel certification requirements. Nagoya's robotics corridor integrates headless AR guidance modules into automated production lines for precision assembly verification.
South Korea
MFDS medical software regulations govern AR training systems for surgical residency programs, with specific provisions for haptic feedback integration. National R&D funding concentrates on 5G network slicing for edge-cloud hybrid rendering architectures. Seoul's gaming conglomerates anchor demand for high-fidelity character rendering in location-based entertainment deployments.
Global AR Game Engine Software Market Competitive Landscape
Capability concentration sits with specialized sensor fusion vendors; scale advantage sits with cross-platform middleware providers. The vendor base organizes around three strategic archetypes: silicon-integrated SDK layers, cloud-native rendering pipelines, and open-source runtime engines. Competitive moves concentrate on hardware OEM revenue-share partnerships and regulatory certification pre-qualification for medical and automotive applications.
Within the integrated platform tier, Unity Technologies and Epic Games occupy positions as ecosystem anchors, while Qualcomm Inc. exemplifies the silicon-optimization archetype through middleware layers extending chip-level performance tuning. These three entities represent distinct competitive vectors: cross-platform reach, high-fidelity visualization, and hardware-native efficiency.
| Leading Market Players |
|---|
| Unity Technologies |
| Epic Games |
| Niantic |
| Crytek GmbH |
| Cocos |
| Godot |
| Qualcomm Inc. |
| Mozilla |
| YoYo Games Ltd. |
| Others |
Supply & Pricing Matrix
Qualcomm's Snapdragon Spaces optimization dependencies create single-source middleware vulnerability that determines both tiered engine licensing spreads and foundry allocation priorities across vendor portfolios. This silicon-level concentration forces pricing stratification across premium certification-grade, standard professional, and economy indie tiers while tethering supply chain resilience to Qualcomm's roadmap decisions.
Pricing Analysis
Long-term enterprise offtake contracts dominate professional-grade engine procurement, with German automotive OEMs and US hospital systems locking multi-year competency-attainment agreements. Pricing stratifies across premium FDA-certified surgical modules, standard industrial training licenses, and economy revenue-share indie tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the economy tier intensifies as Indian and Brazilian developer ecosystems expand, while enterprise buyers show lowest price sensitivity due to outcome-based validation requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and Samsung Foundry for neural processing unit fabrication, with ASE Technology and Amkor Technology holding advanced packaging capacity for AR-specific chipsets. Engine runtime distribution draws from Chinese white-label hardware clusters, German automotive electronics suppliers, and US cloud rendering infrastructure. Single-source vulnerability to Qualcomm's Snapdragon Spaces roadmap creates middleware chokepoint risk. Distribution runs through direct enterprise sales teams, hardware OEM bundling agreements, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR game engine market sits in early-cycle expansion as EU AI Act biometric compliance mandates force enterprise upgrade cycles across European manufacturing and healthcare deployments.
For Market Incumbents: Build regulatory certification moats by securing FDA surgical training pre-qualifications and KBA automotive type-approvals before emerging cloud-native rendering entrants achieve compliance scale. Deepen backward integration into on-device inference silicon partnerships to reduce Qualcomm middleware dependency. Anchor platform standardization through hardware OEM revenue-share exclusives with Apple and Meta. For New Entrants and Emerging Players: Pursue white-space capture in Chinese logistics operator segments where NMPA data residency requirements disadvantage foreign engine incumbents lacking localized architectures. Target Indian mobile-first developer ecosystems through revenue-share pricing with minimal upfront licensing friction. Lead with WebGL cloud rendering deployments that bypass app store gatekeeping for retail engagement applications. For Investors and Strategic Acquirers: FDA 510(k) clearance pathways for AR surgical training modules reshape the acquisition landscape toward professional-grade engine vendors with medical device regulatory infrastructure. Five-to-ten year viability favors simulation providers with defense and healthcare certification alignment over entertainment-focused middleware. Monitor EU AI Act enforcement patterns as signal for biometric data processing compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unity and Epic engine ecosystems anchor hardware OEM bundling agreements with Apple and Meta. |
| Regulatory Certification | FDA pre-qualification for surgical training modules creates professional-grade pricing premiums. |
| Strategic Partnership | Qualcomm Snapdragon Spaces partnerships extend silicon-level optimization into middleware layers. |
| Acquisition of Specialist Firm | SLAM and sensor fusion talent scarcity drives computer vision startup consolidation. |
| Geographic Expansion | China NMPA data residency mandates force localized engine architectures for camera-access applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with engine vendor executives, enterprise training procurement officers, platform engineers, and regulatory affairs specialists; and secondary validation through SEC filings, hyperscaler capex disclosures, App Annie mobile AR deployment data, and EU AI Act implementation guidance documents. Bottom-up triangulation across named vendor revenue disclosures and top-down cross-checks against hardware OEM shipment estimates anchored volume and value outputs.
Forecast inputs considered deployment model, organization size, vertical application, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro technology adoption curves. Industry-specific inputs included SLAM algorithm maturity timelines, 5G network slicing deployment schedules, and biometric data regulation enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT spending cycles, semiconductor foundry capacity allocation, or cross-border data flow restrictions would shift the trajectory. Quarterly review of FDA 510(k) submission volumes, EU AI Act enforcement actions, and Snapdragon Spaces roadmap disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Restaurant Management Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
CGI Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Service Dispatch Software Market
Software & Services
Smartphone Applications Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Architect Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Global Board Management Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Engineering Software Market
Software & Services
Performing Arts Software Market
Software & Services
Global Distribution Software Market
Software & Services
Global Process Mining Software Market