
 Bankruptcy Software Market | 2026-2036
Bankruptcy Software Market Size, Share, and Industry Trends Forecast 2026-2036
Bankruptcy Software Market Insights
Subscription-based case management is broadening what bankruptcy software vendors sell beyond perpetual licenses. Stretto leverages its creditor-facing platform to anchor restructuring workflow automation. Epiq sustains dominance in court-appointed administrative services through integrated technology infrastructure. Clio competes by extending practice management tools into bankruptcy-specialized modules for mid-sized legal firms.
Bankruptcy software encompasses case administration, creditor notification, asset tracking, and court filing systems designed to manage Chapter 7, 11, and 13 proceedings under federal insolvency frameworks. These platforms incorporate automated document generation, calendaring compliance with Rule 9006 deadlines, and electronic claims processing to reduce administrative overhead in high-volume trustee operations. Cloud-based deployment leads solution distribution by eliminating on-site server maintenance for geographically dispersed legal practices, while document automation captures margin pools through per-matter pricing models that scale with case complexity. Consumer bankruptcy applications outpace corporate restructuring in transaction volume, though enterprise cases generate substantially higher revenue per engagement through multi-entity coordination requirements.
The U.S. Courts Administrative Office mandates electronic filing through CM/ECF systems, forcing software vendors to maintain certified interoperability with federal docketing infrastructure. State bar associations and the American Bankruptcy Institute shape ethical standards for automated debtor communications and fee disclosure protocols. Stakeholders must monitor how proposed amendments to Federal Rules of Bankruptcy Procedure alter data retention and notification timelines, as these changes cascade directly into platform development roadmaps and compliance module pricing.
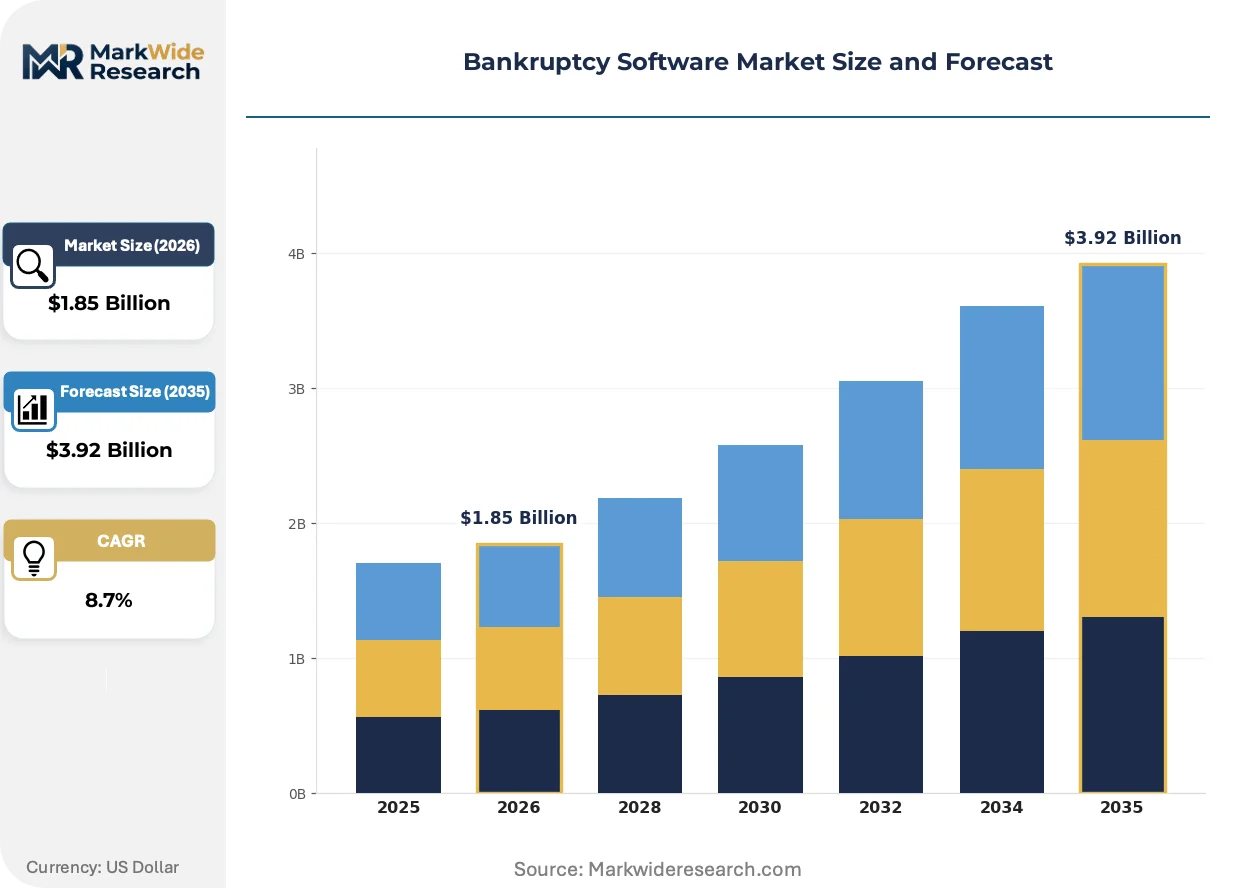
Market Dynamics
Federal electronic filing mandates through CM/ECF systems are compressing vendor certification timelines and forcing platform interoperability investments that reshape competitive economics for bankruptcy software providers.
Growth Catalysts
- Chapter 13 trustee automation:Calendaring compliance with Rule 9006 deadlines reduces manual administrative overhead in high-volume consumer proceedings.
- Cloud migration tailwinds:Elimination of on-site server maintenance costs accelerates adoption among geographically dispersed legal practices managing multi-district cases.
- Texas bankruptcy filing density:Elevated case volumes in Dallas and Houston bankruptcy courts sustain demand for creditor notification automation.
Market Restraints
- Federal certification bottlenecks:CM/ECF interoperability requirements create multi-quarter approval delays for new market entrants.
- Legacy data migration friction:Conversion of historical case files from on-premise systems to cloud architectures imposes substantial implementation costs.
- Substitute platform threat:General legal practice management tools with bankruptcy modules capture price-sensitive mid-market segments.
Strategic Opportunities
- Corporate restructuring workflow gaps:Multi-entity coordination requirements in Chapter 11 proceedings command premium pricing for specialized modules.
- Artificial intelligence convergence:Document automation integrated with natural language processing compresses claims processing timelines in asset-heavy cases.
- California state bar integration:Ethical standards for automated debtor communications create compliance module revenue streams.
Industry Challenges
- Bankruptcy-specialized developer scarcity:Deep expertise in Federal Rules of Bankruptcy Procedure limits platform engineering capacity.
- Legacy system integration complexity:Court-appointed trustees require seamless data exchange with decades-old administrative databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bankruptcy Software Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based, Mobile Solution Type: Case Management, Document Automation, Debt Recovery, Compliance Tracking, Reporting Tools End User: Legal Firms, Financial Advisors, Creditors, Government Agencies, Trustees Application: Consumer Bankruptcy, Corporate Restructuring, Debt Management, Asset Liquidation, Risk Assessment |
| Companies Covered | Stretto, Clio, Epiq, Aryza, Kroll, Altisource, Turnkey IPS, Fastcase, CARET, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bankruptcy Software Market Trends and Innovations
Platform architecture decisions are compressing vendor margins while creating divergence between integrated-suite providers and specialized point-solution developers.
Cloud-native case management infrastructure is consolidating vendor competitive positions by eliminating the capital intensity of on-premise deployment. Mid-sized legal practices in high-filing jurisdictions are migrating subscription workloads to hosted environments at accelerated cadences. This technology is consolidating margin pools around per-matter pricing models that scale with case complexity rather than user seat counts.
The U.S. Courts Administrative Office maintains stringent CM/ECF certification requirements that filter vendor participation in federal docketing workflows. These interoperability mandates force sustained engineering investment in compliance modules that interface with federal infrastructure. Chapter 7 trustee operations bear the highest compliance burden, driving consolidation toward vendors with established certification histories.
Subscription pricing is displacing perpetual license structures across legal practice segments with volatile case volumes. Smaller firms in consumer bankruptcy hotspots prefer operational expenditure models that align software costs with revenue recognition timing. California and Texas legal markets exhibit the most pronounced shift toward recurring-revenue arrangements.
Bankruptcy Software Market Segmentation
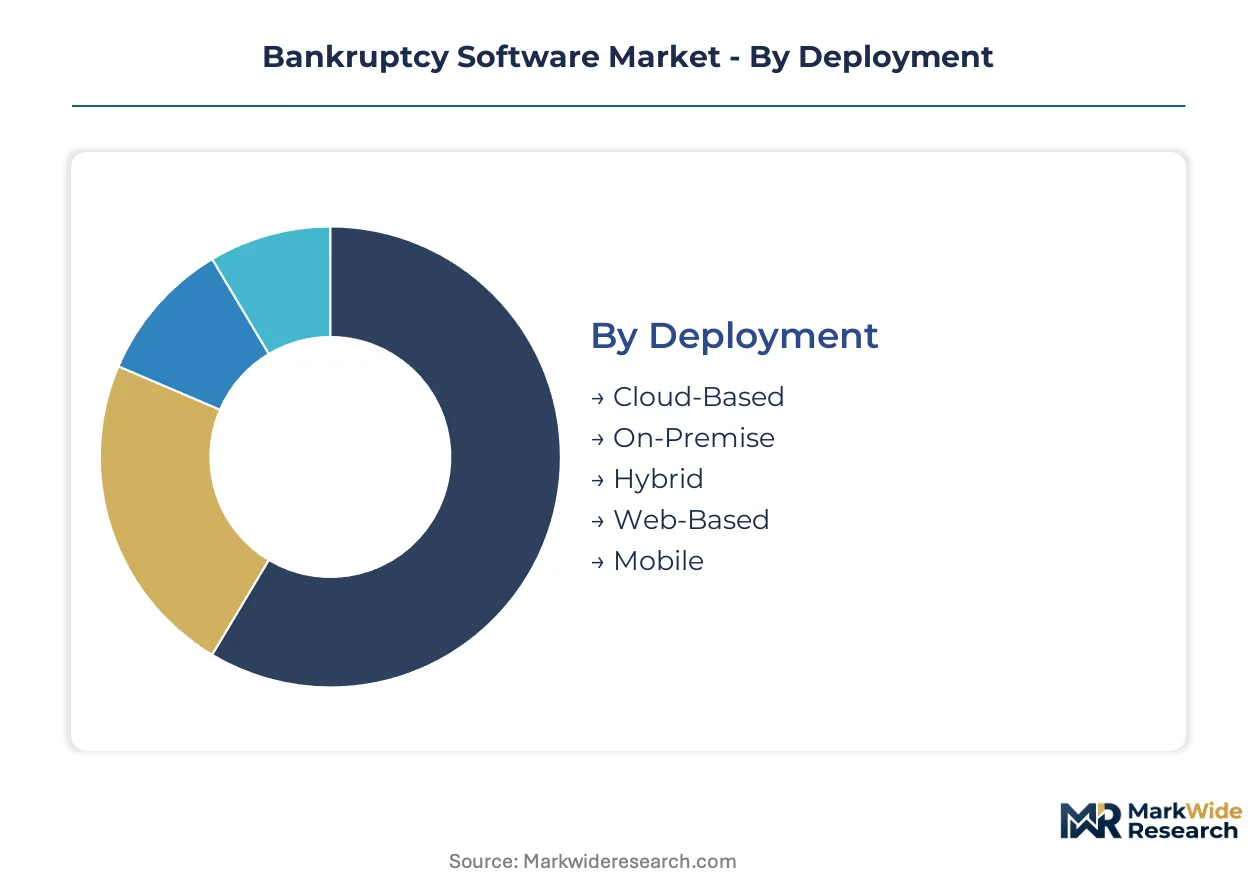
Bankruptcy software segmentation reveals how certification burdens, deployment economics, and end-user specialization create distinct margin pools across the market. Each dimension carries unique CM/ECF interoperability requirements that reshape vendor competitive positioning and pricing architecture.
Deployment:
CM/ECF certification timelines vary sharply by deployment architecture, with cloud-native platforms facing streamlined federal approval pathways compared to legacy on-premise conversions.
- Cloud-Based:Multi-tenant architectures eliminate server maintenance overhead for geographically dispersed practices. Demand concentrates among mid-sized legal firms in California and Texas seeking operational expenditure alignment with volatile case volumes.
- On-Premise:Legacy installations persist among court-appointed trustees managing decades of historical case files. Federal certification bottlenecks create multi-quarter delays for vendors attempting CM/ECF interoperability upgrades.
- Hybrid:Split architectures balance sensitive data retention on local servers with cloud-based collaboration tools. Appeals to trustees requiring seamless exchange with decades-old administrative databases.
- Web-Based:Browser-accessible platforms reduce IT infrastructure requirements for solo practitioners. Gains traction in consumer bankruptcy hotspots with price-sensitive entry-level segments.
- Mobile:Native applications extend calendaring compliance and document access to field-based trustee operations. Addresses Rule 9006 deadline management for high-volume Chapter 13 proceedings.
Leading the category by volume: Cloud-Based. Expanding most quickly: Mobile.
Solution Type:
Margin concentration tracks case complexity tiers, with multi-entity coordination modules commanding premium pricing over standardized consumer bankruptcy tools.
- Case Management:Centralized platforms integrate docketing, calendaring, and creditor notification workflows. Captures the largest revenue share through per-matter pricing models scaling with Chapter 11 proceeding intricacy.
- Document Automation:Natural language processing compresses claims processing timelines in asset-heavy cases. Demand clusters in corporate restructuring practices managing multi-entity coordination requirements.
- Debt Recovery:Automated workflows streamline creditor notification and distribution calculations. Serves trustees in high-volume consumer bankruptcy jurisdictions.
- Compliance Tracking:Ethical standards modules address state bar requirements for automated debtor communications. California state bar integration creates specialized revenue streams.
- Reporting Tools:Analytics dashboards translate case data into trustee administrative reports. Appeals to court-appointed administrators seeking transparency in asset liquidation proceedings.
Highest-margin segment: Document Automation. Steepest expansion trajectory: Compliance Tracking.
End User:
Procurement authority and budget scale diverge sharply across user types, with government agencies imposing stringent certification requirements that filter vendor participation.
- Legal Firms:Mid-sized practices drive subscription migration with operational expenditure preferences. Texas and California markets exhibit pronounced shift toward recurring-revenue arrangements.
- Financial Advisors:Restructuring specialists require multi-entity coordination capabilities for complex Chapter 11 engagements. Commands premium pricing through specialized workflow modules.
- Creditors:Notification automation platforms reduce administrative overhead in high-volume claims processing. Dallas and Houston bankruptcy courts sustain concentrated demand.
- Government Agencies:U.S. Courts Administrative Office mandates force sustained engineering investment in CM/ECF compliance modules. Creates highest barrier to vendor entry.
- Trustees:Court-appointed administrators bear the heaviest federal certification burden. Consolidation favors vendors with established CM/ECF certification histories.
Dominant procurement volume: Legal Firms. Fastest budget growth: Government Agencies.
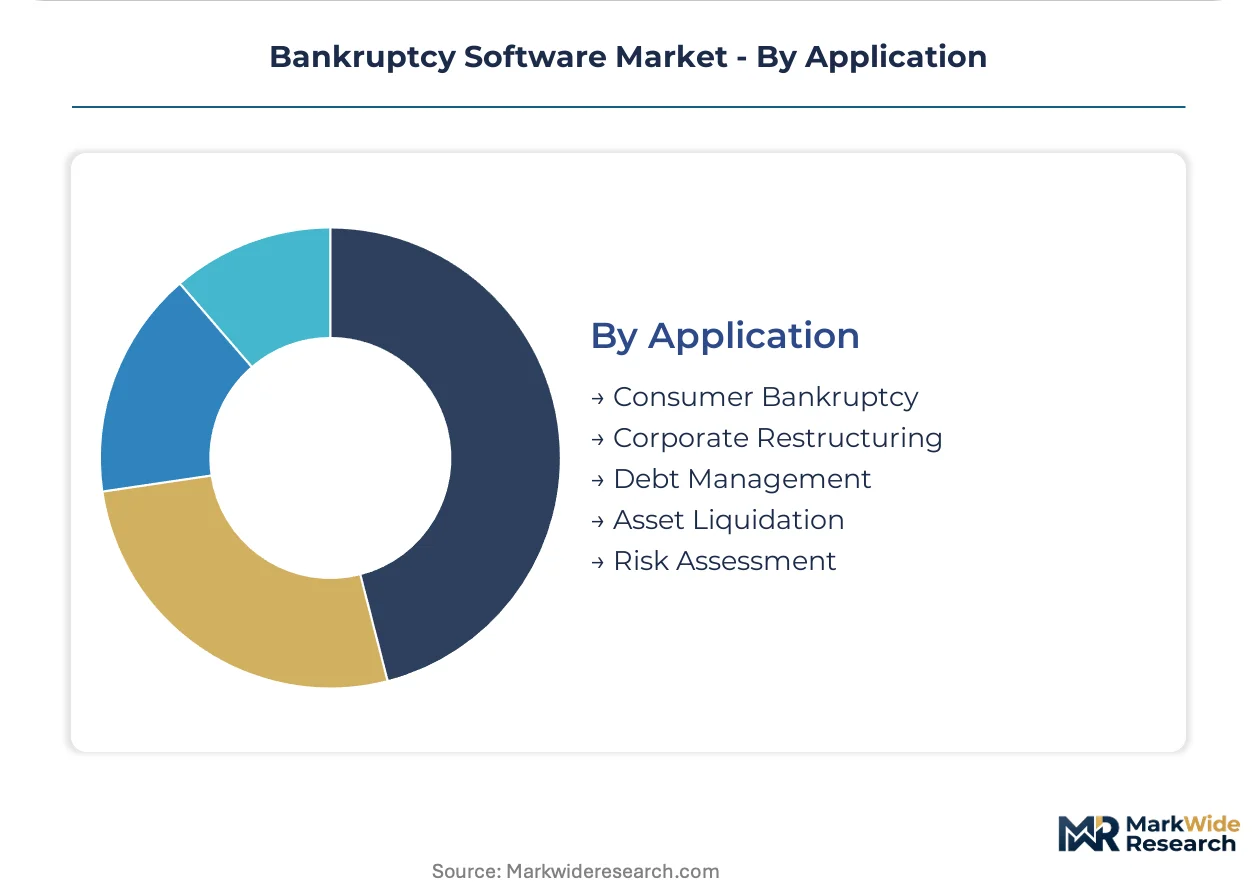
Application:
Revenue per engagement splits dramatically between high-transaction consumer segments and low-volume, high-value corporate restructuring assignments.
- Consumer Bankruptcy:Chapter 7 and 13 proceedings generate elevated transaction volumes with standardized workflow requirements. Automation of Rule 9006 calendaring compliance reduces manual administrative overhead.
- Corporate Restructuring:Chapter 11 multi-entity coordination commands premium pricing through specialized modules. Enterprise cases generate substantially higher revenue per engagement despite lower transaction frequency.
- Debt Management:Repayment plan administration tools serve credit counseling agencies and trustee operations. Addresses consumer bankruptcy application volume concentration.
- Asset Liquidation:Tracking systems manage inventory valuation and distribution workflows. Supports trustee operations in asset-heavy case administration.
- Risk Assessment:Predictive analytics evaluate restructuring feasibility and creditor recovery prospects. Gains adoption among financial advisors in corporate restructuring practices.
Transaction volume leader: Consumer Bankruptcy. Revenue per engagement leader: Corporate Restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dallas and Houston anchor North American bankruptcy software demand through elevated Chapter 13 filing volumes and concentrated trustee operations. Federal electronic filing mandates through CM/ECF systems create distinct certification requirements across jurisdictions, shaping vendor deployment strategies.
United States
California, Texas, and New York sustain the highest bankruptcy filing densities nationwide. The U.S. Courts Administrative Office mandates CM/ECF interoperability for all federal docketing platforms, forcing sustained engineering investment. Dallas and Houston bankruptcy courts drive concentrated demand for creditor notification automation in high-volume consumer proceedings.
Canada
Ontario and British Columbia legal markets exhibit accelerating cloud migration among mid-sized restructuring practices. The Office of the Superintendent of Bankruptcy oversees federal insolvency proceedings under the Bankruptcy and Insolvency Act. Toronto anchors corporate restructuring activity, with practitioners adopting subscription-based case management platforms.
United Kingdom
London insolvency specialists command premium pricing for multi-entity coordination in cross-border restructuring engagements. The Insolvency Service regulates practitioner licensing and ethical standards for automated debtor communications. The City of London financial district concentrates demand for document automation in asset-heavy corporate proceedings.
Germany
Bavaria and North Rhine-Westphalia house the densest concentrations of restructuring advisory practices in continental Europe. The Federal Ministry of Justice oversees implementation of the EU Restructuring Directive into national insolvency frameworks. Munich-based financial advisors drive adoption of compliance tracking modules aligned with German ethical standards.
Australia
New South Wales and Victoria legal markets demonstrate pronounced shift toward operational expenditure models for practice management technology. The Australian Financial Security Authority mandates electronic submission protocols for personal insolvency proceedings. Sydney anchors demand for cloud-native case administration platforms serving geographically dispersed trustee operations.
Bankruptcy Software Market Competitive Landscape
Capital-heavy integrated-suite providers compete with asset-light specialized developers across distinct certification and deployment vectors. The vendor base concentrates around established CM/ECF certification histories, creating multi-quarter barriers for new market entrants. Three strategic archetypes dominate: integrated legal practice management extenders, court-appointed administrative service platforms, and creditor-facing workflow automation specialists. Dominant competitive moves include geographic expansion into high-filing-density jurisdictions and portfolio diversification through AI-enabled document automation modules.
Within the integrated-suite tier, Clio occupies a position exemplifying practice management extension strategies into bankruptcy-specialized modules. Among creditor-facing platform developers, Stretto anchors restructuring workflow automation archetypes. Epiq sits within the court-appointed administrative services category, representing established certification infrastructure advantages. These three entities collectively illustrate how CM/ECF interoperability investments and cloud-native architectures reshape competitive economics.
| Leading Market Players |
|---|
| Stretto |
| Clio |
| Epiq |
| Aryza |
| Kroll |
| Altisource |
| Turnkey IPS |
| Fastcase |
| CARET |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure pricing indices cascade through bankruptcy software supply chains into tiered subscription models, compressing margins for vendors without established CM/ECF certification histories while rewarding integrated-suite providers with federal interoperability investments.
Pricing Analysis
Margin tightening in mid-market tiers reflects general legal practice management tools capturing price-sensitive segments with bankruptcy modules. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by CM/ECF certification grade and volume scale. Cost compression accelerates in consumer bankruptcy hotspots as subscription models displace perpetual licenses. Solo practitioners exhibit highest price sensitivity; court-appointed trustees show lowest sensitivity due to federal compliance mandates.
Supply Chain Analysis
Regional distribution centers for cloud-native platforms cluster in Northern Virginia, Dallas, and Phoenix to minimize latency for federal court system interfaces. Engineering talent concentrates in the United States, India, and Canada, with deep expertise in Federal Rules of Bankruptcy Procedure anchoring platform development. Supply chain risk centers on single-source vulnerability for CM/ECF certification consulting. Distribution runs through direct sales to legal firms and channel partnerships with court-appointed administrative services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bankruptcy software market functions as a cost-of-compliance story where U.S. Courts Administrative Office CM/ECF mandates erect multi-quarter barriers that protect certified incumbents from unqualified entrants.
For Market Incumbents: To counter substitute platform threats from general legal practice management extenders, deepen CM/ECF certification moats through sustained engineering investment in compliance modules and acquire specialized document automation capabilities to capture corporate restructuring premium pricing. For New Entrants and Emerging Players: Begin with white-space targeting of mobile-native applications for Chapter 13 trustee field operations in Texas and California consumer bankruptcy hotspots, leveraging streamlined federal approval pathways for cloud-native architectures against legacy on-premise conversion friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor court-appointed administrative service platforms with established certification histories in the United States, where long-term viability hinges on federal interoperability durability; watch CM/ECF amendment proposals as inflection indicators for compliance module demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| CM/ECF Certification Investment | Federal interoperability mandates force sustained engineering spend that filters vendor participation. |
| AI Document Automation Acquisition | Natural language processing capabilities compress claims processing timelines in asset-heavy Chapter 11 proceedings. |
| Geographic Expansion into Texas | Dallas and Houston bankruptcy courts sustain concentrated demand for creditor notification automation. |
| Mobile Platform Development | Native applications address Rule 9006 deadline management for high-volume Chapter 13 trustee operations. |
| Strategic Partnership with Trustees | Court-appointed administrator relationships anchor recurring revenue through multi-year administrative service contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among bankruptcy trustees, legal practice managing partners, CM/ECF certification consultants, court administrative officers, and software platform engineers. American Bankruptcy Institute proceedings, U.S. Courts Administrative Office technical specifications, state bar association ethics opinions, SEC 10-K disclosures from legal technology vendors, and federal docketing system documentation supplied validation layers. Bottom-up case volume modeling and top-down addressable market sizing underwent iterative reconciliation.
Data-stream reconciliation across deployment architecture, solution type, end-user category, and application segments shaped analytical framework construction throughout the projection horizon. CAGRs derived from historical filing velocity trends, cloud migration adoption curves, and federal mandate implementation timelines. Chapter 11 multi-entity coordination complexity and Chapter 13 trustee automation penetration served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment and consumer bankruptcy application data carry tighter precision than hybrid architectures and corporate restructuring forecasts. Outputs reflect assumptions around CM/ECF certification timeline stability and state bar ethics standard evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Meditation Software Market
Software & Services
Lighting Control Software Market
Software & Services
Global Help Desk Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Global Absence Management Software Market
Software & Services
Desktop Hypervisor Market
Software & Services
Lead Scoring Software Market
Software & Services
Classified Platform Market
Software & Services
Global Business Card Software Market
Software & Services
Global Custom Software Development Services Market
Software & Services
Construction Software Market
Software & Services
Workstation Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Avionics Software Market
Software & Services
Software Repository Market