
 PLM Software Market | 2026-2036
PLM Software Market Size, Share, and Industry Trends Forecast 2026-2036
PLM Software Market Outlook
German automotive suppliers and industrial machinery producers is recalibrating how PLM platforms integrate with digital twin architectures. Siemens Digital Industries Software leverages deep manufacturing domain expertise to anchor its position in discrete industries. Dassault Systèmes sustains competitive differentiation through 3D experience platforms that span design simulation to shop-floor execution. Autodesk competes aggressively on accessibility, extending cloud-native tools to mid-market engineering teams that previously lacked enterprise-grade capabilities.
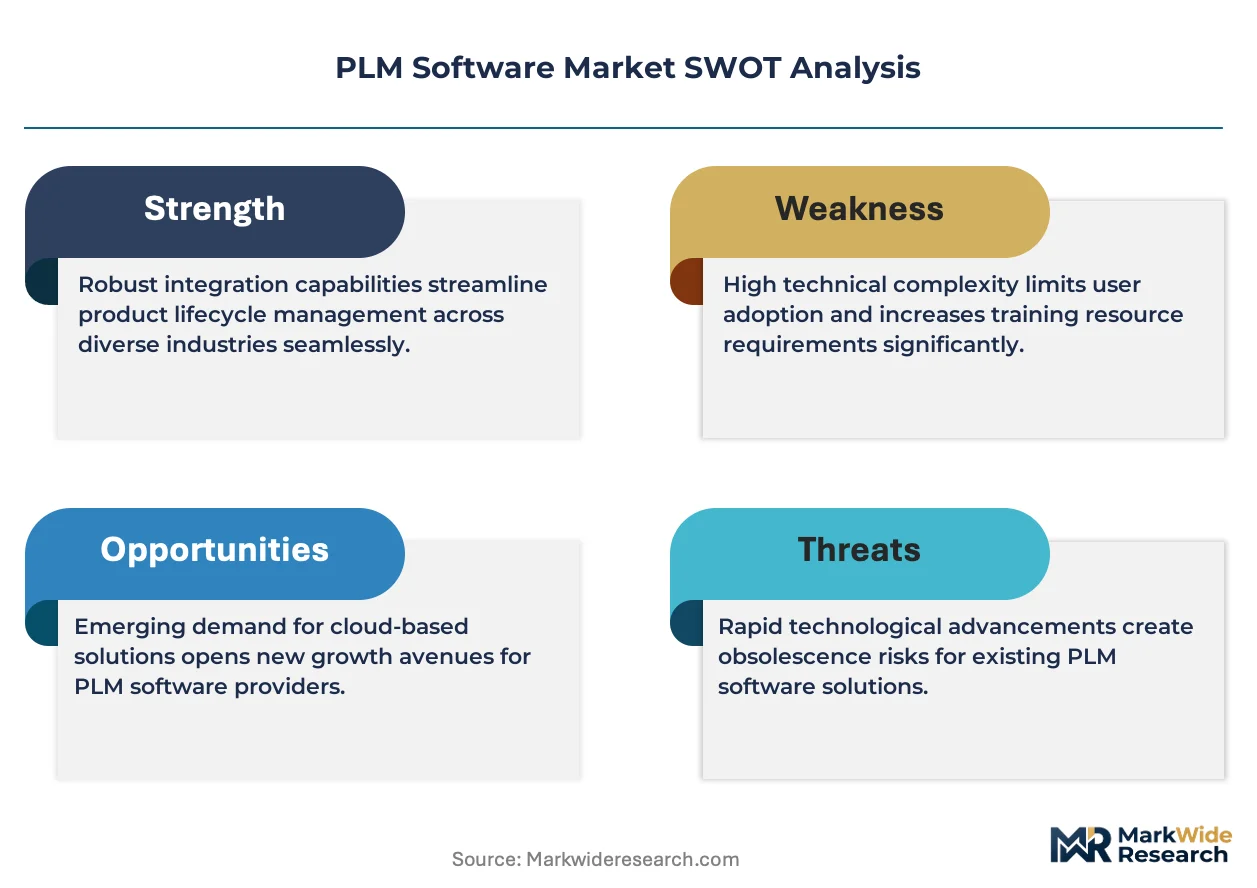
Product lifecycle management software governs the complete digital thread from conceptual design through service retirement, embedding version control, change management, and cross-functional collaboration into unified data models. Cloud-based deployments now outpace on-premise installations as manufacturers prioritize elastic compute for simulation workloads and distributed engineering teams. Aerospace and automotive end users command the largest solution investments, driven by compliance management requirements for traceability and long-tail aftermarket support. Data management and workflow automation solutions capture disproportionate margin pools where vendor stickiness runs highest.
The EU AI Act and GDPR impose strict algorithmic transparency and data residency requirements on PLM platforms processing sensitive design IP across borders. ISO standards for interoperability and NIST cybersecurity frameworks shape how vendors architect cross-enterprise data exchanges. FDA 21 CFR Part 11 compliance remains non-negotiable for medical device manufacturers embedding PLM within regulated quality systems. Stakeholders must weigh sovereign cloud requirements against multi-tenant economics when selecting deployment architectures for the next decade of engineering digitization.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for PLM platforms while ISO 27001 certification demands reshape vendor qualification criteria across aerospace and automotive supply chains.
Growth Catalysts
- EU AI Act compliance mandates:Aerospace manufacturers in Germany and France must embed algorithmic traceability into digital threads, forcing PLM upgrades that capture model lineage and decision audit trails.
- Digital twin convergence:Automotive OEMs in Stuttgart and Munich are mandating real-time physics-based simulation integration between PLM and manufacturing execution systems.
- Elastic compute for simulation:Cloud infrastructure is unshackling engineering teams from on-premise hardware constraints, enabling distributed collaboration across supplier networks.
Market Restraints
- Specialized talent scarcity:System architects capable of bridging mechanical CAD, data science, and cloud infrastructure command compensation premiums that inflate implementation costs.
- Data residency fragmentation:GDPR and emerging sovereign cloud requirements in France, Germany, and China are fragmenting platform architectures and diluting multi-tenant economics.
- Legacy system entrenchment:Decades of on-premise PLM investment at major industrial conglomerates creates switching friction that slows cloud migration timelines.
Strategic Opportunities
- Mid-market accessibility gap:Industrial machinery producers in Bavaria and Baden-Württemberg lack enterprise-grade PLM capabilities, creating white space for modular, subscription-based offerings.
- Aftermarket service monetization:Long-tail spare parts and predictive maintenance integration is opening recurring revenue streams tied to PLM-managed asset histories.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive is mandating lifecycle carbon accounting that PLM platforms can automate through embedded environmental data models.
Industry Challenges
- Cross-functional workflow redesign:PLM implementations require re-engineering how design, procurement, and quality teams share data, creating organizational resistance that stalls deployments.
- Interoperability standard gaps:Incomplete ISO 10303 STEP implementations force costly custom integrations between PLM and specialized simulation or manufacturing software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PLM Software Market |
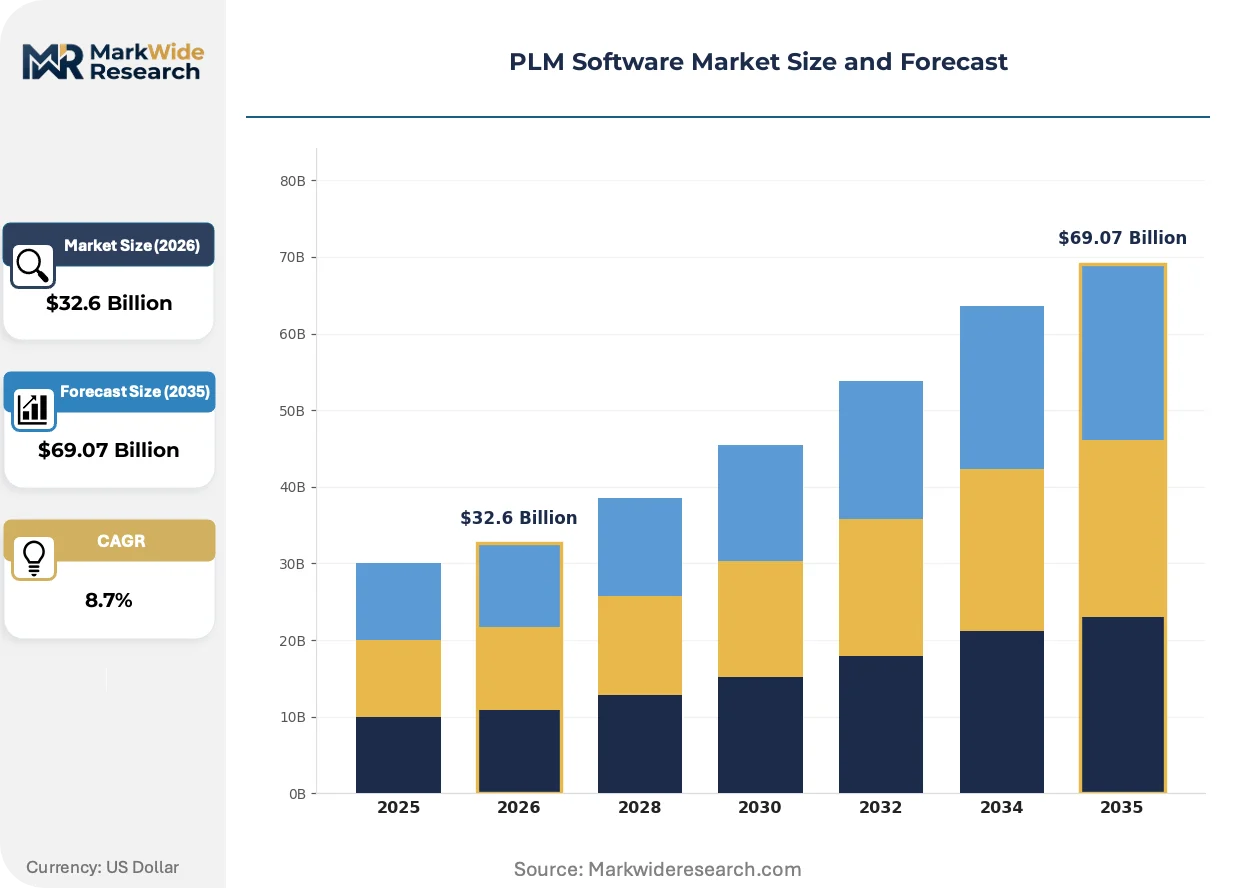
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Aerospace, Automotive, Consumer Goods Deployment: Private Cloud, Public Cloud, Multi-Tenant, Single-Tenant Solution: Data Management, Product Design, Compliance Management, Workflow Automation |
| Companies Covered | Siemens Digital Industries Software, Dassault Systèmes, Autodesk, PTC, Synopsys, Cadence Design Systems, Ansys, Hexagon, Bentley Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PLM Software Market Strategic Shifts
Generative design algorithms and low-code configuration tools are compressing the traditional boundary between PLM as a system of record and PLM as an active design collaborator.
Model-based systems engineering (MBSE) is unifying requirements management, functional architecture, and physical design within single digital thread environments. Aerospace prime contractors in Toulouse and Hamburg are deploying MBSE to compress systems integration testing cycles. This unification is collapsing the historical separation between conceptual design and detailed engineering phases.
The EU AI Act's risk-based classification system is mandating explainability documentation for AI-assisted design decisions embedded in PLM workflows. Medical device manufacturers face the strictest compliance burdens, with notified bodies in Germany and the Netherlands requiring algorithmic impact assessments as part of technical file submissions. High-risk AI applications in diagnostic equipment are driving demand for PLM modules that capture training data provenance and model versioning.
Engineering software purchasing is consolidating under central IT procurement functions rather than remaining within individual R&D departments. Automotive suppliers in Lower Saxony and Bavaria are standardizing on enterprise-wide platform contracts that bundle PLM with simulation and IoT analytics. This centralization is compressing vendor evaluation cycles while elevating cybersecurity certification and API governance as decisive selection criteria.
PLM Software Market Segmentation
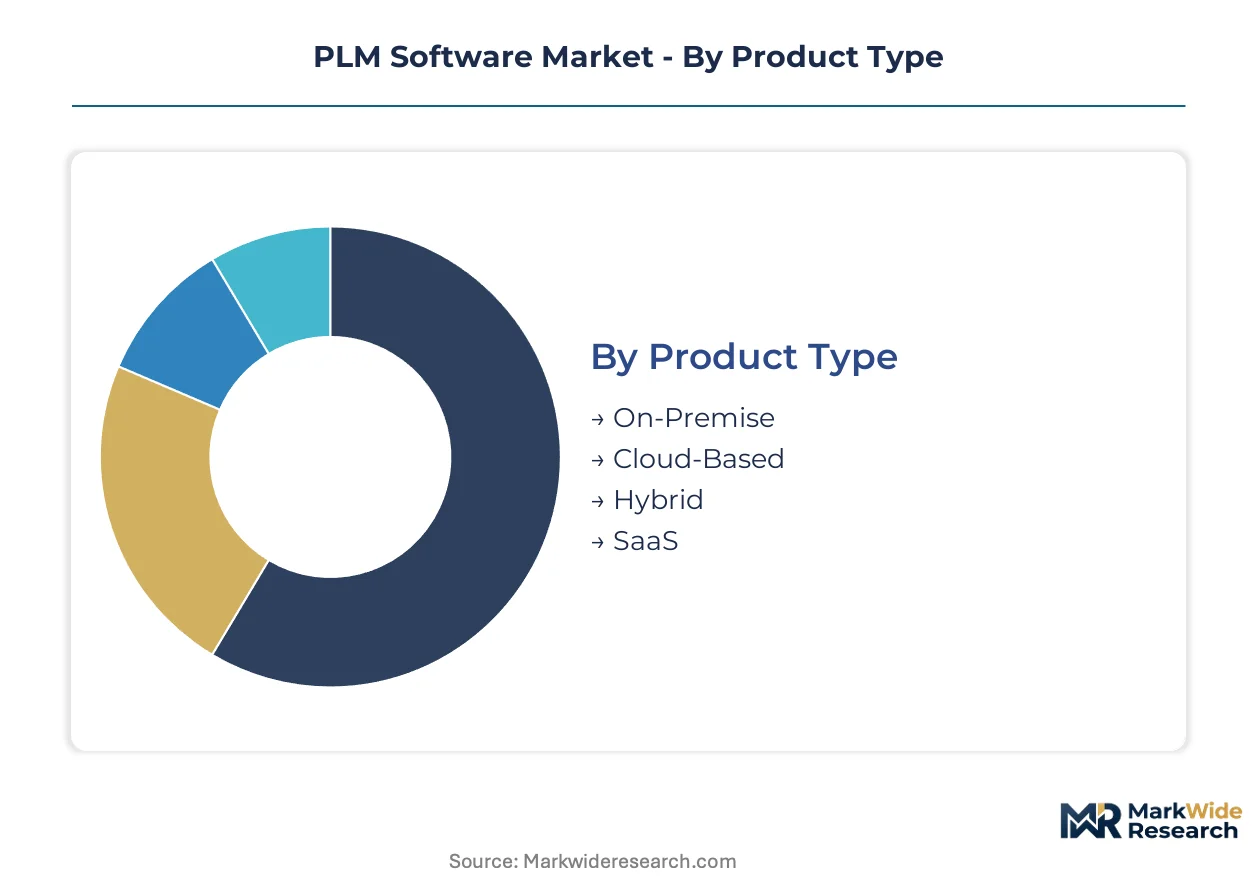
PLM software segmentation reflects divergent buyer priorities across infrastructure maturity, regulatory exposure, and collaboration intensity. Procurement teams weight total cost of ownership against data sovereignty requirements when mapping segments to operational needs.
Product Type:
Cost tier separates enterprise buyers maintaining legacy control from mid-market teams prioritizing accessibility and elastic scaling.
- On-Premise:Full-stack deployment within customer data centers delivers maximum configuration control and air-gapped security. Aerospace primes in Toulouse and Hamburg favor this model for ITAR-controlled programs where cloud egress triggers compliance violations. Volume sits with defense-adjacent manufacturers; growth tilts toward regulated medical device producers in Germany and Switzerland.
- Cloud-Based:Vendor-managed infrastructure eliminates capital expenditure and accelerates deployment timelines. Automotive suppliers in Stuttgart and Munich are migrating here to support distributed engineering across supplier networks. Elastic compute for simulation workloads drives procurement decisions.
- Hybrid:Split architectures preserve sensitive IP on-premise while pushing collaboration layers to cloud. Industrial machinery producers in Bavaria deploy this model to balance GDPR data residency with supplier portal requirements.
- SaaS:Subscription pricing and rapid provisioning target mid-market engineering teams previously excluded from enterprise PLM. Consumer goods designers in Milan and Barcelona leverage these tools for compressed product development cycles.
Volume concentrates in On-Premise installations; Cloud-Based deployments are climbing the fastest as ISO 27001 certification becomes table stakes.
End User:
Application context determines feature prioritization — traceability depth, simulation integration, and compliance documentation vary sharply.
- Manufacturing:Discrete producers and process industries require shop-floor connectivity and production order synchronization. German automotive suppliers anchor demand here, driven by CSRD lifecycle carbon accounting mandates.
- Aerospace:Digital thread requirements span decades-long program lifecycles with rigorous configuration management. Airbus and Safran suppliers in France deploy MBSE-integrated PLM to compress systems integration testing.
- Automotive:Real-time physics-based simulation integration between PLM and manufacturing execution systems is now mandatory. OEMs in Munich and Wolfsburg lead adoption, with tier-one suppliers following under platform consolidation directives.
- Consumer Goods:Rapid SKU turnover and packaging sustainability tracking dominate requirements. Italian and Spanish producers prioritize cloud-native tools for seasonal design cycles.
Automotive captures the largest solution investments; Aerospace is expanding most quickly under EU AI Act algorithmic traceability mandates.
Deployment:
Customer type and data sensitivity dictate tenancy models, with procurement functions elevating cybersecurity certification as decisive criteria.
- Private Cloud:Dedicated infrastructure within sovereign boundaries satisfies GDPR and emerging national cloud requirements. French and German defense contractors mandate this architecture.
- Public Cloud:Shared infrastructure delivers lowest unit economics and fastest provisioning. Mid-market machinery producers in Baden-Württemberg favor this model for non-sensitive design collaboration.
- Multi-Tenant:Vendor-managed resource pooling maximizes efficiency for standardized workloads. SaaS-native vendors compete here on accessibility and rapid implementation.
- Single-Tenant:Isolated environments preserve complete data segregation for competitive IP protection. Medical device manufacturers in Germany and the Netherlands require this for FDA 21 CFR Part 11 compliance.
Multi-Tenant dominates new subscription revenue; Single-Tenant is gaining share fastest as sovereign cloud fragmentation intensifies.
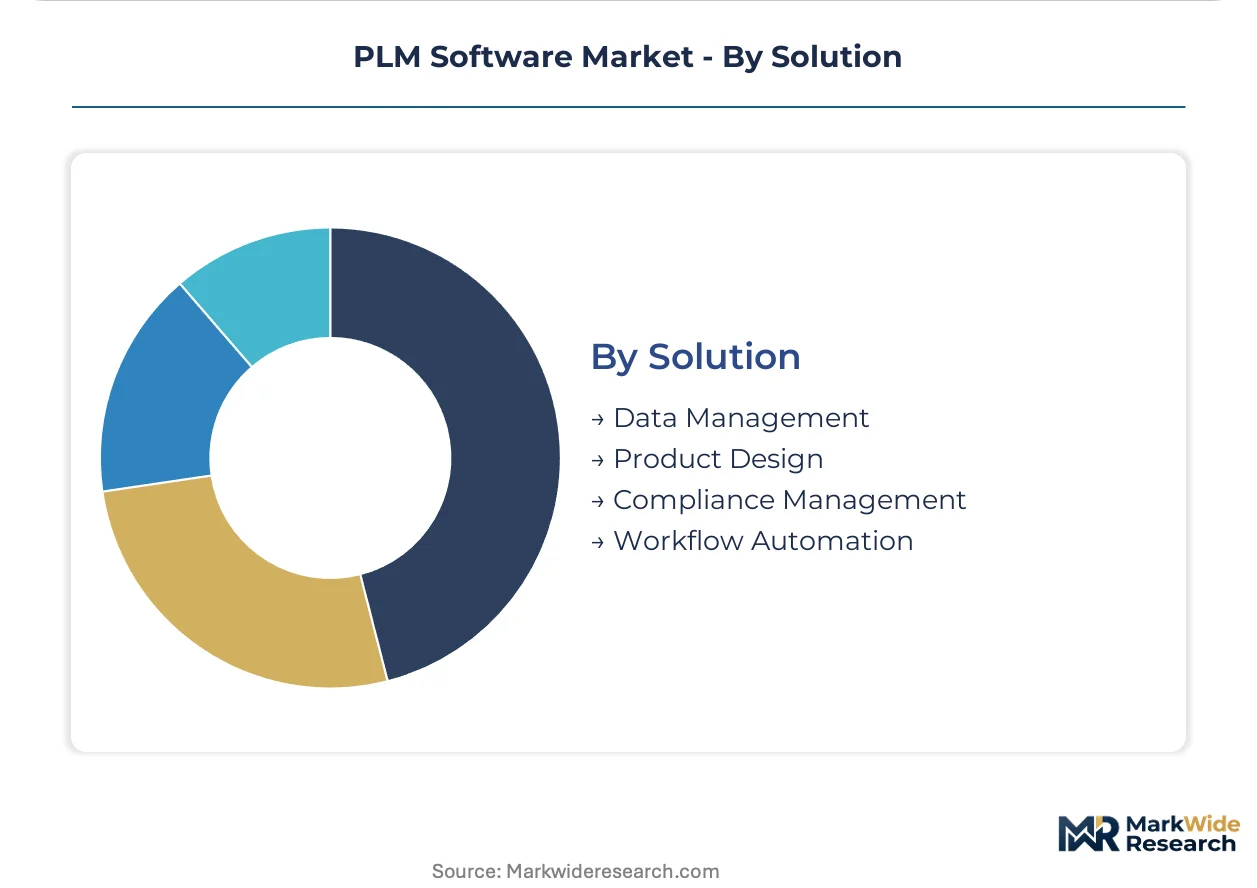
Solution:
Margin concentration follows workflow automation and data management modules where vendor stickiness runs highest and switching costs compound.
- Data Management:Unified data models embed version control, change management, and cross-functional collaboration. This module anchors platform stickiness across aerospace and automotive supply chains.
- Product Design:CAD-integrated environments span conceptual design through detailed engineering. Generative design algorithms are compressing traditional boundaries between system of record and active design collaborator.
- Compliance Management:Automated traceability documentation satisfies EU AI Act, MDR, and CSRD requirements. Medical device and aerospace buyers mandate these capabilities for technical file submissions.
- Workflow Automation:Cross-functional process orchestration between design, procurement, and quality teams captures disproportionate margin pools. Implementation complexity creates organizational resistance that stalls deployments.
Data Management holds the largest installed base; Compliance Management shows the steepest expansion trajectory under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering expertise anchors European PLM demand, while cloud infrastructure investments in the United States and simulation-intensive manufacturing in Japan create distinct procurement patterns across major economies.
United States
Aerospace primes and defense contractors in Seattle and Los Angeles drive demand for air-gapped PLM deployments handling ITAR-controlled programs. The FAA mandates digital thread documentation for commercial aircraft certification. Boeing suppliers in Washington state and Lockheed Martin partners in Texas anchor the largest on-premise installation base.
Germany
Automotive OEMs in Stuttgart and Munich mandate real-time physics-based simulation integration between PLM and manufacturing execution systems. The KBA enforces type-approval documentation standards that cascade through tier-one supplier networks. Industrial machinery producers in Bavaria and Baden-Württemberg are migrating toward hybrid cloud architectures to balance GDPR compliance with supplier collaboration.
France
Airbus and Safran suppliers in Toulouse deploy model-based systems engineering to compress aircraft systems integration testing. The ANSM and CNIL impose strict algorithmic transparency requirements on AI-assisted design workflows under the EU AI Act. Aerospace engineering clusters in Toulouse and Paris-Saclay concentrate the highest compliance management module adoption.
Japan
Precision equipment manufacturers and automotive suppliers in Nagoya and Toyota City prioritize PLM integration with robotics and automated production lines. METI's Society 5.0 initiative accelerates digital twin investments across discrete manufacturing. Electronics producers in Osaka and Yokohama anchor demand for semiconductor design lifecycle management.
United Kingdom
Formula One engineering clusters in Silverstone and advanced aerospace in Bristol drive simulation-intensive PLM procurement. The UK Medicines and Healthcare products Regulatory Agency enforces MDR-aligned technical documentation standards for medical device developers. Automotive suppliers in the Midlands are consolidating engineering software purchasing under central IT procurement functions.
PLM Software Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular SaaS delivery for mid-market engineering teams previously excluded from enterprise-grade capabilities. The vendor landscape consolidates around three maturity tiers: diversified industrial software conglomerates, specialized engineering simulation houses, and cloud-native challengers. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and vertical integration into manufacturing execution systems.
Within the diversified industrial tier, Siemens Digital Industries Software and Dassault Systèmes exemplify archetypes combining deep manufacturing domain expertise with platform breadth. Autodesk occupies a position representing accessibility-focused challengers extending cloud-native tools downstream. PTC anchors the industrial IoT convergence archetype, bridging PLM with connected service and predictive maintenance capabilities. These three companies collectively represent the competitive vectors shaping procurement criteria across aerospace, automotive, and industrial machinery end markets.
| Leading Market Players |
|---|
| Siemens Digital Industries Software |
| Dassault Systèmes |
| Autodesk |
| PTC |
| Synopsys |
| Cadence Design Systems |
| Ansys |
| Hexagon |
| Bentley Systems |
| Others |
Value Chain & Pricing Dynamics
CSRD lifecycle carbon accounting mandates gate both qualified supply and premium-tier pricing access in the PLM software market. Automotive OEMs in Stuttgart and Munich now require ISO 27001-certified vendors with embedded environmental data models, compressing margins for non-compliant providers while elevating pricing power for certified platforms.
Pricing Analysis
Warranty and service bundling separates premium PLM offerings from stripped-down alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ISO 27001 certification grade and after-sales implementation support. Cost compression in the economy tier is intensifying because hyperscale cloud providers are commoditizing basic data management modules. Mid-market machinery producers in Bavaria exhibit highest price sensitivity, while aerospace primes in Toulouse accept premium pricing for air-gapped compliance capabilities.
Supply Chain Analysis
Dual-sourcing requirements for hyperscale cloud infrastructure now mandate multi-supplier qualification across AWS, Azure, and Google Cloud for enterprise PLM deployments. Software development concentrates in the United States, Germany, and France, with cloud infrastructure drawing from Ireland, the Netherlands, and Singapore data centers. Single-source vulnerability persists in specialized MBSE simulation engines sourced from French and German engineering houses. Distribution runs through direct enterprise sales teams and certified systems integrators serving automotive and aerospace verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PLM software market functions as a cost-of-compliance story where EU AI Act algorithmic traceability requirements create a barrier-to-entry moat for compliant players. Vendors lacking embedded audit trail capabilities face exclusion from aerospace and medical device procurement cycles.
For Market Incumbents: Deploy sovereign cloud certification as the primary defensive lever. Siemens Digital Industries Software and Dassault Systèmes should accelerate in-house production of Gaia-X compliant data residency modules to preempt emerging entrant challenges. Backward integration into manufacturing execution systems strengthens platform stickiness against modular SaaS challengers. For New Entrants and Emerging Players: Enter via the mid-market machinery producer segment in Baden-Württemberg where enterprise-grade PLM penetration remains below aerospace and automotive tiers. Target industrial machinery producers with subscription-based offerings emphasizing rapid deployment over customization depth. Partner with regional systems integrators for implementation credibility. For Investors and Strategic Acquirers: ISO 27001 certification acceleration among mid-tier vendors is the leading indicator that consolidation value is accumulating in the compliance-enabled segment. Acquisition targets should exhibit embedded AI governance modules and existing aerospace supplier relationships. Deviation in EU AI Act enforcement timelines would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying PLM with manufacturing execution systems compresses deployment timelines for Stuttgart automotive OEMs. |
| Strategic Partnership | Hyperscale cloud alliances enable elastic compute provisioning for distributed engineering teams in supplier networks. |
| Acquisition of Specialist Firm | MBSE simulation capabilities from Toulouse aerospace clusters accelerate systems integration testing cycles. |
| Geographic Expansion | Sovereign cloud infrastructure in France and Germany satisfies GDPR and ANSM algorithmic transparency mandates. |
| Product Launch | Compliance management modules addressing FDA 21 CFR Part 11 capture medical device manufacturer procurement budgets. |
Study Parameters
Multi-period observation of cloud migration timelines and certification adoption rates anchored the trend analysis, supplemented by interviews with PLM vendor product managers, aerospace procurement directors at Airbus and Safran, automotive platform engineers in Munich and Wolfsburg, and IT procurement officers at German industrial machinery producers. Secondary validation drew from SEC filings of listed software vendors, EU AI Act implementation guidance documents, ISO certification registries, and hyperscaler capex disclosures. Bottom-up deployment estimates and top-down market sizing were triangulated for convergence.
Input-output matrices mapped deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster to volume and value outputs across the projection horizon. CAGRs were derived from regression analysis of historical adoption curves and scenario-weighted regulatory compliance deadlines. Forecast inputs included EU AI Act risk classification timelines and CSRD reporting phase-in schedules for lifecycle carbon accounting.
Revisions become necessary when sovereign cloud fragmentation accelerates beyond current Gaia-X implementation timelines or when hyperscale providers alter certification subsidy programs. Deviation in EU AI Act enforcement stringency or FDA 21 CFR Part 11 audit frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Global Apparel Management Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Production Optimization Software Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Consignment Software Market
Software & Services
Financial Corporate Performance Management (FCPM) Software Market
Software & Services
Global Automation Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Webcasting Software Market
Software & Services
Association Management Software Market
Software & Services
Warranty Management Software Market
Software & Services
Meditation Software Market
Software & Services
MEP Software Market
Software & Services
Construction Software Market
Software & Services
Test Automation Market