
 Staffing Software Market | 2026-2036
Staffing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Staffing Software Market Intelligence
Subscription-based SaaS financing is narrowing the competitive field for mid-tier staffing platforms that lack balance-sheet depth for multi-year R&D cycles. Bullhorn, Inc leverages its established API ecosystem to anchor enterprise recruitment workflows across North America. CEIPAL Corp competes aggressively on AI-driven candidate matching, while Zoho Corporation Pvt. Ltd. sustains pricing pressure through its broader business software bundle that cross-subsidizes staffing modules.
Staffing software encompasses cloud-deployed platforms that automate candidate sourcing, credential verification, compliance tracking, and client billing for temporary and permanent placement operations. These systems typically process structured resume data through parsing engines and integrate with background-check providers to maintain regulatory-ready audit trails. Cloud-Based deployment leads the market by accessibility and lower upfront commitment, though Hybrid configurations are gaining traction among agencies managing sensitive healthcare or financial services placements. Applicant Tracking functionality dominates revenue contribution due to its centrality in every hiring workflow, while Payroll Integration represents a fast-growing margin pool as agencies seek to consolidate vendor relationships.
FDA oversight of healthcare staffing credentials, EU GDPR requirements for candidate data processing, and state-level US Department of Labor classification rules collectively shape product roadmaps and geographic feature availability. Vendors must architect modular compliance layers that activate based on client jurisdiction rather than forcing uniform global deployments. Stakeholders should monitor how generative AI in candidate screening triggers new bias-audit mandates from employment regulators.
Market Dynamics
Subscription SaaS financing constraints are compressing R&D timelines for mid-tier staffing platforms, forcing vendors to prioritize modular compliance architectures over monolithic feature expansion.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare staffing agencies across Germany, France, and the Netherlands are procuring platforms with explainable matching algorithms to satisfy algorithmic accountability requirements.
- Credential verification automation:FDA-cleared background-check integrations are digitizing compliance workflows for US clinical staffing firms managing multi-state license portability.
- Contingent workforce classification rules:State-level US Department of Labor variations are driving localized software customization demand in California, Texas, and New York.
Market Restraints
- Multi-year R&D capital intensity:Balance-sheet depth requirements favor established vendors with recurring revenue bases exceeding $50 million annually.
- API ecosystem concentration:North American enterprise recruitment workflow dominance creates switching friction for agencies seeking modular alternatives.
- GDPR data residency controls:EU candidate processing restrictions fragment cloud deployment architectures and inflate infrastructure costs for global platforms.
Strategic Opportunities
- Hybrid deployment models:Healthcare and financial services placements in Switzerland and Singapore are creating demand for on-premise credential vaults with cloud-accessible scheduling interfaces.
- Payroll integration consolidation:Agencies are unifying vendor relationships by embedding real-time tax withholding and benefits administration within staffing platforms.
- Generative AI bias auditing:Emerging employment regulator mandates in Ontario and Victoria are opening compliance-tooling revenue streams for screening algorithm transparency.
Industry Challenges
- Explainable AI engineering scarcity:Candidate-matching systems require specialized talent capable of building interpretable models that satisfy both performance and regulatory audit requirements.
- Legacy HRIS integration complexity:Enterprise clients maintain decades-old payroll and benefits systems that resist modern REST API connectivity without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Staffing Software Market |
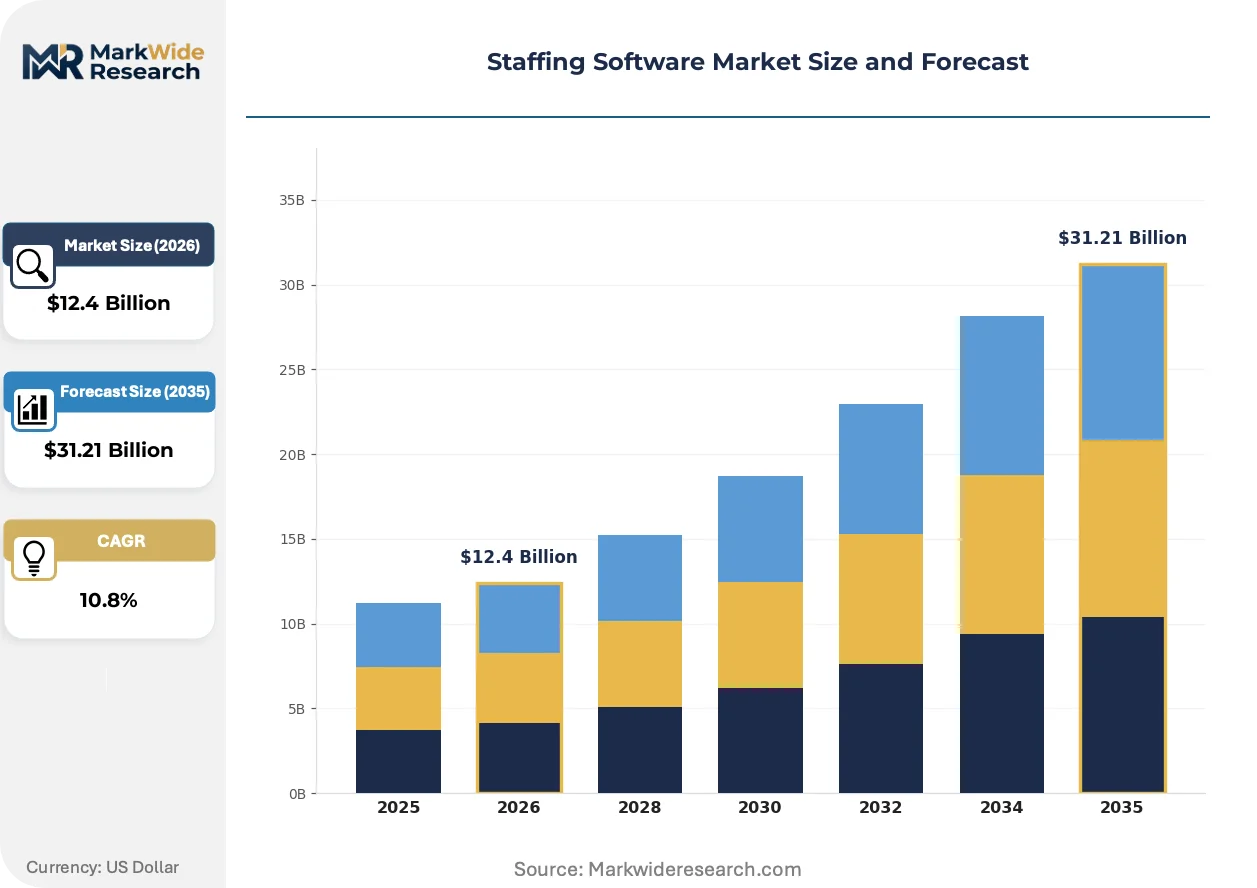
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $31.21 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Recruitment Agencies, Enterprises, Non-Profits, Educational Institutions Functionality: Applicant Tracking, Job Posting, Candidate Management, Reporting Integration Level: API Integrations, HRIS Integration, Payroll Integration, ATS Integration |
| Companies Covered | Bullhorn, Inc, Avionté, CEIPAL Corp, Zoho Corporation Pvt. Ltd., Ramco Systems Ltd, Main Sequence Technology, Inc., Vincere, AkkenCloud, JobDiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Staffing Software Market Strategic Shifts & Innovations
Natural language processing engines are transforming how staffing platforms parse unstructured resume data, compressing candidate-to-placement timelines while raising new regulatory scrutiny over algorithmic decision-making.
Resume parsing automation is digitizing candidate qualification workflows. Large language models extract structured competency data from heterogeneous document formats. Healthcare staffing agencies in Massachusetts and Illinois are deploying these tools at scale, reducing manual screening hours by half while triggering FDA scrutiny over credential verification accuracy.
GDPR Article 22 enforcement is tightening automated decision-making restrictions. EU data protection authorities are issuing fines for opaque candidate-ranking systems. French and German staffing platforms are responding by embedding human-in-the-loop review checkpoints before final placement offers, increasing operational overhead but preserving market access.
Shift-scheduling marketplaces are displacing traditional agency-client relationships. Gig-economy platforms connect credentialed nurses directly with hospital shift vacancies. This pattern is concentrating fastest in Texas and Florida, where right-to-work laws minimize collective bargaining friction and enable real-time wage arbitrage between competing health systems.
Staffing Software Market Segmentation
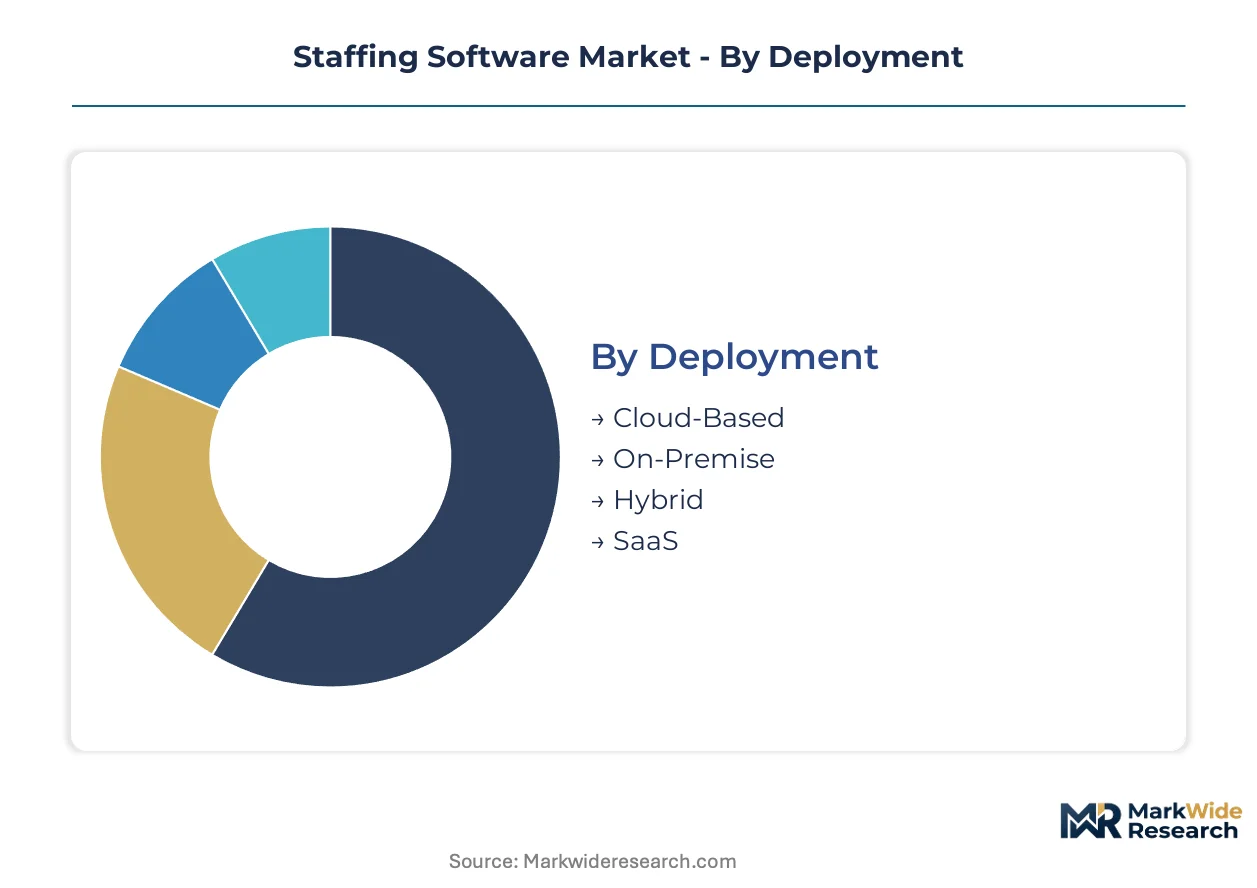
Staffing software architectures fragment across deployment models, user categories, functional modules, and integration depth. Each dimension carries distinct compliance obligations and capital requirements that reshape vendor competitive positioning.
Deployment:
Cost tier determines infrastructure commitment and regulatory exposure for staffing agencies managing sensitive credential data.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server maintenance overhead. Healthcare staffing firms in California and Texas prioritize these configurations for rapid scaling across state lines without hardware procurement cycles.
- Hybrid:On-premise credential vaults synchronize with cloud scheduling interfaces. Swiss and Singaporean financial services placements drive adoption where data residency mandates conflict with workforce mobility requirements.
- On-Premise:Single-tenant installations retain full data sovereignty. German agencies serving federal government contracts favor this model under BSI IT-Grundschutz baseline protection requirements.
- SaaS:Subscription licensing bundles maintenance and updates into predictable operational expenditures. Mid-tier recruitment agencies lacking capital reserves gravitate toward this consumption model.
Cloud-Based deployments anchor the established revenue base. Hybrid configurations are climbing the fastest as cross-border credential portability demands intensify.
End User:
Customer type shapes feature prioritization between high-volume transaction processing and complex compliance documentation.
- Recruitment Agencies:Specialized platforms automate candidate sourcing, client billing, and placement tracking across multiple employer accounts. Massachusetts-based clinical staffing firms leverage these tools to manage FDA-cleared background-check workflows at scale.
- Enterprises:In-house talent acquisition systems integrate with legacy HRIS and payroll infrastructure. Fortune 500 manufacturers in Michigan and Ohio deploy these for contingent workforce classification compliance under varying state Department of Labor interpretations.
- Educational Institutions:Campus recruiting modules handle seasonal hiring surges and work-study program administration. University systems in Florida and Arizona utilize these for adjunct faculty credential verification.
- Non-Profits:Donor-constrained budgets drive demand for stripped-down volunteer coordination and limited-term contract management without enterprise-grade feature overhead.
Recruitment Agencies command the established base. Enterprise adoption is expanding most quickly as insourced talent functions disperse agency dependency.
Functionality:
Application focus determines whether platforms capture value at the sourcing stage or across the full placement lifecycle.
- Applicant Tracking:Centralized candidate pipelines with resume parsing and interview scheduling. Illinois healthcare networks reduced manual screening hours by half after deploying NLP-enabled qualification extraction.
- Candidate Management:Relationship databases maintaining passive talent pools and engagement histories. Texas nursing agencies utilize these for rapid shift-fill against hospital vacancy spikes.
- Job Posting:Multi-channel distribution to job boards and social platforms with performance analytics.
- Reporting:Compliance dashboards and diversity metrics for regulatory filing requirements.
Applicant Tracking dominates current revenue contribution. Payroll Integration—though listed separately under Integration Level—represents the steepest expansion trajectory as agencies consolidate vendor relationships.
Integration Level:
Supply concentration in adjacent HR technology stacks dictates platform connectivity requirements.
- Payroll Integration:Real-time tax withholding and benefits administration embedded within staffing workflows. Agencies in New York and California pursue these capabilities to minimize vendor fragmentation.
- HRIS Integration:Bidirectional data sync with decades-old enterprise payroll systems requiring expensive middleware development. Manufacturing clients in Ohio and Pennsylvania drive demand here.
- API Integrations:Standardized connectivity to background-check providers and credential verification services.
- ATS Integration:Interoperability between agency platforms and client-owned applicant tracking systems for seamless candidate handoff.
API Integrations anchor existing deployments. Payroll Integration is gaining share fastest as agencies seek margin protection through vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act enforcement is redrawing procurement criteria across staffing software markets. Germany, France, the Netherlands, Switzerland, and the United States each present distinct compliance architectures and demand concentrations.
United States
Healthcare staffing agencies in Massachusetts and Texas are expanding platform adoption for FDA-cleared credential verification. State-level Department of Labor classification variations in California and New York force localized software customization. The Greater Boston clinical staffing cluster demands multi-state license portability features.
Germany
Federal contractors in Berlin-Brandenburg require BSI IT-Grundschutz baseline protection for on-premise credential vaults. EU AI Act algorithmic accountability mandates reshape vendor selection in Frankfurt's financial staffing sector. Bavarian industrial recruiters prioritize explainable matching engines for audit readiness.
France
CNIL enforcement of GDPR Article 22 drives human-in-the-loop review checkpoints before placement offers. Paris-based healthcare staffing platforms embed interpretable ranking systems to preserve market access. The Île-de-France region concentrates demand for compliant candidate processing workflows.
Netherlands
Amsterdam's gig-economy nursing marketplaces connect credentialed professionals directly with hospital shifts. Dutch staffing agencies procure platforms with embedded data residency controls for cross-border EU operations. The Randstad urban corridor leads adoption of real-time scheduling interfaces.
Switzerland
Swissmedic oversight of healthcare credentials creates demand for hybrid deployment models with on-premise vaults. Zurich and Geneva financial services placements require cloud-accessible scheduling paired with local data sovereignty. Swiss staffing firms pay premium pricing for modular compliance architectures.
Staffing Software Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered vendor structure. The market consolidates around API ecosystem anchors with recurring revenue bases exceeding $50 million annually. Mid-tier platforms face R&D compression from SaaS financing constraints. Dominant competitive moves include strategic partnerships with background-check providers and modular compliance layer development for jurisdiction-specific activation.
Within the enterprise workflow tier, Bullhorn, Inc and CEIPAL Corp occupy distinct positioning. Bullhorn leverages its established North American API ecosystem to anchor recruitment workflows. CEIPAL represents the AI-driven matching specialist archetype. Zoho Corporation Pvt. Ltd. exemplifies cross-subsidy pricing pressure through bundled business software offerings.
| Leading Market Players |
|---|
| Bullhorn, Inc |
| Avionté |
| CEIPAL Corp |
| Zoho Corporation Pvt. Ltd. |
| Ramco Systems Ltd |
| Main Sequence Technology, Inc. |
| Vincere |
| AkkenCloud |
| JobDiva |
| Others |
Cost & Logistics Intelligence
Transatlantic fiber-optic latency corridors linking Frankfurt and Ashburn shape cloud infrastructure cost dynamics for staffing software vendors, concentrating supply-side power among hyperscalers while forcing tiered pricing differentiation between latency-optimized and standard-deployment tiers.
Pricing Analysis
Certification level creates the primary spread across staffing software tiers, with FDA-cleared credential verification modules commanding premium positioning against standard background-check integrations. Subscription SaaS models dominate, though per-placement transactional pricing persists among gig-economy nursing platforms in Texas and Florida. Price differentiation rests on compliance depth and API ecosystem maturity, with mid-tier vendors facing compression from Zoho's cross-subsidized bundles. Enterprise buyers in Massachusetts and California exhibit lowest price sensitivity due to multi-state regulatory exposure, while non-profit educational institutions in Arizona and Florida prioritize stripped-down configurations.
Supply Chain Analysis
Upstream compute infrastructure feeds from concentrated hyperscaler facilities in Northern Virginia, Frankfurt, and Singapore, with specialized AI inference chips sourced from Taiwan and South Korea. Background-check API providers and credential verification databases constitute critical downstream dependencies. Single-source vulnerability concentrates in NLP parsing engines licensed from a narrow base of large language model providers. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, supplemented by channel partners serving mid-tier recruitment agencies across state-level regulatory variations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among enterprise talent acquisition functions insourcing previously outsourced staffing workflows, fragmenting agency-side purchasing leverage and reshaping vendor negotiation dynamics.
For Market Incumbents: Entrench API ecosystem dominance by deepening background-check provider exclusivity in Massachusetts and Texas clinical staffing corridors. Accelerate modular compliance architecture investment to preempt EU AI Act enforcement in Frankfurt and Paris. Defensive priority centers on explainable matching engine certification before Ontario and Victoria bias-audit mandates activate.
For New Entrants and Emerging Players: Build out hybrid deployment specialization targeting Swissmedic-regulated healthcare placements in Zurich and Geneva, where data residency premiums offset infrastructure complexity. White-space concentration sits in payroll integration consolidation for New York and California agencies seeking vendor relationship unification. Go-to-market leverage rests on real-time tax withholding accuracy against legacy HRIS fragmentation.
For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward explainable AI engineering teams and modular compliance layer intellectual property. Long-term viability favors platforms with recurring revenue bases exceeding threshold scale and jurisdiction-activated feature architectures. Acquisition target archetype: mid-tier vendors with FDA-cleared credential workflows and compressed R&D timelines from SaaS financing constraints. Signal to monitor: Ontario and Victoria employment regulator bias-audit mandate progression.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Compliance Architecture Development | Jurisdiction-activated layers preserve market access under EU AI Act and GDPR Article 22 enforcement. |
| Background-Check API Exclusivity Partnership | FDA-cleared credential verification integration anchors enterprise clinical staffing workflows in Massachusetts. |
| Explainable Matching Engine Certification | Interpretable AI models satisfy algorithmic accountability requirements in Frankfurt and Paris financial staffing. |
| Payroll Integration Consolidation | Embedded tax withholding and benefits administration reduces vendor fragmentation for California agencies. |
| Hybrid Deployment Infrastructure | On-premise credential vaults with cloud scheduling interfaces capture Swiss and Singaporean premium pricing. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with staffing platform CTOs, healthcare agency operations directors, enterprise talent acquisition leads, and background-check API product managers; alongside secondary validation through SEC SaaS vendor filings, EU AI Act implementation guidance, FDA 510(k) clearance databases, and state Department of Labor classification rulings. Bottom-up deployment and functionality segmentation was triangulated against top-down vendor revenue pattern analysis.
Forecast inputs incorporated deployment model migration curves, compliance mandate activation timelines, and integration depth adoption patterns across the projection horizon. Segmentation dimensions modeled included cloud-hybrid-on-premise configurations, recruitment agency versus enterprise end-user categories, applicant tracking versus payroll integration functionality tiers, and regional regulatory cluster variations. CAGRs were derived from fitted growth curves against observed SaaS subscription expansion and transactional placement volume trajectories, with specific weighting for EU AI Act compliance procurement acceleration and US state-level classification rule fragmentation.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hyperscalers into staffing-specific compliance tooling would shift outcomes substantially. Cross-checking against hospital procurement database credential verification spend patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Lifecycle Management Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Global User Interface Service Market
Software & Services
Federal Government Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Global Club Management Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Embedded Software and Tools Market
Software & Services
Expense Management Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Data Extraction Software Market
Software & Services
Global Application Development Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
North America Digital Marketing Software Market